
 File Sharing Market | 2026-2036
File Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
File Sharing Market Analysis
GDPR is hardening the cost-of-entry calculus for file sharing vendors serving European enterprises. Microsoft leverages its Azure regional datacenter footprint to sustain compliance leadership across regulated industries. Dropbox anchors its position through consumer-to-enterprise conversion, while Box specializes in workflow automation for financial services verticals.
File sharing denotes the electronic distribution and synchronized access of digital content across networked endpoints, typically operating through client-server architectures with AES-256 encryption, chunked file transfer protocols, and RESTful API integrations for third-party application connectivity. Cloud storage solutions within the solution segment dominate transaction volumes, though peer-to-peer architectures are gaining traction for latency-sensitive media workflows. Enterprise end users generate the majority of recurring revenue, while hybrid deployment models capture expanding margin pools as organizations navigate data residency requirements.
FCC guidelines on broadband infrastructure and the EU AI Act's data governance provisions shape vendor certification requirements and cross-border transfer protocols. HIPAA in the United States imposes encryption and audit-trail mandates on healthcare file sharing implementations. Stakeholders must monitor evolving fragmentation between regional sovereignty frameworks and unified cloud architectures when allocating platform development resources.
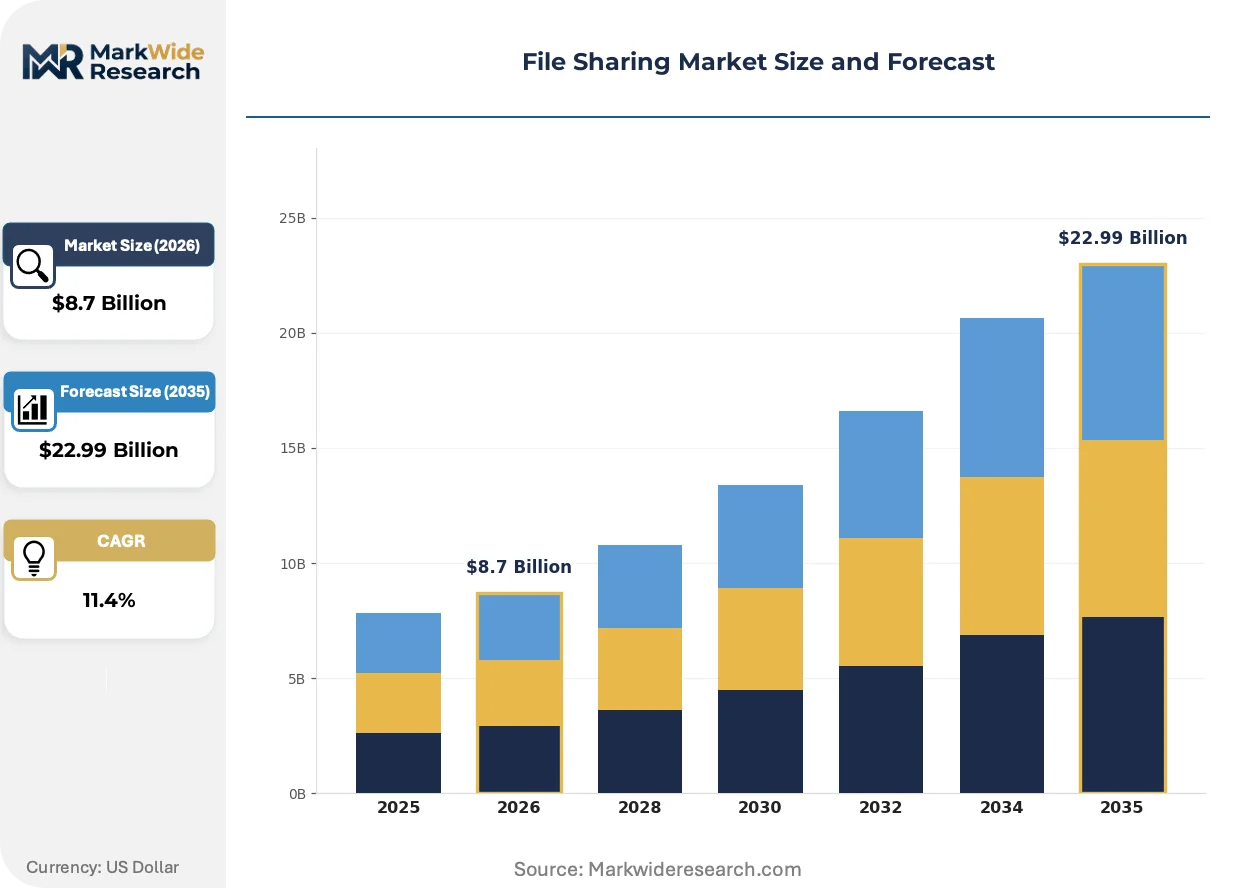
Market Dynamics
Enterprise migration from on-premises storage to cloud-native collaboration platforms is compressing legacy vendor margins while redistributing competitive advantage toward providers with sovereign data architectures. GDPR and the EU AI Act are forcing infrastructure redesigns that favor regional datacenter operators over centralized hyperscale deployments.
Growth Catalysts
- Hybrid deployment mandates:German Mittelstand manufacturers now require local residency guarantees for sensitive design files, creating demand for edge-connected file sharing nodes with sovereign data controls.
- Healthcare digitization:HIPAA encryption and audit-trail requirements in the United States are accelerating compliant cloud adoption among hospital systems and clinical research networks.
- AI-driven content workflows:Media production studios are integrating machine learning-based asset tagging into peer-to-peer file transfer protocols to reduce latency in 4K/8K collaborative editing pipelines.
Market Restraints
- Datacenter energy costs:Electricity price volatility in European markets is squeezing margins for vendors operating Tier III+ facilities required for financial services compliance.
- Encryption export controls:Cross-border transfer restrictions on AES-256 implementations create deployment friction for multinational enterprises with unified security policies.
- Substitution by native collaboration suites:Bundled document management within Microsoft 365 and Google Workspace displaces standalone file sharing subscriptions in mid-market accounts.
Strategic Opportunities
- India's PLI scheme for data centers:Production-linked incentives for domestic cloud infrastructure create entry pathways for vendors establishing Mumbai and Hyderabad edge nodes.
- Convergence of blockchain and file provenance:Immutable audit trails for intellectual property documentation are opening premium pricing tiers in legal and pharmaceutical verticals.
- Direct-to-developer API distribution:Bypassing traditional enterprise sales cycles through marketplace integrations with low-code platforms accelerates land-and-expand revenue models.
Industry Challenges
- Zero-trust architecture skills gap:Implementation of continuous verification protocols for file access requires security engineers with scarce SASE and SSE certifications.
- Legacy ECM integration complexity:Migration from Documentum, SharePoint on-premises, and OpenText systems involves custom middleware development that extends sales cycles by 9-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | File Sharing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Cloud Storage, Peer-to-Peer, File Transfer Protocol, Collaboration Tools End User: SMEs, Enterprises, Individual Users, Educational Institutions Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services File Type: Documents, Multimedia, Images, Software |
| Companies Covered | Dropbox, Microsoft, Box, Google, IBM, Citrix Systems, Egnyte, ownCloud GmbH, Tresorit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
File Sharing Market Emerging Trajectories
Peer-to-peer architectures are displacing client-server models in latency-sensitive workflows, while regulatory fragmentation between GDPR, HIPAA, and emerging AI governance frameworks is fragmenting vendor certification requirements across jurisdictions.
Chunked file transfer protocols with differential synchronization are expanding into broadcast media and visual effects production, where Adobe and Autodesk pipeline integrations demand sub-100ms latency for 8K frame sequences. Major studios in Los Angeles and London now mandate these protocols for distributed editorial teams, compressing the addressable market for traditional FTP-based solutions.
The EU AI Act's data governance provisions are mandating algorithmic transparency logs for any AI-assisted content classification within file sharing platforms. German automotive suppliers and French pharmaceutical firms must now maintain immutable records of automated metadata tagging, forcing vendors to re-engineer backend architectures for forensic auditability. This requirement is accelerating compliance spending among mid-tier European providers.
Consumption-based licensing is displacing per-seat subscriptions in enterprise procurement, particularly among project-based professional services firms with highly variable collaboration intensity. Big Four consultancies and London-based law firms now negotiate tiered usage pools rather than fixed headcount agreements, compressing predictable recurring revenue streams while expanding total addressable spend for vendors with granular metering capabilities.
File Sharing Market Segmentation
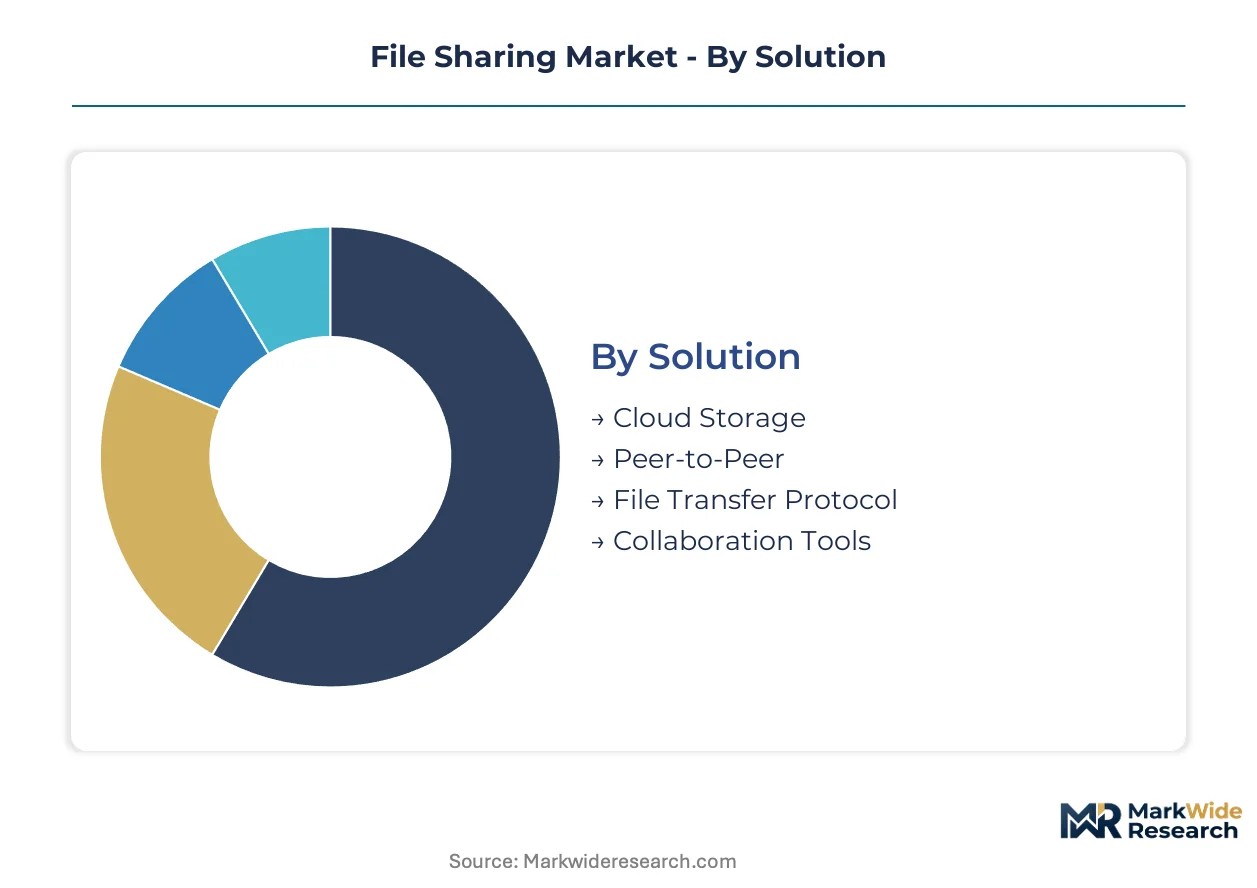
File sharing vendors face divergent margin structures across deployment models and end-user scales. Solution architecture choices determine compliance burden, while deployment mode dictates datacenter capital intensity and sovereign data capabilities.
Solution:
Cloud storage commands transaction volume leadership, yet peer-to-peer architectures capture premium pricing in latency-sensitive verticals.
- Cloud Storage:Centralized architectures with AES-256 encryption and chunked transfer protocols dominate enterprise recurring revenue. German automotive suppliers and French pharmaceutical firms drive demand for regional datacenter nodes with GDPR-compliant residency guarantees.
- Peer-to-Peer:Distributed architectures eliminate single points of failure for 4K/8K media workflows. Los Angeles and London production studios mandate sub-100ms latency for distributed editorial teams, compressing addressable space for legacy FTP solutions.
- File Transfer Protocol:Legacy client-server implementations persist in industrial IoT environments with intermittent connectivity.
- Collaboration Tools:Integrated document editing and synchronous commenting layers command per-seat premiums in professional services.
Today's leader: Cloud Storage. Tomorrow's challenger: Peer-to-Peer.
End User:
Enterprise accounts generate predictable recurring revenue, though SME procurement patterns are shifting toward consumption-based metering.
- Enterprises:Regulated industries with HIPAA, GDPR, and EU AI Act mandates require audit-trail immutability and algorithmic transparency logs. Migration from Documentum and SharePoint on-premises extends sales cycles 9-18 months due to custom middleware complexity.
- SMEs:Project-based professional services firms negotiate tiered usage pools rather than fixed headcount agreements. Big Four consultancies and London law firms compress predictable revenue streams while expanding total addressable spend.
- Individual Users:Consumer-to-enterprise conversion pathways anchor freemium acquisition models.
- Educational Institutions:Federated identity requirements and FERPA compliance shape procurement specifications in US research universities.
Enterprise contracts anchor current profitability; SME metering models are climbing the fastest.
Deployment:
Hybrid configurations capture expanding margin pools as organizations navigate data residency requirements.
- Hybrid:Edge-connected nodes with sovereign controls satisfy German Mittelstand manufacturers requiring local residency for sensitive design files. Electricity price volatility in European Tier III+ facilities squeezes margins for financial services compliance.
- Cloud-Based:Hyperscale deployments face infrastructure redesign pressure from GDPR and EU AI Act fragmentation favoring regional operators.
- On-Premises:Legacy installations persist in classified government networks with air-gapped security requirements.
- Managed Services:Outsourced operations appeal to mid-market accounts lacking zero-trust architecture skills and SASE certification expertise.
Hybrid deployments now dominate new contract value; cloud-native architectures face steepest expansion trajectory.
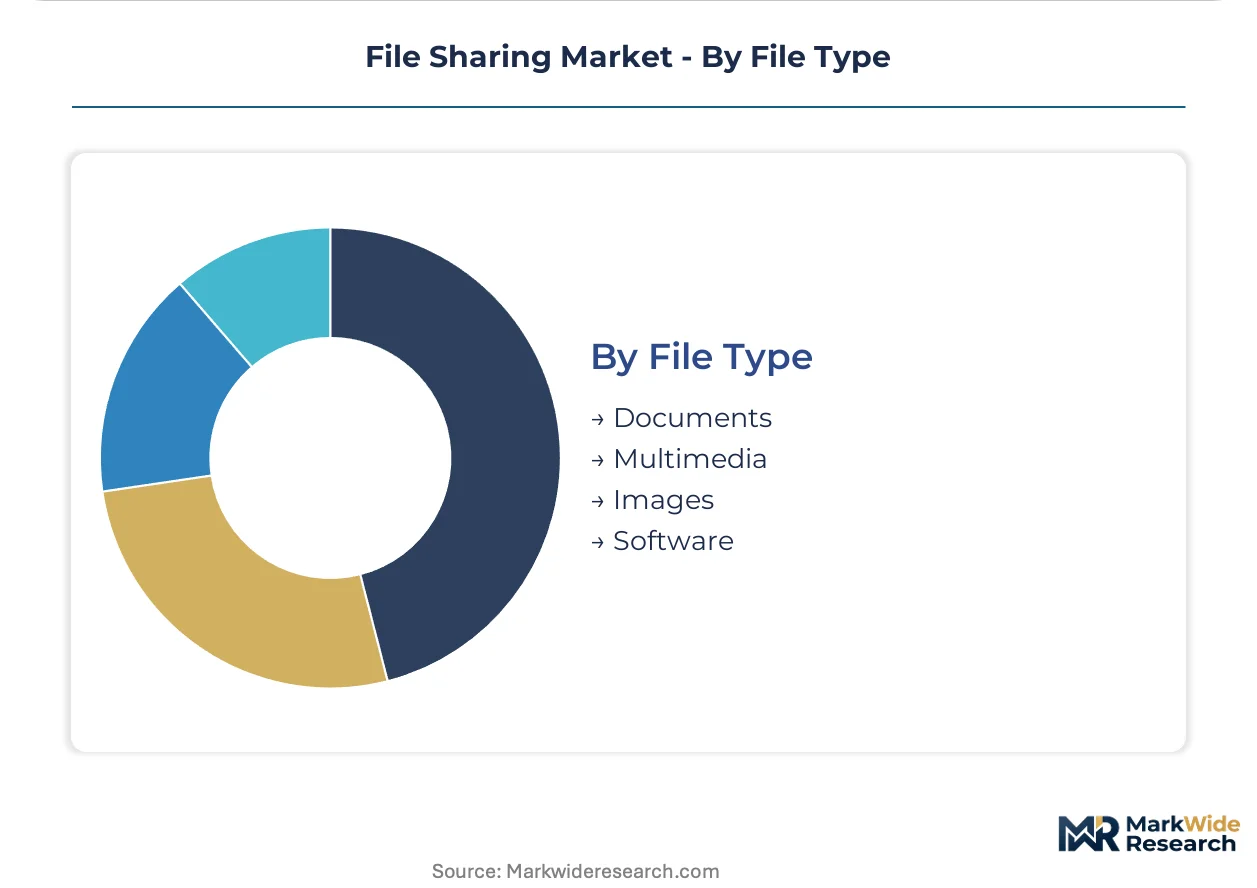
File Type:
Multimedia assets drive infrastructure investment, while document workflows determine platform stickiness.
- Multimedia:8K frame sequences and broadcast media pipelines require differential synchronization and Adobe-Autodesk integrations. Chunked protocols with sub-100ms latency mandates reshape vendor certification requirements.
- Documents:Contract lifecycle management and e-signature integration create workflow automation premiums in legal and financial services verticals.
- Images:AI-assisted metadata tagging triggers EU AI Act algorithmic transparency log requirements for automated classification systems.
- Software:Binary artifact distribution with cryptographic provenance verification opens blockchain-audit premium tiers.
Multimedia infrastructure commands current capital allocation; document workflow integration is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
File sharing infrastructure originated in United States research networks during the 1990s, with commercial cloud platforms scaling from Silicon Valley datacenter clusters before diffusing to regional sovereignty architectures worldwide.
United States
Healthcare systems and financial services drive enterprise cloud adoption under HIPAA encryption mandates and SEC audit-trail requirements. FCC broadband infrastructure guidelines shape vendor certification protocols for cross-state data transfers. Los Angeles production studios mandate sub-100ms latency for 8K media workflows, compressing legacy FTP market share.
Germany
Mittelstand manufacturers require local residency guarantees for sensitive design files, accelerating hybrid deployment contracts. GDPR and EU AI Act provisions force algorithmic transparency logs for AI-assisted content classification. Stuttgart and Munich automotive clusters anchor demand for sovereign data nodes with edge-connected architectures.
United Kingdom
Big Four consultancies and London law firms negotiate consumption-based licensing pools rather than fixed headcount agreements. FCA financial regulations impose immutable audit trails on document workflows. The M4 corridor technology cluster concentrates fintech file sharing procurement with workflow automation requirements.
India
Domestic cloud infrastructure expansion under the PLI scheme creates entry pathways for vendors establishing Mumbai and Hyderabad edge nodes. RBI data localization guidelines restrict cross-border financial document transfers. Bengaluru software development clusters drive API-first distribution models through low-code platform integrations.
France
Pharmaceutical firms must maintain immutable records of automated metadata tagging under EU AI Act governance provisions. CNIL enforcement actions harden consent requirements for consumer file sharing platforms. Paris and Lyon life sciences clusters anchor demand for forensic auditability in clinical research networks.
File Sharing Market Vendor Landscape
The competitive structure tilts toward hyperscale cloud providers with regional datacenter footprints. Consolidation pressures squeeze mid-tier vendors as bundled collaboration suites displace standalone subscriptions. Three archetypes dominate: infrastructure-anchored platforms, consumer-conversion specialists, and vertical workflow automators. Geographic expansion through sovereign data nodes and strategic API distribution partnerships constitute the primary competitive vectors.
Among infrastructure-anchored providers, Microsoft and Google exemplify scale-driven positioning through hyperscale cloud ecosystems. Dropbox occupies a consumer-to-enterprise conversion archetype, while Box represents vertical specialization in regulated workflow automation. These three companies anchor distinct strategic positions without overlapping core value propositions.
| Leading Market Players |
|---|
| Dropbox |
| Microsoft |
| Box |
| IBM |
| Citrix Systems |
| Egnyte |
| ownCloud GmbH |
| Tresorit |
| Others |
Supply Flow & Price Mechanics
Zero-trust architecture engineers concentrated in California and Massachusetts command 40-60% wage premiums over general cloud infrastructure roles, widening spreads between premium sovereign-hybrid tiers and commodity cloud storage pricing. German and Indian datacenter labor arbitrage compresses mid-market SaaS margins while GDPR compliance certification costs anchor premium tier floors.
Pricing Analysis
Consumption-based metering with tiered usage pools now dominates enterprise procurement, replacing per-seat subscriptions across professional services and project-based workflows. Price differentiation hinges on data residency certification grade and edge node proximity guarantees, with HIPAA and EU AI Act compliance tiers commanding substantial premiums. Pricing pressure stems from bundled Microsoft 365 and Google Workspace collaboration suites displacing standalone subscriptions in mid-market accounts. SMEs exhibit highest price sensitivity, while regulated financial services and healthcare verticals demonstrate inelastic demand for sovereign-hybrid configurations.
Supply Chain Analysis
Direct-to-enterprise sales channels handle hyperscale buyer demand, while API marketplace distribution accelerates land-and-expand models among developer-centric segments. Datacenter infrastructure concentrates in the United States, Germany, and India, with Mumbai and Hyderabad edge nodes expanding under India's PLI scheme. Hardware dependencies span AES-256 encryption chipsets, Tier III+ facility power systems, and optical fiber interconnects for sub-100ms latency mandates. Single-source vulnerability in European electricity markets threatens Tier III+ facility margins. Distribution runs through hyperscale cloud marketplaces, systems integrator partnerships, and direct field sales organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
File sharing infrastructure has matured into a late-cycle quality story where sovereign data capabilities and workflow automation depth separate viable platforms from commodity alternatives. Enterprise procurement is shifting toward premium hybrid deployments with algorithmic transparency logs and immutable audit trails.
For Market Incumbents: Deploy sovereign data node expansion as the primary defensive lever. Establish edge-connected facilities in Stuttgart, Munich, and Hyderabad to satisfy Mittelstand manufacturers and PLI-scheme incentives before regional operators capture local residency contracts. Deepen Adobe and Autodesk pipeline integrations to defend against peer-to-peer challengers in media workflows. Certification investment in EU AI Act algorithmic transparency logging creates switching costs against bundled suite substitution.
For New Entrants and Emerging Players: Enter via API-first distribution through low-code platform marketplaces to bypass 9-18 month legacy ECM migration sales cycles. Target India's domestic cloud infrastructure expansion as the most penetrable geography, where RBI data localization guidelines and Bengaluru software clusters create demand for compliant edge nodes. White-space exists in blockchain-provenance premium tiers for legal and pharmaceutical intellectual property documentation.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier European providers facing compliance-driven re-engineering costs without hyperscale balance sheets to absorb capital intensity. Long-term viability favors vendors with hybrid deployment revenue mixes above 60% and vertical workflow automation depth in financial services or healthcare. Monitor electricity price stabilization in European Tier III+ markets as the key inflection signal for margin recovery among regional datacenter operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Node Expansion | Stuttgart and Munich facilities satisfy German Mittelstand local residency mandates under GDPR. |
| EU AI Act Compliance Certification | Algorithmic transparency logging creates mandatory spend for French pharmaceutical and automotive suppliers. |
| API Marketplace Distribution | Bypasses legacy ECM migration friction through low-code platform integrations in Bengaluru clusters. |
| Adobe-Autodesk Pipeline Integration | Sub-100ms latency mandates from Los Angeles and London studios compress FTP market share. |
| Blockchain Provenance Layer | Immutable audit trails open premium pricing in legal and pharmaceutical intellectual property verticals. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with chief information security officers, enterprise IT procurement directors, cloud infrastructure architects, and datacenter operations managers with secondary validation against hyperscaler capex disclosures, SEC filings, EU regulatory filings, and industry trade data. Bottom-up segment sizing across deployment models, end-user scales, and solution architectures was triangulated against top-down market boundary estimates.
Historical reference periods anchored the projection horizon to observed migration patterns from on-premises Documentum and SharePoint systems, with modeled dimensions spanning deployment mode, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted adoption curves incorporating GDPR enforcement trajectory, EU AI Act implementation phases, and healthcare digitization spend patterns. Forecast inputs included datacenter capacity expansion announcements, PLI scheme incentive allocations, and electricity price volatility indices.
The model holds under stable regulatory enforcement intensity and continued enterprise cloud migration; deviation in sovereign data localization mandates or hyperscaler bundling aggression would shift segment growth rates substantially. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Content Recommendation Engine Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Global Unified Endpoint Management Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
Data Monetization Solutions for Life Science Companies Market
Digital Solutions
Australia ICT Market
Digital Solutions
Data Classification Tool Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Global Application Container Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Cloud Logistics Software Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
South Africa Digital Twin Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Revenue Management Software Market