
 Epedigree Software Market | 2026-2036
Epedigree Software Market Size, Share, and Industry Trends Forecast 2026-2036
Epedigree Software Market Intelligence
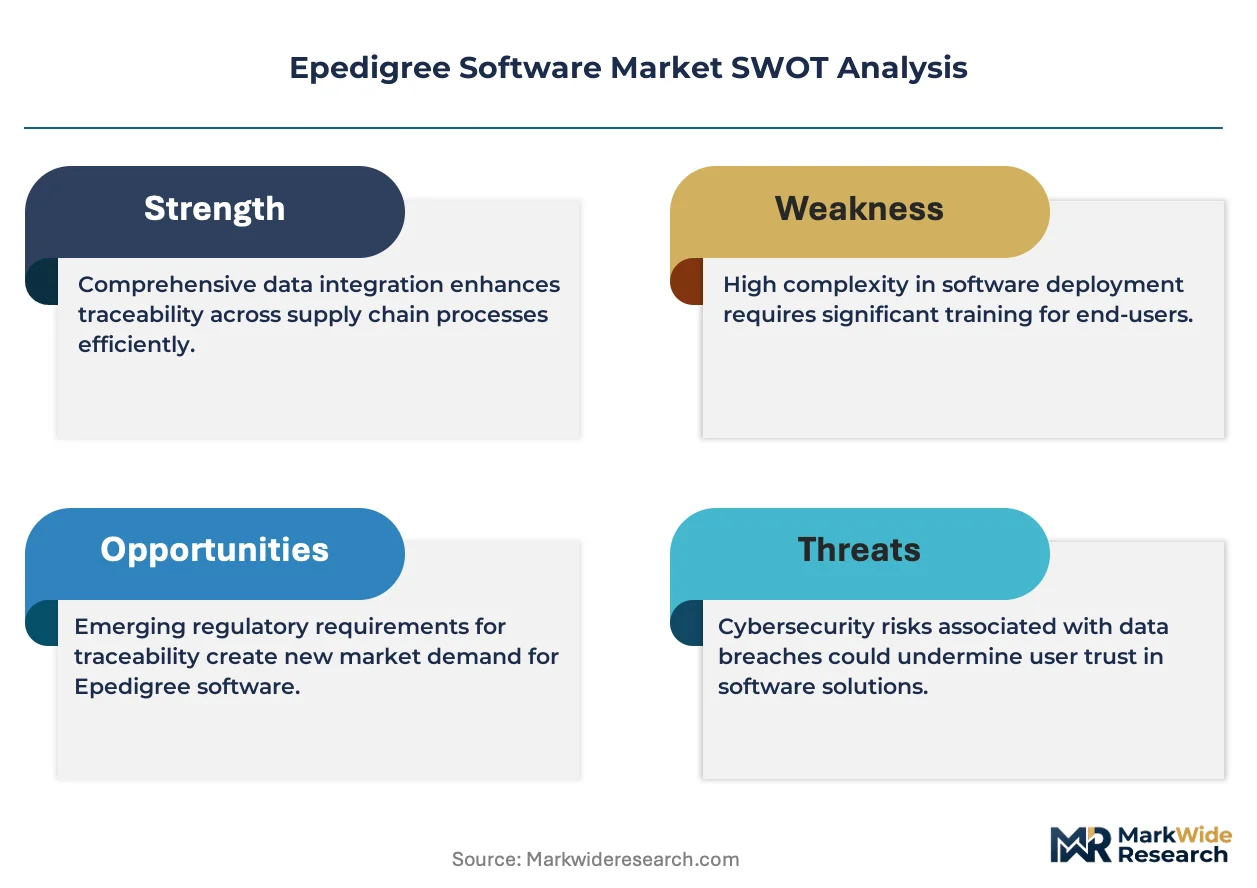
North America is reshaping competitive dynamics in epedigree software through sustained enterprise investment in pharmaceutical traceability infrastructure. Oracle leverages its cloud-native architecture to anchor multi-tenant serialization platforms across major drug manufacturers. SAP competes through deep ERP integration that sustains end-to-end supply chain visibility for compliance-heavy clients.
Epedigree software constitutes a specialized traceability platform that assigns unique serialized identifiers to pharmaceutical products, enabling authentication and lineage verification across distribution networks through GS1 standards and EPCIS event repositories. Its primary commercial purpose centers on eliminating counterfeit medicines from legitimate supply chains while satisfying jurisdictional reporting mandates. Cloud-based deployments now lead product type adoption as pharmaceutical companies prioritize elastic scalability over capital-intensive on-premise installations, whereas API-level integration captures expanding margin pools by reducing bespoke implementation cycles. End-user concentration tilts toward pharmaceutical companies, though biotech firms represent the fastest-growing segment as emerging therapeutics pipelines require rapid compliance scaffolding.
The US FDA enforces DSCSA serialization deadlines that shape demand timelines and technical specifications for domestic distributors. EMA's Falsified Medicines Directive and corresponding national medicines verification systems across EU member states create parallel compliance architectures that vendors must simultaneously address. Stakeholders should monitor evolving interoperability standards between regional track-and-trace databases, as fragmented regulatory synchronization poses the most consequential strategic uncertainty for platform providers and pharmaceutical supply chain architects.
Market Dynamics
Serialized pharmaceutical tracking mandates are compressing implementation timelines and forcing wholesale infrastructure replacement across drug distribution networks. Cloud-native verification platforms are displacing legacy paper-based pedigree systems as the FDA's DSCSA enforcement tightens.
Growth Catalysts
- DSCSA Serialization Mandates:The US FDA's Drug Supply Chain Security Act requires unit-level traceability for all prescription drugs, compelling distributors to deploy interoperable verification systems before statutory deadlines.
- Counterfeit Penetration:Illicit medicines now infiltrate legitimate supply chains through online pharmacies and gray-market diversion, creating existential liability exposure that serialization platforms mitigate.
- Blockchain Verification Protocols:Distributed ledger architectures are anchoring immutable transaction records across multi-party supply chains, reducing dispute resolution cycles between manufacturers and logistics providers.
Market Restraints
- Implementation Cost Burden:Mid-size generic manufacturers face capital intensity exceeding operational budgets for full-stack serialization infrastructure, including hardware, software, and validation protocols.
- Supplier Concentration Risk:Cloud infrastructure dependencies concentrate on three dominant hyperscale providers, creating single-point-of-failure exposure for mission-critical verification uptime.
- Interoperability Friction:Divergent national medicines verification system architectures between the US FDA's DSCSA and EU member state repositories force vendors to maintain parallel compliance stacks.
Strategic Opportunities
- Biotech Pipeline Expansion:Cell and gene therapy manufacturers require rapid compliance scaffolding for personalized medicine batch sizes, creating demand for modular serialization platforms.
- API-First Integration:RESTful interface architectures are reducing bespoke implementation cycles, enabling systems integrators to capture margin pools previously absorbed by custom development.
- India Pharmaceutical Export Growth:The country's central pharmaceutical regulator is aligning with international traceability standards, opening deployment opportunities for verification software vendors serving contract manufacturing organizations.
Industry Challenges
- GS1 Standard Implementation:Master data synchronization across trading partners requires specialized expertise in EPCIS event repositories and SGTIN encoding schemes that remain scarce in labor markets.
- Legacy System Integration:ERP consolidation projects stall when serialization modules conflict with existing warehouse management architectures, extending deployment timelines and inflating professional services costs.
- Validation Documentation Burden:FDA 21 CFR Part 11 compliance for electronic records demands exhaustive audit trails that consume quality assurance resources and compress software release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epedigree Software Market |
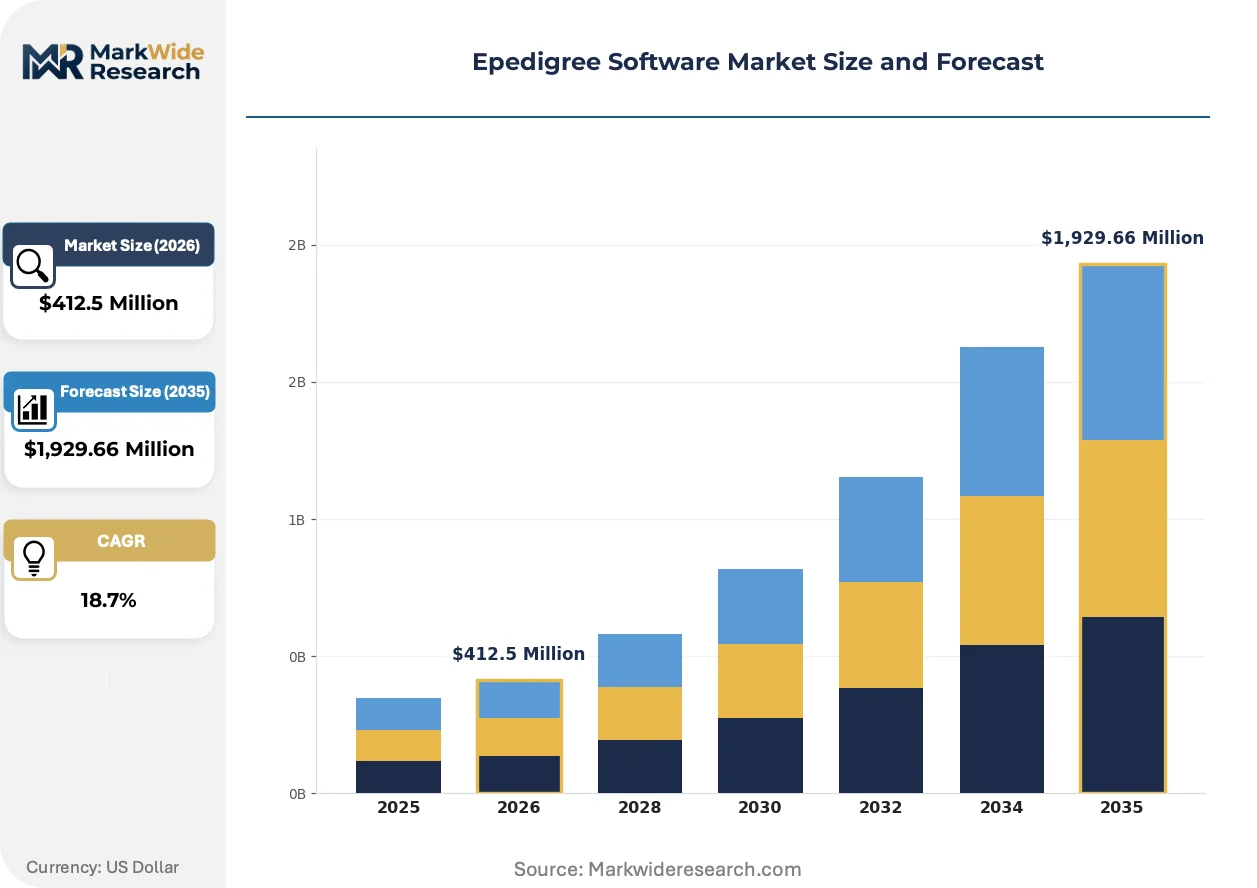
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, SaaS End User: Pharmaceutical Companies, Biotech Firms, Distributors, Hospitals Deployment Model: Private Cloud, Public Cloud, Community Cloud, Local Server Integration Level: API, Full Integration, Semi-Integration, Standalone Solutions |
| Companies Covered | Oracle, SAP, IBM Corporation, Altair Engineering Inc., Antares Vision SpA, Axway Software SA, Aptean, TraceLink Inc., Merit Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epedigree Software Market Strategic Shifts & Innovations
Pharmaceutical traceability is converging with edge computing architectures and artificial intelligence inference engines that compress verification latency at distribution nodes. These technical shifts are reconfiguring vendor competitive positioning away from compliance checklists toward predictive supply chain intelligence.
Machine learning inference engines deployed at warehouse edge nodes are digitizing anomaly detection in serialization data streams. Third-party logistics providers are adopting these architectures fastest to reduce manual intervention in high-volume distribution centers. Real-time pattern recognition is digitizing counterfeit identification from hours to milliseconds, compressing response windows before suspect products reach dispensers.
The EU's Falsified Medicines Directive and corresponding delegated acts are mandating repository system interoperability across member states. This regulatory architecture is forcing software vendors to maintain multi-tenant platforms capable of routing verification queries to national medicines verification systems. Small-market manufacturers in Portugal, Greece, and Ireland face disproportionate compliance complexity relative to operational scale.
Buyer procurement committees are consolidating vendor selection authority under chief supply chain officers rather than IT departments. This organizational shift elevates total cost of ownership and operational resilience above feature checklists in evaluation criteria. Large pharmaceutical distributors in Germany and the United States are piloting outcome-based contracts that tie software fees to verified transaction throughput rather than seat licenses.
Epedigree Software Market Segmentation
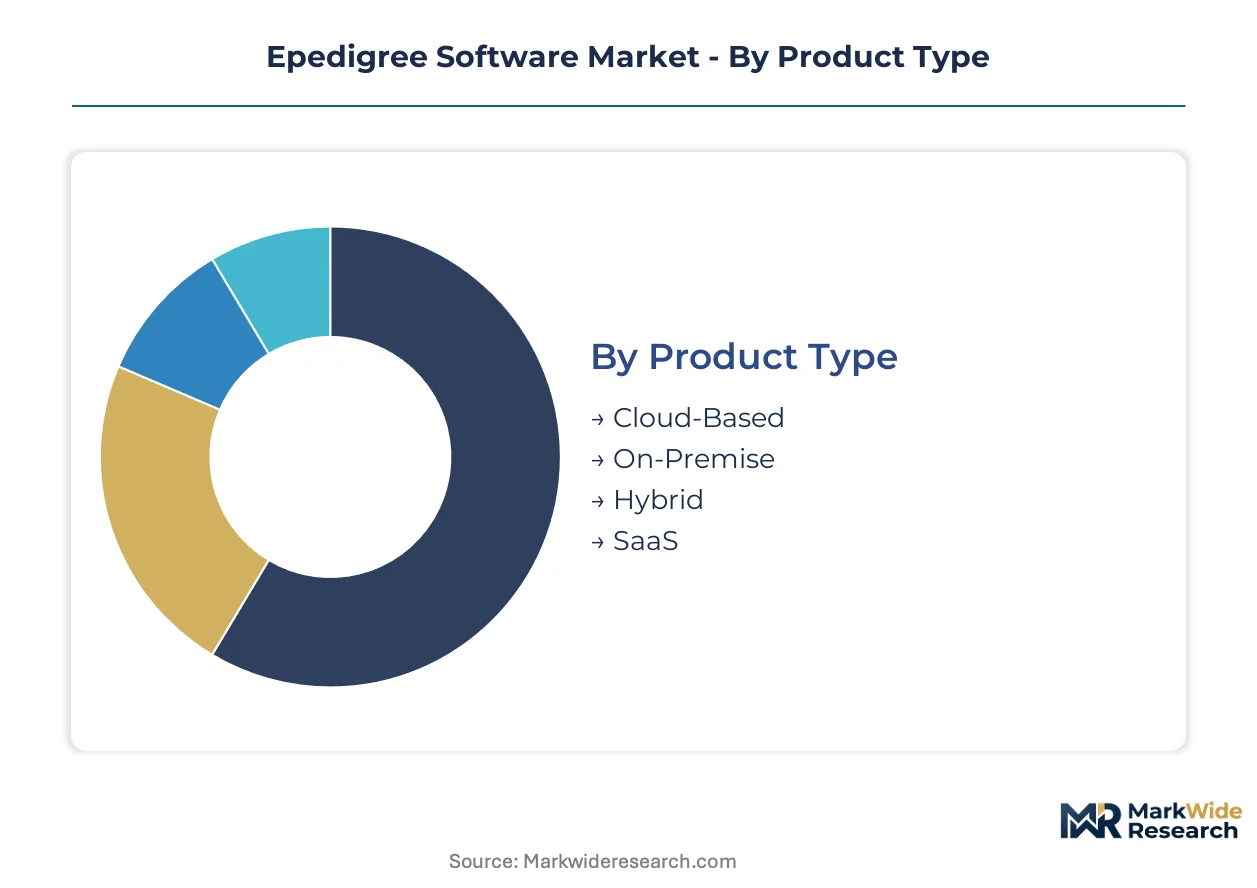
Epedigree software segmentation reveals how pharmaceutical traceability demands fragment across technical architectures, organizational users, and integration complexity. Each dimension carries distinct procurement criteria, compliance burdens, and margin structures that reshape vendor competitive positioning.
Product Type:
Deployment topology determines capital intensity, validation cycles, and scalability ceilings across pharmaceutical supply chains.
- Cloud-Based:Multi-tenant architectures deliver elastic compute for serialization event processing without on-premise hardware procurement. Demand concentrates among mid-size generic manufacturers in the United States seeking to defer FDA DSCSA compliance capital expenditure.
- On-Premise:Dedicated infrastructure installations satisfy data sovereignty requirements and air-gapped security protocols for controlled substance manufacturers. German pharmaceutical clusters favor these deployments to satisfy Bundesamt für Sicherheit in der Informationstechnik audit standards.
- Hybrid:Mixed architectures partition sensitive master data locally while pushing transaction verification to cloud nodes.
- SaaS:Subscription licensing models compress implementation timelines for emerging biotech firms with limited IT infrastructure.
The dominant share belongs to Cloud-Based, while SaaS is closing the gap fastest.
End User:
Organizational scale and regulatory exposure create divergent functional requirements across the pharmaceutical value chain.
- Pharmaceutical Companies:Large-scale manufacturers require end-to-end lineage tracking from active pharmaceutical ingredient sourcing through dispenser delivery. Pfizer and Johnson & Johnson anchor procurement volume in the United States, driven by FDA enforcement timelines and product liability exposure.
- Biotech Firms:Cell and gene therapy developers need modular serialization for personalized medicine batch sizes. Massachusetts and California clusters are expanding most quickly as CAR-T and CRISPR pipelines mature.
- Distributors:Wholesale operators prioritize high-throughput verification systems capable of processing millions of serialized units daily.
- Hospitals:Health systems are adopting point-of-dispense authentication to intercept counterfeit infiltration at the final patient interface.
Pharmaceutical Companies command the installed base, though Biotech Firms are gaining share fastest.
Deployment Model:
Infrastructure tenancy arrangements balance control, compliance, and operational resilience for mission-critical verification workloads.
- Private Cloud:Single-tenant virtualized environments satisfy 21 CFR Part 11 validation requirements while retaining cloud scalability benefits. European pharmaceutical manufacturers in Switzerland and Germany favor these deployments under EMA data integrity guidelines.
- Public Cloud:Shared hyperscale infrastructure delivers lowest unit economics for high-volume transaction processing. Indian contract manufacturing organizations are climbing the fastest as CDSCO aligns with international traceability standards.
- Community Cloud:Industry-specific platforms serve consortium requirements for regional pharmaceutical associations.
- Local Server:Physical hardware installations persist in markets with unreliable connectivity or strict data localization mandates.
Private Cloud holds the leading position, while Public Cloud is expanding most quickly.
Integration Level:
Systems connectivity depth determines implementation friction, ongoing maintenance burden, and total cost of ownership across enterprise technology stacks.
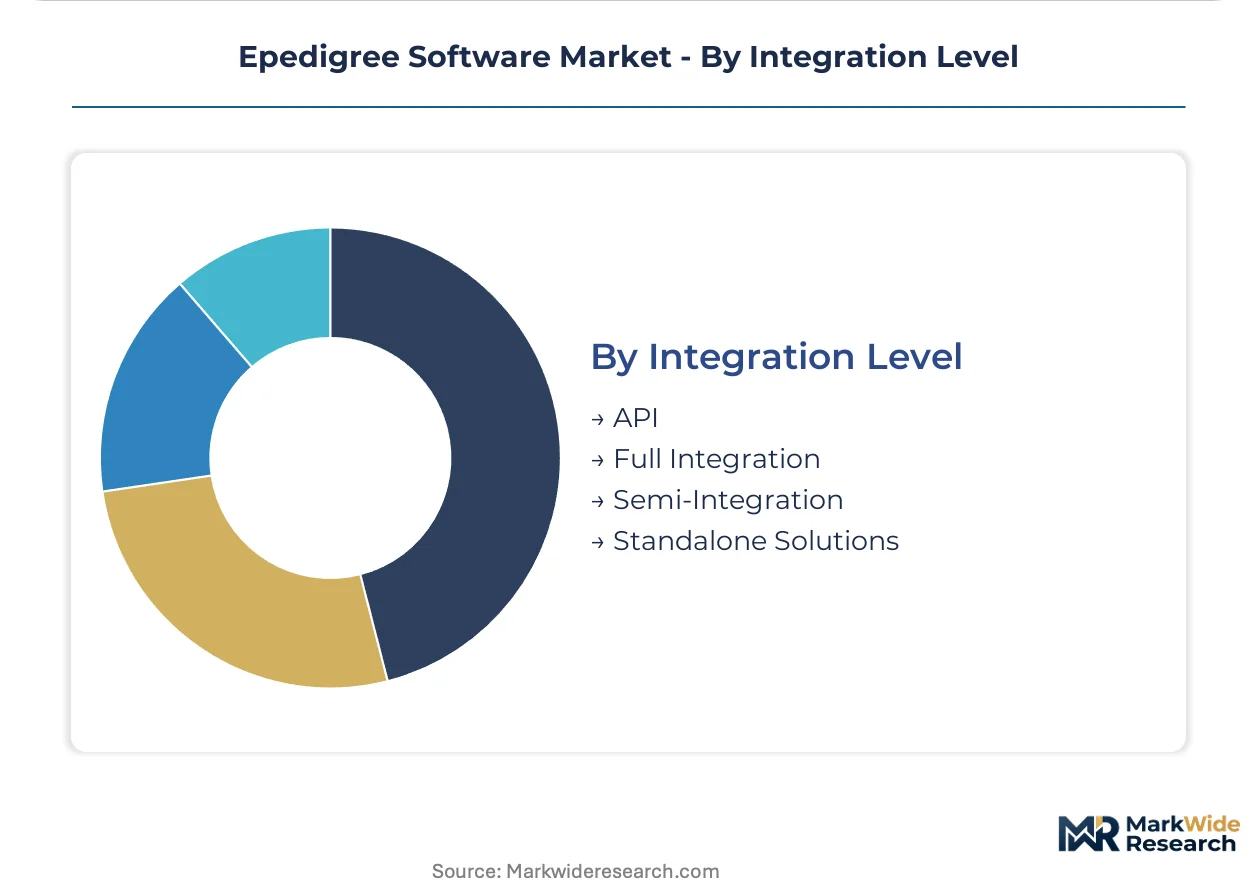
- API:RESTful interface architectures enable rapid connection to existing ERP and warehouse management systems without custom code development. Third-party logistics providers in the Netherlands and Belgium are adopting these most aggressively to compress deployment timelines.
- Full Integration:Native module embedding within SAP or Oracle environments delivers seamless data flow but extends validation cycles. Large pharmaceutical manufacturers with complex supply chains favor this depth despite higher upfront professional services costs.
- Semi-Integration:Partial connectivity through middleware layers balances implementation speed with functional coverage.
- Standalone Solutions:Self-contained verification platforms serve smaller manufacturers with limited legacy system complexity.
Full Integration retains the largest footprint, though API is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates anchor demand concentration in the United States, while EMA's Falsified Medicines Directive and India's CDSCO traceability alignment create parallel enforcement architectures across three continents.
United States
Pharmaceutical distributors in New Jersey and Illinois are deploying cloud-native verification platforms ahead of DSCSA enforcement deadlines. The FDA's unit-level traceability requirements compress implementation timelines for wholesale operators. Massachusetts biotech clusters around Cambridge require modular serialization for cell therapy batch sizes.
Germany
Bundesamt für Sicherheit in der Informationstechnik audit standards drive private cloud preferences among Baden-Württemberg pharmaceutical manufacturers. EMA data integrity guidelines shape validation protocols for serialization event repositories. The Rhine-Main logistics corridor anchors high-throughput verification system deployments for European distribution.
India
Contract manufacturing organizations in Gujarat and Maharashtra are climbing fastest as CDSCO aligns with international traceability standards. The central pharmaceutical regulator's serialization mandates open deployment opportunities for verification software vendors. Hyderabad and Bangalore pharmaceutical clusters require rapid compliance scaffolding for export-oriented production.
Switzerland
Swissmedic enforcement of data integrity guidelines sustains demand for air-gapped security protocols among controlled substance manufacturers. Basel's pharmaceutical headquarters concentration drives ERP-integrated serialization module procurement. Geneva-based logistics providers prioritize high-availability verification architectures for cross-border distribution.
United Kingdom
Medicines and Healthcare products Regulatory Agency traceability requirements sustain verification platform investment despite post-EU regulatory divergence. London pharmaceutical distributors maintain parallel compliance stacks for EU and domestic markets. The Cambridge life sciences cluster generates demand for SaaS serialization among emerging biotech firms.
Epedigree Software Market Key Industry Players
Enterprise software conglomerates and specialized traceability vendors split the market between integrated ERP modules and standalone verification platforms. Consolidation pressure intensifies as pharmaceutical distributors demand unified compliance stacks rather than fragmented point solutions. Two strategic archetypes dominate: cloud-native serialization specialists and legacy ERP extenders. M&A activity concentrates on API-first integration capabilities, while strategic partnerships with third-party logistics providers expand addressable transaction volume.
Within the enterprise software tier, Oracle and SAP exemplify divergent approaches to pharmaceutical traceability. Oracle leverages multi-tenant cloud architectures to serve mid-size generic manufacturers seeking deferred capital expenditure. SAP competes through deep ERP integration that sustains end-to-end supply chain visibility for compliance-heavy clients. Among specialized vendors, TraceLink occupies a position representing API-first integration architectures that compress implementation cycles for systems integrators.
| Leading Market Players |
|---|
| Oracle |
| SAP |
| IBM Corporation |
| Altair Engineering Inc. |
| Antares Vision SpA |
| Axway Software SA |
| Aptean |
| TraceLink Inc. |
| Merit Solutions |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud infrastructure regions serving pharmaceutical serialization workloads is compressing vendor margins while simultaneously expanding buyer negotiating leverage. This utilization dynamic forces software providers to absorb validation and compliance costs rather than pass them through, reshaping both supplier consolidation patterns and procurement committee evaluation criteria.
Pricing Analysis
Price spreads between North American and Indian contract manufacturing deployments exceed three-to-one for equivalent serialization throughput tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation depth and 21 CFR Part 11 audit trail comprehensiveness. Pricing pressure stems from mid-size generic manufacturers deferring capital expenditure through SaaS subscriptions. Biotech firms demonstrate highest price sensitivity due to limited IT infrastructure budgets, while large pharmaceutical distributors prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Upstream feedstock for serialization infrastructure draws from hyperscale cloud providers concentrated in the United States, Germany, and India. Critical component dependencies span GS1-certified barcode hardware, EPCIS event repository software, and blockchain verification node architectures. Single-source vulnerability concentrates on three dominant cloud infrastructure providers for mission-critical verification uptime. Distribution runs through systems integrators and direct enterprise sales channels serving pharmaceutical manufacturers and wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epedigree software is approaching a platform-economics inflection where interoperability standards between FDA DSCSA and EU Falsified Medicines Directive repositories will determine vendor survival. The GS1 EPCIS 2.0 specification shift exemplifies this ecosystem transition.
For Market Incumbents: Pre-empt margin erosion in mid-market generic manufacturing by acquiring API-first integration specialists before systems integrators consolidate the channel. Threat vectors include modular SaaS entrants undercutting full-stack pricing and CDSCO regulatory alignment opening Indian contract manufacturing to low-cost competitors. Vertical integration into edge computing hardware for warehouse anomaly detection represents a defensible lever. For New Entrants and Emerging Players: Establish a beachhead in cell and gene therapy serialization where personalized medicine batch sizes defeat incumbent ERP-integrated architectures. Biotech clusters in Massachusetts and California present the most penetrable geography due to rapid compliance scaffolding requirements. A go-to-market angle anchored to RESTful API deployment compresses implementation cycles and bypasses incumbent professional services moats. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SaaS-native serialization platforms as validation automation reduces quality assurance overhead. Long-term viability over a five-to-ten year window favors vendors with multi-tenant architectures capable of serving both FDA and EMA compliance stacks simultaneously. Acquisition targets should exhibit API-first integration capabilities and existing third-party logistics provider partnerships. The signal to watch is CDSCO enforcement timeline acceleration for Indian pharmaceutical exports.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Multi-tenant architectures serving both FDA DSCSA and EMA FMD compliance stacks reduce vendor fragmentation. |
| Acquisition of Specialist Firm | API-first integration capabilities compress implementation cycles for systems integrators and capture margin pools. |
| Strategic Partnership | Third-party logistics provider alliances expand addressable transaction volume through high-throughput verification nodes. |
| Product Launch | Edge computing inference engines for warehouse anomaly detection differentiate beyond compliance checklists. |
| Geographic Expansion | Indian contract manufacturing organization deployments leverage CDSCO regulatory alignment with international traceability standards. |
Research Approach
A spread of perspectives from pharmaceutical supply chain officers, regulatory affairs leads, serialization platform engineers, and third-party logistics procurement managers converged on the working assumptions. Primary interviews combined with secondary validation against FDA DSCSA guidance documents, EMA delegated acts, GS1 implementation guidelines, and pharmaceutical distributor SEC filings. Bottom-up deployment sizing across cloud, on-premise, and hybrid architectures triangulated with top-down market aggregation.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, organizational scale, integration complexity, and regional regulatory cluster. CAGRs derived from pharmaceutical serialization mandate enforcement timelines and biotech pipeline expansion rates. Industry-specific forecast inputs encompass DSCSA deadline compliance curves and EMA repository system interoperability specifications.
Stress conditions across FDA enforcement acceleration, EU member state repository synchronization delays, and Indian CDSCO mandate timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and cloud infrastructure cost trajectories. Cross-checking against pharmaceutical distributor capital expenditure disclosures and systems integrator backlog reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Deviation Management and CAPA Platforms for Cold Chain Logistics Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Online Dating Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
Smart and Connected Offices Market
Digital Solutions
API Management Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Global Asset Reliability Software Market
Digital Solutions
Digital Library Software Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
Big Data and Data Engineering Services Market