
 Lecture Capture Systems Market | 2026-2036
Lecture Capture Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Lecture Capture Systems Market Intelligence
The market's center of gravity is pivoting from hardware-centric deployments in higher education toward scalable, software-based solutions for corporate training. Kaltura Inc. specializes in flexible cloud platforms catering to enterprise video needs. Panopto Inc. sustains its leadership by offering deep integrations with university learning management systems. TechSmith Corporation competes with user-friendly screen recording tools for individual creators and smaller teams.
Lecture capture systems are integrated solutions designed to record, process, and distribute educational content. These platforms typically synchronize multi-source inputs, including presenter video, audio, and screen content like presentations. The primary purpose is to create a searchable, on-demand digital library for students and trainees. While hardware-based systems still exist, cloud-based solutions are gaining share due to their scalability, and corporate training is emerging as a high-growth application.
Product development is shaped by accessibility and data privacy mandates. In the United States, ADA compliance drives the inclusion of features like automated captioning. Concurrently, Europe's GDPR imposes strict rules on student data collection, consent, and storage for recorded lectures. Vendors must therefore balance the demand for powerful analytics with evolving privacy norms to maintain market access.
Market Dynamics
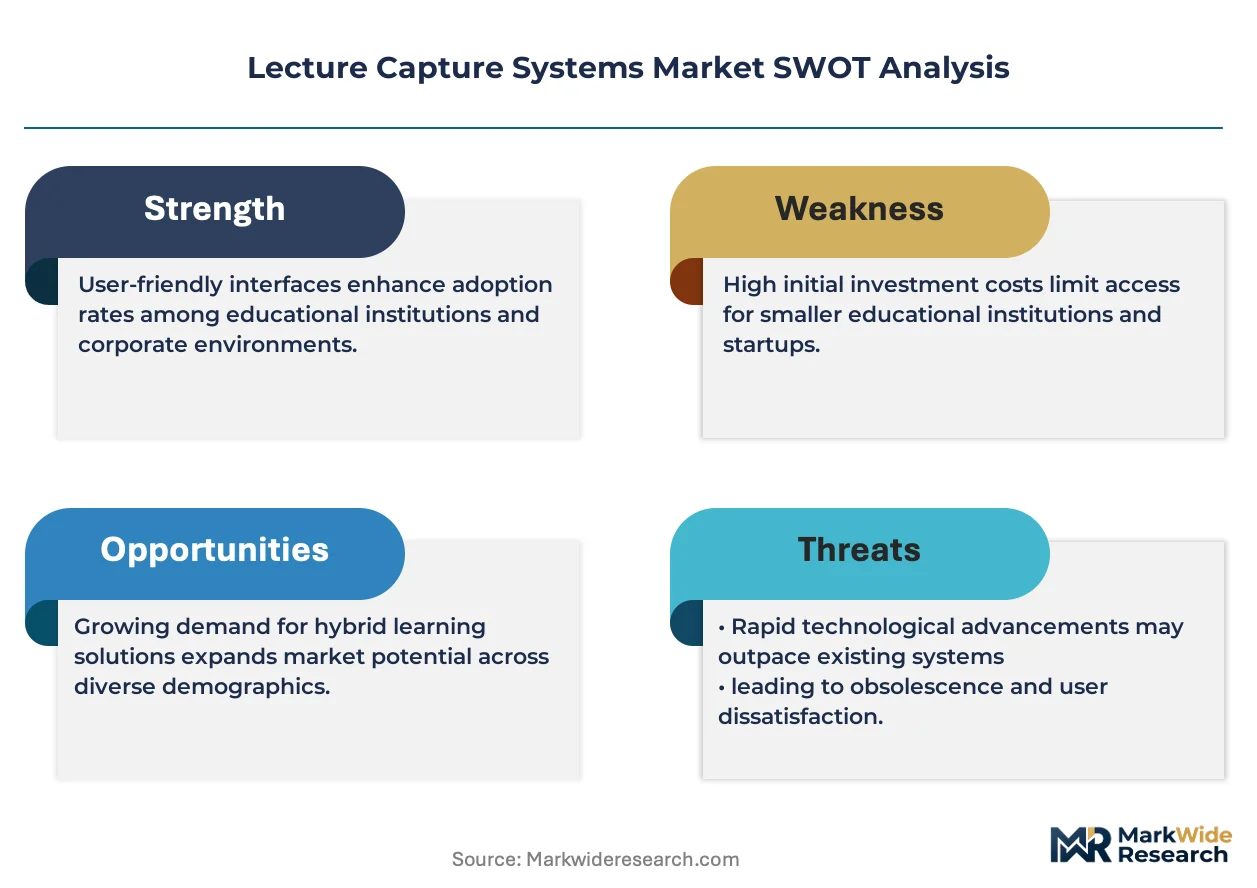
The market's primary dynamic is the migration from capital-intensive, hardware-based systems in academia to scalable, cloud-native software platforms. This shift is propelled by accelerating demand from the corporate sector for flexible and data-rich employee training and development solutions.
Growth Catalysts
- Corporate Training Expansion:Businesses are increasingly deploying lecture capture for scalable employee onboarding, compliance training, and professional development, creating a high-growth demand vector beyond traditional higher education.
- AI-Powered Automation:The integration of artificial intelligence for automated video transcription, captioning, and content indexing significantly enhances searchability and accessibility, directly responding to mandates like the ADA in the United States.
- Hybrid Learning Models:The institutionalization of hybrid and remote learning formats in universities across North America and Europe solidifies the need for robust, integrated systems to support asynchronous student access.
Market Restraints
- Data Privacy and Governance:Strict regulations, notably Europe's GDPR, impose complex consent management and data residency requirements on recorded content, increasing compliance costs and development complexity for vendors.
- High Initial Investment:The upfront cost for comprehensive, hardware-based capture appliances and dedicated recording studios remains a significant barrier for smaller educational institutions and budget-constrained organizations.
- Legacy System Integration:Challenges in ensuring seamless interoperability with a fragmented landscape of existing Learning Management Systems (LMS) and enterprise IT infrastructures can delay or complicate implementation projects.
Strategic Opportunities
- Healthcare and Medical Education:There is a significant opportunity in applying these systems for surgical procedure recording, clinical skills training, and delivering continuing medical education (CME) content for healthcare professionals.
- Emerging Market Penetration:Higher education institutions in rapidly developing economies like India and Brazil represent a substantial, underpenetrated market as they modernize their educational technology infrastructure.
- Microlearning Content Creation:A market exists for specialized tools designed to create, manage, and distribute short-form video content optimized for mobile-first consumption in corporate microlearning and just-in-time training scenarios.
Industry Challenges
- Content Security and IP Protection:Protecting valuable institutional intellectual property and sensitive student data within recorded lectures from unauthorized access and cyber threats is a persistent operational challenge for platform providers.
- Faculty and Trainer Adoption:Overcoming user resistance and ensuring widespread, effective adoption by educators and trainers requires substantial institutional investment in professional development and ongoing technical support.
- Network and Storage Demands:Managing the escalating storage costs and network bandwidth requirements associated with a growing library of high-definition video assets strains institutional IT budgets and infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lecture Capture Systems Market |
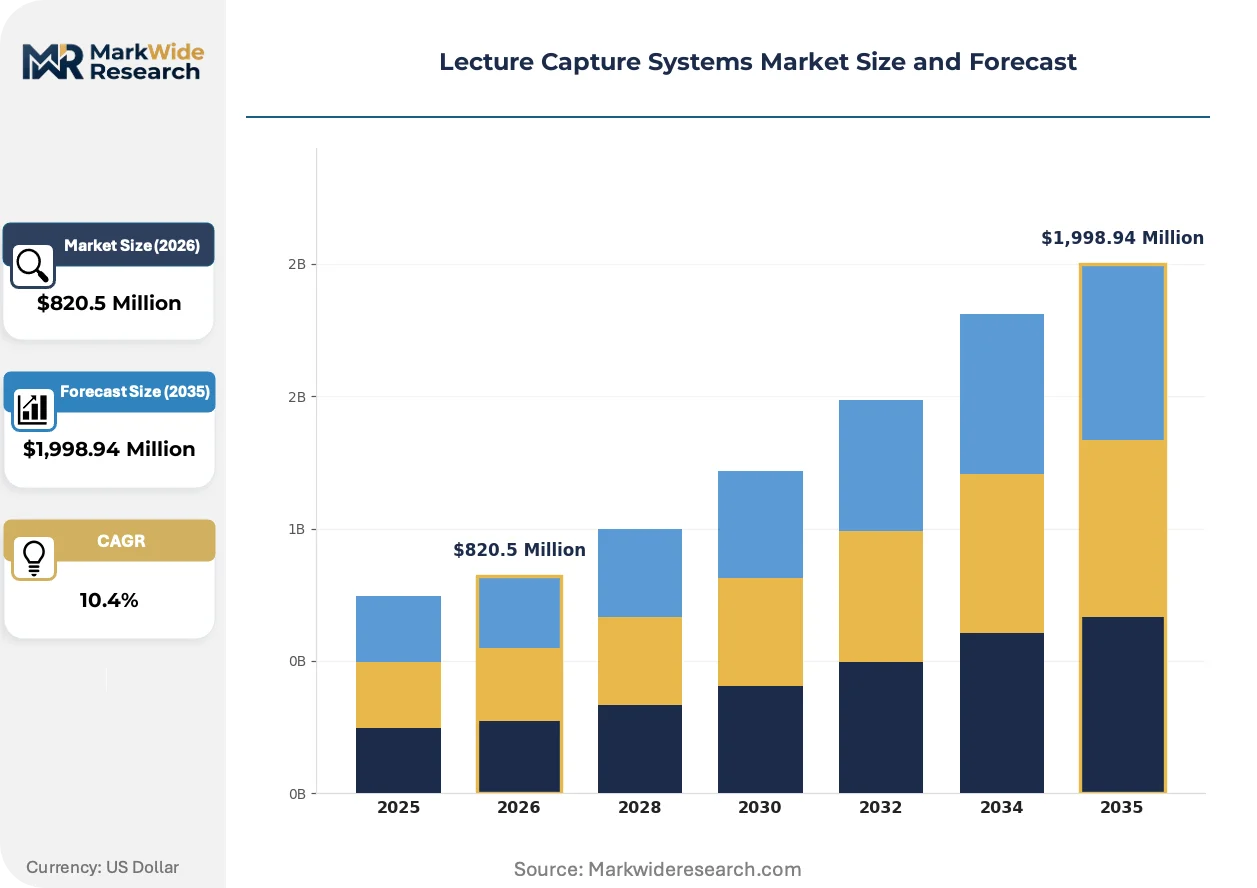
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,998.94 Million |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware-Based, Software-Based, Cloud-Based, Hybrid Systems Technology: Screen Recording, Video Streaming, Interactive Whiteboards, Audio Capture, Automated Editing Application: Higher Education, Corporate Training, K-12 Education, Professional Certification, E-Learning Platforms End User: Universities, Training Institutes, Online Educators, Video Production Teams |
| Companies Covered | Panopto Inc., YuJa Corporation, Echo360 Inc., Kaltura Inc., Cisco Systems Inc., TechSmith Corporation, Haivision Systems Inc., Panasonic Holdings Corp., Adobe Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lecture Capture Systems Market Strategic Shifts & Innovations
Product innovation is centered on transforming captured video from a passive archive into an active, data-rich asset. The convergence of AI-driven analytics with enhanced accessibility features is defining the next generation of platforms, moving beyond simple recording to offer measurable learning insights.
AI-powered analytics provide deep insights into learner engagement. This technology tracks viewer behavior, identifies points of confusion, and generates data on content effectiveness. Corporate learning and development departments are the primary adopters, using the data to quantify the impact and ROI of training programs. This analytical capability is expanding into a predictive tool for personalizing learning paths and proactively identifying students or trainees who may require additional support.
Accessibility mandates are fundamentally shaping product design and procurement criteria. Regulations like the Americans with Disabilities Act (ADA) in the United States and parallel directives in the European Union are making automated captioning and searchable transcripts non-negotiable features. This regulatory pressure forces vendors to build accessibility into the core of their platforms, not as an add-on. The higher education segment is most impacted, with ADA compliance becoming a key factor in purchasing decisions.
Subscription-based SaaS models are rapidly displacing perpetual licensing for on-premise hardware. This shift aligns with broader enterprise IT trends favoring operational expenditures (OpEx) over large, upfront capital expenditures (CapEx). The model offers customers greater flexibility, scalability, and access to continuous updates without requiring significant hardware management. This trend is most advanced in North America and Western Europe, where mature cloud infrastructure supports reliable service delivery.
Lecture Capture Systems Market Segmentation
Segmentation analysis provides a granular view of the Lecture Capture Systems market, revealing distinct characteristics and growth patterns across various dimensions. Understanding these segments helps stakeholders identify specific opportunities and tailor strategies to address diverse user needs and technological preferences within the evolving landscape.
Product Type:
The product type segmentation highlights the spectrum from highly standardized, off-the-shelf solutions to deeply customized, integrated deployments. Each category offers distinct advantages regarding implementation complexity, scalability, and operational control for end users.
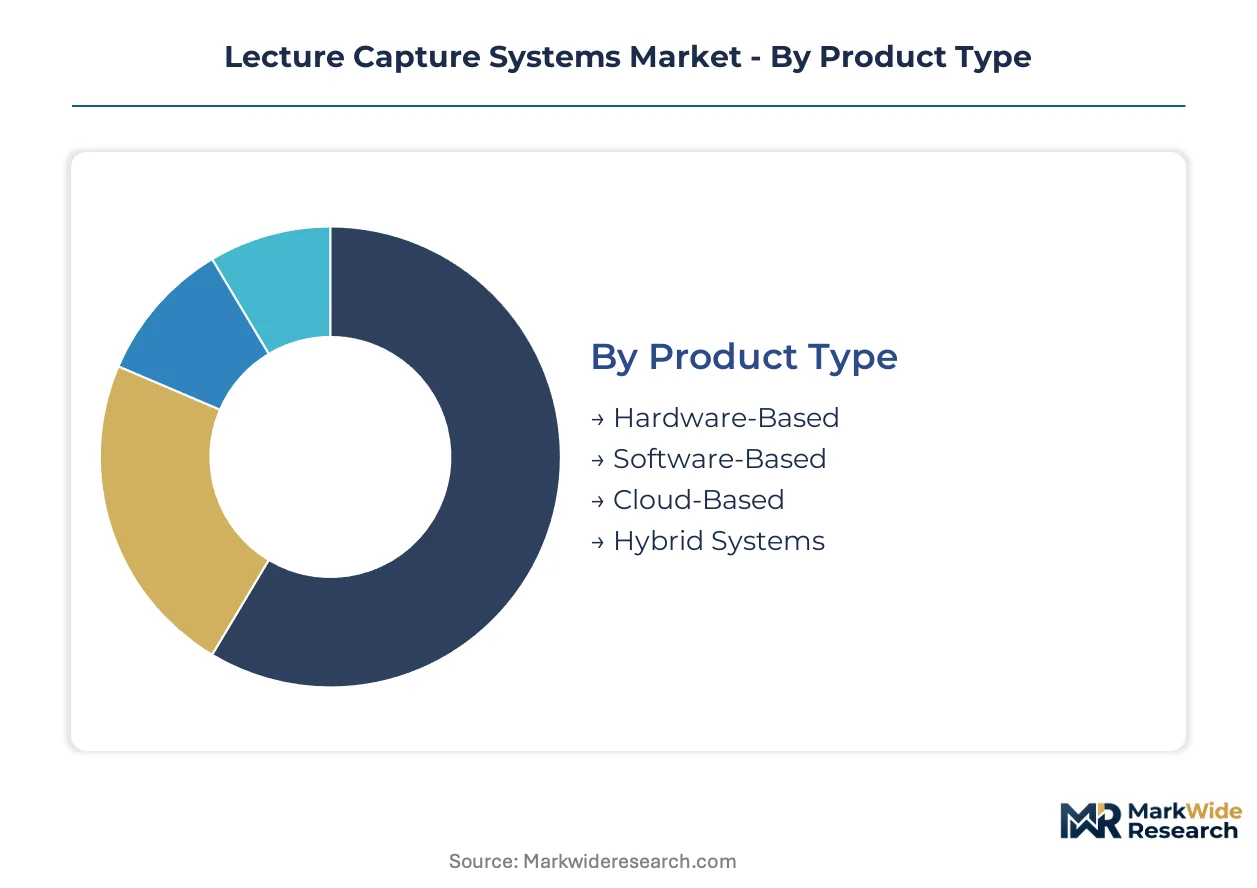
- Cloud-Based:Cloud-Based solutions deliver content and management via internet infrastructure, offering significant scalability and reduced upfront capital expenditure. Demand is accelerating from corporate training departments and higher education institutions seeking operational flexibility.
- Software-Based:Software-Based systems primarily consist of applications installed on local servers or user devices, providing extensive control over data and customization options. These solutions are heavily utilized by universities requiring deep integration with existing learning management systems.
- Hardware-Based:Hardware-Based systems involve dedicated physical devices for recording, often integrated into lecture halls or studios.
- Hybrid Systems:Hybrid Systems combine elements of both hardware and software, offering a balance of local control and cloud-based scalability.
Most installed capacity flows through Hardware-Based systems. Expansion is steepest in Cloud-Based solutions.
Technology:
Technological distinctions define the core functionalities and user interaction models within lecture capture systems. These advancements directly influence content quality, accessibility, and the efficiency of content creation and distribution workflows.
- Automated Editing:Automated Editing technology leverages artificial intelligence to streamline post-production, including transcription, captioning, and content indexing. This innovation significantly enhances content searchability and accessibility, particularly for ADA compliance in the United States.
- Video Streaming:Video Streaming enables real-time or on-demand delivery of recorded content over networks to a wide audience. Its pervasive use in e-learning platforms ensures broad access to educational materials for students and trainees globally.
- Screen Recording:Screen Recording captures digital content displayed on a computer monitor, essential for software tutorials and presentation-based lectures.
- Interactive Whiteboards:Interactive Whiteboards integrate digital writing and drawing capabilities directly into recorded sessions, enhancing engagement and visual explanations.
- Audio Capture:Audio Capture focuses on high-fidelity sound recording, a fundamental component for clear communication in all lecture capture scenarios.
Advanced analytics capabilities are enhancing the utility of Automated Editing, while Video Streaming remains fundamental for content delivery.
Application:
Application segmentation delineates the primary sectors leveraging lecture capture, reflecting diverse educational and training imperatives. Each sector presents unique requirements for content delivery, learner engagement, and platform integration.
- Corporate Training:Corporate Training applications involve using lecture capture for employee onboarding, compliance education, and professional development programs. Businesses are investing in these systems to achieve scalable and consistent employee skill enhancement.
- Higher Education:Higher Education applications encompass recording lectures, seminars, and virtual classes for asynchronous student access and pedagogical support. Universities in North America and Europe rely on these systems to support hybrid learning models.
- K-12 Education:K-12 Education utilizes lecture capture for flipped classrooms, remote learning support, and teacher professional development within primary and secondary schools.
- Professional Certification:Professional Certification bodies deploy these systems to deliver standardized training and examination preparation for various industries.
- E-Learning Platforms:E-Learning Platforms integrate lecture capture to build comprehensive online courses and digital learning libraries for global audiences.
While Higher Education represents the foundational demand, Corporate Training is experiencing significant investment and expansion.
End User:
End user segmentation categorizes the organizational entities primarily deploying lecture capture solutions, impacting procurement and deployment scales. The specific needs of each user group influence feature prioritization and vendor selection.
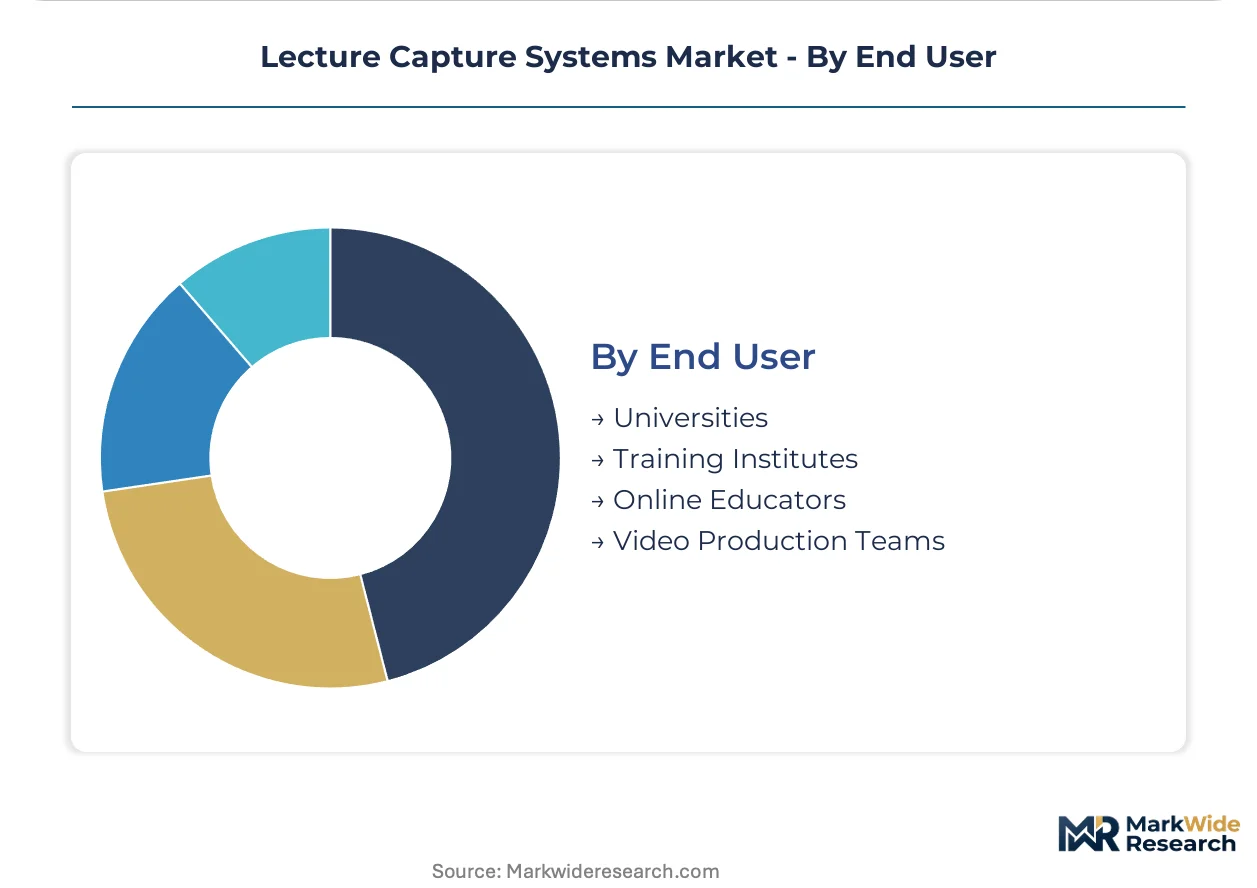
- Universities:Universities represent large institutional clients requiring robust, integrated systems for campus-wide content creation and distribution. Their demand is driven by the need to support diverse academic programs and student populations.
- Training Institutes:Training Institutes, including vocational schools and specialized certification bodies, utilize lecture capture to deliver structured curricula and practical skill demonstrations. These entities prioritize platforms that offer certification-aligned content management.
- Online Educators:Online Educators are individual instructors or small teams creating digital course content for various e-learning platforms.
- Video Production Teams:Video Production Teams within organizations use lecture capture systems for high-quality content creation, often for marketing or internal communications.
Large-scale institutional deployments are driven by Universities, with specialized content creators increasingly relying on Online Educators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diverse regulatory environments significantly influence market entry and product development strategies for lecture capture systems. Vendors must carefully balance powerful analytics with evolving privacy norms to maintain market access across different jurisdictions. This strategic adaptation shapes regional investment and feature prioritization.
United States
The United States market experiences strong demand from both higher education institutions and the expanding corporate training sector. ADA compliance drives the widespread integration of automated captioning and transcription features across platforms. Silicon Valley companies and Boston-area ed-tech firms actively develop cloud-native solutions, focusing on scalability and advanced analytics for educational content.
Germany
European demand, particularly in Germany, emphasizes robust data privacy and secure content delivery, supporting hybrid learning models. GDPR imposes strict rules on student data collection and storage, directly impacting vendor offerings and compliance costs. Berlin's vibrant startup ecosystem fosters innovation in secure, high-quality lecture capture technologies for both academic and corporate clients.
India
Modernization efforts in India's educational technology infrastructure present significant opportunities for lecture capture system providers. The National Education Policy 2020 actively promotes digital learning and online content creation across all educational levels. Bangalore's burgeoning IT hubs develop scalable e-learning platforms and content management solutions tailored for a large student population.
Japan
Digital transformation initiatives in Japan's universities and corporate upskilling programs are driving increased adoption of lecture capture systems. METI promotes digital education tools and mandates stringent data security standards for educational content. Tokyo-based technology firms integrate AI for enhanced content accessibility and analytics, supporting both domestic and regional market expansion.
Lecture Capture Systems Market Key Industry Players
Technological innovation dominates the current competitive landscape for lecture capture systems, driving continuous product evolution. The market features a blend of established players with deep institutional ties and agile cloud-native providers. Strategic archetypes include comprehensive platform developers, specialized LMS integrators, and user-friendly screen recording tool vendors serving diverse user needs. Competitive moves center on AI-powered automation, strategic partnerships for broader ecosystem integration, and portfolio diversification into scalable software solutions.
Specialists in enterprise video solutions, Panopto Inc. and Kaltura Inc., exemplify the market's shift towards comprehensive, integrated platforms. Panopto Inc. maintains a strong position through deep integrations with university learning management systems, representing a key archetype focused on academic institutions. Kaltura Inc. anchors the segment for flexible cloud platforms, catering extensively to broader enterprise video needs and corporate training initiatives. TechSmith Corporation sits within the category of providers offering user-friendly screen recording tools, serving individual creators and smaller team requirements.
| Leading Market Players |
|---|
| Panopto Inc. |
| YuJa Corporation |
| Echo360 Inc. |
| Kaltura Inc. |
| Cisco Systems Inc. |
| TechSmith Corporation |
| Haivision Systems Inc. |
| Panasonic Holdings Corp. |
| Adobe Inc. |
Cost & Logistics Intelligence
Venture-backed software specialists, driving innovation in cloud platforms, often dictate supply behavior and pricing discipline through their rapid development cycles and scalable service models. This dynamic influences both component sourcing and end-user subscription costs.
Pricing Analysis
Direct-to-enterprise discounts define the primary channel-margin layer for large institutional deployments of lecture capture systems. Subscription-based SaaS models represent the dominant pricing structure, offering operational expenditure flexibility to customers. Price differentiation stems from customization levels and the inclusion of advanced AI-powered analytics features. Pricing softness reflects the increasing competition from open-source alternatives and the commoditization of basic recording functionalities. Corporate training departments are typically less price-sensitive than budget-constrained K-12 educational institutions.
Supply Chain Analysis
Single-source vulnerability sits with specialized software development teams for core platform functionalities, particularly in AI-driven automation. Geographic supply concentration for hardware components centers on East Asian manufacturing hubs like China and Taiwan. Raw material dependencies include microprocessors, memory modules, and specialized optical sensors for capture devices. Regulatory restrictions on data residency, such as Europe's GDPR, introduce a structural risk by requiring localized data storage infrastructure. Distribution runs through direct sales teams and value-added resellers targeting educational and corporate sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lecture Capture Systems market functions as a stable compounder, with the institutionalization of hybrid learning models driving steady, predictable growth across educational and corporate segments.
For Market Incumbents: Acquire specialized AI-driven analytics firms to enhance platform intelligence and personalize learning insights. This move helps counter emerging threats from agile cloud-native providers offering superior data processing capabilities. Integrate advanced accessibility features to meet evolving ADA compliance mandates, a crucial lever for retaining higher education market share.
For New Entrants and Emerging Players: Launch via a freemium model targeting individual online educators and small training institutes to build initial user bases. Focus on underpenetrated emerging markets like India and Brazil, offering localized support and simplified user interfaces. Develop specialized microlearning content creation tools, providing a distinct go-to-market angle for mobile-first consumption.
For Investors and Strategic Acquirers: Private equity firms are the most active acquirer in this space, seeking to consolidate fragmented software providers with strong recurring revenue streams. Target acquisition archetypes include niche providers with proprietary AI algorithms or deep integrations with specific Learning Management Systems. A signal to watch is the increasing investment in secure, compliant cloud infrastructure for educational content, indicating long-term platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-powered Content Indexing | This enhances content searchability and accessibility, crucial for ADA compliance and user engagement. |
| Expand Cloud Infrastructure in Europe | This addresses GDPR data residency requirements and supports hybrid learning models in the region. |
| Develop Microlearning Authoring Tools | This caters to the growing demand for short-form, mobile-optimized training content in corporate settings. |
| Form Strategic Partnerships with LMS Vendors | This ensures seamless integration and broadens market reach within higher education institutions. |
| Invest in Cybersecurity for Content Protection | This safeguards intellectual property and sensitive student data, a persistent challenge for platform providers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. The study engaged IT procurement officers, university administrators, corporate learning and development managers, and software engineers. Secondary data sources included academic journals, company financial reports, government education statistics, and ed-tech patent filings, triangulating findings from both bottom-up and top-down perspectives.
The forecast framework anchored the projection horizon to comparable historical reference periods, ensuring continuity in trend analysis. Segmentation dimensions modeled included product type, technology, application, end-user, and regional adoption patterns. Compound annual growth rates were derived from a multi-factor regression model, incorporating educational technology spending and corporate training budgets as key industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including rapid technological obsolescence and shifting regulatory interpretations of data privacy. Forecasts reflect assumptions documented through extensive primary and secondary research. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Data Integration Market
Digital Solutions
Europe Online Dating Services Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Construction Design App Market
Digital Solutions
UK Route Optimization Software Market
Digital Solutions
Global B2B Buyer Intent Data Tools Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Global Intelligent Document Processing Market
Digital Solutions
Location-Based Services (LBS) Market
Digital Solutions
Accounts Receivable Automation Market
Digital Solutions
Global Demand Side Platforms (DSP) for Programmatic Advertising Market
Digital Solutions
Document Management System Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Workspace As a Service Market