
 Data Fusion Solutions Market | 2026-2036
Data Fusion Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Data Fusion Solutions Market Outlook
Multi-source data sourcing from disparate cloud and on-premises repositories is consolidating around platforms that normalize schema conflicts before analytics consumption. Snowflake leverages elastic compute separation to sustain query performance across federated datasets. Palantir Technologies anchors government and defense contracts through ontology-based integration that preserves lineage. Microsoft competes by extending Fabric's unified data stack into hybrid environments where sovereign cloud requirements persist.
Data fusion solutions architecturally combine heterogeneous streams—structured warehouse tables, semi-structured logs, and unstructured sensor feeds—into query-ready unified views through schema-on-read engines, ontology mapping, and distributed stream processing. These systems primarily serve organizations requiring operational intelligence without the latency of traditional extract-transform-load pipelines. Cloud-based deployment captures the fastest expansion as enterprises retire fixed-capacity data centers for consumption-priced alternatives. Real-time processing segments command premium positioning where milliseconds determine fraud detection or predictive maintenance value. Batch processing retains volume dominance in regulatory reporting and historical analytics where latency tolerance permits cost optimization.
FDA's 21 CFR Part 11 electronic records requirements shape healthcare provider adoption by mandating immutable audit trails across fused clinical and operational data. The EU AI Act imposes conformity assessments on automated decision systems built from fused inputs, forcing re-architecture of black-box integration layers. ISO 27001 and SOC 2 Type II certifications function as table stakes for vendor selection in financial services procurement. Stakeholders must evaluate whether their current fusion platforms can expose provenance chains sufficient for emerging algorithmic accountability mandates without rebuilding core integration logic.
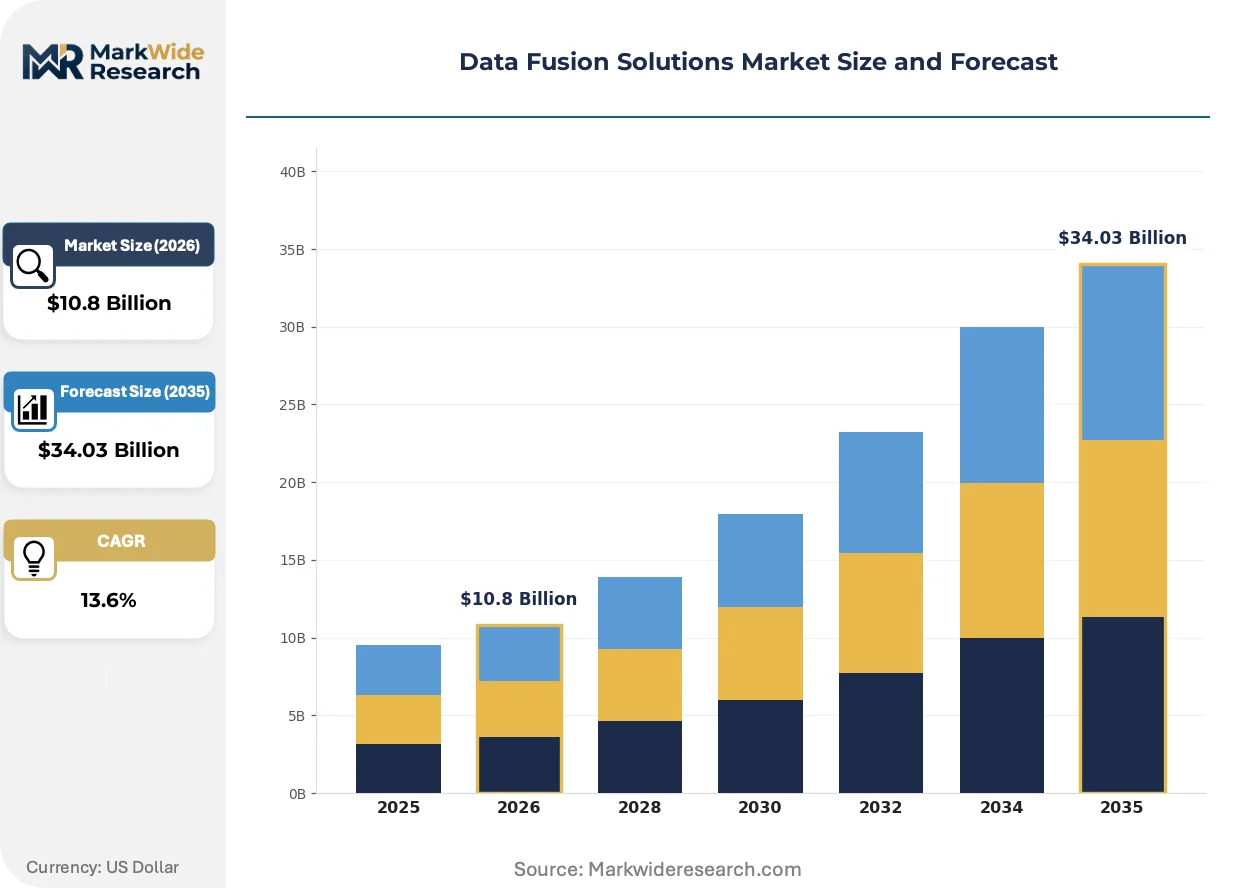
Market Dynamics
The Data Fusion Solutions Market pivots on the tension between real-time operational intelligence requirements and the architectural rigidity of legacy data warehouses. Defense agencies and automotive manufacturers now mandate sub-second query latency across federated sources, forcing infrastructure rebuilds that bypass traditional ETL bottlenecks entirely.
Growth Catalysts
- EU AI Act Conformity Assessments:Automated decision systems in financial services require auditable provenance chains, driving demand for governed fusion architectures that expose lineage natively.
- Smart Manufacturing Sensor Unification:German automotive clusters require real-time harmonization of heterogeneous machine data streams for predictive maintenance and quality control.
- NATO Multi-Source Intelligence Mandates:Defense agencies across member states fund ontology-based integration platforms that preserve semantic relationships across classified and open-source feeds.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers proficient in distributed stream processing and ontology engineering constrains deployment velocity for complex fusion projects.
- Cloud Egress Cost Volatility:Cross-cloud data movement fees accumulate unpredictably when federated queries traverse multiple provider environments.
- GDPR Data Residency Friction:Strict localization requirements prevent seamless fusion across EU and non-EU jurisdictions, fragmenting unified views.
Strategic Opportunities
- Healthcare Clinical-Operational Fusion:FDA 21 CFR Part 11 compliance creates demand for immutable audit trails across fused electronic health records and operational systems.
- Edge-to-Cloud Stream Convergence:5G-enabled manufacturing facilities in Japan and South Korea require distributed processing architectures that harmonize plant-floor and enterprise data.
- ISO 27001 Certification Differentiation:Financial services procurement increasingly mandates SOC 2 Type II and ISO 27001 as baseline vendor qualifications, favoring certified platform providers.
Industry Challenges
- Schema Drift Management:Continuous evolution of upstream source structures breaks query-ready unified views, requiring automated detection and remapping pipelines.
- Legacy Warehouse Integration:Decades-old on-premises data infrastructure resists API-based connectivity, necessitating costly middleware layers or full migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Fusion Solutions Market |
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $34.03 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Data Integration, Real-Time Processing, Batch Processing, Data Analytics Deployment Model: On-Premises, Cloud-Based, Hybrid, Multi-Cloud End User: Retail Sector, Financial Services, Government Agencies, Healthcare Providers Technology: Machine Learning, Statistical Analysis, API Management, Big Data |
| Companies Covered | Snowflake, IBM, Accenture, Google Cloud, Palantir Technologies, Infosys, Microsoft, Oracle, Tata Consultancy Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Fusion Solutions Market Strategic Shifts
Data fusion architecture is fragmenting from monolithic platforms into composable stacks that buyers assemble from specialized components. Vendors now compete on interoperability rather than lock-in, with schema-on-read engines and ontology layers becoming separable purchase decisions.
Knowledge graph technology is modularizing data integration workflows by externalizing relationship semantics from hard-coded ETL scripts. Defense contractors and pharmaceutical firms adopt graph-native fusion to preserve entity resolution across disparate intelligence or clinical sources. This shift compresses time-to-insight by eliminating repeated transformation cycles when source schemas change.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes automated decisions built from fused inputs. Healthcare providers and credit scoring agencies must reconstruct provenance chains that were previously opaque in black-box integration layers. German automotive suppliers now embed conformity assessment checkpoints into their data pipelines preemptively.
Buyer procurement patterns favor consumption-priced deployment over fixed-capacity licensing, accelerating cloud-native platform selection. Financial services firms in Frankfurt and Singapore negotiate utility-based contracts that scale with query volume rather than provisioned infrastructure. This shift pressures incumbent vendors to retire perpetual license models or lose competitive evaluations.
Data Fusion Solutions Market Segmentation
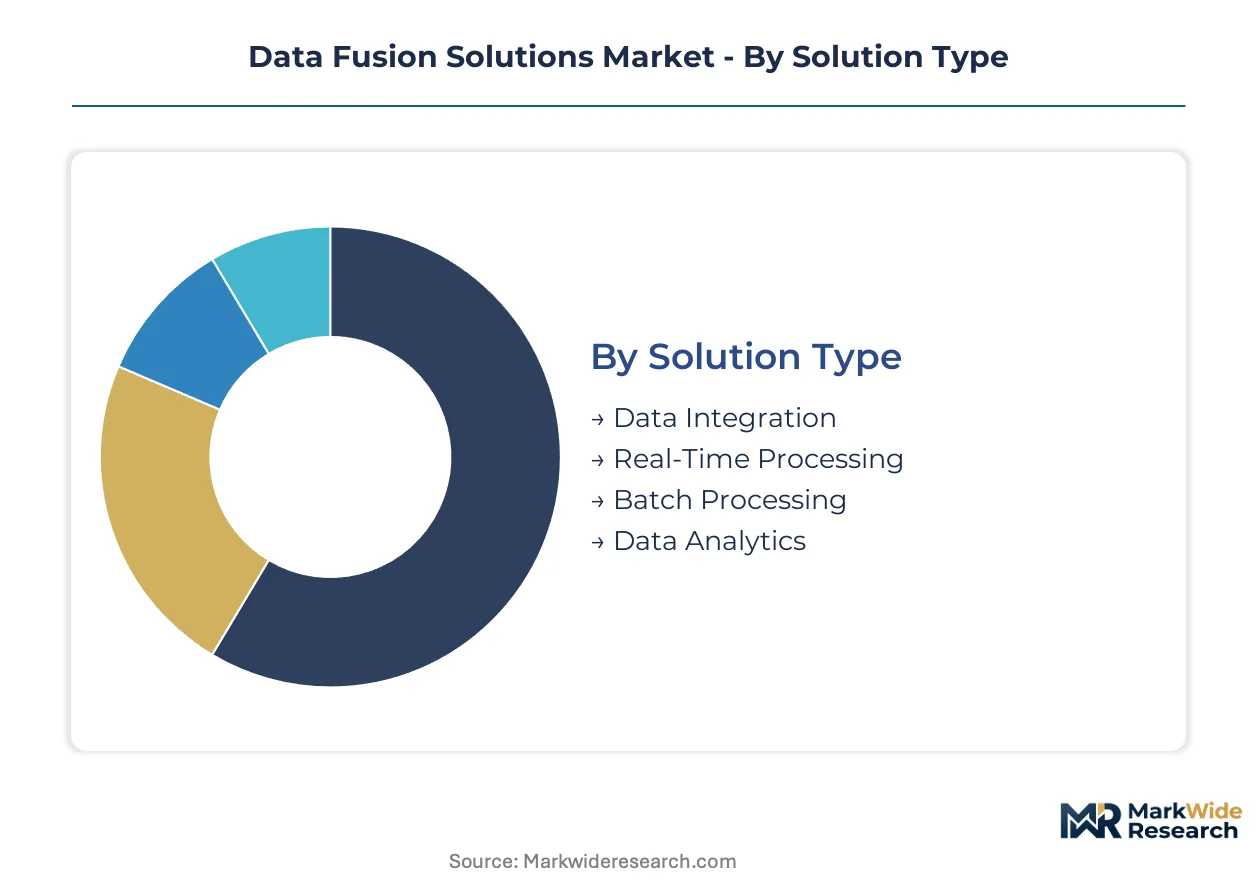
Data fusion solutions fragment across multiple technical and commercial dimensions. Buyers select architectures based on latency tolerance, sovereignty constraints, and existing infrastructure investments rather than single-vendor consolidation.
Solution Type:
Real-time processing platforms command the highest upfront capital allocation due to distributed stream infrastructure and sub-second latency engineering.
- Data Integration:Schema normalization engines harmonize disparate source structures into query-ready unified views. German automotive clusters deploy these for predictive maintenance pipelines bridging factory-floor sensors with enterprise ERP systems. Most installed capacity flows through Data Integration. Expansion is steepest in Real-Time Processing.
- Real-Time Processing:Distributed stream processing architectures sustain millisecond query latency across federated sources. NATO defense agencies mandate these for multi-source intelligence fusion where operational decisions depend on immediate data synthesis.
- Batch Processing:Scheduled ETL workflows optimize cost for regulatory reporting and historical analytics where latency tolerance permits overnight processing windows.
- Data Analytics:Consumption-layer tools execute queries against pre-fused datasets without managing underlying integration logic.
Capital deployment skews toward latency-sensitive segments despite higher infrastructure costs.
Deployment Model:
Cloud-based platforms now absorb the majority of new procurement spend as enterprises retire fixed-capacity data centers.
- Cloud-Based:Consumption-priced compute separates storage from query processing, enabling elastic scaling without provisioned infrastructure commitments. Financial services firms in Frankfurt and Singapore negotiate utility-based contracts tied to query volume rather than fixed licensing.
- Hybrid:Architectures split sensitive data residency on-premises while bursting compute to cloud environments. Healthcare providers under FDA 21 CFR Part 11 requirements retain immutable audit trails locally while leveraging cloud analytics for non-regulated workloads.
- On-Premises:Fixed-capacity deployments persist in classified defense environments where air-gapped networks prevent external connectivity.
- Multi-Cloud:Federated queries traverse multiple provider environments, though unpredictable egress fees complicate total cost forecasting.
Procurement velocity concentrates in Cloud-Based models. Hybrid architectures gain share fastest among regulated industries.
End User:
Government agencies represent the most technically demanding customer segment due to classified data handling and ontology complexity requirements.
- Government Agencies:Defense and intelligence organizations require ontology-based integration preserving semantic relationships across classified and open-source feeds. NATO member states fund these platforms as mission-critical infrastructure.
- Financial Services:EU AI Act conformity assessments force auditable provenance chains for automated credit and fraud decisions. Firms re-architect black-box integration layers to expose lineage natively.
- Healthcare Providers:Clinical-operational fusion demands immutable audit trails across electronic health records and operational systems under FDA electronic records requirements.
- Retail Sector:Real-time inventory and customer data unification supports omnichannel fulfillment optimization.
Technical complexity peaks in Government Agencies. Regulatory pressure drives fastest adoption acceleration in Financial Services.
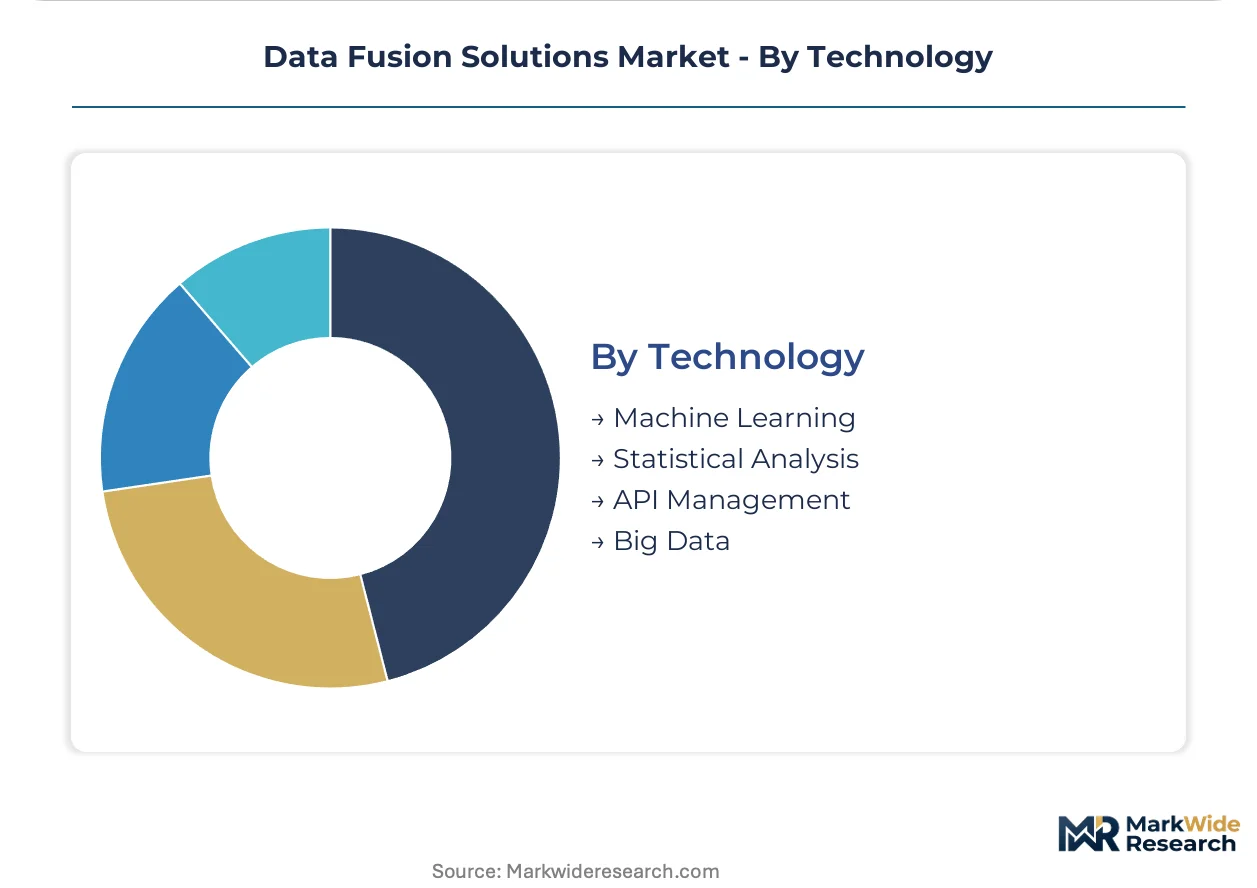
Technology:
Machine learning layers require the most specialized engineering investment for model training and inference integration.
- Machine Learning:Automated pattern recognition across fused datasets enables predictive maintenance, anomaly detection, and recommendation engines. German automotive suppliers embed conformity assessment checkpoints preemptively for EU AI Act compliance.
- Big Data:Distributed storage and processing frameworks handle petabyte-scale fusion across structured, semi-structured, and unstructured sources.
- Statistical Analysis:Traditional inference methods persist in regulatory reporting where model interpretability requirements prohibit black-box approaches.
- API Management:Connectivity layers standardize access patterns across heterogeneous source systems without custom point-to-point integration.
Engineering talent scarcity constrains Machine Learning deployment velocity. API Management spreads fastest as retrofit layer for legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters anchor demand for real-time sensor-data unification across smart manufacturing operations. Defense agencies in NATO member states fund ontology-based integration platforms. Financial services firms in Frankfurt and Singapore negotiate utility-based contracts tied to query volume.
United States
Defense and intelligence agencies mandate sub-second query latency across federated sources for multi-source intelligence fusion. FDA 21 CFR Part 11 requirements shape healthcare provider adoption through immutable audit trail mandates. The Greater Boston biotech corridor deploys clinical-operational fusion for electronic health records integration.
Germany
Automotive and industrial engineering clusters require real-time harmonization of heterogeneous machine data streams. EU AI Act conformity assessments force auditable provenance chains for automated decision systems. Baden-Württemberg manufacturing facilities embed conformity assessment checkpoints preemptively into data pipelines.
United Kingdom
Financial services firms re-architect black-box integration layers to expose lineage natively for regulatory compliance. GDPR data residency requirements prevent seamless fusion across EU and non-EU jurisdictions. The London financial district concentrates procurement of governed fusion architectures.
Japan
5G-enabled manufacturing facilities require distributed processing architectures harmonizing plant-floor and enterprise data. METI industrial digitization programs accelerate edge-to-cloud stream convergence investments. The Nagoya automotive manufacturing belt leads sensor unification deployments for predictive maintenance.
Singapore
Financial services procurement mandates SOC 2 Type II and ISO 27001 as baseline vendor qualifications favoring certified platform providers. The Monetary Authority of Singapore's technology risk management guidelines shape vendor selection criteria. The city-state's fintech hub concentrates utility-based contract negotiations for cloud-native platforms.
Data Fusion Solutions Market Competitive Environment
Global majors compete with regional champions across deployment model preferences and latency requirements. The vendor base organizes around three tiers: cloud-native specialists, legacy infrastructure extenders, and systems integrators with vertical expertise. Strategic archetypes include schema-on-read engine providers, ontology-based integration specialists, and managed service operators. Competitive moves concentrate on strategic partnerships for hybrid deployment capabilities and portfolio diversification into edge processing.
Within the cloud-native tier, Snowflake and Palantir Technologies exemplify divergent architectural philosophies. Snowflake represents elastic compute separation for federated query performance. Palantir Technologies anchors government and defense contracts through ontology-based integration. IBM occupies a position bridging legacy infrastructure with modern fusion architectures.
| Leading Market Players |
|---|
| Snowflake |
| IBM |
| Accenture |
| Google Cloud |
| Palantir Technologies |
| Infosys |
| Microsoft |
| Oracle |
| Tata Consultancy Services |
| Others |
Value Chain & Pricing Dynamics
Certification-tier divergence between ISO 27001-certified platforms and uncertified alternatives manifests in both subscription pricing premiums and supply chain partner selection, with financial services procurement in Frankfurt and Singapore filtering vendors through compliance gateways that reshape distribution economics.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers governs SaaS-tiered subscription models, with compute and storage fees from hyperscalers flowing directly into customer-facing rates. Price differentiation rests on SOC 2 Type II certification status and real-time latency guarantees, with defense agencies showing least price sensitivity due to mission-critical mandates while mid-market manufacturers face acute pressure from utility-based billing volatility. Cost compression in multi-cloud deployments intensifies as cross-egress fees accumulate unpredictably.
Supply Chain Analysis
Warehouse-distribution layer concentration in Germany, the United States, and Singapore anchors regional service delivery for ontology engineering and stream processing infrastructure. Component dependencies draw from specialized GPU clusters, high-throughput networking hardware, and proprietary graph database licenses. Single-source vulnerability in classified defense environments where air-gapped networks prevent vendor diversification poses structural risk. Distribution runs through certified systems integrators with vertical expertise in government and financial services procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
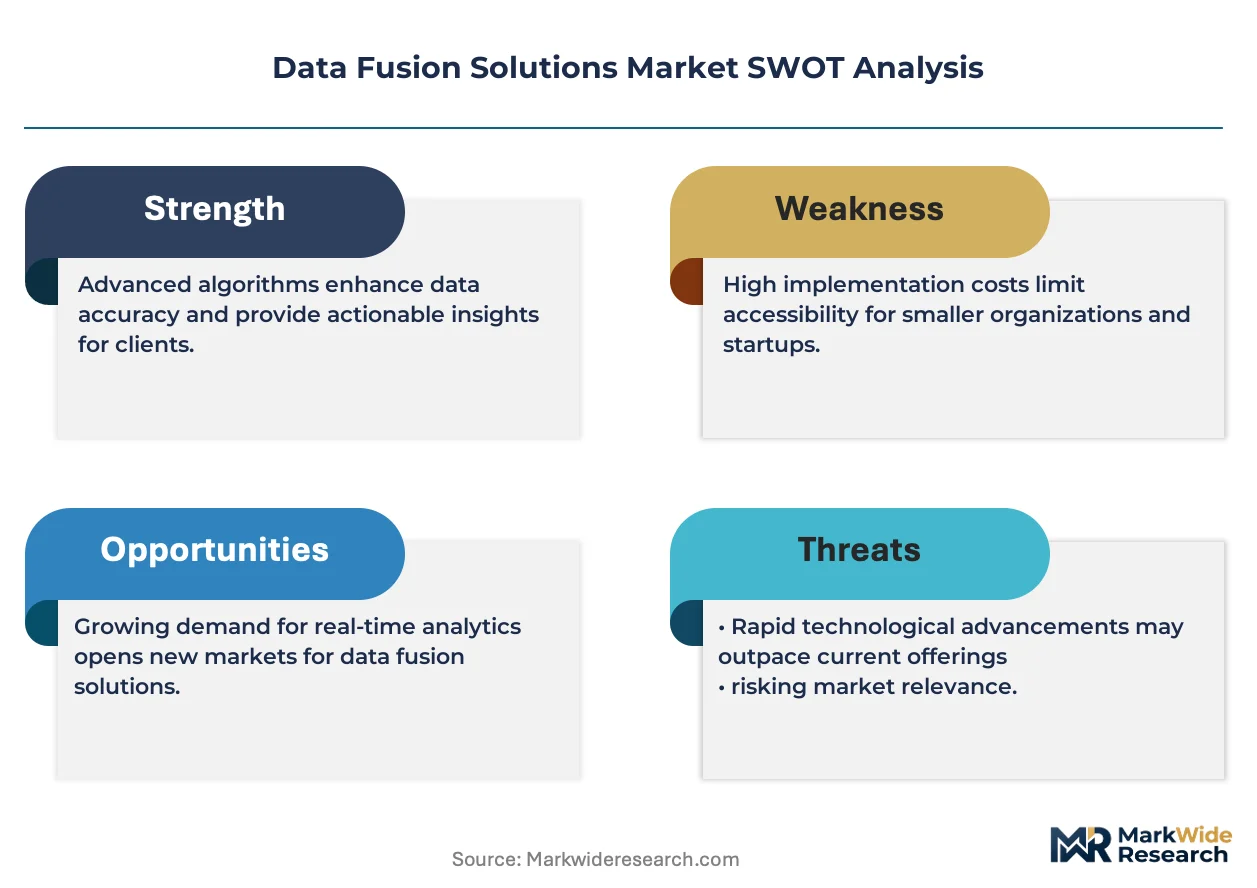
Data fusion solutions constitute a late-cycle quality story as EU AI Act conformity assessments and FDA 21 CFR Part 11 mandates shift procurement toward auditable provenance architectures that command pricing premiums over black-box alternatives.
For Market Incumbents: Acquire ontology engineering talent pools to counter specialized scarcity constraining deployment velocity for NATO defense contracts. Consolidate hybrid deployment capabilities through strategic partnerships with sovereign cloud providers, as GDPR data residency friction fragments unified views and threatens renewal rates in European financial services accounts.
For New Entrants and Emerging Players: Capture edge-to-cloud stream convergence opportunities in 5G-enabled Japanese manufacturing facilities where METI industrial digitization programs accelerate investment but incumbent presence remains thin. Penetrate healthcare clinical-operational fusion through FDA compliance-focused go-to-market positioning that exploits immature audit trail architectures among established vendors.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native specialists possessing ISO 27001 certification and proven government contract execution. Long-term viability favors platforms demonstrating native lineage exposure for algorithmic accountability mandates. Watch for EU AI Act enforcement patterns as inflection indicator for compliance-premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies schema-on-read engines with ontology layers for NATO intelligence fusion requirements. |
| Strategic Partnership | Enables hybrid deployment capabilities addressing GDPR data residency constraints in Frankfurt. |
| Acquisition of Specialist Firm | Secures distributed stream processing talent scarce in German automotive cluster deployments. |
| Geographic Expansion | Targets Singapore fintech hub where MAS technology risk guidelines shape vendor selection. |
| Product Launch | Introduces real-time processing tiers for predictive maintenance in Nagoya manufacturing belt. |
Study Parameters
Bottom-up enterprise deployment modeling reconciled against top-down vendor capacity tracking forms the analytical core. Primary interviews with data platform engineers, government procurement officers, financial services CTOs, and healthcare information systems directors combined with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory filings. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map deployment model adoption patterns, solution type preferences, and end-use intensity across the projection horizon. Segmentation dimensions include latency requirements, sovereignty constraints, integration complexity, and regional regulatory clusters. CAGRs derive from fitted growth curves adjusted for technology substitution effects and compliance mandate timelines.
Regulatory enforcement delays, cloud egress cost volatility, and talent scarcity escalation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about mandate implementation schedules and infrastructure cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Smart Card Reader Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
France ICT Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Asia-Pacific Smart Government Market
Digital Solutions
Space and Workplace Management Software Market
Digital Solutions
Web Performance Market
Digital Solutions
Ticket Admission Systems Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Retail Warehouse Management Systems Market
Digital Solutions
Customer Experience As a Service (Cxaas) Market