
 Smart Card in Government Market | 2026-2036
Smart Card in Government Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Card in Government Market Analytics
Border control agencies and social welfare departments is bifurcating demand between high-security biometric credentials and standardized citizen service cards. Thales Group leverages its aerospace and defense heritage to dominate European national ID tenders with dual-interface chip platforms. IDEMIA sustains competitive intensity through integrated enrollment-to-issuance systems that reduce government procurement complexity. Giesecke+Devrient anchors its position in German-speaking markets with advanced physical security features and polycarbonate card body manufacturing.
A smart card in government contexts denotes a pocket-sized plastic credential embedding a microcontroller chip or secure memory element, typically operating at 13.56 MHz for contactless protocols or ISO/IEC 7816 standards for contact interfaces, designed to authenticate identity, authorize transactions, or grant facility access within public sector systems. Contactless technology leads volume deployment due to transit integration and queue-reduction mandates at government service points, while biometric-embedded variants command premium positioning where immigration and law enforcement agencies require multi-factor verification against template databases. RFID and magnetic stripe segments retain niche utility in legacy infrastructure upgrades and low-cost regional deployments where chip migration budgets remain constrained.
EMA and GDPR frameworks in Europe enforce strict data minimization and citizen consent protocols for government-held biometric templates, directly elevating demand for encryption-certified chip architectures and localized data processing. In the United States, NIST guidelines and FIPS 201 standards for personal identity verification shape product roadmaps through mandated PIV card interoperability across federal agencies. Stakeholders must monitor divergence between regional certification regimes, as chip vendors face escalating compliance costs when technical specifications fragment across national procurement standards rather than converging toward mutual recognition agreements.
Market Dynamics
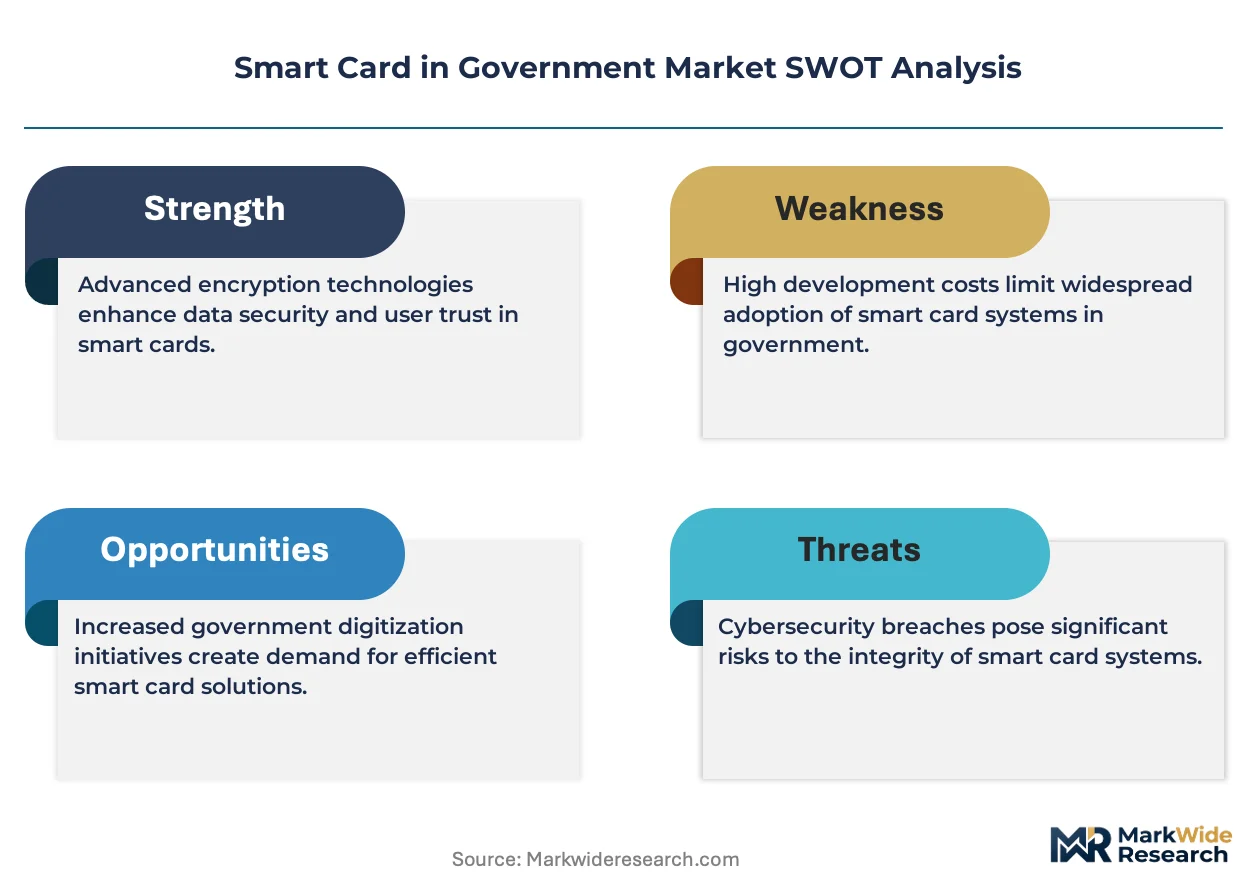
National procurement authorities are consolidating vendor pools around interoperable chip architectures, compressing supplier margins while elevating compliance burdens for encryption certification and localized data processing mandates.
Growth Catalysts
- EU Digital Identity Wallet framework:Mandates for cross-border credential interoperability are accelerating replacement cycles for legacy card systems across member states.
- India's Aadhaar-linked welfare networks:State-level distribution programs for food subsidies and direct benefit transfers are driving volume procurement of contactless credential systems.
- Contactless transit integration:Queue-reduction mandates at government service points are forcing upgrades from magnetic stripe and contact-only interfaces to dual-interface chip platforms.
Market Restraints
- Polycarbonate substrate concentration:German and Japanese specialty chemical suppliers dominate card body material supply, exposing procurement budgets to petrochemical price volatility.
- Biometric template storage fragmentation:GDPR data minimization requirements conflict with law enforcement demands for centralized fingerprint databases, creating procurement paralysis.
- Legacy magnetic stripe infrastructure:Budget-constrained municipal governments in secondary cities delay chip migration, perpetuating dual-system maintenance costs.
Strategic Opportunities
- Mobile driver's license convergence:ISO/IEC 18013-5 compliant smartphone credentials are opening white space in vehicle registration and age verification applications.
- Post-quantum cryptography migration:NIST's standardization of quantum-resistant algorithms creates replacement demand for encryption-certified chips before obsolescence risks materialize.
- ASEAN digital economy frameworks:Cross-border labor mobility agreements between Indonesia, Malaysia, and Singapore are mandating interoperable national ID systems for migrant worker credentialing.
Industry Challenges
- Embedded firmware engineering scarcity:Secure element operating system development requires rare combinations of cryptography expertise and smart card hardware knowledge.
- Common Criteria EAL4+ certification timelines:Evaluation periods stretching 18-24 months delay product launches and freeze development roadmaps.
- PIV card backward compatibility:Federal agencies in the United States maintain decades-old card readers that constrain chip memory and protocol upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Card in Government Market |
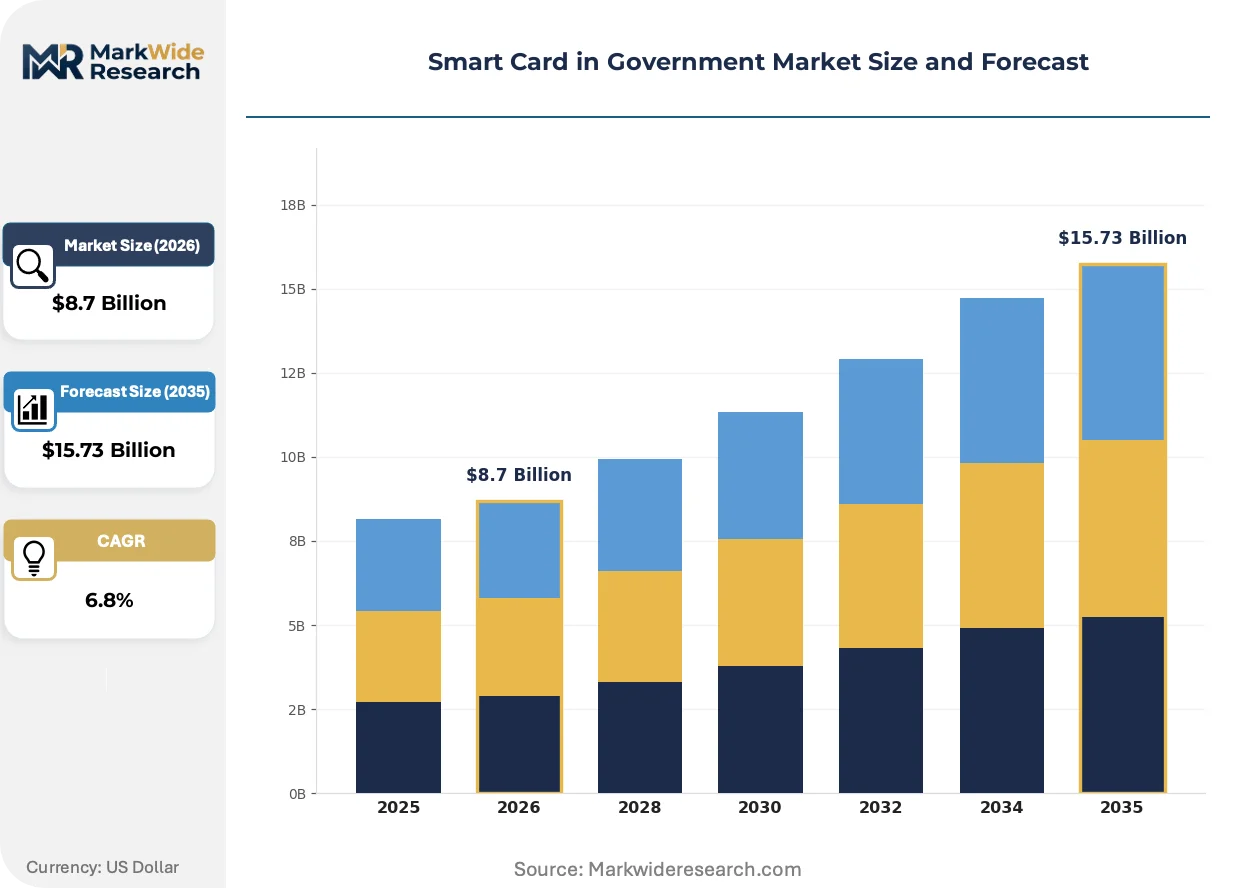
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
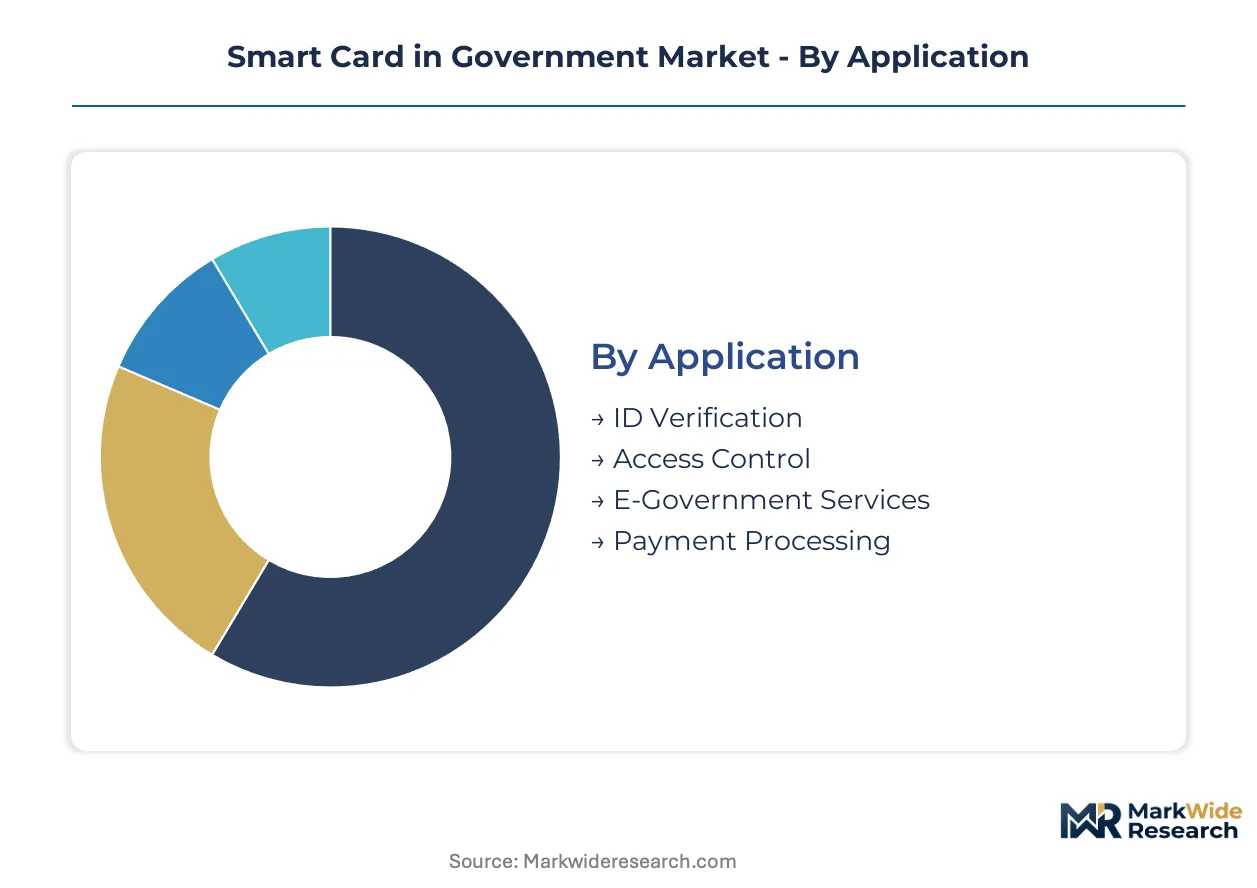
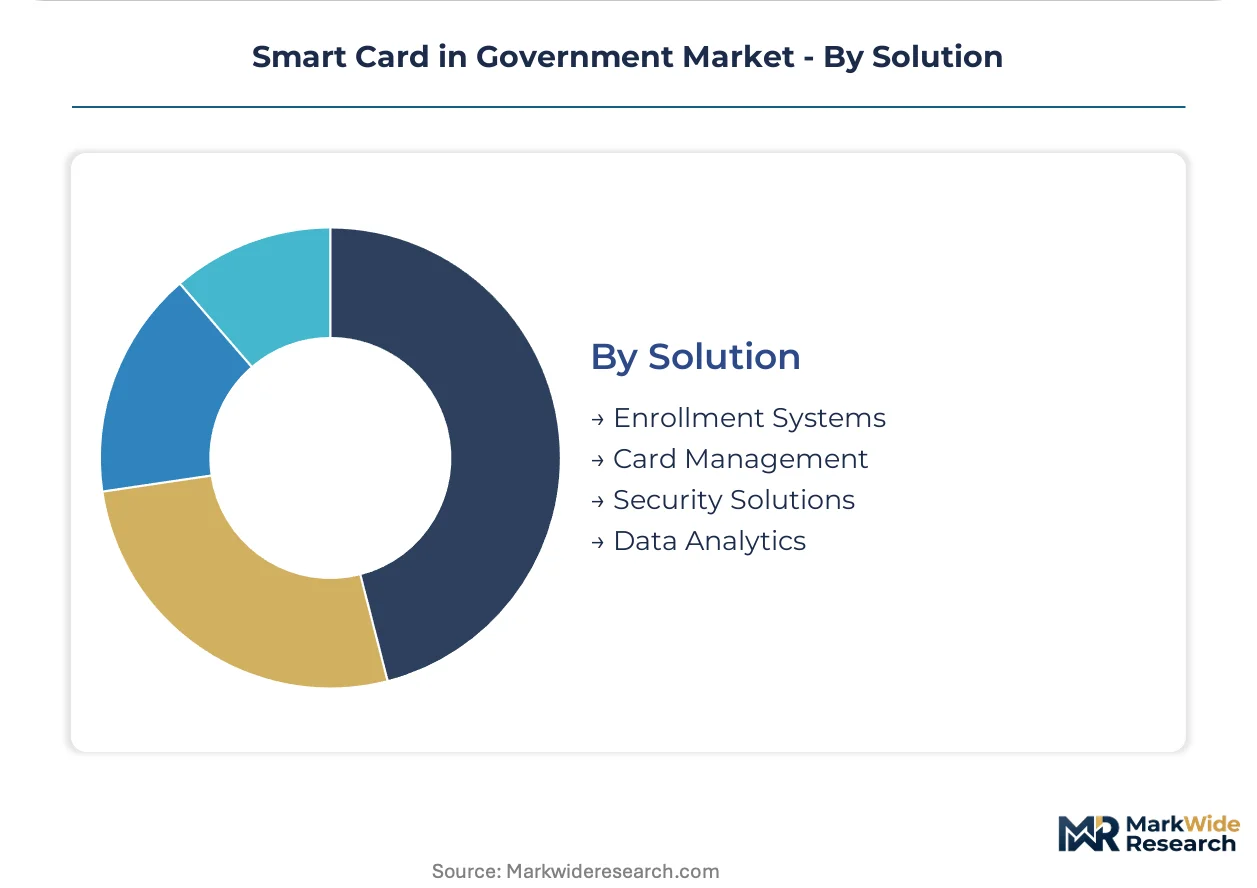
| Segmentation | Application: ID Verification, Access Control, E-Government Services, Payment Processing Technology: Contactless, RFID, Biometric, Magnetic Stripe End User: Government Agencies, Law Enforcement, Public Health, Immigration Solution: Enrollment Systems, Card Management, Security Solutions, Data Analytics |
| Companies Covered | Thales Group, IDEMIA, Giesecke+Devrient, NXP Semiconductors, HID Global, Infineon Technologies, CardLogix Corporation, Watchdata Technologies, CPI Card Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Card in Government Market Evolving Landscape
Chip architecture roadmaps are diverging between high-security biometric credentials for border control and streamlined citizen service cards for welfare distribution, reshaping R&D allocation across the vendor base.
Dual-interface chip platforms are bifurcating procurement specifications between European national ID tenders demanding advanced physical security features and Asian welfare programs prioritizing cost-optimized contactless throughput. Immigration agencies in Germany and France are adopting these platforms for multi-factor verification against central biometric databases, while India's state governments deploy stripped variants for ration card authentication. The technology is bifurcating vendor specialization between premium polycarbonate card body manufacturers and high-volume PVC substrate suppliers.
GDPR's strict data minimization protocols are forcing encryption-certified chip architectures with localized template processing rather than centralized storage. European government IT departments are redesigning credential systems to keep biometric data on-card rather than in networked databases. This regulatory pressure elevates demand for secure microcontrollers with dedicated cryptographic coprocessors and tamper-resistant memory enclosures.
Consolidated enrollment-to-issuance procurement is displacing fragmented vendor management across government credential programs. National identity authorities in India and Brazil are awarding single-source contracts covering biometric capture, personalization, and distribution logistics. This bundling compresses margins for pure-play chip suppliers while favoring system integrators with established government relationships and existing secure facility networks.
Smart Card in Government Market Segmentation
Smart card procurement specifications fragment across government verticals based on security certification tiers, transaction throughput requirements, and biometric integration mandates. Each segmentation dimension carries distinct regulatory weight that shapes vendor qualification and pricing architecture.
Application:
FIPS 201 standards in the United States and GDPR data minimization protocols in Europe enforce divergent technical specifications across credential use cases, compressing interoperability while elevating compliance premiums.
- ID Verification:Dual-interface chip platforms with ISO/IEC 7816 contact and 13.56 MHz contactless protocols dominate national ID tenders. India's Aadhaar-linked ecosystem drives volume procurement for polycarbonate card bodies with embedded secure microcontrollers.
- Access Control:Physical and logical access convergence demands PKI-enabled credentials with tamper-resistant memory enclosures. Federal agencies in Germany and France prioritize Common Criteria EAL4+ certified chips for facility entry and network authentication.
- E-Government Services:Digital signature capabilities and qualified electronic signature compliance anchor procurement for tax filing and benefit enrollment portals.
- Payment Processing:EMVCo certification and domestic payment scheme interoperability constrain chip vendor selection for social welfare distribution networks.
Established volume favors ID Verification; emerging adoption favors E-Government Services.
Technology:
Cost tiers stratify sharply between premium biometric-embedded credentials and commodity contactless platforms, with procurement budgets bifurcating between immigration agencies and state-level welfare departments.
- Contactless:ISO/IEC 14443 Type A/B protocols enable queue-reduction mandates at government service points. Transit integration requirements in Asian megacities accelerate dual-interface deployment over legacy contact-only systems.
- Biometric:On-card fingerprint matching and facial recognition templates command premium positioning where GDPR data localization requirements conflict with law enforcement centralized database demands. Immigration agencies in the United Kingdom and Australia drive specification roadmaps.
- RFID:UHF and HF variants retain niche utility in asset tracking and vehicle registration applications with relaxed security requirements.
- Magnetic Stripe:Legacy infrastructure in budget-constrained municipal governments perpetuates dual-system maintenance costs during prolonged chip migration timelines.
Procurement gravity concentrates on Contactless platforms; Biometric variants claim the steepest expansion trajectory.
End User:
Customer type determines security certification depth, with law enforcement and immigration agencies demanding EAL5+ thresholds while public health departments accept EAL4 baselines.
- Government Agencies:Consolidated enrollment-to-issuance procurement favors system integrators with secure facility networks and established credential personalization infrastructure.
- Law Enforcement:Multi-factor verification against central biometric databases mandates high-memory secure microcontrollers with dedicated cryptographic coprocessors.
- Public Health:Vaccine credentialing and insurance card programs prioritize cost-optimized contactless throughput over physical security features.
- Immigration:ICAO Doc 9303 compliance and electronic passport standards shape chip memory and antenna specifications for border control credentials.
Longstanding demand anchors Government Agencies; Immigration applications are expanding most quickly.
Solution:
Margin structures diverge between hardware-centric card manufacturing and software-heavy data analytics, with bundling trends compressing pure-play supplier positions.
- Enrollment Systems:Biometric capture hardware and deduplication algorithms constitute the highest-margin segment within credential lifecycle management.
- Card Management:Lifecycle issuance, revocation, and key management platforms attract recurring revenue models from national identity authorities.
- Security Solutions:Encryption-certified chip architectures and post-quantum cryptography migration services command premium pricing during replacement cycles.
- Data Analytics:Credential usage pattern analysis and fraud detection algorithms represent emerging software revenue streams for system integrators.
Revenue concentration favors Card Management; Security Solutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Border control agencies and social welfare departments concentrate procurement authority, with national ID programs and transit integration mandates driving specification divergence across major economies.
United States
Federal agencies anchor demand through FIPS 201-compliant PIV card mandates and NIST-guided post-quantum cryptography migration. The Department of Homeland Security shapes procurement specifications for multi-factor verification systems. Washington DC and Northern Virginia host credential personalization facilities serving federal enrollment-to-issuance contracts.
Germany
Law enforcement and immigration agencies drive premium-tier demand for Common Criteria EAL4+ certified chips with polycarbonate card bodies. The BSI (Federal Office for Information Security) enforces strict data localization protocols for biometric template processing. Munich and Berlin concentrate secure microcontroller design centers and government credential manufacturing infrastructure.
India
State-level welfare distribution networks and Aadhaar-linked authentication systems generate volume procurement of cost-optimized contactless platforms. The UIDAI (Unique Identification Authority of India) mandates technical specifications for dual-interface credential ecosystems. Bangalore and Hyderabad host system integrators managing enrollment-to-issuance logistics for ration card and direct benefit transfer programs.
Brazil
National identity authorities consolidate vendor pools around integrated biometric capture and card personalization contracts. ANVISA and federal digital identity frameworks shape compliance requirements for citizen service credentials. São Paulo anchors secure facility networks and credential manufacturing capacity serving Latin American government tenders.
Singapore
Cross-border labor mobility agreements within ASEAN frameworks drive interoperable national ID specifications for migrant worker credentialing. The Infocomm Media Development Authority mandates technical standards for digital identity wallet convergence. The city-state's procurement offices influence regional specification roadmaps through pilot deployments of mobile driver's license platforms.
Smart Card in Government Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with aerospace, defense, or semiconductor heritage, compressing margins for pure-play card manufacturers. The vendor base stratifies between premium-tier suppliers of polycarbonate biometric credentials and high-volume producers of PVC-based welfare cards. Three archetypes dominate: integrated enrollment-to-issuance system integrators, secure element semiconductor specialists, and card body material-cum-personalization providers. Competitive intensity concentrates on encryption certification timelines and strategic partnerships with national identity authorities.
Within the integrated systems tier, Thales Group and IDEMIA exemplify vendors bundling biometric capture hardware with credential lifecycle management platforms. Giesecke+Devrient occupies a position among European heritage manufacturers with established secure facility networks. These three entities anchor competitive positioning through government relationship depth and existing compliance with Common Criteria EAL4+ evaluation regimes.
| Leading Market Players |
|---|
| Thales Group |
| IDEMIA |
| Giesecke+Devrient |
| NXP Semiconductors |
| HID Global |
| Infineon Technologies |
| CardLogix Corporation |
| Watchdata Technologies |
| CPI Card Group |
| Others |
Value Network & Pricing Analysis
Polycarbonate substrate substitution for PVC in European national ID programs simultaneously concentrates supply geography around German and Japanese specialty chemical suppliers and elevates per-unit material costs by roughly 40 percent, compressing margins for card body manufacturers while rewarding vendors with backward integration into polymer compounding.
Pricing Analysis
Cost-plus contracts with polycarbonate resin indexation dominate European national ID tenders, while Asian welfare programs run on fixed-price volume commitments for PVC-based credentials. Price differentiation separates Common Criteria EAL4+ certified biometric credentials from commodity contactless platforms, with certification grade and embedded secure microcontroller memory capacity as primary tiering variables. Pricing pressure stems from consolidated enrollment-to-issuance procurement compressing supplier margins across the credential lifecycle. State-level welfare departments exhibit highest price sensitivity, whereas immigration agencies prioritize security certification depth over unit economics.
Supply Chain Analysis
Inbound logistics costs from Rotterdam and Hamburg port congestion periodically disrupt polycarbonate card body deliveries to personalization facilities in Munich and Berlin. Secure microcontroller fabrication concentrates in Taiwan, South Korea, and Germany, while polycarbonate resin supply draws from German and Japanese petrochemical complexes. Single-source vulnerability in specialty polymer supply exposes procurement budgets to commodity price volatility. Distribution runs through secure facility networks operated by system integrators with established government relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart card in government market reads as a service-attach opportunity where card management platforms and post-issuance lifecycle services are expanding faster than hardware unit shipments, rewarding vendors that bundle recurring-revenue software layers with credential manufacturing.
For Market Incumbents: Compound defensive positioning by deepening backward integration into secure microcontroller design through captive semiconductor partnerships, and by accelerating post-quantum cryptography certification timelines ahead of NIST standardization deadlines. The threat of mobile driver's license convergence demands preemptive investment in ISO/IEC 18013-5 compliant platform engineering to retain government relationship lock-in. For New Entrants and Emerging Players: Anchor in ASEAN cross-border labor mobility credentialing programs where interoperable national ID specifications are still crystallizing, particularly Indonesia-Malaysia-Singapore migrant worker authentication networks. White space concentrates in mobile-first enrollment systems for secondary city municipal governments with constrained chip migration budgets. A direct-to-government SaaS model bypassing hardware manufacturing entirely offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward enrollment-to-issuance system integrators with established secure facility networks and existing Common Criteria EAL4+ evaluation regimes, as these assets command scarcity premiums in consolidated procurement environments. Long-term viability hinges on recurring revenue from card management platforms rather than transactional hardware margins. The signal to watch is NIST post-quantum cryptography standardization triggering replacement demand cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptography Certification | NIST standardization creates preemptive replacement demand before algorithm obsolescence risks materialize. |
| Enrollment-to-Issuance Integration | Single-source contracts covering biometric capture through distribution logistics compress pure-play chip supplier margins. |
| Mobile Driver's License Platform Development | ISO/IEC 18013-5 compliance opens vehicle registration and age verification applications beyond physical cards. |
| ASEAN Interoperability Partnership | Cross-border labor mobility agreements mandate credential standardization across Indonesia, Malaysia, and Singapore. |
| Localized Biometric Template Processing | GDPR data minimization protocols elevate demand for on-card matching rather than centralized database architectures. |
Research Methodology
A spread of perspectives from national identity authority procurement officers, secure facility operations directors, biometric system engineers, and semiconductor product managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against Common Criteria certification databases, EU Digital Identity Wallet framework documentation, and UIDAI technical specification releases. Bottom-up credential volume modeling triangulated against top-down government IT expenditure forecasts across the analysis window.
Segmentation dimensions modeled include application type, chip interface technology, end-user security tier, and solution component across the projection horizon. CAGRs were derived from polynomial trend fitting of historical procurement volumes adjusted for policy mandate acceleration effects. Forecast inputs incorporated Aadhaar-linked welfare network expansion rates and EU member state Digital Identity Wallet replacement cycle assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and polycarbonate supply continuity assumptions; material deviation in petrochemical price volatility or post-quantum cryptography standardization timelines would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Chile ICT Market
Digital Solutions
Sales Acceleration Technology Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
Global Referral Management Market
Digital Solutions
Ediscovery Solution Market
Digital Solutions
Utility App Market
Digital Solutions
Communication Intelligence Market
Digital Solutions
On-Demand Warehousing Platforms Market
Digital Solutions
Business Process Management As a Service Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Mobile Command and Control Solutions Market