
 Reverse Logistics Visibility and Disposition Optimization Platforms Market | 2026-2036
Reverse Logistics Visibility and Disposition Optimization Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Reverse Logistics Visibility and Disposition Optimization Platforms Market Insights
E-commerce sector requirements for returns handling is hardening as a primary demand driver for reverse logistics platforms. Oracle leverages its cloud infrastructure dominance to anchor enterprise-grade visibility solutions across North American retail networks. SAP competes through deep ERP integration that sustains cross-functional data flows between forward and reverse supply chains. Blue Yonder differentiates via AI-native forecasting modules that specialize in predicting return volumes by SKU and geography.
Reverse Logistics Visibility and Disposition Optimization Platforms constitute software systems that integrate IoT sensor feeds, barcode or RFID scan data, and warehouse management protocols to track product condition, location, and routing decisions through returns, refurbishment, recycling, or liquidation channels. Their primary commercial purpose is reducing recovery cycle times and maximizing recovery value per returned unit through automated disposition rules. Cloud-based deployment leads the solution architecture landscape due to scalability requirements for seasonal return spikes, while disposition management captures concentrated margin pools as the most technically complex module requiring real-time integration with secondary market channels. Third-party logistics providers represent the fastest-growing end user category as outsourced reverse supply chain management expands beyond traditional retail self-operation.
The EPA's e-waste tracking regulations in the United States and the EU Green Deal's extended producer responsibility frameworks are mandating auditable chain-of-custody documentation, directly elevating platform requirements for granular visibility. ISO 14001 environmental management standards and REACH substance restrictions further shape product recovery protocols by restricting landfill disposition for certain material categories. Stakeholders must monitor how emerging battery passport regulations and right-to-repair legislation expand data collection obligations beyond current platform capabilities.
Market Dynamics
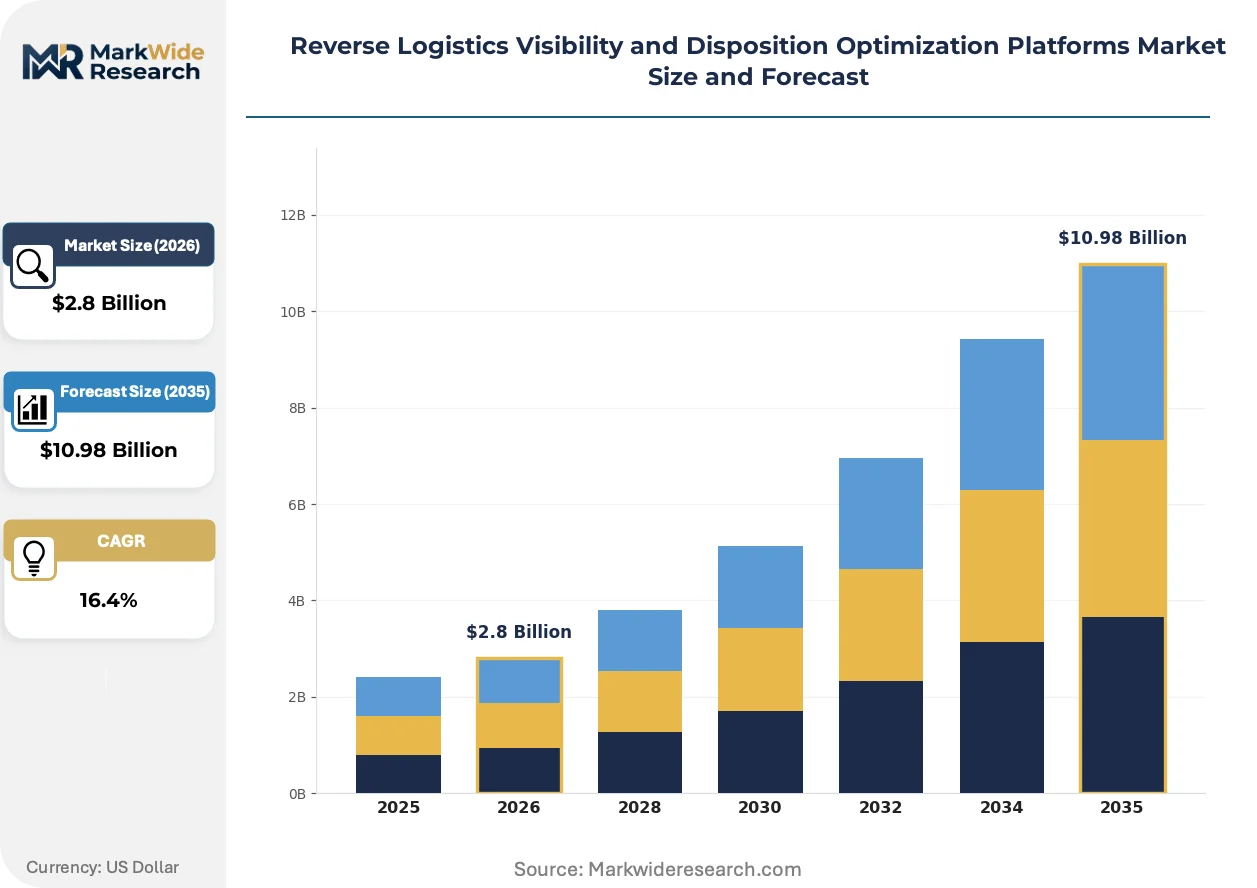
The EU Green Deal's extended producer responsibility mandates are forcing retailers to deploy auditable chain-of-custody systems, compressing decision timelines for disposition automation investments.
Growth Catalysts
- E-commerce return volumes:Online apparel and electronics retailers require automated sorting and routing to handle seasonal spikes without proportional labor expansion.
- REACH substance restrictions:European chemical regulations prohibit landfill disposal for specific material categories, mandating traceable recovery pathways.
- Battery passport frameworks:Emerging EU regulations for electric vehicle and consumer electronics batteries require granular lifecycle documentation.
Market Restraints
- Cloud infrastructure costs:Multi-tenant platform architectures face margin pressure from compute and storage pricing volatility.
- Secondary market liquidity gaps:Disposition optimization depends on real-time price discovery in fragmented resale channels.
- Legacy ERP integration friction:Warehouse management system heterogeneity slows API standardization for bidirectional data flows.
Strategic Opportunities
- Third-party logistics penetration:3PL providers in Germany and the Netherlands seek white-label visibility modules for automotive aftermarket services.
- AI-native forecasting convergence:Machine learning for return prediction is merging with robotic process automation for disposition execution.
- Right-to-repair legislative tailwinds:US state-level repair access laws create demand for component-level tracking and refurbishment routing.
Industry Challenges
- Data science talent scarcity:Platform vendors compete for engineers skilled in supply chain optimization and IoT data pipeline architecture.
- Multi-stakeholder certification timelines:ISO 14001 environmental management audits delay go-live dates for cross-border implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reverse Logistics Visibility and Disposition Optimization Platforms Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Tracking & Monitoring, Analytics & Reporting, Disposition Management, Inventory Control, Returns Management Application: Consumer Electronics, Apparel & Accessories, Pharmaceuticals, Industrial Equipment, Consumer Packaged Goods End User Industry: Third-Party Logistics Providers, Retailers, Wholesalers, Reverse Logistics Service Providers, E-Commerce Companies |
| Companies Covered | Oracle, SAP, Blue Yonder, Manhattan Associates, ReverseLogix, Infor, ServiceNow, Optoro, Locus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reverse Logistics Visibility and Disposition Optimization Platforms Market Trends and Innovations
Artificial intelligence is compressing the latency between return initiation and disposition decision, redefining competitive advantage around prediction accuracy rather than network scale alone.
Computer vision systems for automated product condition assessment are overtaking manual inspection protocols in high-volume fulfillment centers. Fashion and consumer electronics retailers in Germany and the United States are deploying these systems at throughput rates exceeding human sorting capacity. This compression of inspection time is overtaking traditional labor-dependent models and enabling same-day disposition routing.
The EU Green Deal's circular economy action plan mandates auditable recovery rates for packaging and electronics categories. Retailers must now document product flows through refurbishment, recycling, or energy recovery channels with regulator-accessible records. French and German retailers are responding by integrating blockchain-anchored custody logs into their visibility platforms.
Subscription and rental commerce models are fragmenting ownership patterns and multiplying return touchpoints per unit lifecycle. Furniture and apparel verticals are shifting from transactional sales to membership-based access, requiring platforms to track condition degradation across multiple user cycles. This pattern is most visible in urban markets across the Netherlands and Sweden where circular service models have achieved mainstream adoption.
Reverse Logistics Visibility and Disposition Optimization Platforms Market Segmentation
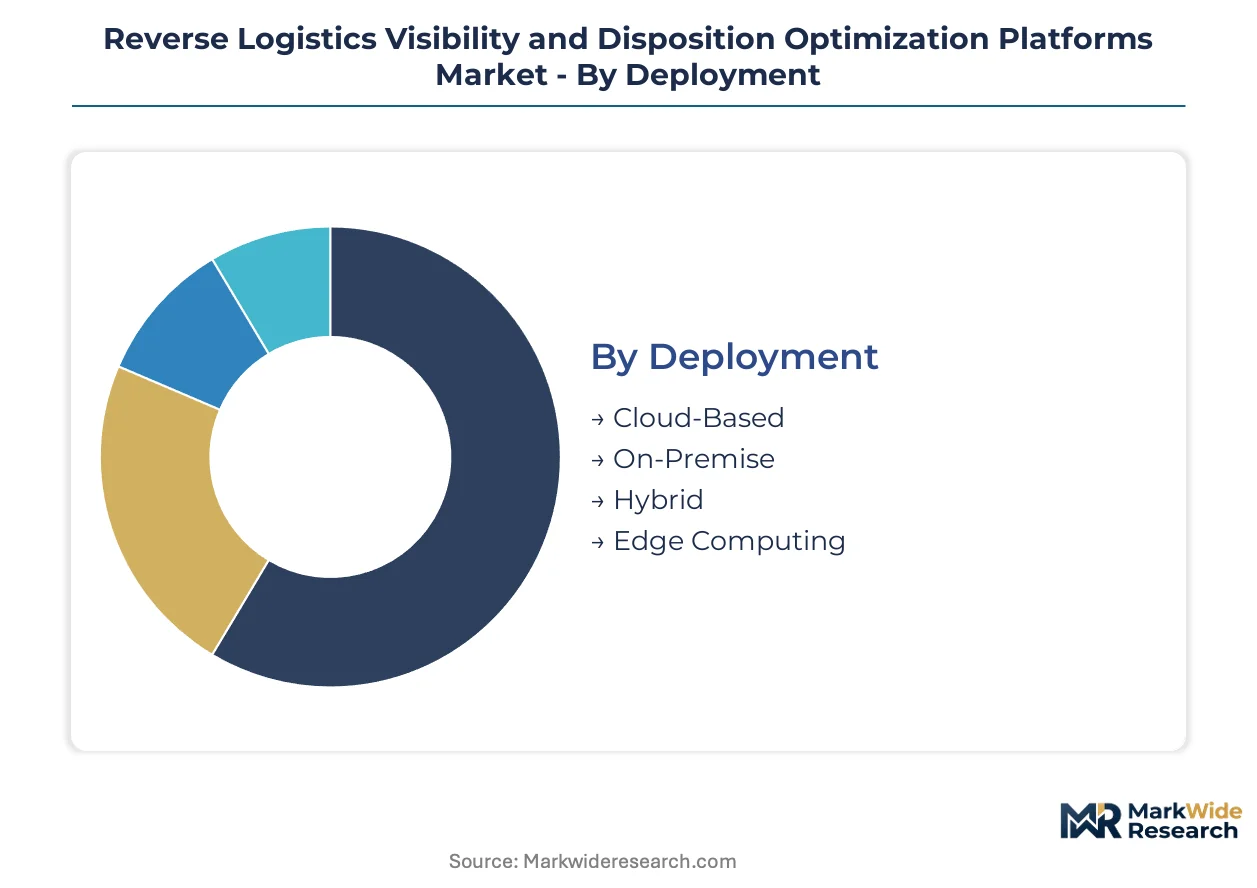
Segmentation in reverse logistics platforms reveals how deployment architecture, solution depth, and industry verticals create distinct capability requirements and margin profiles. Understanding these divisions exposes where technology investments concentrate and which customer configurations drive platform complexity.
Deployment:
Cloud infrastructure scalability defines the architectural choice matrix for seasonal return volume spikes and data sovereignty requirements.
- Cloud-Based:Multi-tenant architectures leverage elastic compute for Black Friday and post-holiday return surges without capital-intensive provisioning. E-commerce companies in Germany and the Netherlands prioritize this model for API-native integration with marketplace seller portals.
- On-Premise:Air-gapped installations serve pharmaceutical distributors facing FDA 21 CFR Part 11 validation requirements and defense contractors with classified material handling protocols. These deployments sacrifice scalability for audit trail control and offline operational continuity.
- Hybrid:Sensitive disposition algorithms run locally while visibility data synchronizes to cloud analytics layers, balancing latency-sensitive routing with centralized reporting dashboards.
- Edge Computing:Warehouse floor processing enables real-time condition assessment via computer vision without backhaul latency, gaining traction in high-throughput electronics refurbishment centers.
Mature deployment sits with Cloud-Based configurations. Newer deployment is concentrated in Edge Computing for latency-critical inspection workflows.
Solution Offering:
Module selection tracks customer sophistication and the technical complexity of their secondary market relationships.
- Disposition Management:Automated routing engines integrate with liquidation exchanges, refurbishment contractors, and recycling certifications to maximize recovery value per unit. This module commands premium pricing due to real-time API complexity and channel liquidity dependencies.
- Tracking & Monitoring:IoT sensor aggregation and RFID scan reconciliation provide chain-of-custody documentation for EU Green Deal compliance and EPA e-waste mandates.
- Analytics & Reporting:Predictive dashboards consolidate return reasons, seasonal patterns, and supplier quality scores to inform procurement negotiations and product design feedback loops.
- Inventory Control:Returned goods availability synchronization with forward sales channels prevents double-counting and enables B-stock listing automation.
- Returns Management:Customer-facing portal integration handles authorization workflows, label generation, and refund triggering across multi-channel retail operations.
Disposition Management captures the steepest expansion trajectory as regulatory documentation requirements harden. Tracking & Monitoring represents the most mature module with standardized IoT protocol adoption.
Application:
Product category characteristics dictate sensor requirements, refurbishment feasibility, and secondary market channel depth.
- Consumer Electronics:Battery passport regulations and precious metal recovery value drive granular component-level tracking. German automotive electronics suppliers require batch-level genealogy for warranty attribution.
- Apparel & Accessories:Condition grading automation via computer vision enables same-day resale channel routing, with Zara and H&M piloting AI-native sorting in Spanish and Swedish distribution centers.
- Pharmaceuticals:Temperature excursion documentation and counterfeit detection impose serialization requirements exceeding standard retail visibility protocols.
- Industrial Equipment:Remanufacturing economics favor modular tracking of replaceable subsystems, with Caterpillar and Siemens deploying field-to-factory lifecycle monitoring.
- Consumer Packaged Goods:Expiration-date-driven routing to food banks or anaerobic digestion facilities requires integration with local charitable networks and waste management infrastructure.
Industrial Equipment applications show the deepest vertical integration into OEM service operations. Apparel & Accessories is climbing the fastest as rental and resale business models multiply return touchpoints.
End User Industry:
Customer organizational structure determines whether platforms serve internal operations or multi-tenant service delivery.
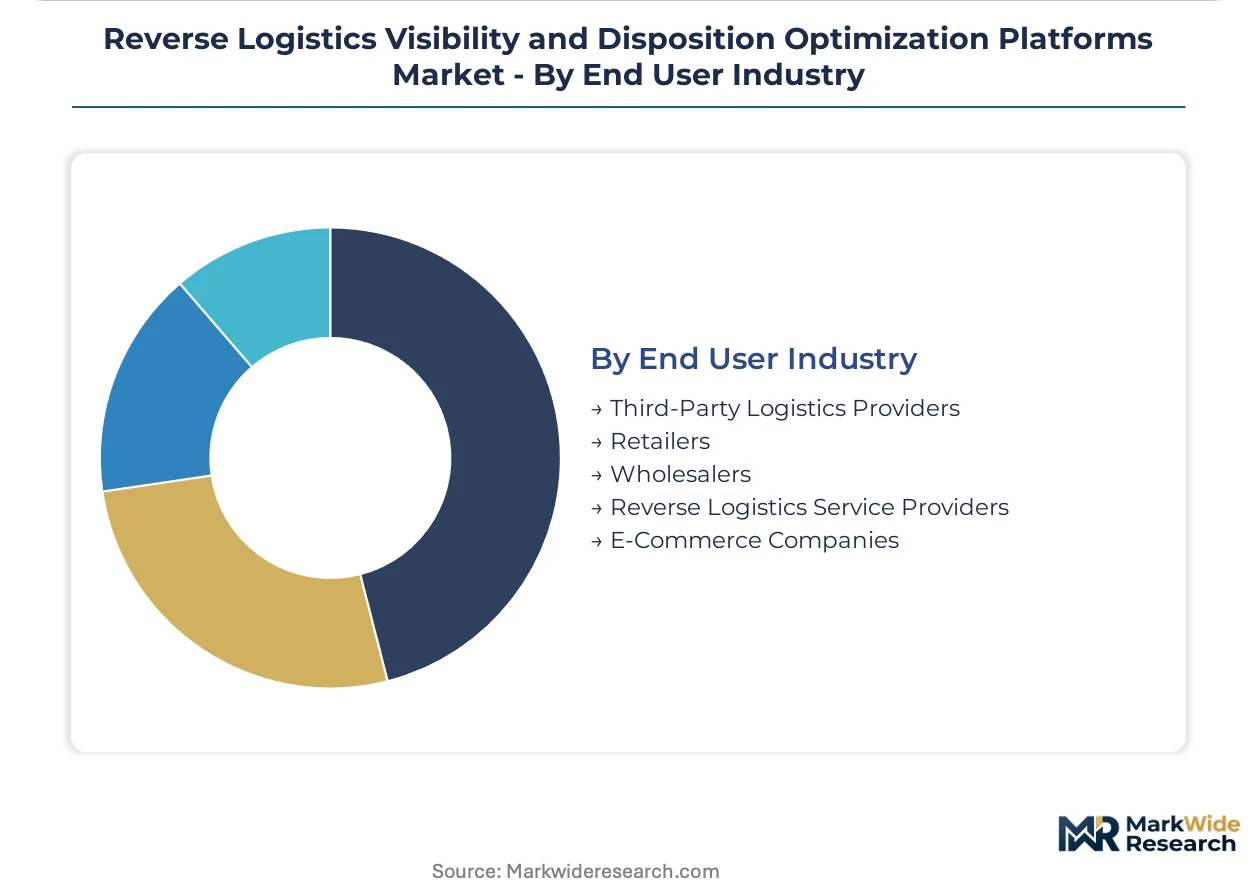
- Third-Party Logistics Providers:White-label platform deployments for automotive aftermarket and medical device clients require tenant isolation and customizable workflow engines. DHL Supply Chain and Kuehne+Nagel are expanding dedicated reverse logistics divisions in Germany and the Netherlands.
- Retailers:Department store networks and specialty chains prioritize unified visibility across owned stores, franchise locations, and online returns consolidation points.
- E-Commerce Companies:Pure-play marketplaces need seller-agnostic returns aggregation and automated disposition routing that spans thousands of merchant accounts with divergent product categories.
- Reverse Logistics Service Providers:Specialized refurbishers and recyclers require inbound shipment visibility and outbound channel price optimization for recovered materials.
- Wholesalers:B2B return authorization workflows differ from consumer patterns, with lot-level traceability for agricultural and construction supply categories.
Retailers maintain the most mature deployment base with decade-long WMS integration histories. Third-Party Logistics Providers are gaining share fastest as outsourcing accelerates beyond captive retail operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Rotterdam and Singapore concentrate platform deployment for cross-border returns processing. Tax incentives for circular economy infrastructure in these zones accelerate vendor facility placement. The analysis spans five countries where regulatory pressure and industrial density combine to drive adoption.
United States
E-commerce return volumes and automotive remanufacturing networks anchor demand in Michigan and Tennessee. The EPA's e-waste tracking regulations mandate auditable chain-of-custody documentation for electronics recovery. Dallas-Fort Worth logistics clusters host third-party providers expanding dedicated reverse supply chain divisions.
Germany
Automotive aftermarket services and industrial equipment remanufacturing require sophisticated disposition optimization across Bavaria and Baden-Württemberg. The EU Green Deal's extended producer responsibility frameworks pressure retailers to improve product recovery traceability. Stuttgart's automotive electronics suppliers deploy batch-level genealogy tracking for warranty attribution.
Netherlands
Port-centric logistics infrastructure and circular service model adoption concentrate demand in Randstad and Eindhoven. REACH substance restrictions prohibit landfill disposal for specific material categories, mandating traceable recovery pathways. Amsterdam fashion retailers pilot AI-native sorting systems for rental commerce return volumes.
China
Consumer electronics manufacturing scale and cross-border e-commerce expansion drive platform requirements in Shenzhen and Shanghai. Dual carbon goals under MEE oversight accelerate closed-loop supply chain investments. Yangtze River Delta refurbishment centers integrate computer vision for automated condition assessment.
United Kingdom
Pharmaceutical serialization requirements and fashion resale platform growth shape demand in London and the Midlands. CSRD disclosure mandates elevate visibility requirements for corporate sustainability reporting. Manchester distribution centers deploy edge computing for real-time returns processing during seasonal peaks.
Reverse Logistics Visibility and Disposition Optimization Platforms Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors holding consolidated positions in cloud infrastructure while specialized logistics technology firms occupy fragmented niches. The vendor landscape organizes around three strategic archetypes: ERP-integrated suite providers, AI-native forecasting specialists, and vertical-focused disposition optimizers. M&A activity concentrates on API-native startups with proven secondary market integrations, while geographic expansion targets German and Dutch automotive aftermarket corridors.
Within the ERP-integrated tier, Oracle and SAP anchor enterprise-grade deployments through cloud infrastructure dominance and deep forward-reverse supply chain data flows. Blue Yonder occupies a position exemplifying the AI-native forecasting archetype, with machine learning modules specializing in SKU-level return prediction. These three represent divergent competitive vectors: suite breadth versus algorithmic specialization versus disposition execution depth.
| Leading Market Players |
|---|
| Oracle |
| SAP |
| Blue Yonder |
| Manhattan Associates |
| ReverseLogix |
| Infor |
| ServiceNow |
| Optoro |
| Locus |
| Others |
Pricing and Supply Chain Analysis
Captive cloud infrastructure ownership among Oracle, SAP, and Microsoft anchors both supply security and pricing power for enterprise-grade reverse logistics platforms, insulating tier-one vendors from compute cost volatility that compresses margins for multi-tenant SaaS providers.
Pricing Analysis
Short lead-time deployment commands premium subscription tiers, while spot inventory arrangements for secondary market liquidity access trade at discounted rates. Three-tier pricing structure across premium, standard, and economy levels tracks API integration depth and real-time disposition channel connectivity. Pricing pressure stems from cloud infrastructure cost volatility and secondary market price discovery gaps in fragmented resale channels. Third-party logistics providers exhibit highest price sensitivity due to thin margin profiles, whereas automotive OEMs prioritize traceability over unit economics.
Supply Chain Analysis
Domestic-content mandates under the EU Green Deal's extended producer responsibility frameworks are reshaping sourcing patterns for IoT sensor hardware and edge computing equipment toward European-certified suppliers. Platform development concentrates in the United States, Germany, and the Netherlands, with cloud infrastructure provisioning drawing from hyperscaler data center networks in Ireland and Frankfurt. Supply chain risk centers on single-source vulnerability for specialized computer vision hardware used in automated condition assessment. Distribution runs through direct enterprise sales teams and systems integrator partnerships for complex ERP-integrated deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering talent scarcity props pricing power for vendors with proven AI-native forecasting capabilities, as supply-constrained implementation timelines stretch customer commitments.
For Market Incumbents: Extend API-native disposition channel integrations to defend against specialized logistics technology entrants capturing automotive aftermarket share. Invest in ISO 14001 certification automation to compress multi-stakeholder audit timelines that delay cross-border go-live dates. Prioritize backward integration into edge computing hardware to reduce dependency on third-party sensor suppliers facing REACH substance restriction compliance costs. For New Entrants and Emerging Players: Capture white-label visibility module demand from German and Dutch third-party logistics providers expanding dedicated reverse logistics divisions. Target pharmaceutical distributors in the United States facing FDA 21 CFR Part 11 validation requirements with air-gapped on-premise deployment expertise. Lead with computer vision condition assessment specialization to differentiate from suite providers with broader but shallower inspection automation. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by ERP-integrated suite providers seeking AI-native forecasting capabilities. Long-term viability favors vendors with proven secondary market API integrations and tenant-isolated multi-tenant architectures. Monitor battery passport regulatory implementation velocity as inflection indicator for platform data collection obligation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Disposition Channel Integration | Real-time connectivity with liquidation exchanges and refurbishment contractors maximizes recovery value per returned unit under EU Green Deal mandates. |
| Edge Computing Hardware Provisioning | Warehouse-floor processing enables computer vision condition assessment without cloud backhaul latency during seasonal return surges. |
| ISO 14001 Certification Automation | Streamlined environmental management audits accelerate cross-border implementation timelines compressed by regulatory deadlines. |
| White-Label Platform Deployment | Tenant-isolated architectures capture third-party logistics provider demand for automotive aftermarket and medical device client services. |
| AI-Native Return Forecasting Convergence | Machine learning modules merged with robotic process automation compress latency between return initiation and disposition execution. |
Research Methodology
SEC filings, EU regulatory submission databases, and hyperscaler infrastructure capex disclosures formed the secondary backbone, cross-referenced with primary interviews involving supply chain directors at e-commerce companies, platform engineers at logistics technology vendors, procurement leads at third-party logistics providers, and regulatory affairs specialists at automotive OEMs. Bottom-up and top-down triangulation validated segment sizing and growth trajectory assumptions.
Bottom-up modeling aggregated deployment architecture, solution module, and end-user industry segments across the analysis window, while top-down validation tracked aggregate software spending patterns in reverse supply chain management. CAGRs derived from regression analysis against e-commerce return volume indices, regulatory implementation timelines, and cloud infrastructure adoption curves. Forecast inputs incorporated EU Green Deal extended producer responsibility phase-in schedules and battery passport framework development milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cloud infrastructure pricing volatility, secondary market liquidity fragmentation, and right-to-repair legislative expansion beyond current platform data collection architectures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Predictive Maintenance Software Market
Digital Solutions
Global Asset Tracking Software Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Kubernetes Solutions Market
Digital Solutions
Enterprise Imaging Solutions Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Decision Support System Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Global Inventory Optimization Software Market
Digital Solutions
Queue Management System (QMS) Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Email Marketing Market
Digital Solutions
Smart Process Application (SPA) Market