
 Global Asphalt Additives Market | 2026-2036
Global Asphalt Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Asphalt Additives Market Foresight
Warm-mix asphalt formulation is tilting the technology stack toward lower-temperature production methods that reduce energy use and emissions during paving. BASF SE leverages its polymer modifier portfolio to serve high-performance roadway specifications across multiple continents. Evonik Industries AG anchors its position through specialized anti-stripping agents that improve binder-aggregate adhesion in demanding climates. Kraton Corporation dominates the polymer modification segment with styrene-butadiene-styrene chemistry optimized for rutting resistance.
Asphalt additives comprise chemical or polymeric substances blended into bituminous binders to enhance rheological properties, durability, or application characteristics, typically dosed at 0.5% to 5.0% by weight of the binder depending on performance targets. Their primary industrial purpose is to extend pavement service life, reduce maintenance frequency, and enable construction under broader temperature or moisture conditions. Polymer modifiers command the largest value share due to their critical role in stress-absorbing membrane interlayers and heavy-traffic overlays. Rejuvenators represent the fastest-expanding product category as recycling rates for reclaimed asphalt pavement climb in North America and Europe. Anti-stripping agents concentrate margin pools in regions with high rainfall or freeze-thaw exposure where moisture damage poses structural risks.
The EPA enforces volatile organic compound limits on asphalt production facilities, pushing additive suppliers toward low-emission formulation chemistries. REACH registration requirements in Europe govern the import and use of specialty chemicals in pavement applications, creating compliance barriers for non-EU suppliers. China's MEE implements emission standards for asphalt mixing plants that favor additives enabling reduced production temperatures. Stakeholders must monitor regulatory divergence between jurisdictions and align product registration strategies with the most restrictive standards in their target markets.
Market Dynamics
Warm-mix asphalt technology is compressing the traditional hot-mix production paradigm as infrastructure agencies mandate lower-temperature paving to meet tightening emissions thresholds. This shift is redistributing value toward chemical additives that enable viscosity reduction at reduced thermal inputs.
Growth Catalysts
- EPA Emissions Guidelines:The United States Environmental Protection Agency enforces volatile organic compound limits on asphalt production facilities, pushing additive adoption for low-temperature formulation compliance.
- Polymer Modifiers:Styrene-butadiene-styrene chemistry dominates stress-absorbing membrane interlayers and heavy-traffic overlays as agencies specify longer pavement service intervals.
- China:National highway expansion programs continue driving additive consumption through centralized procurement of high-performance binder systems.
Market Restraints
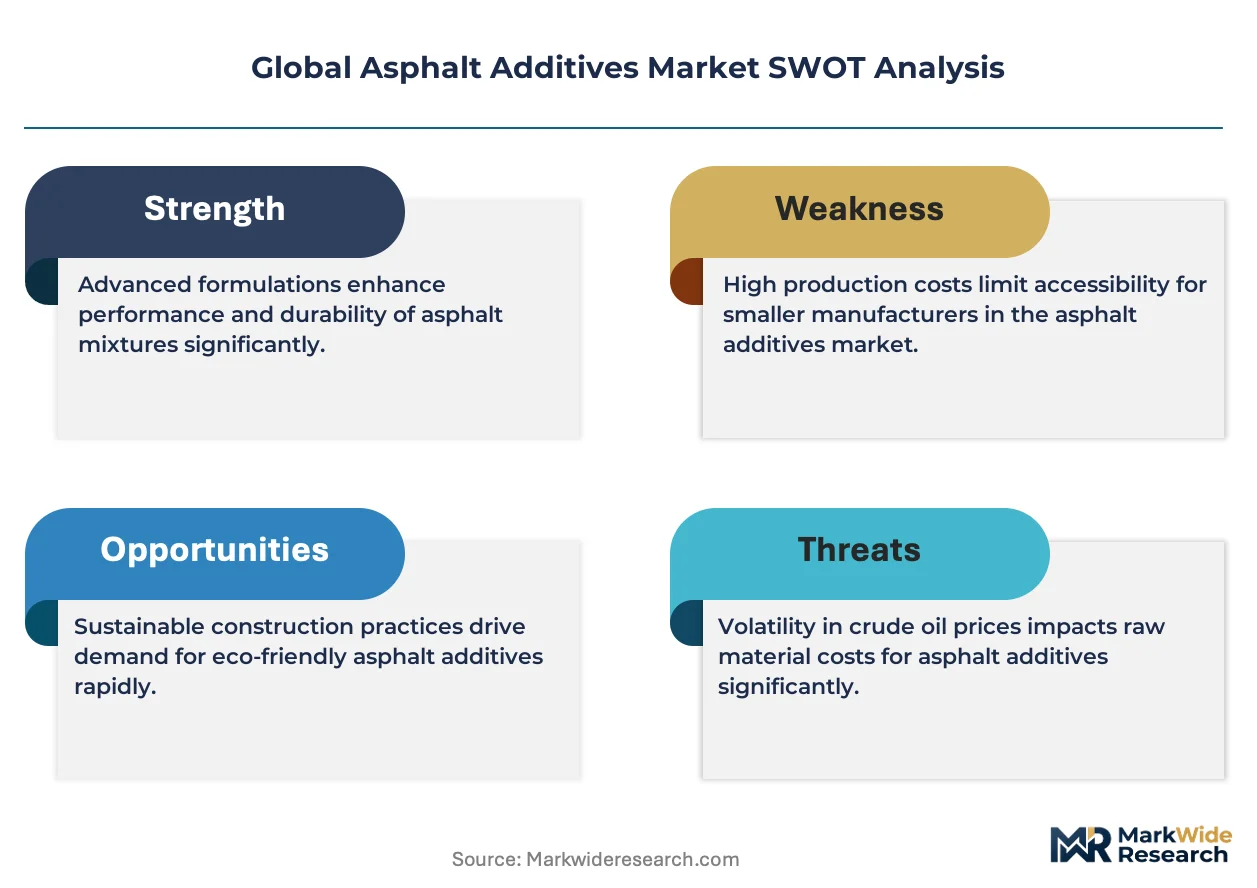
- Crude-Derived Feedstock Volatility:Bitumen pricing fluctuates with crude oil markets, compressing margin predictability for additive suppliers locked into fixed-price road contracts.
- REACH Registration Burden:The European Chemicals Agency imposes compliance costs and timeline barriers on non-EU specialty chemical suppliers seeking pavement market entry.
- Portland Cement Substitution:Concrete paving competes for federal infrastructure dollars in certain climate zones, capping asphalt additive addressable market expansion.
Strategic Opportunities
- Rejuvenator Chemistry:Reclaimed asphalt pavement recycling rates climb in North America and Europe, opening formulation white space for binder restoration additives.
- India:National highway development schemes under the Ministry of Road Transport and Highways present underpenetrated demand for polymer-modified binders in tropical monsoon conditions.
- Warm-Mix Additive Distribution:Direct technical service partnerships with state-level asphalt mixing plant operators bypass traditional distributor markups in fragmented procurement environments.
Industry Challenges
- Rheology Specialist Scarcity:Formulation chemists with bitumen-polymer compatibility expertise remain concentrated at incumbent suppliers, constraining new entrant technical capabilities.
- State-Level Qualification Protocols:Each United States Department of Transportation maintains distinct approved-products lists, fragmenting registration timelines and duplicating testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Asphalt Additives Market |
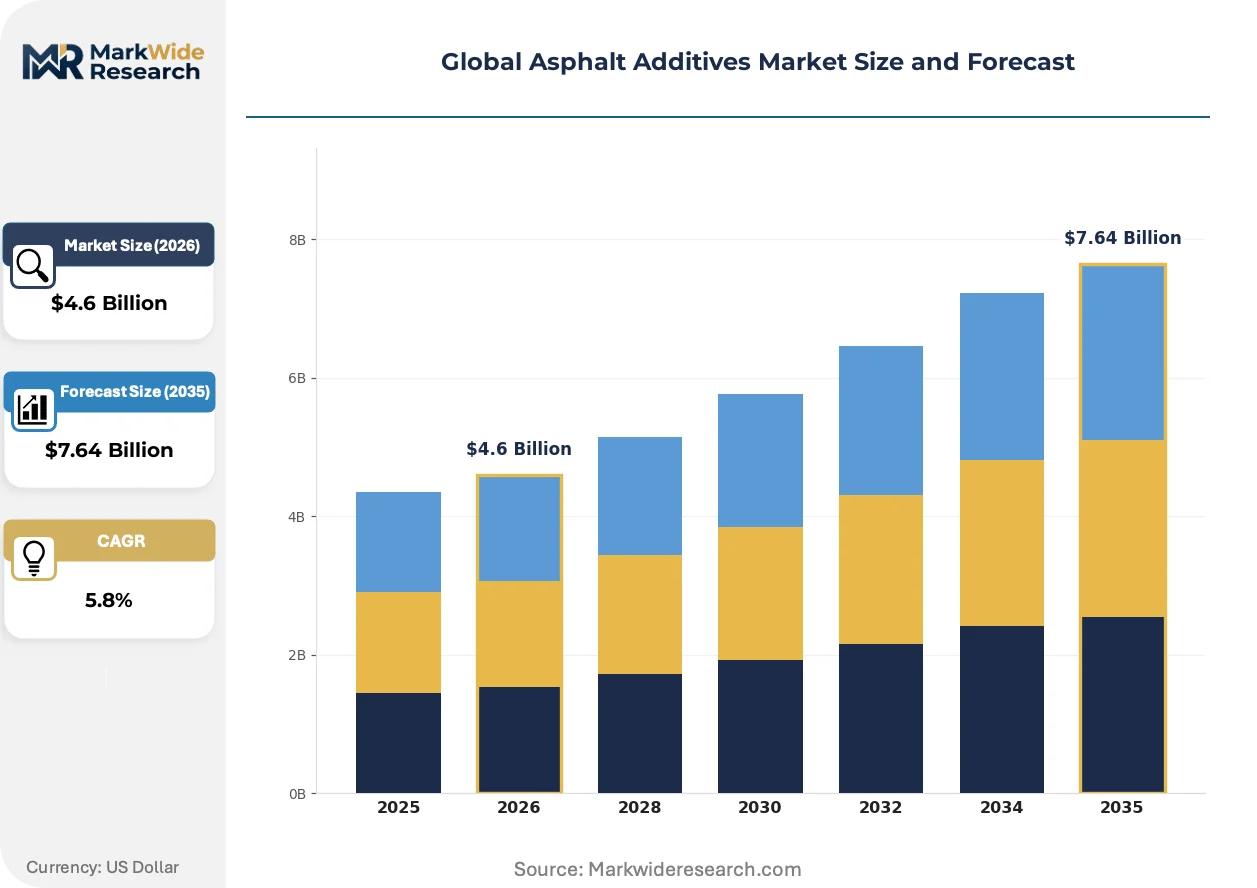
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $7.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Modifier, Anti-Stripping Agent, Asphalt Emulsifier, Rejuvenator Application: Roadway Pavements, Airport Runways, Bridge Decks, Parking Lots End User: Construction Contractors, Infrastructure Developers, Government Agencies, Municipal Corporations Packaging Type: Drums, Bulk Bags, Liquid Containers, Powder Bags |
| Companies Covered | BASF SE, Evonik Industries AG, Kraton Corporation, Dow Inc., Honeywell International Inc., Arkema, Nouryon, Dynasol Group, Ingevity Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Asphalt Additives Market Shifts & Advancements
Additive suppliers are converging on bio-based chemistries and digital formulation tools that compress development cycles. These shifts are rewriting competitive differentiation around sustainability credentials and technical service depth rather than commodity volume scale.
Digital twin technology for asphalt mix design is virtualizing laboratory testing workflows, enabling real-time binder-aggregate compatibility prediction. State transportation agencies in Germany and the Netherlands pilot these platforms to compress qualification timelines. The technology is virtualizing the traditional empirical mix design process that historically required weeks of physical specimen preparation.
China's Ministry of Ecology and Environment implements emission standards for asphalt mixing plants that favor additives enabling reduced production temperatures. Industrial consequence includes accelerated substitution of traditional hot-mix modifiers with chemical warm-mix agents. The regulatory pressure concentrates margin pools among suppliers with MEE-registered low-emission formulations.
Specification-driven procurement now dominates large infrastructure tenders, with agencies bundling performance warranties into additive selection criteria. Traditional spot purchasing through distributor networks loses share to direct manufacturer partnerships in the United States and Western Europe. This behavioral shift is most visible in heavy-traffic corridor projects where pavement lifecycle cost calculations override initial material price comparisons.
Global Asphalt Additives Market Segmentation
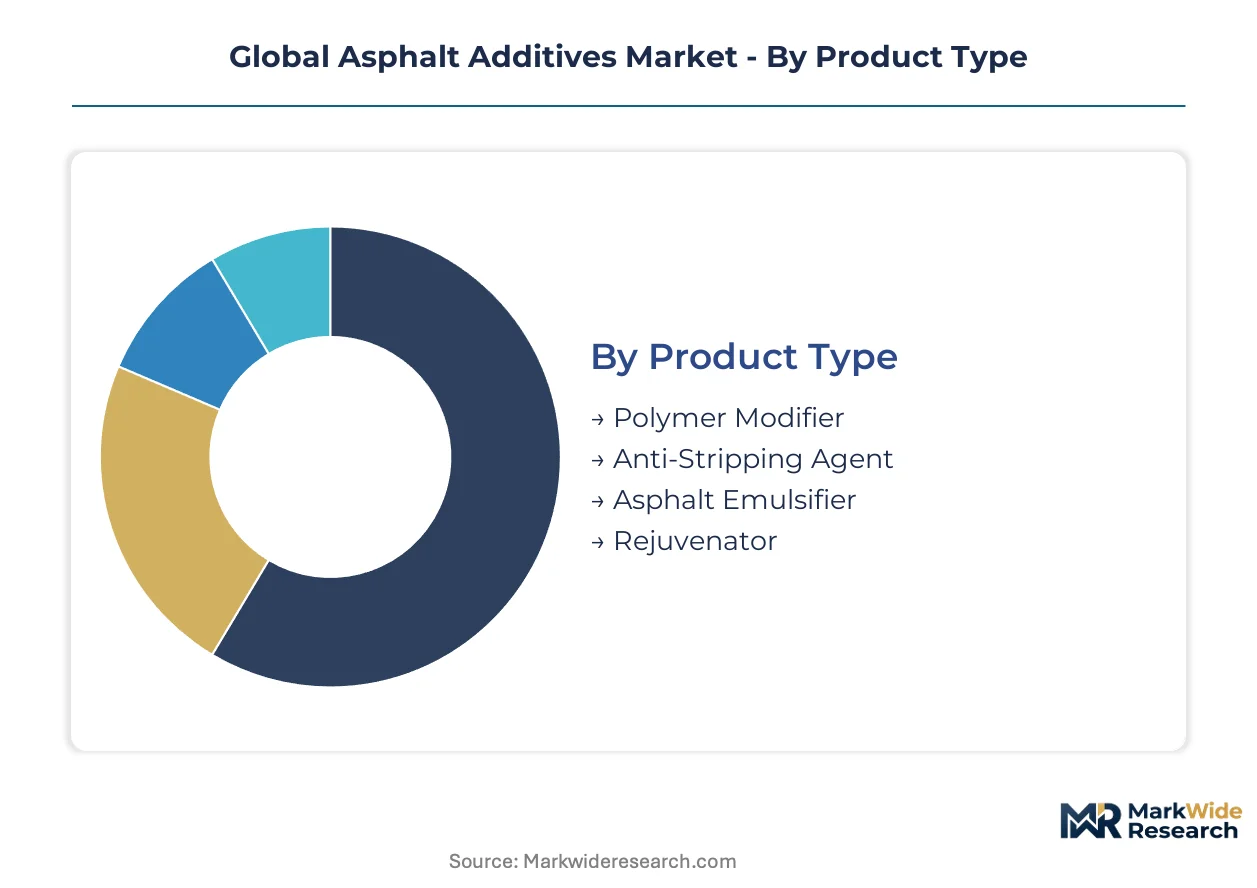
Asphalt additives serve distinct performance requirements across binder chemistry, infrastructure application, procurement channel, and logistics format. Each segmentation dimension captures different margin structures and technical qualification barriers that reshape competitive positioning.
Product Type:
Cost tier separates commodity chemical additives from high-value polymer systems with proprietary formulation IP.
- Polymer Modifier:Styrene-butadiene-styrene and ethylene-vinyl-acetate copolymers enhance elastic recovery and rutting resistance in heavy-traffic overlays. Demand concentrates in China and the United States where centralized highway procurement mandates extended pavement warranties.
- Rejuvenator:Bio-based and petroleum-derived recycling agents restore aged binder properties in reclaimed asphalt pavement streams. European Union circular economy directives and North American state-level recycling mandates are accelerating specification.
- Anti-Stripping Agent:Amine-based and organosilane chemistry improves moisture resistance in tropical monsoon and freeze-thaw climates.
- Asphalt Emulsifier:Cationic and anionic surfactants enable cold-mix and chip-seal applications without thermal processing.
Polymer modifiers hold installed capacity. Rejuvenators are rotating up the share rankings.
Application:
Application type maps directly to performance specification intensity and lifecycle cost accountability.
- Roadway Pavements:Federal and state highway agencies specify polymer-modified binders for interstate corridors and urban arterials bearing commercial freight loads. China's Ministry of Transport mandates high-performance systems for national expressway expansion.
- Airport Runways:Jet fuel resistance and high-temperature stability requirements drive premium additive loading in pavement fueling zones and touchdown areas. Federal Aviation Administration specification P-401 creates qualification barriers for non-approved formulations.
- Bridge Decks:Waterproofing membrane interlayers demand specialized anti-stripping and polymer systems.
- Parking Lots:Commercial developers balance initial cost against maintenance liability in lower-traffic installations.
Roadway pavements anchor volume throughput. Airport runways capture the steepest expansion trajectory among specification-driven segments.
End User:
Customer type determines procurement sophistication, from spot purchasing to lifecycle-cost contracting.
- Government Agencies:Federal and state departments of transportation bundle performance warranties into multi-year additive supply agreements. EPA emissions compliance and pavement lifecycle calculators override initial price evaluation.
- Infrastructure Developers:Public-private partnership concessionaires specify additives based on availability payment or shadow toll revenue models that internalize maintenance cost risk.
- Construction Contractors:Project-based procurement concentrates in regional mixing plant networks with state-approved product lists.
- Municipal Corporations:City-level road maintenance departments operate fragmented purchasing with limited technical specification resources.
Government agencies concentrate multi-year contract value. Infrastructure developers are gaining procurement sophistication fastest.
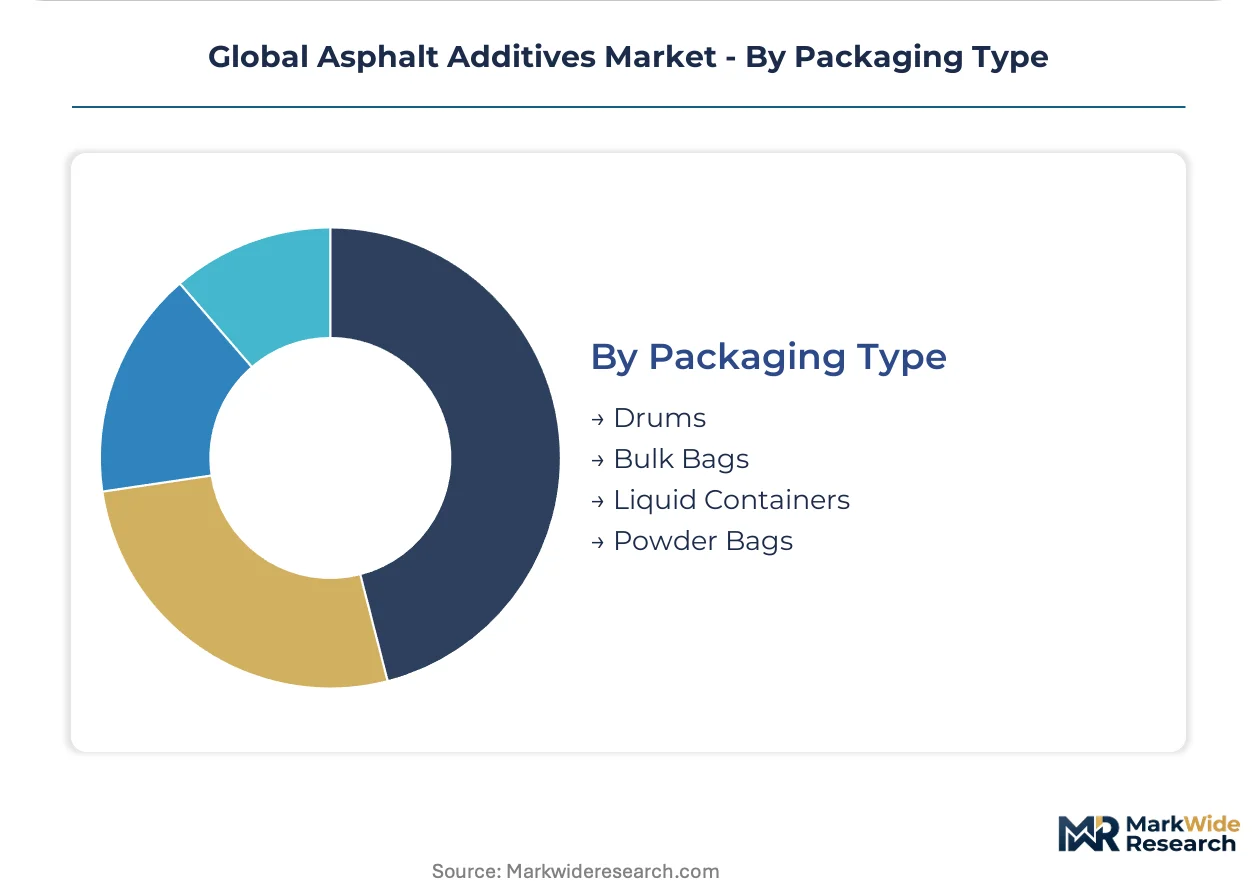
Packaging Type:
Logistics format aligns with project scale, storage constraints, and regional supply chain infrastructure.
- Bulk Bags:One-ton flexible intermediate bulk containers serve continuous production at centralized asphalt mixing plants with pneumatic handling systems. Scale economies favor this format for polymer modifiers in high-volume markets.
- Liquid Containers:Tote and drum configurations enable precise metering of emulsifiers and rejuvenators at batch plants lacking bulk storage.
- Drums:Standard 55-gallon steel containers persist in remote project sites and international export logistics.
- Powder Bags:Multi-wall paper and woven polypropylene sacks package anti-stripping agents and dry emulsifier concentrates.
Bulk bags dominate tonnage throughput. Liquid containers are expanding fastest in warm-mix additive distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical exporters supply polymer modifiers to highway authorities across Central and Eastern Europe. This trade corridor channels formulation expertise toward infrastructure agencies seeking extended pavement warranties.
United States
State transportation departments specify polymer-modified binders for interstate freight corridors. The EPA enforces volatile organic compound limits on asphalt production facilities. Texas and California concentrate warm-mix additive adoption where emission compliance pressures are most acute.
China
National highway expansion programs drive consumption of high-performance binder systems. The Ministry of Ecology and Environment implements emission standards favoring reduced-temperature production methods. The Yangtze River Delta hosts the densest concentration of MEE-registered formulation suppliers.
Germany
Federal motorway maintenance contracts mandate stress-absorbing membrane interlayers for heavy-traffic zones. REACH registration requirements govern specialty chemical imports for pavement applications. The Ruhr industrial corridor anchors polymer modifier production serving Benelux and Scandinavian export markets.
India
National highway development schemes under the Ministry of Road Transport and Highways expand specification of tropical-grade binders. Central pollution control directives increasingly reference emission reduction in mixing plant permits. Gujarat and Maharashtra concentrate domestic additive blending capacity near petrochemical feedstock sources.
Japan
Metropolitan expressway authorities specify premium anti-stripping agents for coastal humidity exposure. METI guidelines on construction material lifecycle assessment influence procurement scoring. The Kansai region around Osaka hosts specialized formulation R&D clusters serving domestic airport runway specifications.
Global Asphalt Additives Market Competitive Landscape
On the supply side, the industry is tiered between multinational chemical conglomerates and regional specialty blenders. The top tier commands polymer modification technology through captive resin production. Strategic archetypes include integrated petrochemical players, independent modifiers, and rejuvenator specialists. Competitive moves concentrate on direct technical service partnerships with state asphalt mixing plants and backward integration into bio-based feedstock cultivation.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes defined by polymer portfolio breadth versus specialized adhesion chemistry. Kraton Corporation occupies a distinct position in styrenic block copolymer supply. These three anchors demonstrate how geographic origin and corporate structure map to divergent specialization vectors in formulation supply.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Kraton Corporation |
| Dow Inc. |
| Honeywell International Inc. |
| Arkema |
| Nouryon |
| Dynasol Group |
| Ingevity Corporation |
| Others |
Supply & Pricing Matrix
Crude-derived feedstock volatility compresses margin predictability for additive suppliers locked into fixed-price road contracts, forcing a three-tier pricing structure across premium polymer modifiers, standard chemical additives, and economy-grade emulsifiers while simultaneously driving geographic consolidation of production capacity near petrochemical hubs.
Pricing Analysis
The technology-generation pricing gap separates legacy hot-mix modifiers from warm-mix chemical additives and next-generation bio-based rejuvenators. The market operates on a contract-based long-term offtake model where government agencies bundle multi-year supply agreements with performance warranties. Price differentiation hinges on certification level—FAA P-401 approval for airport specifications versus state DOT qualification—and volume scale through centralized procurement. Pricing pressure stems from bitumen cost pass-through clauses in highway contracts. Municipal corporations exhibit highest price sensitivity due to fragmented purchasing authority, while infrastructure developers internalize lifecycle cost calculations.
Supply Chain Analysis
Extended payment terms from state transportation departments strain working capital for regional blenders, accelerating supplier-financing facilities among multinational chemical conglomerates. Production concentrates in the United States, China, and Germany where integrated petrochemical complexes feed polymer modifier output. Formulation draws from styrene-butadiene-styrene resins, ethylene-vinyl-acetate copolymers, and amine-based adhesion promoters. Single-source vulnerability threatens regional blenders dependent on imported specialty chemicals under REACH registration timelines. Distribution runs through direct technical service partnerships with asphalt mixing plant operators, bypassing traditional distributor markups in fragmented procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global asphalt additives market represents an early-cycle expansion story as warm-mix technology penetration accelerates under tightening EPA and MEE emission mandates, creating formulation white space for suppliers with low-temperature chemistry portfolios.
For Market Incumbents: Insulate polymer modifier margins through backward integration into captive SBS resin production and MEE-registered formulation capacity in the Yangtze River Delta. Cement channel control via direct technical service partnerships with state-level asphalt mixing plant operators to lock out distributor-dependent competitors facing qualification protocol fragmentation across United States Department of Transportation jurisdictions.
For New Entrants and Emerging Players: Pursue rejuvenator chemistry specialization targeting North American and European reclaimed asphalt pavement recycling mandates, the fastest-expanding product category with lower incumbent IP concentration. Enter through warm-mix additive distribution partnerships with fragmented municipal procurement networks in India where national highway development schemes under the Ministry of Road Transport and Highways present underpenetrated demand.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors acquisition targets with bio-based feedstock cultivation capabilities and MEE-registered low-emission formulations. Long-term viability over the coming decade rests on positioning ahead of circular economy directive acceleration in Europe and state-level recycling mandate expansion in North America. Monitor FAA P-401 qualification timelines as inflection indicators for premium airport runway specification capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SBS Resin Production | Captive polymer supply secures margin control against crude-derived feedstock volatility. |
| MEE Registration for Low-Emission Formulations | Regulatory compliance unlocks Yangtze River Delta procurement concentration under China's emission standards. |
| Direct Technical Service Partnerships | Bypassing distributor markups captures value in fragmented state DOT procurement environments. |
| Rejuvenator Chemistry R&D Investment | Bio-based binder restoration aligns with EU circular economy directives and North American recycling mandates. |
| Warm-Mix Additive Distribution Expansion | Reduced-temperature formulation chemistry addresses EPA volatile organic compound enforcement pressure. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with asphalt mixing plant managers, state DOT materials engineers, polymer procurement leads at infrastructure developers, and technical R&D directors at chemical suppliers; and secondary validation through customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, EPA enforcement disclosures, and MEE emission standard documentation. Bottom-up volume modeling across product type, application, end user, and packaging format segments triangulated against top-down macroeconomic indicators.
Forecast inputs considered warm-mix technology adoption curves, reclaimed asphalt pavement recycling rate trajectories, and regulatory enforcement intensity across jurisdictions. Segmentation dimensions modeled include binder chemistry tier, infrastructure application specification intensity, procurement channel sophistication, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand projections incorporating polymer modifier specification mandates and rejuvenator penetration assumptions. Industry-specific inputs encompassed state DOT approved-products list qualification timelines and FAA P-401 certification barriers.
Sensitivities concentrate around crude oil price volatility affecting bitumen input costs, REACH registration timeline delays for non-EU specialty chemical suppliers, and divergence between EPA and MEE emission enforcement intensity. Forecasts reflect documented assumptions regarding warm-mix technology substitution rates and circular economy directive implementation pacing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Tocopheryl Acetate Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Global Isosorbide Market
Additives
Antimicrobial Additives Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
South Africa Acidulants Market
Additives
Feed Additive Nosiheptide Premix Market
Additives
Global Performance Additives Market
Additives
Chelating Agents Market
Additives
Global Pearlizing Agent Market
Additives
Caprylyl Glycol Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Crosslinking Agents Market
Additives
Europe Feed Additives Market
Additives
North America Paints and Coatings Additives Market
Additives
Polyols and Sorbitols Products Market