
 Premium Motorcycle Helmets Market | 2026-2036
Premium Motorcycle Helmets Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Motorcycle Helmets Market Intelligence
ECE 22.06 is repositioning the engineering baseline for premium helmet manufacturers worldwide. Shoei Co. Ltd leverages in-house wind tunnel testing to sustain aerodynamic leadership across its racing and touring lines. AGV Helmets anchors its brand equity through deep ties to MotoGP heritage and Italian manufacturing. Arai Helmet Limited differentiates through its proprietary round-oval shell philosophy and hand-built construction methods.
Premium motorcycle helmets represent head protection systems engineered from composite laminates such as carbon fiber, fiberglass, or multi-density EPS liners, designed to absorb impact energy while minimizing rotational forces during crashes. These systems serve motorcyclists requiring certified protection above minimum legal thresholds, particularly in high-speed road and closed-circuit applications. Full-face configurations command the dominant share of value given their structural complexity and consumer preference for maximum coverage. Carbon fiber materials represent the fastest-expanding segment as weight reduction becomes a decisive purchase criterion among performance-oriented riders. Bluetooth-enabled features are maturing into standard expectations rather than premium differentiators, compressing margin pools for basic connectivity while opening space for integrated heads-up display systems.
Federal Motor Vehicle Safety Standard 218 governs baseline impact performance in the United States, while ECE 22.06 in Europe introduces stricter oblique impact and visor penetration protocols that manufacturers must satisfy for market access. Japan's JIS T 8133 and Snell Memorial Foundation certifications create additional compliance layers that premium brands navigate to signal quality tiering. Stakeholders must monitor how impending updates to DOT testing protocols and potential harmonization pressures between ECE and FMVSS frameworks reshape certification investment requirements.
Market Dynamics
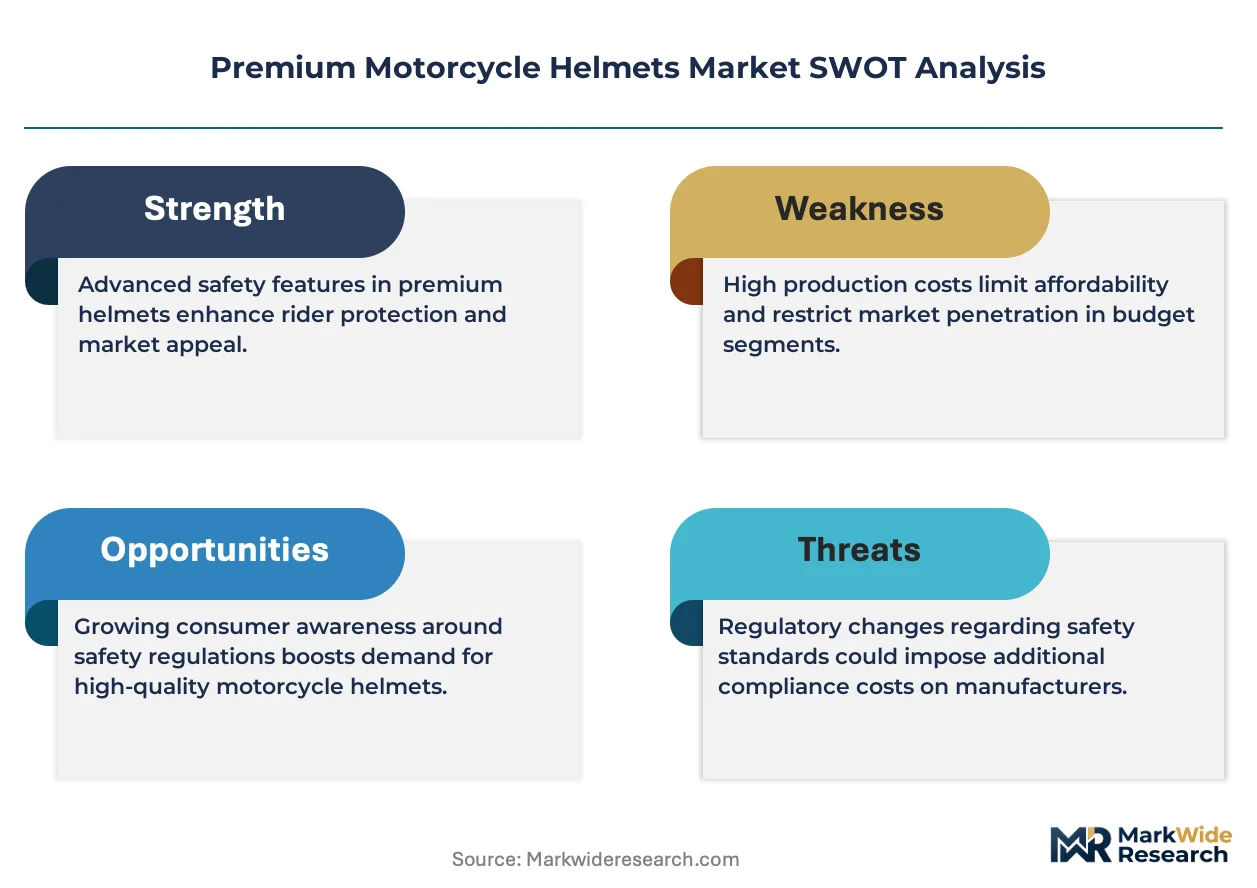
ECE 22.06 certification mandates are forcing wholesale redesign cycles across the premium helmet sector, compelling manufacturers to re-engineer shell geometries, liner densities, and retention systems to satisfy oblique impact protocols that exceed legacy testing thresholds.
Growth Catalysts
- Composite Material Advancement:Carbon fiber layup techniques refined in aerospace applications are migrating into helmet shell production, delivering weight reductions that track-day riders prioritize over legacy fiberglass constructions.
- Japan's JIS T 8133 Alignment:Updated testing protocols harmonizing with ECE 22.06 oblique impact standards are expanding addressable markets for certified manufacturers seeking premium positioning in Asian markets.
- Alpine Road Network Density:Italy's concentrated high-altitude touring corridors sustain replacement demand among sport-touring enthusiasts who subject helmets to thermal cycling and UV degradation.
Market Restraints
- Carbon Fiber Supply Concentration:Prepreg manufacturing capacity clusters in Japan and the United States, exposing premium brands to aerospace contract prioritization and extended lead times during demand surges.
- ECE 22.06 Compliance Friction:The regulation's rotational acceleration testing requirements demand specialized laboratory infrastructure that smaller manufacturers cannot access, consolidating design authority among well-capitalized incumbents.
- Integrated Communication Substitution:Aftermarket Bluetooth communicator systems from Cardo and Sena threaten OEM connectivity premiums by delivering comparable functionality at lower installed cost.
Strategic Opportunities
- Heads-Up Display Convergence:Micro-projection optics and augmented reality overlays represent untapped white space beyond basic Bluetooth integration, enabling navigation and telemetry visualization without rider distraction.
- Indian Premium Two-Wheeler Expansion:Rising disposable incomes among 300cc-plus motorcycle purchasers in Maharashtra and Karnataka create first-time premium helmet adoption potential.
- Australian Market Harmonization:AS/NZS 1698 standards revision aligning with ECE 22.06 protocols reduces certification duplication costs for European-certified manufacturers entering Oceania.
Industry Challenges
- Computational Modeling Talent Scarcity:Finite element analysis expertise for impact simulation commands premium compensation, constraining smaller manufacturers' ability to iterate designs rapidly.
- Multi-Certification Timeline Compression:Simultaneous pursuit of ECE 22.06, Snell, and JIS approvals extends product development cycles by 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Motorcycle Helmets Market |
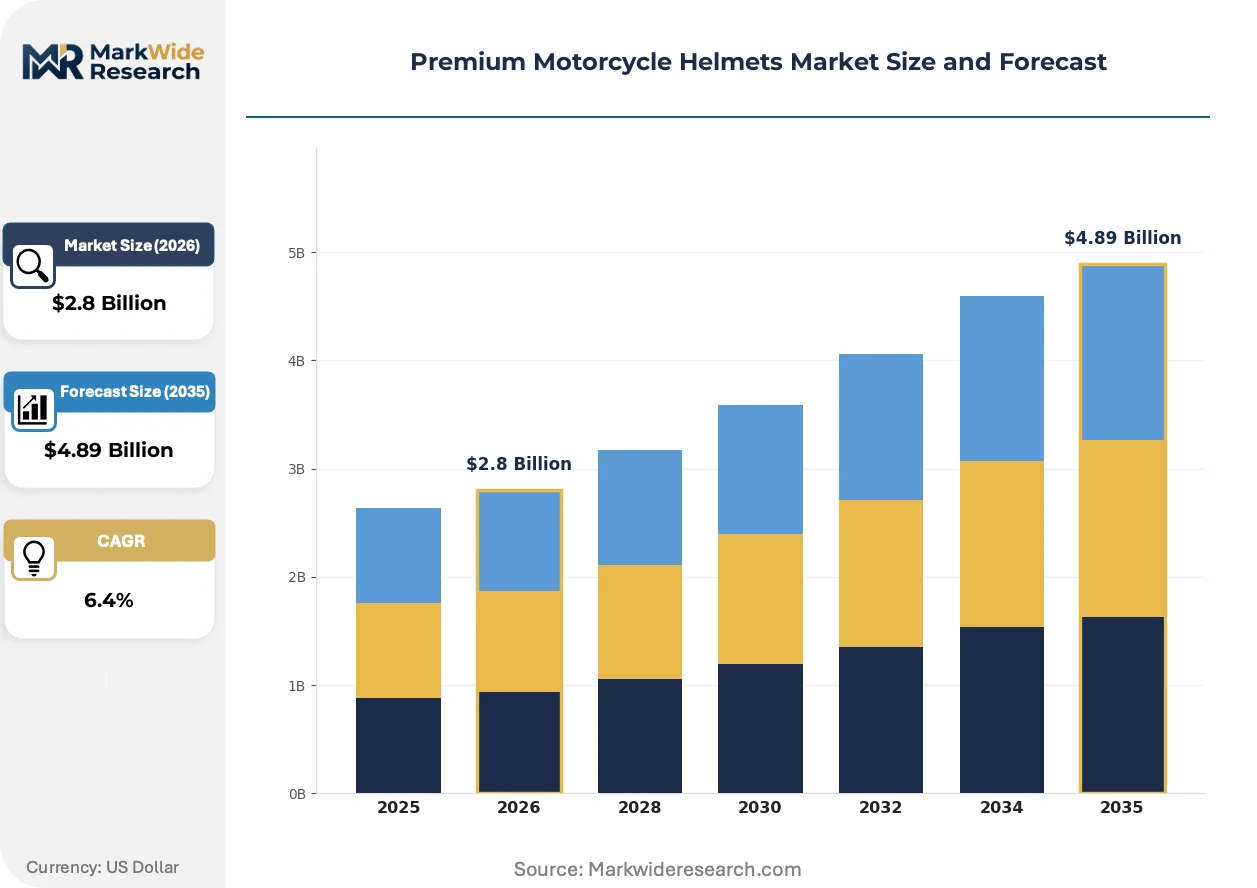
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Face, Modular, Open Face, Half Helmet Material: Fiberglass, Carbon Fiber, Polycarbonate, Kevlar Brand: Shoei, Arai, Bell, HJC Feature: Bluetooth Enabled, Anti-Fog Visor, Lightweight, Advanced Ventilation |
| Companies Covered | AGV Helmets, Dainese SpA, Shoei Co. Ltd, HJC Helmets, Nolan Helmets SpA, Arai Helmet Limited, Bell Helmets, Shark Helmets, Schuberth GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Motorcycle Helmets Market Strategic Shifts & Innovations
Active safety integration and material science breakthroughs are redefining performance benchmarks, shifting competitive advantage from passive impact absorption toward real-time hazard mitigation and biometric monitoring.
Multi-density EPS liner systems with variable cell structures are automating energy management across impact velocities. Track-day riders and sport-touring enthusiasts are specifying these configurations in custom-fit orders. The technology is automating the trade-off between low-speed comfort and high-speed protection that previously required manual liner selection.
REACH regulation amendments restricting persistent organic pollutants in textile treatments are compelling visor anti-fog coating reformulations. Manufacturers serving European markets must qualify alternative hydrophilic chemistries that maintain optical clarity across temperature extremes. Racing-oriented product lines face the steepest reformulation costs due to stringent anti-fog performance requirements.
Direct-to-consumer fit scanning via smartphone photogrammetry is displacing traditional retail sizing for premium purchasers. Urban dealerships in Milan and Munich are consolidating floor space as riders complete purchases through manufacturer portals. This pattern concentrates most visibly among carbon fiber full-face buyers who prioritize precise shell matching over immediate inventory availability.
Premium Motorcycle Helmets Market Segmentation
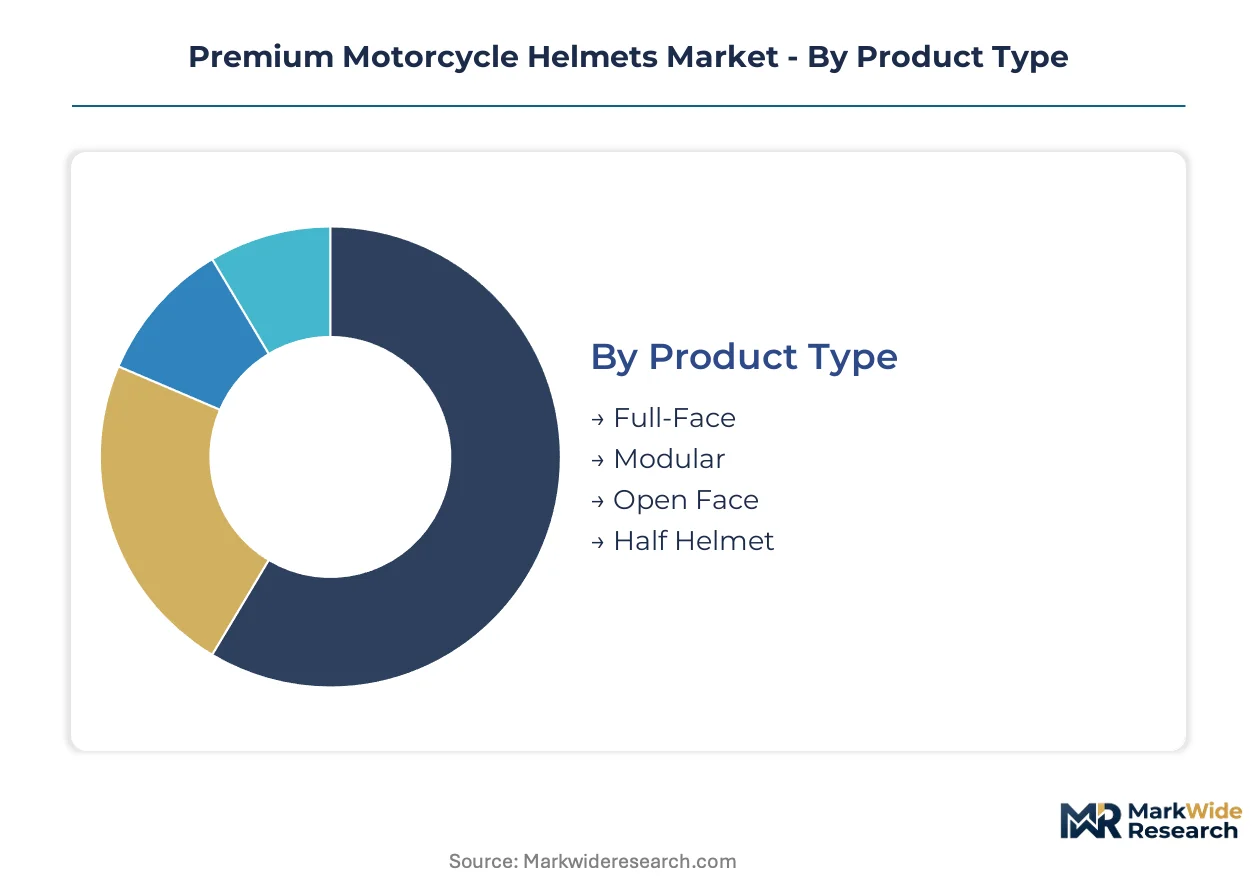
Premium motorcycle helmets fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct buyer priorities that manufacturers must address through targeted engineering and positioning strategies.
Product Type:
Helmet configuration choice reflects riding discipline intensity and risk tolerance thresholds among purchasers.
- Full-Face:Enclosed shell design with integrated chin bar and visor mechanism delivers maximum structural coverage for high-speed road and track applications. Italian sport-touring corridors and Japanese expressway networks sustain replacement demand as riders prioritize impact protection over ventilation convenience.
- Modular:Hinged chin bar enables open-face configuration for urban commuting while retaining full-coverage capability for highway segments. European metropolitan riders in Milan and Munich specify these systems for multimodal journeys combining city traffic and alpine touring routes.
- Open Face:Three-quarter coverage shell exposes the chin and lower face for improved peripheral vision and airflow. Urban scooter operators in Mediterranean climates favor this configuration for low-speed maneuverability.
- Half Helmet:Minimalist crown coverage meeting baseline legal requirements with negligible weight penalty. Casual cruiser riders in North American markets accept reduced protection for styling conformity.
Full-face configurations command the dominant revenue position today; modular systems are gaining share fastest among urban professionals seeking versatility.
Material:
Shell composition directly determines weight-to-strength ratios that performance-oriented riders weight heavily in purchase decisions.
- Fiberglass:Woven glass fiber reinforcement in thermoset resin matrices delivers balanced impact absorption and manufacturing scalability. Established production lines in Italy and Japan supply volume production for mid-premium positioning.
- Carbon Fiber:Aerospace-grade prepreg layup achieves 30-40% weight reduction versus fiberglass equivalents. Track-day riders and racing professionals absorb premium pricing for rotational inertia reduction during high-G cornering sequences.
- Polycarbonate:Injection-molded thermoplastic shells enable cost-efficient production with consistent thickness distribution. Entry-premium positioning targets first-time buyers transitioning from basic protection.
- Kevlar:Aramid fiber reinforcement adds puncture resistance and structural integrity for extreme impact scenarios. Specialized applications in professional racing and military-adjacent markets justify material costs.
Fiberglass maintains volume leadership across certified product lines; carbon fiber is expanding most quickly as weight reduction becomes a decisive purchase criterion.
Brand:
Manufacturer heritage and certification pedigree segment buyers along trust and performance expectation continuums.
- Shoei:Japanese engineering tradition emphasizing wind tunnel-validated aerodynamics and multi-density liner systems. In-house testing infrastructure supports rapid iteration across racing and touring portfolios.
- Arai:Family-owned manufacturing with proprietary round-oval shell philosophy and hand-built construction protocols. Snell Foundation certification alignment reinforces premium positioning in North American markets.
- Bell:American motorsport heritage spanning automotive and motorcycle applications with integrated communications development. Racing pedigree supports credibility in closed-circuit segments.
- HJC:Korean manufacturing scale enabling competitive pricing across certification tiers with expanding carbon fiber capability. European market penetration accelerates through ECE 22.06 compliance investment.
Shoei and Arai anchor the premium tier through heritage manufacturing; HJC is climbing fastest through aggressive certification expansion and price positioning.
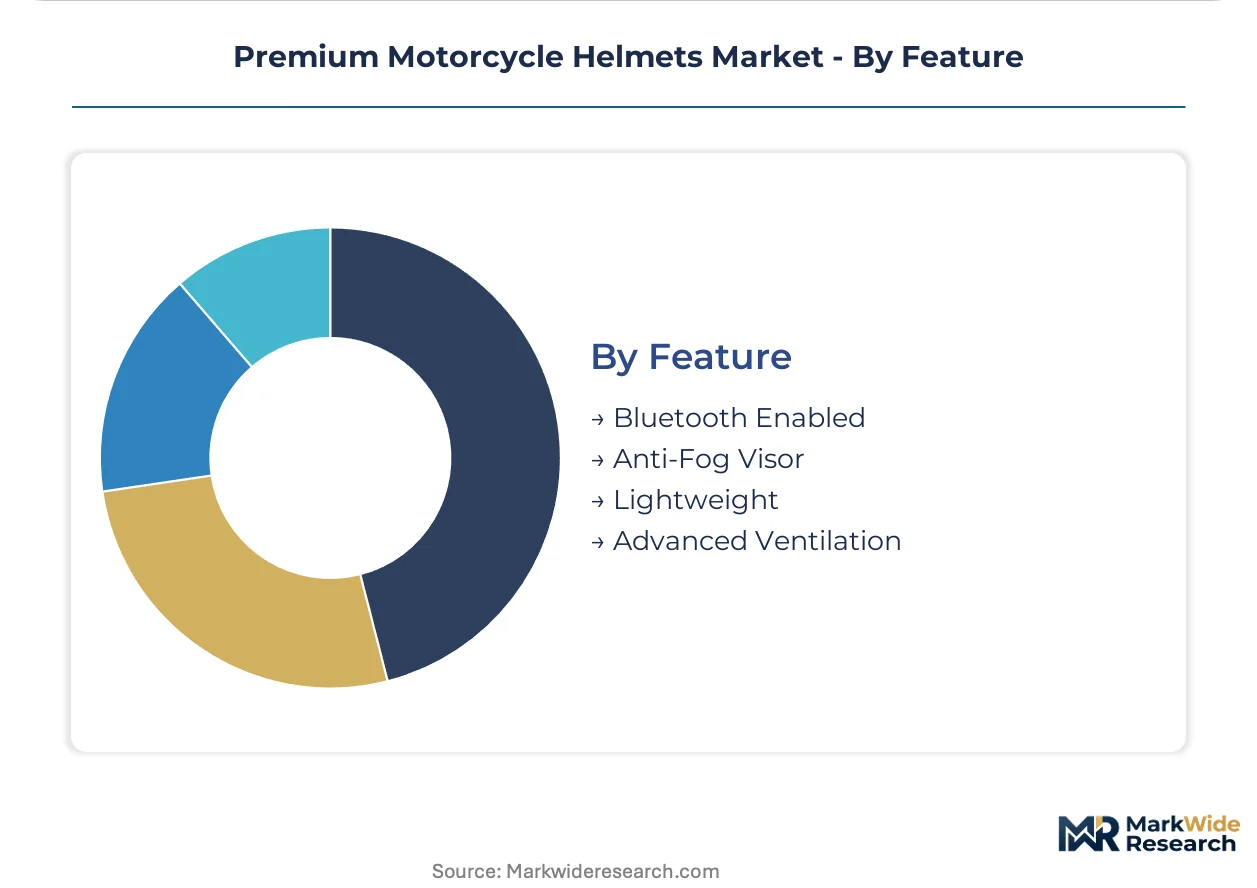
Feature:
Integrated functionality expectations are maturing from premium differentiators toward baseline requirements.
- Bluetooth Enabled:Embedded wireless communication modules enabling rider-to-rider intercom and smartphone connectivity. Aftermarket substitution pressure from Cardo and Sena compresses OEM margin pools for basic implementations.
- Anti-Fog Visor:Hydrophilic coating chemistries maintaining optical clarity across temperature differentials. REACH regulation amendments in Europe are forcing coating reformulations that increase qualification costs.
- Lightweight:Material and structural optimization targeting sub-1400g mass for full-face configurations. Neck strain reduction during extended touring sessions drives specification among aging rider demographics.
- Advanced Ventilation:Multi-position intake and exhaust port systems with ducted airflow management. Alpine road thermal cycling conditions in Italian and Austrian markets validate performance claims.
Bluetooth integration leads feature attachment rates today; advanced ventilation is gaining specification fastest as climate adaptability becomes a purchase priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian composite engineers and Japanese wind tunnel aerodynamicists anchor the geographic talent clusters shaping premium helmet development. Their proximity to racing circuits and certification laboratories concentrates design authority in specific metropolitan zones. Regional demand patterns diverge sharply between alpine touring corridors and urban commuting basins.
Italy
MotoGP heritage and dense alpine road networks sustain replacement demand among sport-touring enthusiasts. ECE 22.06 certification mandates from Brussels force continuous redesign cycles for manufacturers based in the Lombardy and Emilia-Romagna industrial clusters. The Modena corridor hosts multiple legacy brands whose hand-built construction protocols command premium positioning across European markets.
Japan
Expressway network density and track-day rider expansion drive specification of lightweight carbon fiber configurations. METI-aligned updates to JIS T 8133 standards harmonize oblique impact testing with European protocols, reducing certification friction for domestic manufacturers. The Tokyo-Osaka manufacturing belt concentrates wind tunnel facilities and prepreg composite supply chains serving both aerospace and helmet applications.
Germany
Autobahn touring culture and high-performance motorcycle ownership rates sustain demand for advanced ventilation systems. KBA enforcement of ECE 22.06 compliance creates barrier conditions for uncertified imports while rewarding established European manufacturers. The Bavarian industrial corridor around Munich anchors precision molding capabilities and testing laboratory infrastructure.
United States
Track-day participation growth and closed-circuit racing culture expand the addressable base for Snell-certified headgear. NHTSA oversight of FMVSS 218 baseline standards persists alongside voluntary Snell Memorial Foundation tiering that segments premium positioning. California and Texas metropolitan clusters concentrate specialty retail networks and direct-to-consumer fit scanning adoption.
India
Rising disposable incomes among 300cc-plus motorcycle purchasers in Maharashtra and Karnataka create first-time premium helmet adoption potential. BIS certification alignment with international standards remains partial, creating compliance complexity for imported brands. The Pune-Bengaluru industrial corridor hosts emerging domestic manufacturers investing in carbon fiber layup capabilities.
Premium Motorcycle Helmets Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across a tiered market structure where heritage manufacturing credentials separate premium positioning from volume plays. The vendor base clusters around three strategic archetypes: Japanese engineering-led brands emphasizing aerodynamic validation, Italian heritage manufacturers leveraging racing pedigree and hand-built construction, and Korean scale players compressing price points through automated production. Competitive moves concentrate on certification expansion to unlock geographic markets and material upgrades to capture weight-sensitive performance segments.
Within the heritage manufacturing tier, Arai Helmet Limited and AGV Helmets exemplify family-owned or racing-tethered positioning that resists commoditization pressure. Shoei Co. Ltd occupies a position between pure heritage and engineering-scale hybridization. HJC Helmets represents the scale-driven archetype climbing into premium tiers through aggressive ECE 22.06 compliance investment and carbon fiber portfolio expansion.
| Leading Market Players |
|---|
| AGV Helmets |
| Dainese SpA |
| Shoei Co. Ltd |
| HJC Helmets |
| Nolan Helmets SpA |
| Arai Helmet Limited |
| Bell Helmets |
| Shark Helmets |
| Schuberth GmbH |
| Others |
Cost & Logistics Intelligence
Carbon fiber prepreg layup migration from aerospace applications is simultaneously compressing unit economics for premium helmet shells and concentrating manufacturing authority among Japanese and Italian facilities with legacy composite expertise. This dual transformation rewards incumbents with captive wind tunnel and testing infrastructure while squeezing margin recovery for brands dependent on outsourced shell procurement.
Pricing Analysis
Bluetooth communicator bundling versus standalone helmet sales defines the dominant pricing split. Three-tier pricing structure across premium carbon fiber, mid-grade fiberglass, and entry polycarbonate levels segments buyers by certification ambition and weight sensitivity. Pricing pressure stems from Cardo and Sena aftermarket systems delivering comparable connectivity at lower installed cost. Track-day riders absorb highest premiums for rotational inertia reduction, while commuter segments exhibit greatest price elasticity.
Supply Chain Analysis
Composite technician scarcity in Japan's Kansai region and Italy's Emilia-Romagna belt constrains shell production scaling for ECE 22.06-compliant manufacturers. Prepreg carbon fiber supply clusters in Japan and the United States, with fiberglass weaving concentrated in Italy and Taiwan. Single-source vulnerability runs through Toray Industries aerospace contract prioritization during demand surges. Distribution runs through specialty motorsport retailers in Milan, Munich, and Los Angeles, supplemented by direct-to-consumer fit scanning portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between European ECE 22.06 certification investment and Asian manufacturing cost bases creates structural margin opportunity for brands with dual-hemisphere production footprints. The JIS T 8133 harmonization with European oblique impact standards collapses regulatory friction for manufacturers with existing Tokyo-Osaka testing infrastructure.
For Market Incumbents: Extend wind tunnel validation capabilities into modular helmet architectures to capture urban professional demand in Milan and Munich. Consolidate design authority through in-house carbon fiber layup production, defending against HJC's aggressive ECE 22.06 certification expansion. Certification investment remains the priority lever for geographic market access. For New Entrants and Emerging Players: Begin with direct-to-consumer fit scanning platforms targeting Indian 300cc-plus motorcycle purchasers in Maharashtra and Karnataka. White space concentrates in heads-up display integration beyond basic Bluetooth, and in Australian AS/NZS 1698 alignment leveraging European certification equivalence. Go-to-market should emphasize smartphone photogrammetry precision over retail floor space. For Investors and Strategic Acquirers: Roll-up economics work for heritage manufacturing specialists with hand-built construction protocols and MotoGP tethered brand equity, because ECE 22.06 compliance friction consolidates design authority among well-capitalized incumbents with laboratory infrastructure. Five-to-ten year viability hinges on carbon fiber portfolio penetration and integrated display technology readiness. Watch for JIS T 8133 enforcement acceleration as inflection signal for Asian market access premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| ECE 22.06 Certification Investment | Unlocks European market access and signals quality tiering to Japanese and Australian regulators. |
| Carbon Fiber Portfolio Expansion | Captures weight-sensitive track-day riders and sport-touring enthusiasts prioritizing rotational inertia reduction. |
| Direct-to-Consumer Fit Scanning Launch | Displaces traditional retail sizing in Milan and Munich urban corridors for carbon fiber full-face buyers. |
| Heads-Up Display Integration | Opens white space beyond Bluetooth commoditization through augmented reality navigation overlays. |
| Indian Distribution Partnership | Addresses rising disposable incomes among 300cc-plus motorcycle purchasers in Maharashtra and Karnataka. |
Research Approach
Direct dialogue with helmet design engineers, composite manufacturing specialists, motorsport retail buyers, and certification laboratory directors grounded qualitative findings in operational reality. Secondary validation drew from ECE documentation, JIS T 8133 protocol amendments, METI regulatory filings, and customs trade data for carbon fiber prepreg movements. Bottom-up unit economics and top-down market sizing triangulated volume and value estimates.
Bottom-up modeling tracked helmet shipments by material grade, configuration type, and certification tier across the projection horizon. Top-down validation assessed aggregate consumer expenditure on premium two-wheeler accessories through regional registration data and discretionary income proxies. Segmentation dimensions included shell material, face coverage configuration, integrated feature set, and geographic regulatory cluster. CAGRs derived from fitted growth curves against historical replacement cycle patterns and certification mandate implementation timelines.
Several conditions sit outside the modeled scope, including unforeseen harmonization between FMVSS 218 and ECE frameworks, abrupt carbon fiber supply disruption from aerospace contract prioritization, and rapid aftermarket communicator technology obsolescence. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and material cost trajectories. Material deviation in JIS T 8133 adoption velocity, ECE 22.06 laboratory capacity expansion, or Indian BIS alignment progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Body Armor Accessories Market
Safety Equipment and Personal Protective Equipment (PPE)
FFP2 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Protective Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market