
 Safety Connection Devices Market | 2026-2036
Safety Connection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Connection Devices Market Analytics
Germany is reconfiguring its industrial safety hardware supply base as machinery OEMs localize production of AS-Interface and PROFIsafe gateway modules. Siemens AG leverages deep integration with German automotive assembly lines to sustain specification control across Tier-1 automation procurement. Rockwell Automation, Inc. anchors North American channel presence through embedded safety I/O partnerships with material handling integrators. ABB Ltd competes on marine-certified safety junction boxes for offshore energy platforms in the North Sea and Gulf of Mexico.
Safety connection devices comprise electromechanical and electronic components—safety relays, interlock switches, programmable safety controllers, and network gateways—that monitor machine guard positions, emergency stop circuits, and hazardous area access points to achieve SIL-rated or Category-4/PLe functional safety per ISO 13849. These devices translate physical safety states into standardized digital signals traversing industrial fieldbus or Ethernet safety protocols to halt equipment within milliseconds of fault detection. Wireless sensors and emergency shut-off systems command the strongest margin pools as end-users retrofit aging hardwired E-stop chains with networked, diagnostics-capable alternatives. IoT connectivity and embedded systems represent the fastest-expanding technology pairing, though Bluetooth technology lags in high-availability environments due to latency and interference susceptibility.
The EU Machinery Regulation and CE marking framework compel manufacturers to document safety control reliability through notified body assessment, directly expanding demand for certified connection hardware with traceable MTTFd data. OSHA lockout/tagout standards and NFPA 70E electrical safety mandates in the United States drive periodic replacement of non-compliant legacy contactors and terminal blocks in heavy manufacturing. Stakeholders must monitor evolving IEC 62061 and ISO 13849 harmonization timelines to align product roadmaps with upcoming third-party certification requirements before compliance deadlines harden competitive access barriers.
Market Dynamics
The transition from hardwired safety architectures to networked, diagnostics-capable systems is compressing replacement cycles and forcing incumbent suppliers to requalify legacy product lines under harmonized IEC 62061 and ISO 13849 certification timelines.
Growth Catalysts
- EU Machinery Regulation:Tightened CE marking requirements for documented safety control reliability are expanding demand for certified connection hardware with traceable MTTFd data across German and Italian machinery OEM supply chains.
- Wireless retrofit momentum:End-users in automotive assembly and material handling are replacing aging hardwired E-stop chains with networked alternatives, commanding premium margins for diagnostics-enabled safety relays and interlock switches.
- OSHA enforcement intensity:Periodic compliance audits in US heavy manufacturing are accelerating replacement of non-compliant legacy contactors and terminal blocks under lockout/tagout and NFPA 70E electrical safety mandates.
Market Restraints
- Semiconductor input volatility:Safety controller and gateway module production faces margin pressure from specialized industrial-grade chip supply concentration in East Asian foundries.
- Bluetooth latency limitations:Wireless safety protocols in high-availability environments remain constrained by interference susceptibility, limiting deployment in metal-intensive automotive body shops.
- Third-party certification bottlenecks:Notified body assessment queues for SIL-rated and Category-4/PLe documentation are extending product launch timelines by six to twelve months for mid-tier suppliers.
Strategic Opportunities
- Marine-certified safety junction boxes:Offshore energy platforms in the North Sea and Gulf of Mexico present underpenetrated demand for corrosion-resistant, explosion-proof safety connection hardware.
- IoT-Ethernet convergence:Integration of embedded diagnostics with PROFIsafe and CIP Safety protocols is opening specification control at greenfield battery manufacturing facilities.
- India PLI scheme alignment:Machinery safety component localization incentives are creating channel entry points for AS-Interface gateway production serving domestic automotive and textile equipment builders.
Industry Challenges
- Functional safety engineering scarcity:Qualified talent for SIL verification and ISO 13849 compliance documentation is concentrated among Tier-1 automation suppliers, constraining mid-market R&D scaling.
- Legacy system integration friction:Retrofit projects face commissioning complexity when bridging decades-old hardwired safety chains with modern Ethernet-based safety networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Connection Devices Market |
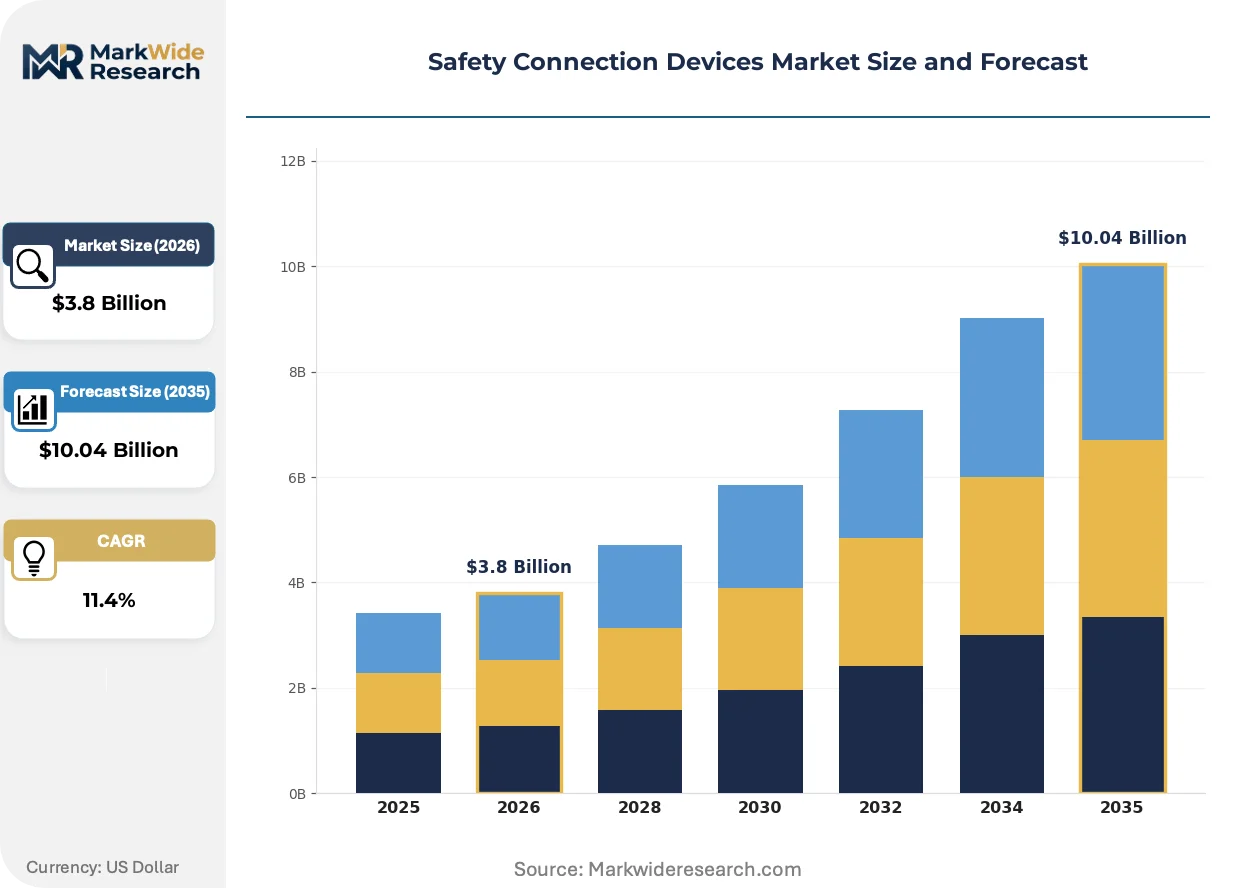
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Safety Alarms, Emergency Shut-off Systems, Circuit Breakers End User: Manufacturing Plants, Healthcare Facilities, Oil & Gas Industry, Construction Sites Technology: IoT Connectivity, Bluetooth Technology, RFID Systems, Embedded Systems Application: Personal Safety, Equipment Monitoring, Hazard Management, Fire Protection |
| Companies Covered | Rockwell Automation, Inc., ABB Ltd, Siemens AG, Schneider Electric SE, Honeywell International Inc, Advantech Co Ltd, Bihl + Wiedemann GmbH, Ifm electronic gmbh, TE Connectivity Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Connection Devices Market Evolving Landscape
Diagnostics-embedded safety hardware is displacing passive electromechanical components, while regulatory harmonization and buyer consolidation are reshaping competitive qualification requirements and channel economics.
Ethernet-based safety protocols with integrated condition monitoring are rendering obsolete standalone safety relays that lack remote diagnostics capability. Automotive OEMs in Germany and the United States are specifying these networked alternatives in new assembly line contracts. The shift is compressing margins for suppliers dependent on replacement part revenue from legacy installed bases.
REACH substance restrictions and RoHS recast directives are forcing reformulation of contact materials in safety interlock switches sold into European markets. Manufacturers must resubmit technical documentation to notified bodies for updated CE marking compliance. German machinery builders are accelerating supplier audits to verify material composition traceability ahead of enforcement deadlines.
Specification consolidation among material handling integrators is concentrating procurement authority with embedded safety I/O partners rather than distributed component distributors. System integrators in North American logistics hubs are demanding bundled safety controller and gateway packages with unified technical support. This channel compression is squeezing standalone safety relay vendors without integrator certification programs.
Safety Connection Devices Market Segmentation
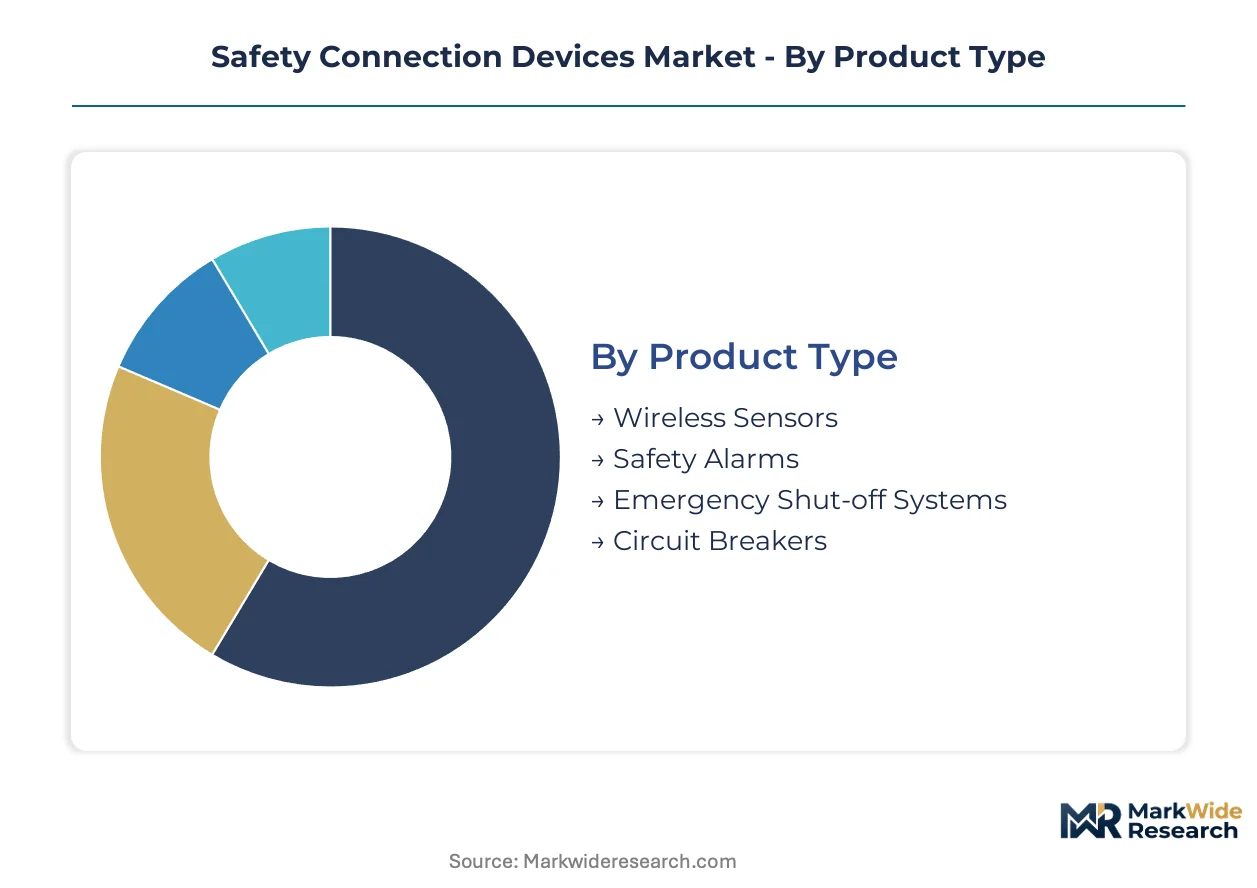
Safety connection devices fragment across four critical dimensions that determine procurement patterns and supplier economics. Product type governs replacement cadence and margin structure. End user concentration shapes regional demand geography. Technology selection locks in architecture decisions for multi-year deployment cycles. Application focus determines certification requirements and regulatory exposure.
Product Type:
Wireless sensors and emergency shut-off systems command the shortest replacement cycles due to battery degradation and firmware obsolescence, while circuit breakers and safety alarms persist for decades in hardwired installations.
- Wireless Sensors:Battery-powered devices transmitting guard position and proximity data over industrial wireless protocols. German automotive assembly plants are retrofitting legacy interlock chains with networked alternatives to satisfy tightened EU Machinery Regulation documentation requirements.
- Emergency Shut-off Systems:Networked E-stop stations with integrated diagnostics replacing hardwired relay chains. Demand concentrates in US material handling facilities where OSHA lockout/tagout audits are accelerating replacement of non-compliant legacy infrastructure.
- Safety Alarms:Audible and visual warning devices triggered by safety controller outputs. Petrochemical facilities in the Gulf of Mexico specify marine-certified variants for offshore platform deployment.
- Circuit Breakers:Overcurrent protection devices with safety-rated auxiliary contacts for SIL loops. Heavy manufacturing in the US Midwest maintains steady demand for replacement of aging motor protection circuits.
Circuit breakers dominate installed base across industrial facilities worldwide. Wireless sensors are where expansion concentrates as diagnostics-enabled architectures displace passive electromechanical alternatives.
End User:
Cost tier stratification separates specification-intensive applications with certified hardware requirements from price-sensitive deployments tolerating standard industrial components.
- Manufacturing Plants:Automotive, electronics, and food processing facilities requiring Category-4/PLe safety architectures. German machinery OEMs are localizing AS-Interface gateway production to serve domestic assembly line builders.
- Oil & Gas Industry:Upstream and downstream operations demanding explosion-proof and corrosion-resistant safety junction boxes. North Sea and Gulf of Mexico platforms present underpenetrated demand for marine-certified connection hardware.
- Healthcare Facilities:Hospitals and medical device manufacturing with specialized cleanroom and patient safety requirements. US facilities align procurement with Joint Commission accreditation standards and NFPA 99 electrical system guidelines.
- Construction Sites:Temporary and mobile equipment installations with portable safety systems. Price sensitivity here favors standard industrial relays over certified safety controllers.
Manufacturing plants anchor procurement volume through automation upgrade cycles. Oil and gas represents the steepest expansion trajectory as offshore energy investment revives and platform safety system refresh accelerates.
Technology:
Supply concentration in semiconductor fabrication shapes availability and pricing volatility for controller and gateway modules.
- IoT Connectivity:Cloud-integrated safety devices with remote monitoring and predictive maintenance capabilities. Battery manufacturing facilities in Germany and the United States are specifying IoT-Ethernet convergence in greenfield automation contracts.
- Embedded Systems:Safety controllers with integrated diagnostics and protocol translation. These modules face margin pressure from specialized industrial-grade chip supply concentration in East Asian foundries.
- RFID Systems:Contactless access control and personnel tracking for hazardous area management. Chemical processing plants in Germany deploy these for CE-marked machinery safety compliance.
- Bluetooth Technology:Short-range wireless for portable safety devices and configuration interfaces. Latency limitations and interference susceptibility constrain deployment in metal-intensive automotive body shops.
Embedded systems capture the largest share of controller and gateway revenue. IoT connectivity is climbing the fastest as end-users retrofit aging installations with remote diagnostics capability.
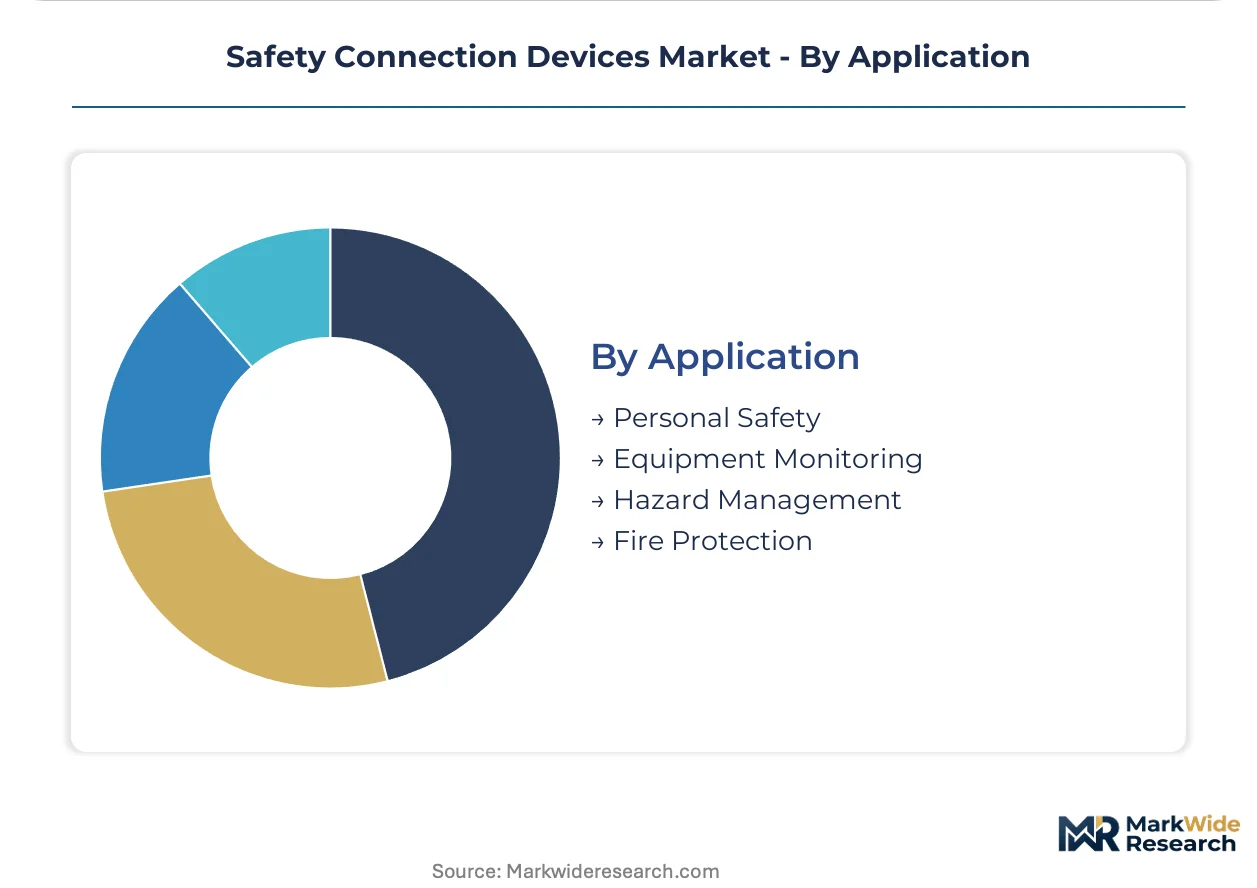
Application:
Maturity gradients separate established fire protection and personal safety categories from emerging equipment monitoring and integrated hazard management platforms.
- Equipment Monitoring:Condition-based safety interlocks tracking machine guard integrity and emergency stop circuit health. German automotive OEMs specify networked alternatives with integrated diagnostics in new assembly line contracts.
- Hazard Management:Coordinated safety responses across multiple hazard zones through centralized safety controllers. US logistics hubs demand bundled safety controller and gateway packages with unified technical support.
- Fire Protection:Smoke detection and suppression system integration with safety networks. Commercial and industrial facilities maintain steady replacement demand for legacy fire alarm interface modules.
- Personal Safety:Wearable devices and area monitoring for lone worker protection. Construction and offshore energy applications drive demand for portable, battery-powered safety transmitters.
Fire protection commands the deepest installed base through code-mandated system maintenance. Equipment monitoring is gaining share fastest as predictive safety architectures displace reactive maintenance models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian semiconductor foundries supply critical industrial-grade chips for safety controllers and gateway modules, while machinery OEM clusters in Germany and the United States drive specification authority for certified connection hardware.
United States
OSHA enforcement intensity and industrial automation upgrades accelerate replacement cycles for legacy hardwired safety infrastructure. NFPA 70E electrical safety mandates compel periodic renewal of non-compliant contactors and terminal blocks in heavy manufacturing. Material handling integrators in Midwest logistics hubs demand bundled safety controller packages with unified technical support.
Germany
Machinery OEMs localize production of AS-Interface and PROFIsafe gateway modules following tightened EU Machinery Regulation directives. CE marking requirements for documented safety control reliability expand demand for certified hardware with traceable MTTFd data. Automotive assembly clusters in Bavaria and Baden-Württemberg specify networked safety architectures in new line contracts.
China
Battery manufacturing facilities specify IoT-Ethernet convergence in greenfield automation contracts, driving demand for embedded diagnostics-capable safety devices. GB standards alignment with IEC functional safety norms pressures domestic suppliers toward third-party SIL certification. Yangtze River Delta industrial zones concentrate procurement for automotive and electronics assembly safety upgrades.
India
PLI scheme incentives for machinery safety component localization create channel entry points for AS-Interface gateway production. Domestic automotive and textile equipment builders expand safety system specifications as export compliance requirements tighten. Gujarat and Maharashtra industrial corridors anchor demand for retrofit safety infrastructure in aging manufacturing plants.
United Kingdom
North Sea offshore energy platforms present underpenetrated demand for marine-certified, corrosion-resistant safety junction boxes. Post-Brexit regulatory divergence from EU Machinery Regulation creates certification complexity for cross-border equipment suppliers. Aberdeen energy cluster drives specification for explosion-proof safety connection hardware in platform refresh cycles.
Safety Connection Devices Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fragmented supply tiers. The vendor base separates into consolidated automation conglomerates with full-stack safety portfolios and mid-tier specialists focused on protocol-specific gateway modules. Three archetypes dominate: diversified industrial automation platforms, safety protocol specialists, and marine-certified hardware fabricators. Competitive moves concentrate on embedded safety I/O partnerships with system integrators and geographic localization of gateway production.
Among German-based automation conglomerates, Siemens AG and Bihl + Wiedemann GmbH exemplify divergent strategic positions within the safety protocol ecosystem. Rockwell Automation, Inc. anchors North American channel presence through integrator-embedded partnerships. Schneider Electric SE occupies a position spanning both European and North American specification networks.
| Leading Market Players |
|---|
| Rockwell Automation, Inc. |
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Honeywell International Inc |
| Advantech Co Ltd |
| Bihl + Wiedemann GmbH |
| Ifm electronic gmbh |
| TE Connectivity Ltd |
| Others |
Value Network & Pricing Analysis
East Asian foundry concentration for industrial-grade safety controller chips feeds margin compression into mid-tier gateway suppliers while premium-tier vendors capture value through embedded diagnostics bundling. German automotive OEMs and US material handling integrators concentrate procurement authority, amplifying price leverage over standalone component vendors.
Pricing Analysis
EU Machinery Regulation CE marking requirements dictate the pricing tier structure across safety connection hardware. Three-tier pricing structure across SIL-certified premium, standard industrial-grade, and uncertified economy levels separates vendors by traceable MTTFd documentation depth. Price differentiation rests on certification grade and after-sales technical support bundling. Cost compression in standard-tier safety relays is intensifying because semiconductor input volatility feeds through from East Asian foundries. Construction site buyers exhibit highest price sensitivity, tolerating non-certified relays, while offshore energy platforms accept premium marine-certified hardware with minimal negotiation.
Supply Chain Analysis
Extended payment terms from German machinery OEMs and supply-chain finance facilities at major automotive assemblers strain working capital for mid-tier safety component vendors. Manufacturing concentrates in Germany, China, and the United States for gateway modules and safety controllers. Production draws from specialized industrial-grade semiconductors, corrosion-resistant alloys for marine enclosures, and high-reliability electromechanical contacts. Single-source vulnerability in East Asian foundry capacity for safety-rated microcontrollers threatens delivery timelines. Distribution runs through embedded safety I/O partnerships with system integrators rather than traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among material handling integrators and automotive OEMs, compressing channel economics for standalone safety relay vendors without embedded partnership certification.
For Market Incumbents: Entrench specification control through PROFIsafe and CIP Safety protocol certification investments at greenfield battery manufacturing facilities. Deepen backward integration into AS-Interface gateway module production in Germany to defend margin position against localized competitors. Lock in channel control via unified technical support bundling with safety controller packages for North American logistics hub integrators. For New Entrants and Emerging Players: Marine-certified safety junction boxes for North Sea and Gulf of Mexico offshore platforms represent the most penetrable entry point given underpenetrated supply and specialized certification barriers. India PLI scheme-aligned AS-Interface gateway production for domestic automotive and textile equipment builders offers second-mover localization advantages. Pursue go-to-market through notified body partnerships to accelerate SIL-rated documentation timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation platforms seeking portfolio rationalization. Five-to-ten year viability hinges on Ethernet safety protocol convergence and IoT-Ethernet integration capability at battery manufacturing facilities. Target acquisition archetype: mid-tier safety protocol specialists with embedded diagnostics IP and integrator certification relationships. Watch for inflection in notified body assessment queue lengths as signal for competitive access barrier hardening.| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Certification Investment | PROFIsafe and CIP Safety certification locks in specification control at German automotive OEMs. |
| Geographic Localization | AS-Interface gateway production in India captures PLI scheme incentives for domestic machinery builders. |
| Marine Certification Program | Explosion-proof safety junction box certification opens North Sea and Gulf of Mexico platform demand. |
| Embedded Diagnostics Development | Integrated condition monitoring displaces passive electromechanical relays in automotive assembly retrofits. |
| Integrator Partnership Expansion | Embedded safety I/O partnerships with material handling integrators concentrate procurement authority. |
Research Methodology
A spread of perspectives from plant engineers at German automotive OEMs, procurement leads at US material handling integrators, safety system architects at offshore energy operators, and notified body certification specialists converged on the working assumptions. Primary field engagement combined with secondary validation from EU Machinery Regulation documentation, OSHA enforcement records, SEC filings of listed automation suppliers, and IEC standard harmonization timelines. Bottom-up installed base modeling and top-down industrial automation capex analysis triangulated volume estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end user concentration, technology selection, and application maturity. CAGRs derived from replacement cycle compression rates and greenfield specification adoption curves. Forecast inputs incorporated semiconductor lead time volatility and notified body assessment queue dynamics.
Macroeconomic conditions sit as an overlay; deviation in industrial automation investment cycles, EU regulatory enforcement intensity, or East Asian foundry capacity utilization would shift the trajectory. Forecasts reflect documented assumptions about replacement cadence and protocol convergence timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Guns Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
In Room Safes Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market