
 Middle East and Africa Safety Lancet Market | 2026-2036
Middle East and Africa Safety Lancet Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Safety Lancet Market Analytics
Bundle configurations that pair safety lancets with blood glucose monitoring consumables is pivoting hospital procurement patterns across the Middle East and Africa. Cardinal Health leverages its distribution infrastructure to anchor supply contracts with large hospital networks in Saudi Arabia and the United Arab Emirates. B. Braun SE sustains manufacturing scale for safety-engineered devices, while BD differentiates through integrated diabetes management portfolios that span lancets, meters, and data platforms.
A safety lancet is a single-use puncture device incorporating an integrated needle or blade with a spring-loaded retraction mechanism that shields the user after activation, typically manufactured from medical-grade ABS plastic housings and stainless steel needles with penetration depths calibrated between 0.8 mm and 2.2 mm depending on application. The device serves primary commercial purposes in capillary blood sampling for point-of-care diagnostics, diabetes monitoring, and neonatal screening where needlestick injury prevention is mandatory. Single-use configurations dominate procurement volumes across Middle Eastern hospital systems due to infection control protocols, while blood collection applications generate premium pricing in South African private laboratories. Diabetes management represents the fastest-expanding application segment as Gulf states experience rising metabolic disease prevalence.
Saudi FDA device registration requirements and South African Health Products Regulatory Authority standards enforce needlestick safety compliance, while WHO prequalification pathways shape tender eligibility for public sector procurement across the region. Egypt's medical device import regulations and the UAE's Ministry of Health and Prevention conformity assessment schemes further fragment market access requirements. Stakeholders must monitor evolving national procurement centralization initiatives and harmonization pressures between Gulf Cooperation Council regulatory frameworks.
Market Dynamics
Gulf Cooperation Council procurement centralization is compressing supplier margins while Egyptian and Nigerian laboratory expansion creates volume pull for safety-engineered devices. Saudi SFDA registration timelines and UAE MOHAP conformity assessments now determine market access viability.
Growth Catalysts
- SFDA Medical Device Registration:Saudi Arabia's tightened safety lancet standards are filtering out non-compliant suppliers and consolidating procurement toward certified manufacturers.
- Neonatal Screening Programs:Expanded national screening mandates across Egypt and South Africa are generating dedicated demand for calibrated-depth safety lancets in pediatric settings.
- GCC Hospital Network Consolidation:Large-scale group purchasing organizations in the United Arab Emirates and Qatar are standardizing on single-use safety-engineered devices.
Market Restraints
- Medical-Grade ABS Plastic Input Volatility:Petrochemical feedstock price fluctuations are squeezing housing material costs for manufacturers serving price-sensitive African markets.
- Spring Mechanism Supply Concentration:Precision spring component production clusters in East Asian supplier bases create lead time vulnerability for MEA-assembled devices.
- Reusable Lancet Substitution:Cost-conscious diabetes patients in lower-income segments continue using traditional lancets with manual sterilization despite injury risk.
Strategic Opportunities
- Nigerian Diagnostic Laboratory Chains:Private pathology network expansion in Lagos and Abuja offers first-mover positioning for safety lancet bundle suppliers.
- WHO Prequalification Pathway:Alignment with WHO procurement eligibility standards unlocks public sector tenders across multiple African ministries of health.
- Blood Glucose Monitoring Convergence:Integration of safety lancets with connected meter ecosystems is creating differentiated positioning in Gulf diabetes management portfolios.
Industry Challenges
- Biocompatibility Testing Timelines:Extended ISO 10993 evaluation periods for new needle coatings are delaying product launches in competitive tenders.
- Legacy Inventory System Integration:Hospital ERP platforms across South African private networks require custom API development for automated safety lancet reordering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Safety Lancet Market |
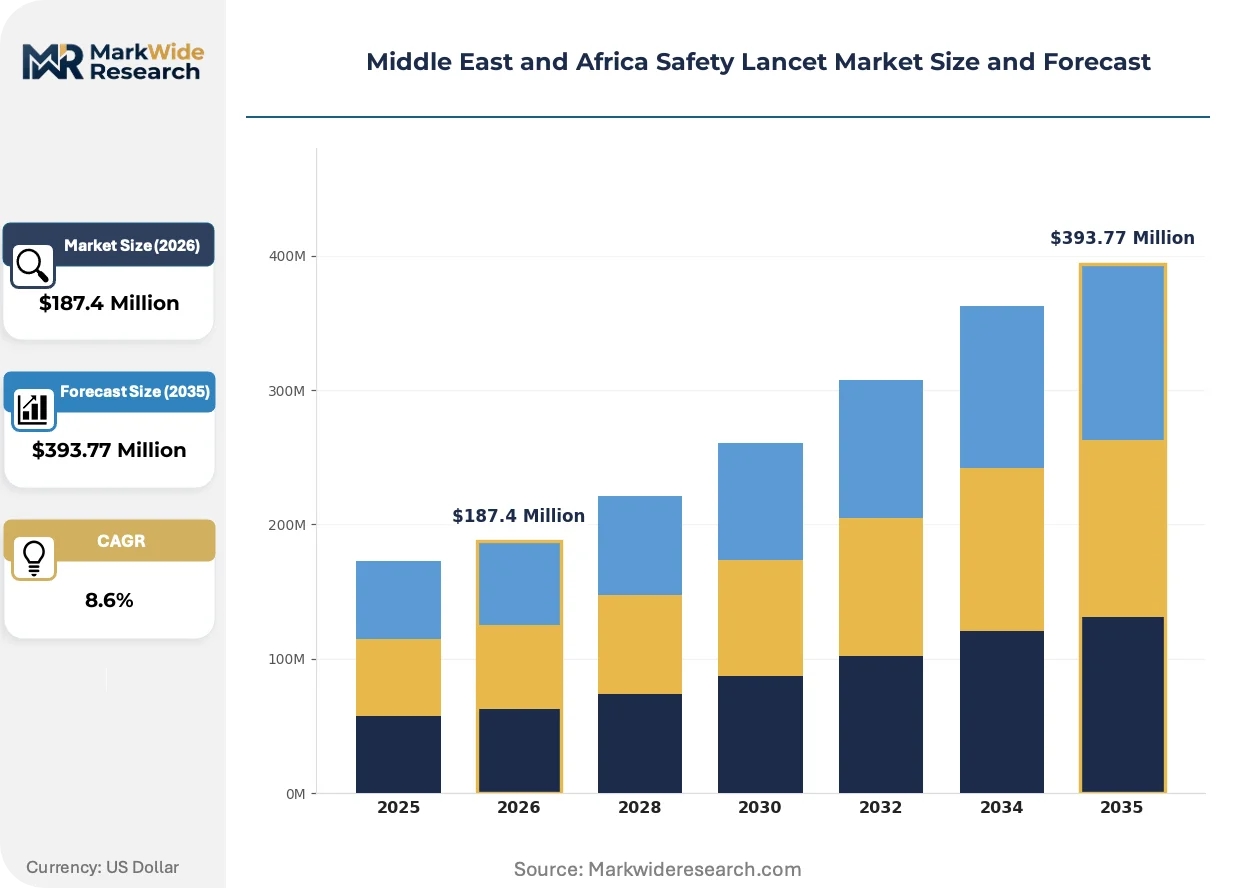
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Multi-Use, Safety-Syringe, Blood Collection End User: Hospitals, Clinics, Laboratories, Homecare Application: Vaccination, Blood Testing, Diabetes Management, Infusion Therapy Distribution Channel: Online, Pharmacies, Medical Supply Stores, Direct Sales |
| Companies Covered | Cardinal Health, B. Braun SE, BD, SARSTEDT AG & Co. KG, Roche Diagnostics, HTL-STREFA, Terumo Medical Corporation, Medtronic, Abbott, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Safety Lancet Market Evolving Landscape
Active needle retraction mechanisms and connected diagnostics are redefining device value propositions across Middle Eastern and African healthcare systems. Procurement stakeholders now prioritize injury-prevention certification and data integration capabilities.
Silicone-coated needle surfaces are integrating into premium safety lancet designs to reduce penetration force variance and improve patient comfort during capillary sampling. Saudi Arabia's Ministry of Health is adopting these configurations for national diabetes screening programs. The technology is integrating with automated inventory management systems that track activation events and predict replenishment cycles.
SFDA's 2023 medical device technical documentation requirements are mandating clinical evidence packages for all new safety lancet registrations in Saudi Arabia. Manufacturers must now submit biocompatibility studies and usability testing data that previously applied only to higher-risk device classes. South African private hospital groups are accelerating supplier qualification processes to meet these documentation standards ahead of GCC tender deadlines.
Diagnostic laboratory chains in Nigeria and Egypt are consolidating purchasing decisions at regional hub level rather than individual facility procurement. Group procurement officers now negotiate multi-year safety lancet supply agreements with penalty clauses for stockout events. This concentration is most visible in Lagos and Cairo metropolitan laboratory networks where three distributors now control eighty percent of safety-engineered device flows.
Middle East and Africa Safety Lancet Market Segmentation
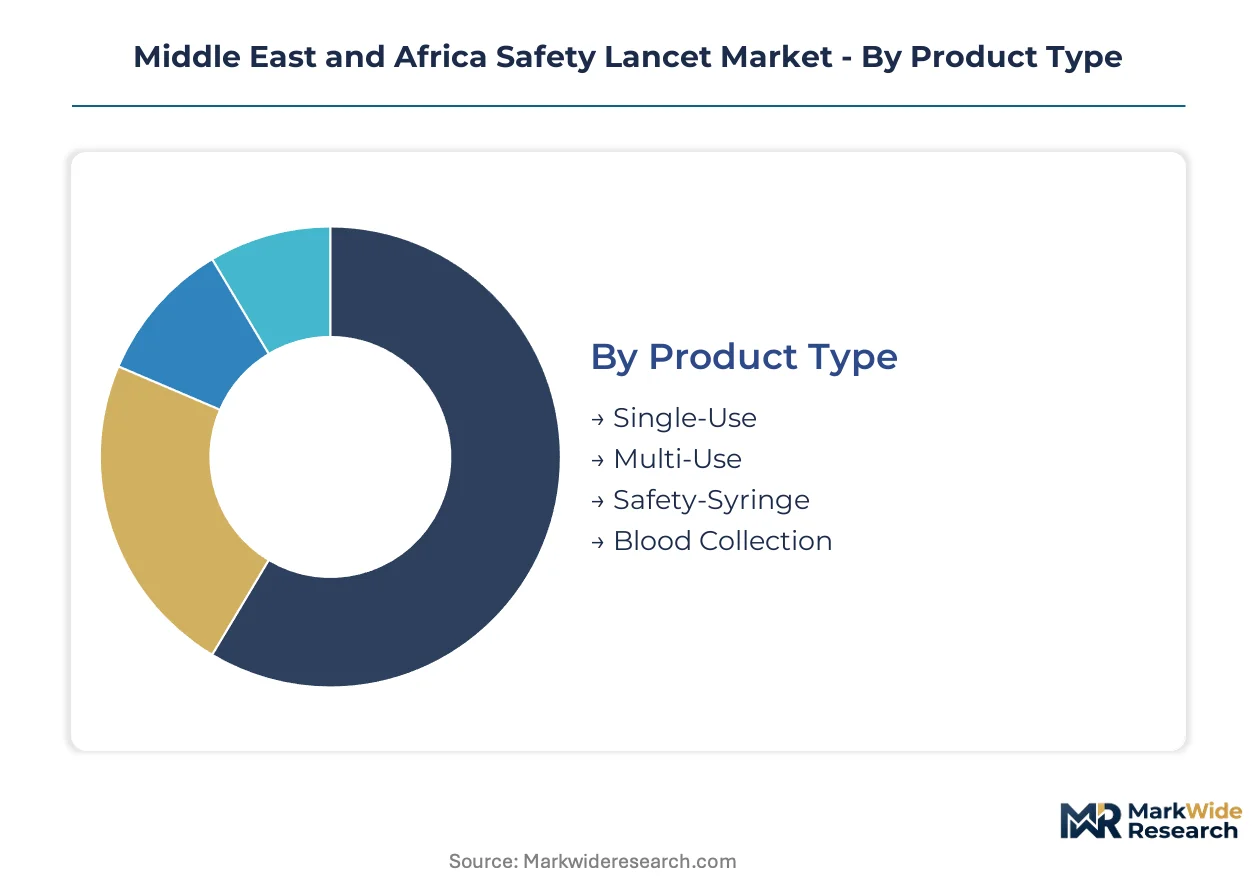
Procurement stakeholders across Middle Eastern and African healthcare systems prioritize different device attributes based on clinical setting, regulatory environment, and patient population. Segment-level differentiation determines supplier positioning in tender processes and private network negotiations.
Product Type:
Cost sensitivity and infection control protocols diverge sharply between institutional buyers and individual consumers across the region.
- Single-Use:Spring-loaded retraction mechanisms with ABS plastic housings and calibrated penetration depths between 0.8 mm and 2.2 mm dominate hospital procurement in Saudi Arabia and the United Arab Emirates. GCC group purchasing organizations mandate these configurations for needlestick injury compliance, though petrochemical feedstock volatility squeezes manufacturer margins in price-sensitive African markets.
- Blood Collection:Premium silicone-coated needle surfaces reduce penetration force variance for capillary sampling in South African private laboratories and Egyptian diagnostic chains. These devices command higher unit economics in laboratory tenders where sample quality consistency determines contract renewal.
- Multi-Use:Manual sterilization protocols persist among cost-conscious diabetes patients in Nigeria and lower-income Egyptian segments despite SFDA and SAHPRA safety guidance.
- Safety-Syringe:Integrated needle retraction designs serve specialized infusion therapy applications in Qatar's tertiary hospital networks.
Volume sits with Single-Use configurations; growth tilts toward Blood Collection as laboratory networks consolidate purchasing across Lagos and Cairo metropolitan hubs.
End User:
Procurement sophistication varies from centralized ministry tenders to fragmented retail pharmacy channels.
- Hospitals:Saudi Arabia's Ministry of Health and UAE Ministry of Health and Prevention enforce conformity assessment schemes that filter supplier pools to certified manufacturers. Large-scale network consolidation in Dubai and Abu Dhabi creates multi-year supply agreements with automated reordering clauses.
- Laboratories:Nigerian diagnostic chains in Lagos and Abuja are consolidating purchasing decisions at regional hub level, with three distributors now controlling the majority of safety-engineered device flows. Group procurement officers negotiate penalty clauses for stockout events.
- Clinics:Outpatient facilities across Egypt's healthcare infrastructure expansion zones source through mixed direct sales and pharmacy channels.
- Homecare:Individual diabetes patients in lower-income segments substitute reusable lancets despite injury risk, constraining premium safety device penetration.
Procurement concentration favors Hospitals; expansion is steepest in Laboratories as private pathology networks scale.
Application:
Clinical workflow integration determines device specification requirements and bundling opportunities.
- Diabetes Management:Connected meter ecosystems integrating safety lancets with data platforms are gaining traction in Gulf state metabolic disease programs. Saudi Arabia's national screening initiatives adopt silicone-coated configurations for patient comfort compliance.
- Blood Testing:Capillary sampling for point-of-care diagnostics drives standardized procurement across South African private hospital networks requiring ISO 10993 biocompatibility documentation.
- Vaccination:Mass immunization campaigns in Egypt and Nigeria generate volume demand for basic safety-engineered configurations.
- Infusion Therapy:Specialized calibrated-depth devices serve neonatal screening programs with expanded mandates across Egypt and South Africa.
Diabetes Management captures premium positioning; Blood Testing anchors procurement volume in laboratory network tenders.
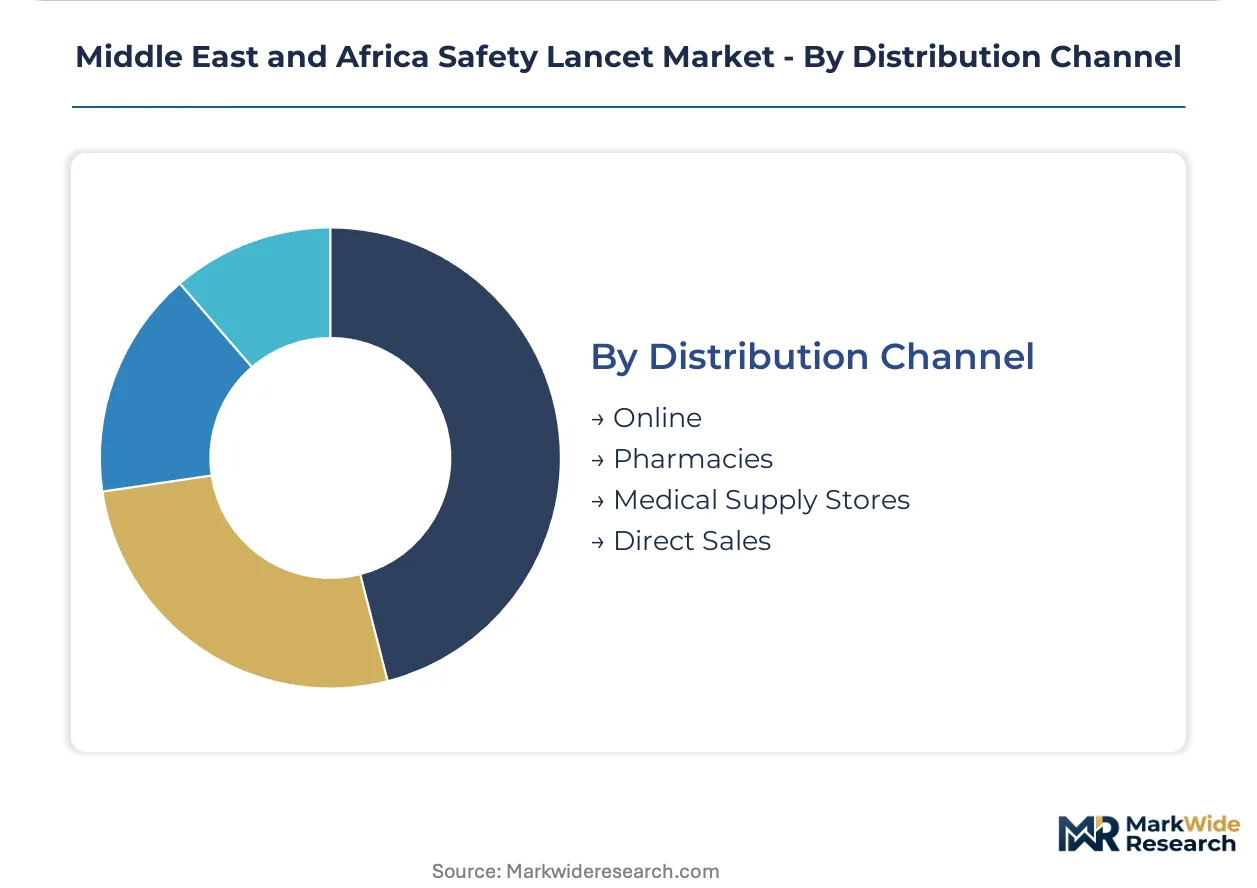
Distribution Channel:
Channel selection reflects buyer scale, urgency requirements, and regulatory documentation needs.
- Direct Sales:Cardinal Health and B. Braun SE anchor supply contracts with large hospital networks through dedicated account management and ERP integration services. Custom API development supports automated safety lancet reordering in South African private networks.
- Medical Supply Stores:Regional distributors control device flows to mid-tier clinics and smaller laboratories across Nigeria's expanding diagnostic infrastructure.
- Pharmacies:Retail channels serve individual diabetes patients and small clinic replenishment in fragmented Egyptian and Nigerian markets.
- Online:E-procurement platforms are emerging for standardized safety lancet configurations in UAE and Saudi Arabian healthcare system digitization initiatives.
Direct Sales commands institutional volume; Medical Supply Stores are gaining share fastest as regional laboratory hubs consolidate purchasing authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for safety lancets remains anchored in European and East Asian supplier bases, while consumption gravity centers on Gulf hospital networks and South African laboratory chains. The Middle East and Africa region imports finished devices and precision spring components, with local assembly operations scaling in Egypt and Morocco to serve price-sensitive African markets.
Saudi Arabia
SFDA medical device registration timelines now determine supplier viability, with tightened technical documentation requirements filtering procurement toward certified manufacturers. The Ministry of Health mandates silicone-coated safety lancets for national diabetes screening programs. Riyadh and Jeddah hospital networks consolidate purchasing through centralized tenders, compressing margins for non-compliant vendors.
United Arab Emirates
MOHAP conformity assessment schemes enforce needlestick safety compliance across Dubai and Abu Dhabi hospital systems. Large-scale group purchasing organizations standardize on single-use configurations with automated reordering clauses. The Dubai Healthcare City cluster anchors distribution infrastructure serving GCC markets.
South Africa
SAHPRA standards and ISO 10993 biocompatibility documentation requirements shape private laboratory procurement. Lagos and Cape Town metropolitan pathology networks negotiate multi-year supply agreements with penalty clauses for stockout events. Three distributors now control the majority of safety-engineered device flows to diagnostic chains.
Egypt
Healthcare infrastructure investments and expanded neonatal screening mandates generate dedicated demand for calibrated-depth pediatric devices. Medical device import regulations fragment market access, while local assembly operations scale to serve North African price points. Cairo laboratory hubs consolidate purchasing authority at regional level.
Nigeria
Private diagnostic chains in Lagos and Abuja offer first-mover positioning for safety lancet bundle suppliers. WHO prequalification pathways unlock public sector tender eligibility for ministry of health procurement. Regional distributors control device flows to mid-tier clinics through pharmacy and medical supply store channels.
Middle East and Africa Safety Lancet Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated diabetes management portfolios. Procurement concentration in Gulf hospital networks favors suppliers with dedicated account management and ERP integration capabilities. Two strategic archetypes dominate: full-line diabetes care providers bundling lancets with meters and data platforms, and precision device specialists manufacturing safety-engineered components at scale. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure spring mechanism supply and biocompatibility certification.
Among diversified health technology groups, Cardinal Health, B. Braun SE, and BD occupy positions exemplifying the full-line and precision manufacturing archetypes. Cardinal Health leverages distribution infrastructure to anchor supply contracts with large hospital networks. B. Braun SE represents European-based manufacturing scale for safety-engineered devices. BD sits within the integrated diabetes management tier, bundling lancets with connected meter ecosystems. These three entities collectively illustrate how procurement centralization across Saudi Arabia and the UAE rewards suppliers combining regulatory certification with logistics integration.
| Leading Market Players |
|---|
| Cardinal Health |
| B. Braun SE |
| BD |
| SARSTEDT AG & Co. KG |
| Roche Diagnostics |
| HTL-STREFA |
| Terumo Medical Corporation |
| Medtronic |
| Abbott |
| Others |
Value Network & Pricing Analysis
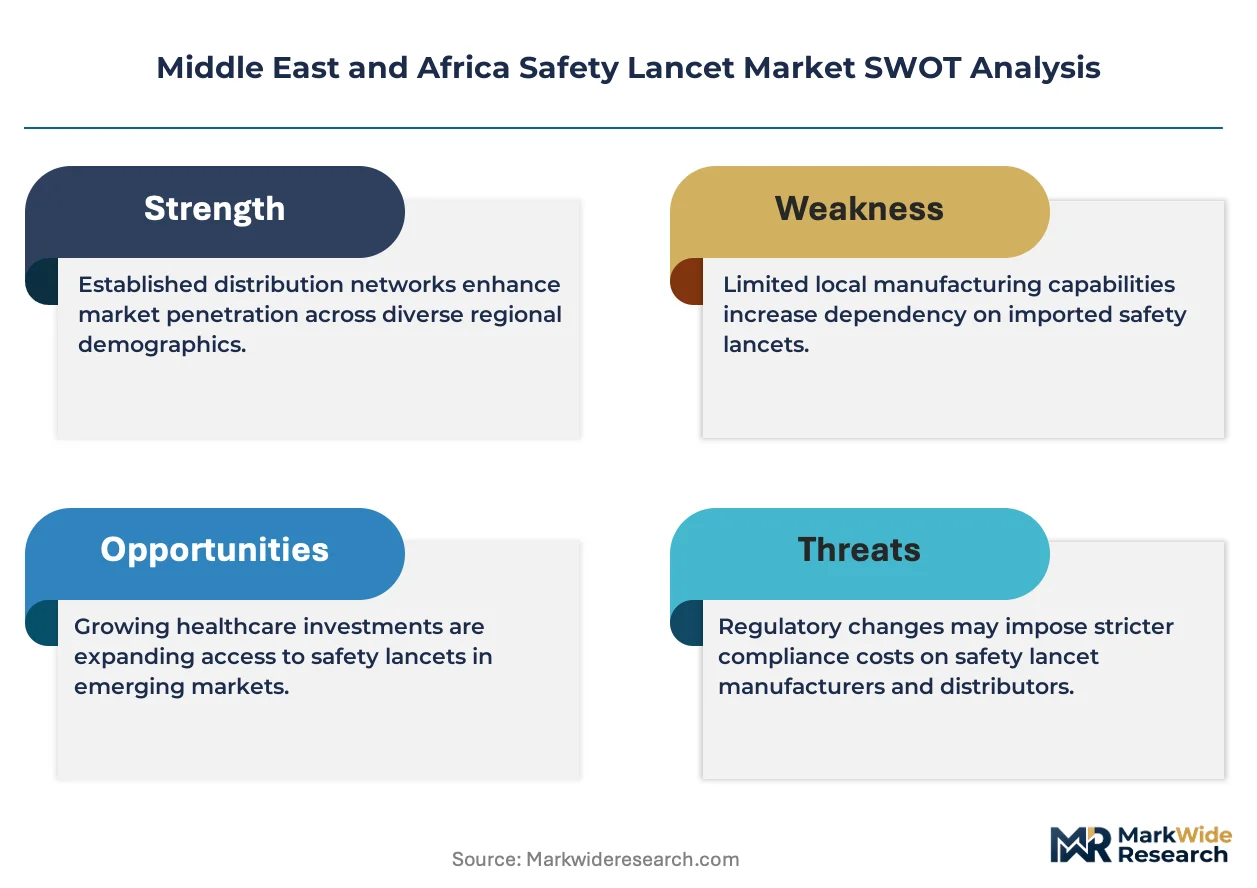
Petrochemical feedstock price indices cascade through medical-grade ABS plastic housing costs, fragmenting pricing power across Middle Eastern hospital procurement tiers and African laboratory networks. GCC group purchasing organizations leverage volume concentration to compress supplier margins, while Egyptian and Nigerian buyers absorb upstream volatility through shorter contract durations and mixed sourcing strategies.
Pricing Analysis
Cost-down pressure on economy-tier devices accelerates because petrochemical input volatility squeezes manufacturers serving price-sensitive African markets. Three-tier pricing structure across premium silicone-coated, standard spring-retraction, and economy basic configurations stratifies by ISO 10993 biocompatibility certification grade and SFDA registration status. Procurement centralization in Saudi Arabia and the UAE intensifies margin compression through multi-year tender aggregation. Homecare diabetes patients in lower-income segments exhibit highest price sensitivity, while South African private laboratories accept premium positioning for sample quality consistency.
Supply Chain Analysis
SFDA and SAHPRA certification requirements gate supplier participation, filtering device flows toward manufacturers with documented biocompatibility testing and usability validation. Manufacturing concentration rests on Germany, China, and Malaysia for precision spring mechanisms and medical-grade plastic housings. Raw material dependencies draw from East Asian petrochemical feedstocks, Japanese stainless steel needle stock, and European silicone coating formulations. Single-source vulnerability concentrates in precision spring component production clusters. Distribution runs through Cardinal Health and B. Braun SE anchored logistics networks serving GCC hospital systems, with regional distributors controlling Nigerian and Egyptian laboratory flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where spring mechanism supply security and biocompatibility certification speed determine competitive endurance. Players pursue backward integration into precision component manufacturing or downstream control through hospital ERP system embedding.
For Market Incumbents: Anchor procurement relationships through dedicated account management and automated inventory API integration with South African private hospital networks. Defend against emerging Asian manufacturers by accelerating SFDA registration timelines and securing multi-year GCC group purchasing organization contracts. Prioritize captive supply of precision spring components to insulate against East Asian lead time volatility. For New Entrants and Emerging Players: Silicone-coated needle surface technology offers entry positioning into Saudi national diabetes screening tenders where patient comfort specifications create differentiation headroom. Target Nigerian diagnostic laboratory chains in Lagos and Abuja through WHO prequalification pathway alignment and regional hub-level contract negotiation. Pursue bundle configurations pairing safety lancets with blood glucose monitoring consumables to bypass entrenched distribution relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap manufacturers with existing SFDA registrations and underutilized Egyptian assembly capacity amid petrochemical margin compression. Long-term viability hinges on consolidation plays that combine certification assets with Gulf distribution infrastructure. Watch for SFDA technical documentation requirement expansion as inflection signal for regulatory compliance cost escalation and supplier pool contraction.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Compressed approval timelines filter procurement toward certified manufacturers in Saudi hospital tenders. |
| Spring Mechanism Backward Integration | Captive component supply insulates against East Asian production concentration and lead time vulnerability. |
| Hospital ERP System Embedding | Automated reordering API integration locks in replenishment cycles with South African private networks. |
| Silicone Coating Technology Investment | Reduced penetration force variance meets Saudi Ministry of Health patient comfort mandates. |
| WHO Prequalification Pathway Alignment | Procurement eligibility unlocks public sector tenders across multiple African ministries of health. |
Research Methodology
Independent corroboration across hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SFDA device registration databases, SAHPRA submission records, hospital tender documentation, and GCC trade flow data. Bottom-up segmentation modeling and top-down market sizing triangulate volume and value estimates.
Rate-of-change decomposition across product type, end user, application, and distribution channel dimensions structures the analytical framework. CAGRs derive from segment-level growth trajectory blending and cross-referencing against macro healthcare expenditure patterns. Modeled inputs incorporate diabetes prevalence projections, laboratory network expansion pipelines, and regulatory harmonization pressures between GCC frameworks.
Several conditions sit outside the modeled scope, including sudden petrochemical price spike events, GCC procurement centralization policy reversals, and reusable lancet substitution acceleration in lower-income segments. Forecasts reflect documented assumptions about regulatory timeline stability and spring component supply continuity. A model refresh is warranted upon material change in SFDA technical documentation requirements or WHO prequalification pathway criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Instrumentation Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Motion Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market