
 Industrial Gloves Market | 2026-2036
Industrial Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gloves Market Intelligence
Asset-light leasing models for automated glove dipping lines is tilting capital requirements toward contract manufacturers. Ansell leverages its integrated nitrile supply chain across Southeast Asian production hubs. Hartalega sustains cost leadership through proprietary thin-gauge manufacturing technology. Top Glove Corporation anchors volume supply to North American healthcare distributors.
Industrial gloves are engineered barrier devices constructed from elastomeric films or woven materials, typically measuring 4-8 mil in thickness for chemical protection and rated under ANSI/ISEA 105 for mechanical hazards, designed to prevent occupational dermal exposure and mechanical injury in hazardous work environments. The nitrile material segment dominates procurement volumes due to latex allergy migration and superior chemical permeation resistance against petroleum-based solvents. Disposable gloves command the largest revenue pool in food processing and cleanroom applications, while cut-resistant gloves with ANSI A6-A9 ratings represent the fastest-expanding margin tier as metal fabrication employers upgrade from leather to engineered fiber blends.
OSHA's 29 CFR 1910.138 hand protection standard mandates employer-conducted hazard assessments, while the EU's PPE Regulation 2016/425 requires CE marking with notified body intervention for Category III chemical-resistant gloves. The FDA enforces Quality System Regulation for medical-grade glove manufacturing under 21 CFR Part 820. Stakeholders must monitor evolving PFAS restrictions in fluoropolymer-coated gloves and calibrate material substitution roadmaps ahead of regulatory phase-out timelines.
Market Dynamics
OSHA's updated 29 CFR 1910.138 enforcement posture is compressing compliance timelines for chemical-resistant glove specification, forcing employers to accelerate hazard assessment cycles and retire legacy leather protection in favor of engineered barrier materials.
Growth Catalysts
- Semiconductor cleanroom expansion:Chemical-resistant nitrile glove demand accelerates in wafer fabrication facilities as process node shrinkage intensifies solvent exposure protocols.
- EU PPE Regulation 2016/425:CE marking mandates for Category III chemical-resistant gloves drive replacement cycles among European metal fabrication employers upgrading from leather to engineered fiber blends.
- Malaysia's Klang Valley concentration:Integrated nitrile supply chain clustering reduces logistics friction for contract manufacturers serving North American healthcare distributors.
Market Restraints
- Butadiene feedstock volatility:Synthetic rubber precursor price swings compress margin predictability for nitrile glove producers without captive petrochemical supply.
- Single-region production gravity:Southeast Asian manufacturing corridor concentration creates systemic disruption exposure from monsoon logistics interruptions or port congestion.
- PFAS regulatory phase-out timelines:Fluoropolymer-coated glove formulations face ECHA restriction proposals, forcing material substitution R&D before certified alternatives reach scale.
Strategic Opportunities
- India's BIS certification gap:Domestic industrial safety equipment standardization lags behind manufacturing output growth, creating first-mover positioning for compliant importers.
- Automated glove dipping line leasing:Asset-light contract manufacturing models reduce capital barriers for regional entrants seeking volume supply relationships.
- Thin-gauge nitrile technology convergence:Proprietary manufacturing processes enabling 3-4 mil thickness with retained chemical resistance open premium positioning in electronics assembly.
Industry Challenges
- ANSI/ISEA 105 certification bottlenecks:Third-party mechanical hazard testing backlog delays product launch timelines for cut-resistant glove innovators.
- Legacy ERP integration friction:Automated dipping line sensor networks require custom middleware development to connect with incumbent manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gloves Market |
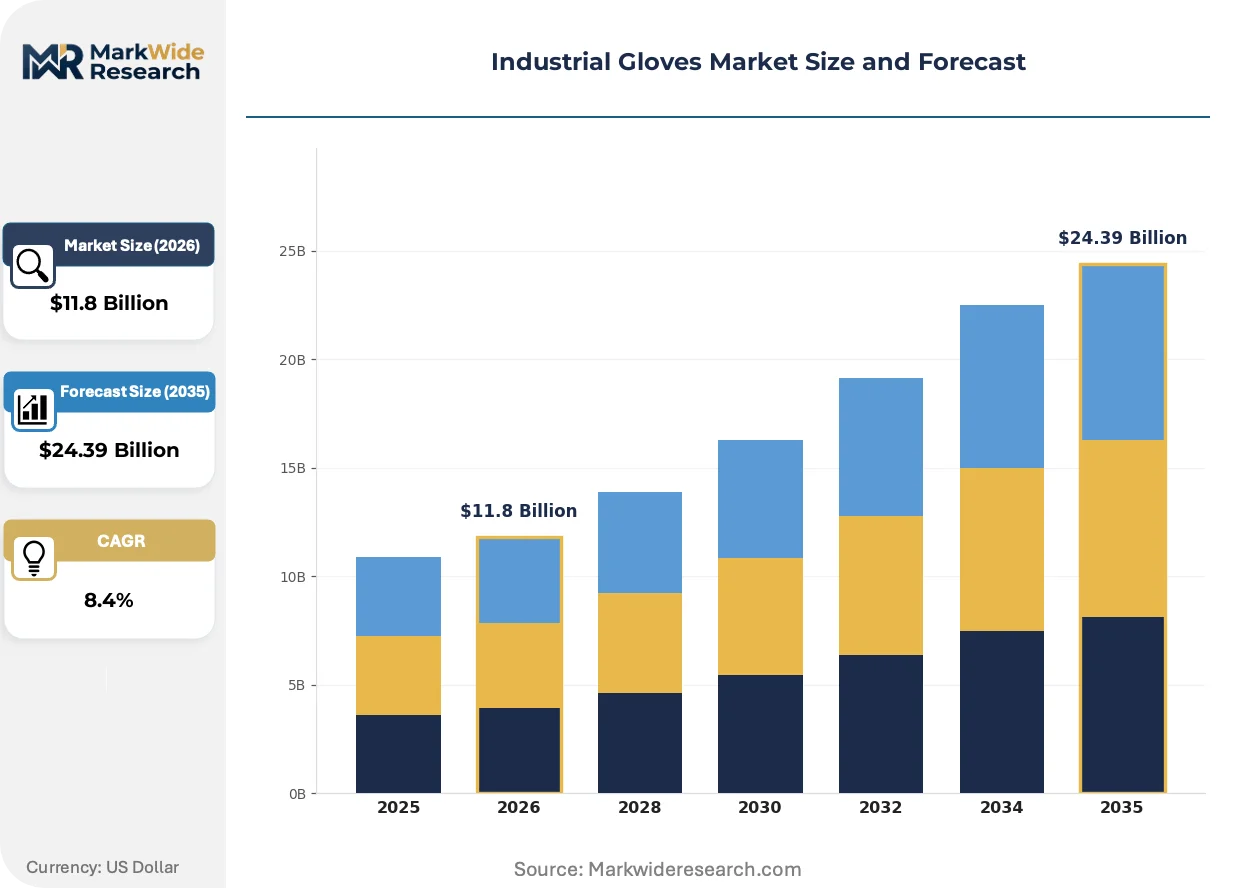
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Cut-resistant, Chemical-resistant, Leather End User: Manufacturing, Construction, Oil & Gas, Food Processing Material: Latex, Nitrile, Vinyl, Neoprene Application: Personal Protection, Cleanroom, Medical, Maintenance |
| Companies Covered | Ansell, Top Glove Corporation, Hartalega, 3M, Honeywell, MCR Safety, INTCO, Superior Glove, Showa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gloves Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory enforcement intensification are compressing product lifecycles while redistributing value capture toward integrated supply chain operators with in-house polymer compounding capabilities.
Water-based polyurethane coating technology is rendering obsolete solvent-borne fluoropolymer treatments in chemical-resistant glove production. Semiconductor fabrication facilities in South Korea and Taiwan are specifying these formulations for solvent-handling operations. The shift eliminates volatile organic compound exposure liabilities while maintaining permeation resistance against petroleum-based chemicals.
REACH restriction proposals on per- and polyfluoroalkyl substances are forcing reformulation roadmaps across European chemical-resistant glove portfolios. Manufacturers with advance PFAS-free certification are securing preferred supplier status with German automotive OEMs. The regulatory pressure is compressing substitution timelines from typical five-year material qualification cycles to eighteen-month compliance deadlines.
Direct procurement relationships between institutional buyers and integrated manufacturers are displacing layered distribution networks in North American healthcare supply. Group purchasing organizations are consolidating vendor panels around producers with captive nitrile supply and FDA 21 CFR Part 820 quality system documentation. This channel consolidation is most visible in surgical glove categories, where distributor markups face sustained compression from volume-direct contracting models.
Industrial Gloves Market Segmentation
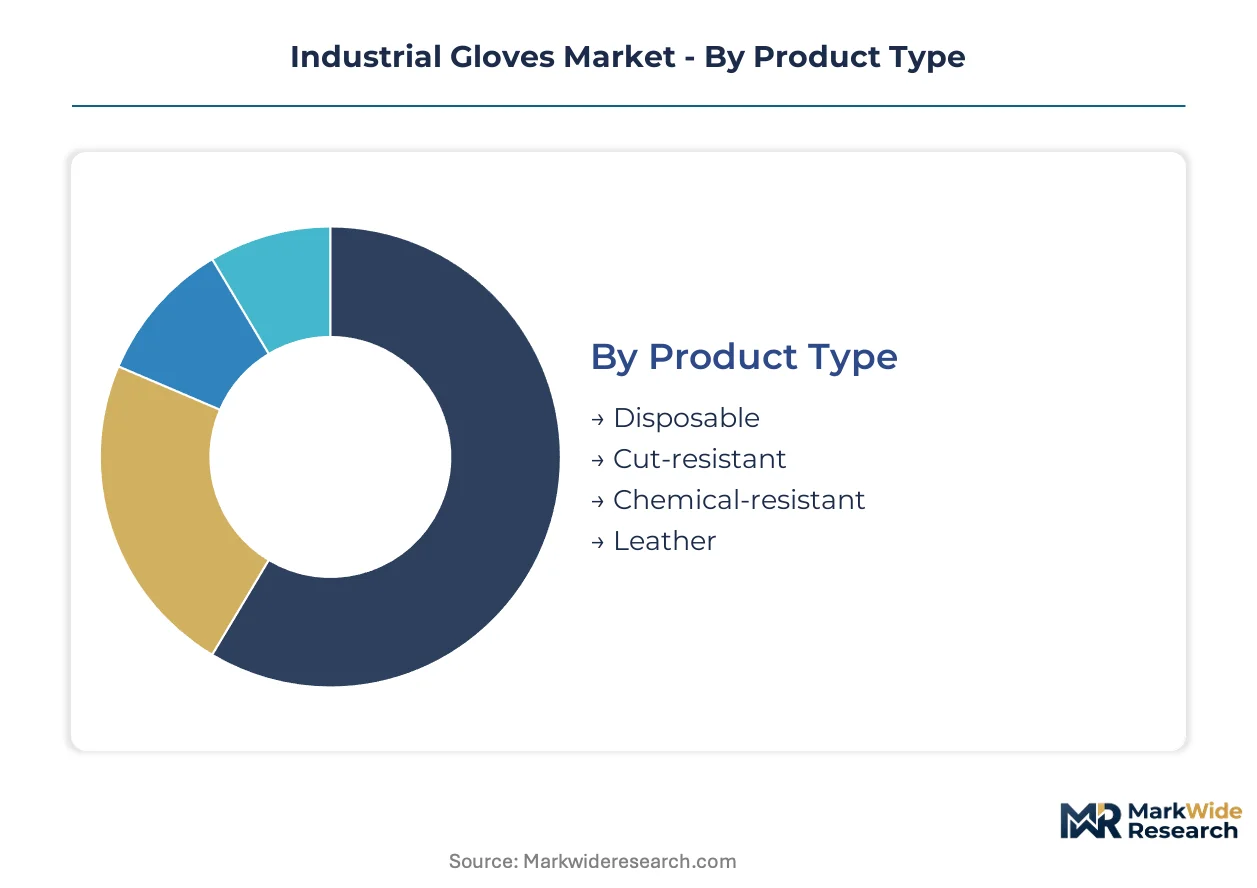
Industrial glove procurement patterns diverge sharply across use environments, with specification requirements for chemical permeation resistance, mechanical hazard ratings, and contamination control creating distinct product-service bundles. Segmentation clarity enables suppliers to align manufacturing assets with demand pockets that reward technical differentiation over commodity volume.
Product Type:
Mature categories dominate revenue tonnage while emerging formats capture specification premiums in regulated environments.
- Disposable:Single-use nitrile and latex barriers, typically 3-8 mil thickness, serve food processing lines and medical examination protocols where cross-contamination protocols mandate frequent changeouts. Malaysian Klang Valley producers anchor supply to North American healthcare distributors under FDA 21 CFR Part 820 quality mandates.
- Cut-resistant:Engineered fiber blends with ANSI A6-A9 ratings replace legacy leather in metal fabrication shops facing OSHA 29 CFR 1910.138 compliance deadlines. German automotive OEMs specify these for stamped component handling where laceration risk exceeds leather protection thresholds.
- Chemical-resistant:Elastomeric formulations rated for permeation resistance against petroleum solvents and acids.
- Leather:Traditional hide-based protection for low-hazard material handling and welding operations.
Disposable handles the majority of throughput; cut-resistant is the fastest mover on share.
End User:
Cost tier stratification separates specification-intensive buyers from price-sensitive volume purchasers.
- Manufacturing:Metal fabrication, electronics assembly, and semiconductor wafer facilities require multi-glove portfolios spanning cut, chemical, and cleanroom categories. South Korean foundries specify thin-gauge nitrile for solvent-handling at sub-5 mil thickness.
- Construction:General contractors and specialty trades balance mechanical hazard protection with dexterity for tool manipulation.
- Oil & Gas:Upstream and downstream operations demand chemical-resistant formulations for hydrocarbon exposure.
- Food Processing:High-volume disposable consumption driven by HACCP contamination control protocols.
Manufacturing commands the deepest specification requirements; food processing generates the highest unit velocity.
Material:
Supply concentration around nitrile feedstocks is redistributing margin capture toward integrated polymer compounders.
- Nitrile:Acrylonitrile-butadiene copolymer dominates procurement volumes due to latex allergy migration and superior chemical resistance against petroleum-based solvents. Malaysian producers with captive butadiene supply sustain cost leadership.
- Latex:Natural rubber formulations retain share in surgical and examination applications where tactile sensitivity remains paramount.
- Vinyl:Polyvinyl chloride offers lowest-cost barrier protection for low-risk food service and janitorial tasks.
- Neoprene:Chloroprene rubber serves specialty chemical resistance against acids and caustics.
Nitrile handles the majority of throughput; neoprene is climbing the fastest on specification premiums.
Application:
Volume concentrates in personal protection while margin accumulates in contamination-controlled environments.
- Personal Protection:General industrial safety applications across manufacturing and construction sites where OSHA hazard assessments mandate hand protection.
- Cleanroom:Ultra-low particulate nitrile gloves for semiconductor fabrication and pharmaceutical aseptic processing. Taiwan and South Korean wafer facilities specify water-based polyurethane coatings eliminating solvent-borne fluoropolymer VOC liabilities.
- Medical:Surgical and examination gloves under FDA enforcement of 21 CFR Part 820 quality systems.
- Maintenance:Repair and facility upkeep operations requiring durable mechanical and chemical protection.
Personal protection generates the highest unit volumes; cleanroom is gaining share fastest on node shrinkage intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA's updated enforcement posture and the EU's PPE Regulation 2016/425 are accelerating specification upgrades across manufacturing corridors. Malaysia's integrated nitrile supply chain anchors cost-competitive production for North American healthcare distributors.
United States
Semiconductor wafer fabrication in Arizona and Texas drives chemical-resistant nitrile procurement as process nodes shrink below 3nm. OSHA's 29 CFR 1910.138 mandates compress hazard assessment cycles for metal fabrication employers. The Southeast manufacturing corridor spanning Georgia and Tennessee sees cut-resistant glove upgrades in automotive stamping operations.
Germany
Automotive OEMs specify PFAS-free chemical-resistant gloves ahead of ECHA restriction timelines. REACH compliance deadlines force eighteen-month substitution cycles versus traditional five-year qualifications. The Ruhr industrial basin concentrates demand for engineered fiber blends in metal fabrication and machinery assembly.
China
Electronics assembly in the Yangtze River Delta specifies thin-gauge nitrile below 4 mil thickness for solvent-handling precision. The country's national standards body accelerates industrial safety equipment certification alignment with international norms. Shenzhen and Dongguan clusters integrate water-based polyurethane coating lines for cleanroom applications.
South Korea
Foundry expansion by Samsung and SK Hynix intensifies cleanroom glove consumption for sub-5nm wafer processing. MFDS enforcement of medical device quality systems extends to glove manufacturing for pharmaceutical exports. The Pyeongtaek semiconductor complex anchors premium nitrile procurement volumes.
Malaysia
Klang Valley producers leverage captive butadiene supply to sustain cost leadership in nitrile glove exports. The national industrial standards agency aligns BIS-equivalent certification with ASEAN harmonization initiatives. Port Klang logistics corridors reduce friction for contract manufacturers serving North American group purchasing organizations.
Industrial Gloves Market Key Industry Players
On the supply side, the industry is consolidating around integrated polymer compounders with captive nitrile supply chains. Malaysian producers with backward integration into butadiene feedstocks capture margin from contract manufacturers dependent on spot market purchasing. Three archetypes dominate: integrated Southeast Asian compounders, North American specification specialists, and European regulatory compliance leaders. Capacity expansion and technology licensing represent the dominant competitive vectors as players race to qualify PFAS-free formulations ahead of regulatory deadlines.
Within the integrated Southeast Asian tier, Top Glove Corporation and Hartalega exemplify scale-driven positioning through Klang Valley production clustering. Ansell occupies a position bridging integrated supply chain control with North American healthcare distribution relationships. These three anchors represent divergent strategic postures: volume leadership through geographic concentration, cost leadership through proprietary thin-gauge processes, and margin capture through quality system documentation for FDA-regulated channels.
| Leading Market Players |
|---|
| Ansell |
| Top Glove Corporation |
| Hartalega |
| 3M |
| Honeywell |
| MCR Safety |
| INTCO |
| Superior Glove |
| Showa Group |
| Others |
Cost & Logistics Intelligence
Malaysian Klang Valley concentration of butadiene-to-nitrile production anchors cost leadership for integrated compounders while contract manufacturers absorb feedstock volatility through spot market exposure. This upstream clustering concentrates margin capture with producers possessing captive petrochemical supply, compressing pricing power for assemblers lacking backward integration.
Pricing Analysis
Certification level creates the primary spread between FDA 21 CFR Part 820 medical-grade premiums and general industrial commodity tiers. Three-tier pricing structure separates surgical-grade nitrile from standard chemical-resistant formulations from economy vinyl alternatives. Pricing pressure stems from butadiene feedstock volatility squeezing non-integrated producers. Food processing buyers exhibit highest price sensitivity due to volume velocity and low switching costs, while semiconductor cleanroom specifications tolerate premium positioning for contamination control assurance.
Supply Chain Analysis
Export-control scrutiny on advanced polymer compounding equipment limits technology transfer to emerging production regions, constraining supply expansion outside established manufacturing corridors. Malaysia, Thailand, and Indonesia anchor global nitrile glove output through integrated petrochemical feedstocks. Raw material dependencies center on acrylonitrile, butadiene, and polymerization catalysts. Single-region concentration creates systemic disruption exposure from monsoon logistics interruptions. Distribution runs through group purchasing organizations consolidating vendor panels around quality-documented producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PFAS regulatory phase-out timelines and REACH restriction proposals are compressing material qualification cycles from five years to eighteen months, creating winner-take-most dynamics for compliant producers. This regulatory inflection favors integrated compounders with in-house R&D capabilities over contract assemblers.
For Market Incumbents: Build regulatory compliance moats through PFAS-free certification ahead of ECHA enforcement deadlines. Secure captive butadiene supply through petrochemical partnerships or upstream acquisitions to insulate margins from feedstock volatility. Ansell's integrated nitrile positioning and Hartalega's proprietary thin-gauge technology exemplify defensible differentiation against commodity contract manufacturers. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification gap where domestic industrial safety standardization lags manufacturing output growth. Target automated glove dipping line leasing models to reduce capital barriers for regional volume supply relationships. Pursue water-based polyurethane coating partnerships with South Korean and Taiwanese semiconductor foundries seeking PFAS-free alternatives. For Investors and Strategic Acquirers: Capital is best deployed toward integrated Southeast Asian compounders with captive feedstock and FDA quality system documentation. The long-term viability window favors producers with demonstrated PFAS-free formulation scale and direct procurement relationships with North American healthcare group purchasing organizations. Monitor ECHA restriction proposal finalization as the critical inflection signal for substitution timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Formulation Certification | ECHA REACH compliance secures preferred supplier status with German automotive OEMs ahead of restriction deadlines. |
| Backward Integration into Butadiene | Captive petrochemical supply insulates Malaysian producers from synthetic rubber precursor price volatility. |
| Thin-Gauge Nitrile Technology Scale-Up | Proprietary 3-4 mil manufacturing processes open premium positioning in South Korean semiconductor cleanrooms. |
| Automated Dipping Line Leasing Models | Asset-light contract manufacturing reduces capital barriers for regional entrants seeking volume supply relationships. |
| Direct Procurement Channel Development | Bypassing distributor markups through GPO volume-direct contracting compresses channel costs for FDA-documented producers. |
Research Approach
The analysis maps disposable, cut-resistant, chemical-resistant, and leather glove categories, each validated through procurement directors at metal fabrication facilities, semiconductor cleanroom managers, and FDA quality system auditors. Primary interviews with plant engineers, GPO contracts managers, and polymer compounding specialists combined with secondary validation from OSHA enforcement records, FDA 21 CFR Part 820 inspection databases, and ECHA REACH restriction proposals. Bottom-up production capacity modeling and top-down end-use demand estimation provided triangulation across the analysis window.
Assumptions held fixed include OSHA 29 CFR 1910.138 enforcement posture, EU PPE Regulation 2016/425 CE marking requirements, and Malaysian Klang Valley production clustering. Segmentation dimensions modeled span product type, material formulation, end-use industry, and application environment across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating semiconductor wafer fabrication expansion rates and automotive stamping output forecasts.
Macroeconomic conditions sit as an overlay; deviation in butadiene feedstock pricing, Southeast Asian logistics disruption frequency, or PFAS regulatory acceleration would shift the trajectory. Material shifts in ECHA restriction timeline finalization or OSHA enforcement resource allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Hearing Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Power Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market