
 Decanoyl Chloride Market | 2026-2036
Decanoyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Decanoyl Chloride Market Analytics
China's Jiangsu and Shandong provinces is narrowing the historical supply gap for C10 acyl chlorides in Asia-Pacific. Seqens leverages its European integrated acyl chloride platform to sustain pharmaceutical-grade output across multiple sites. Shanghai Mayao Chemical anchors regional distribution through dedicated intermediate supply contracts with domestic agrochemical formulators.
Decanoyl chloride, a ten-carbon saturated fatty acid chloride with molecular formula C10H19ClO, functions primarily as an acylation reagent in organic synthesis and intermediate manufacturing for active pharmaceutical ingredients, agrochemicals, and personal care compounds; industrial-grade material typically assays at 98% minimum purity and requires moisture-free handling due to hydrolytic sensitivity. Pharmaceutical-grade demand leads value generation as CDSCO and FDA-aligned purity protocols tighten acceptable impurity profiles for acyl chloride precursors. Cosmetic-grade volumes expand fastest from peptide synthesis and surfactant derivatization in South Korean and Chinese personal care manufacturing.
EPA oversight of chlorinated intermediate emissions shapes North American production economics, while REACH registration requirements in Europe govern import volumes and substitution incentives for acyl chloride derivatives. China's MEE enforces wastewater discharge limits on thionyl chloride-based manufacturing routes, pushing producers toward alternative chlorination technologies. Stakeholders must monitor regulatory divergence between FDA-aligned purity standards and emerging GB standard revisions in China to align capacity investments with compliant demand pools.
Market Dynamics
Pharmaceutical-grade purity mandates from CDSCO and FDA-aligned regulators are compressing acceptable impurity tolerances for acyl chloride intermediates, forcing producers to upgrade chlorination infrastructure and analytical capabilities.
Growth Catalysts
- API synthesis expansion:Indian formulators are scaling bulk intermediate output for export markets, driving procurement of high-assay C10 acyl chlorides from Gujarat's chemical corridor.
- REACH registration compliance:European pharmaceutical manufacturers require documented supply chain transparency for acyl chloride precursors, favoring registered producers with ECHA-aligned dossiers.
- Peptide surfactant demand:South Korean and Chinese personal care manufacturers are expanding decanoyl chloride derivatization for cosmetic-grade peptide synthesis.
Market Restraints
- Thionyl chloride input volatility:SOCl2 price swings and supply interruptions from Chinese producers directly transmit to decanoyl chloride manufacturing economics.
- Jiangsu-Shandong supply concentration:Asia-Pacific C10 acyl chloride capacity clusters in two Chinese provinces, creating geographic vulnerability to MEE environmental enforcement actions.
- Green solvent substitution:Bio-based acylation reagents from enzymatic catalysis are encroaching on cosmetic-grade applications with lower carbon footprint credentials.
Strategic Opportunities
- Agrochemical intermediate channel:Shanghai Mayao Chemical's dedicated supply contracts with domestic formulators demonstrate viable distribution innovation bypassing traditional merchant chemical houses.
- Dual-use pharmaceutical-cosmetic grade:Producers achieving simultaneous CDSCO and MFDS cosmetic compliance can access premium pricing across both end-use pools.
- Alternative chlorination technology:Phosgene-free and catalytic chlorination routes offer regulatory tailwind as China's MEE tightens wastewater discharge limits on legacy thionyl chloride processes.
Industry Challenges
- Analytical chemistry talent scarcity:Pharmaceutical-grade production requires specialists in GC-MS impurity profiling and ICP-MS elemental analysis, skills concentrated at Seqens and limited contract research organizations.
- Multi-jurisdiction certification timelines:Simultaneous FDA, CDSCO, and NMPA active pharmaceutical ingredient precursor approvals extend commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Decanoyl Chloride Market |
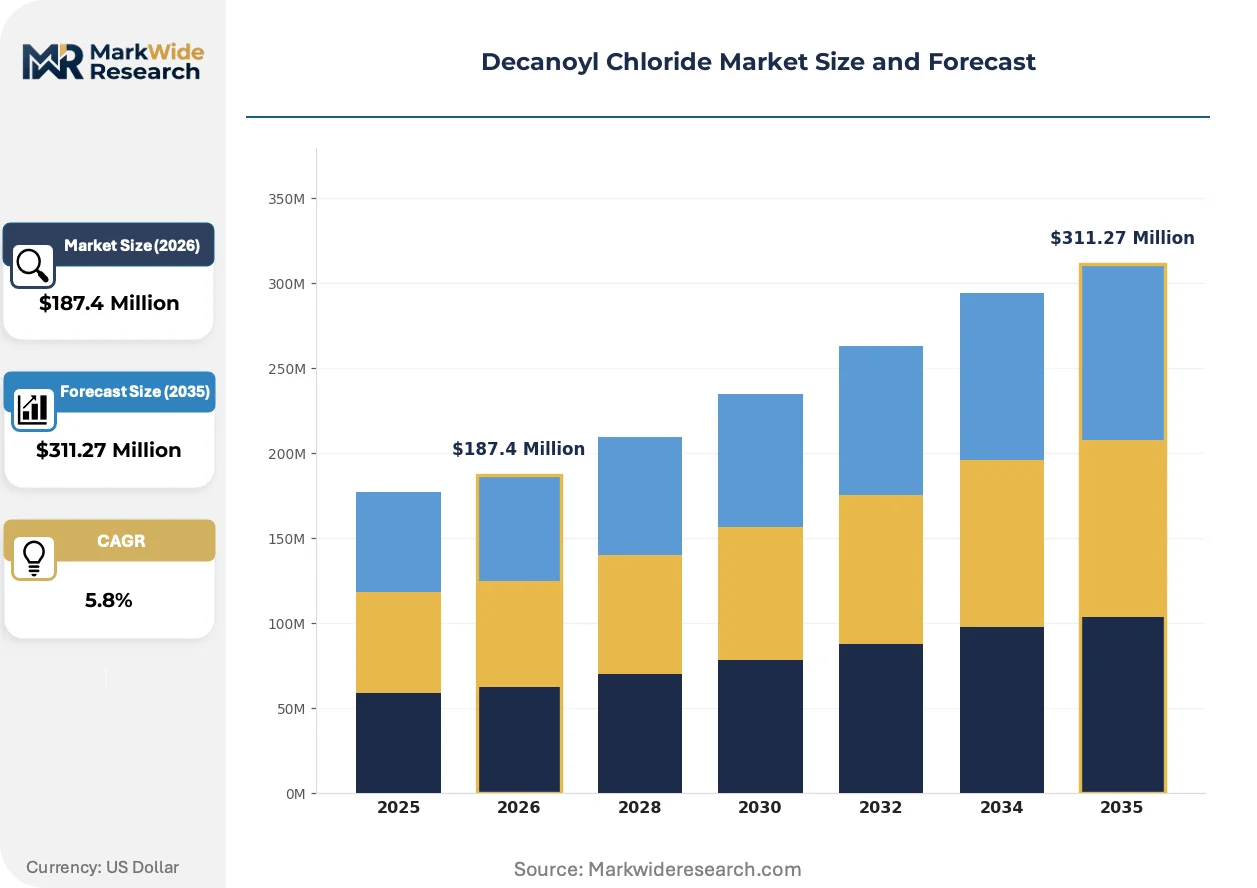
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Laboratory Grade, Pharmaceutical Grade, Cosmetic Grade End Use Industry: Chemicals, Pharmaceuticals, Cosmetics, Agrochemicals Packaging Type: Drums, Bottles, Bulk Containers, Pails Delivery Mode: Direct Shipping, Freight Shipping, Courier, Others |
| Companies Covered | Seqens, PMC Isochem, Shree Sulphurics, Actylis, Novaphene Specialities, Shanghai Mayao Chemical, Shandong Yinglang Chemical, Fengchen Group, Shanghai Shenju Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Decanoyl Chloride Market Evolving Landscape
Catalytic chlorination technologies and continuous-flow reactor designs are disrupting batch-wise thionyl chloride processes, while regulatory data harmonization initiatives reshape quality documentation requirements across pharmaceutical supply chains.
Flow chemistry reactor systems for acyl chloride synthesis are collapsing the capital-intensity barrier for pharmaceutical-grade production. Mid-scale Indian and European producers are adopting Corning Advanced-Flow reactors to achieve ton-scale output with smaller footprints and tighter temperature control. This technology is collapsing the historical scale advantage of large-batch Chinese manufacturers by enabling distributed, compliant production closer to formulation sites.
REACH registration requirements for acyl chloride derivatives are tightening substance dossier standards across European pharmaceutical supply chains. ECHA's updated guidance on impurity qualification thresholds forces producers to generate chronic toxicity data on trace chlorinated byproducts. API manufacturers in Germany and Switzerland are responding by qualifying dual-source supply arrangements with registered European and Indian producers rather than relying on unregistered Asian merchant supply.
Specification-driven procurement contracts are replacing spot-market purchasing for pharmaceutical-grade material. Large Indian formulators in Hyderabad and Mumbai are locking multi-year supply agreements with assay guarantees and audit rights, displacing the traditional merchant distributor channel. This pattern is most visible in CDSCO-inspected facilities supplying regulated export markets, where documentation continuity outweighs marginal price advantages from spot purchasing.
Decanoyl Chloride Market Segmentation
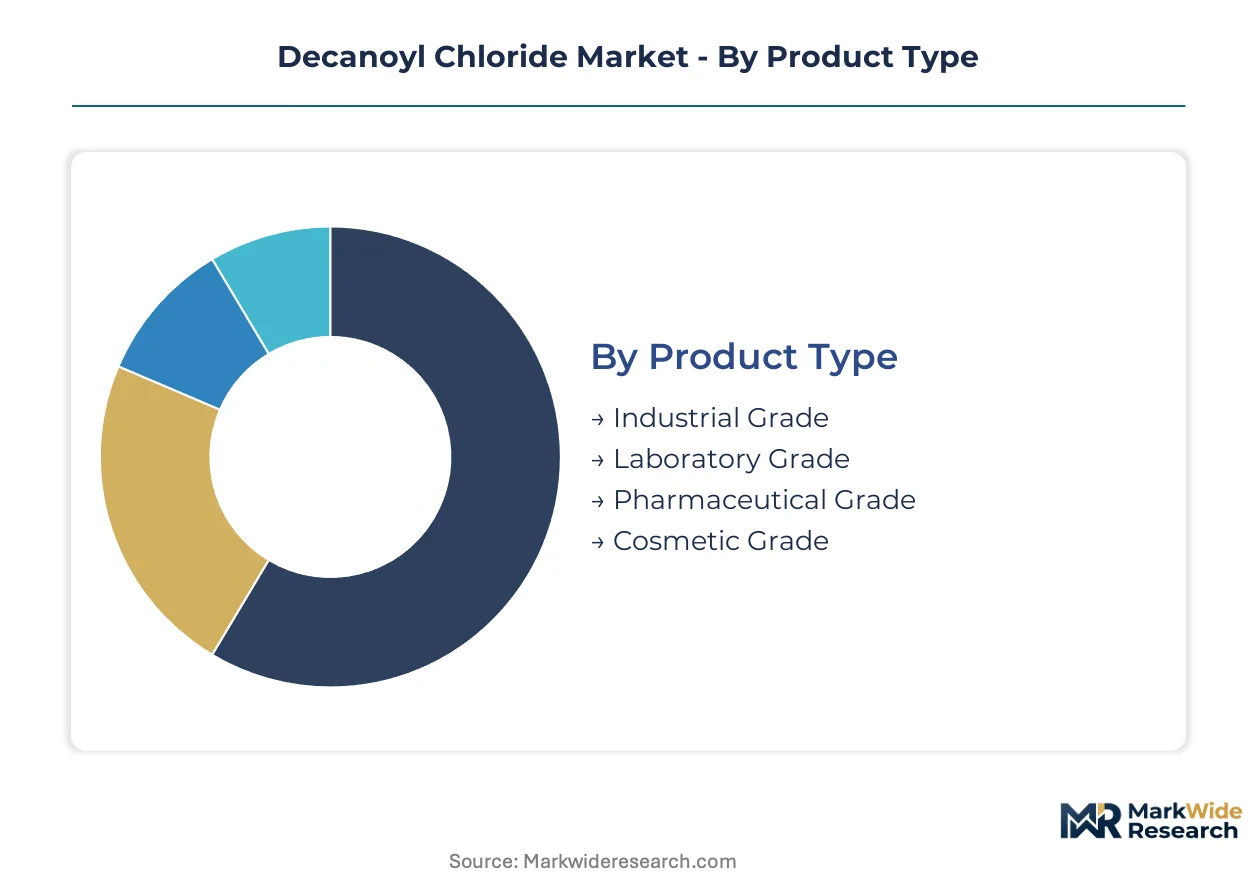
Grade stratification in decanoyl chloride determines capital intensity, regulatory burden, and margin structure across the value chain. Pharmaceutical and cosmetic specifications command premium positioning due to impurity profiling requirements, while industrial grades compete on throughput and logistics efficiency.
Product Type:
Cycle times vary dramatically by grade: pharmaceutical batches require extended analytical hold periods, while industrial material moves continuously from reactor to drum.
- Pharmaceutical Grade:Assay specifications typically exceed 99% purity with tight limits on chlorinated byproducts and trace metals. CDSCO-inspected facilities in Hyderabad and Ahmedabad drive procurement volumes as Indian API exporters scale intermediate output for regulated markets.
- Industrial Grade:Standard 98% minimum assay serves bulk acylation in surfactant and polymer intermediate manufacturing. Gujarat's chemical corridor processes the highest throughput volumes, with freight economics favoring drum-scale shipments to domestic formulation sites.
- Laboratory Grade:Small-batch material packaged in amber glass with certificate of analysis for R&D-scale peptide synthesis and method development.
- Cosmetic Grade:MFDS-aligned impurity specifications support peptide surfactant derivatization in South Korean personal care manufacturing.
Industrial grade dominates installed base. Pharmaceutical grade is where expansion concentrates.
End Use Industry:
Margin structures diverge sharply: pharmaceutical precursors justify dedicated quality systems, while agrochemical applications prioritize volume throughput and supply security.
- Pharmaceuticals:C10 acyl chlorides function as acylation reagents in API synthesis for antiviral and metabolic therapeutic classes. Seqens and European registered producers capture value from ECHA-aligned supply chain documentation requirements.
- Agrochemicals:Intermediate demand from herbicide and fungicide synthesis routes concentrates in Jiangsu and Shandong provinces. Shanghai Mayao Chemical's dedicated supply contracts demonstrate channel innovation bypassing traditional merchant distribution.
- Chemicals:Bulk surfactant and polymer additive manufacturing consumes drum-scale industrial grade through established distributor networks.
- Cosmetics:Peptide synthesis and specialty surfactant derivatization in Chinese and South Korean personal care manufacturing is climbing the fastest.
Pharmaceutical applications anchor value generation. Agrochemical throughput is expanding most quickly.
Packaging Type:
Packaging selection tracks handling requirements and customer scale: moisture-sensitive material demands sealed systems, while bulk users optimize for tote discharge efficiency.
- Drums:Standard 200-liter steel drums with nitrogen blanket dominate pharmaceutical and chemical intermediate shipments. Corrosion-resistant linings extend shelf life for hydrolytically sensitive material.
- Bulk Containers:Intermediate bulk containers and ISO-tanks serve agrochemical formulators with dedicated synthesis capacity and rapid inventory turnover.
- Bottles:Amber glass packaging with septum closures protects laboratory-grade material from moisture ingress during storage.
- Pails:Small-volume pails address cosmetic compounders requiring frequent batch-scale access with minimal headspace exposure.
Drums dominate installed base. Bulk containers are where expansion concentrates.
Delivery Mode:
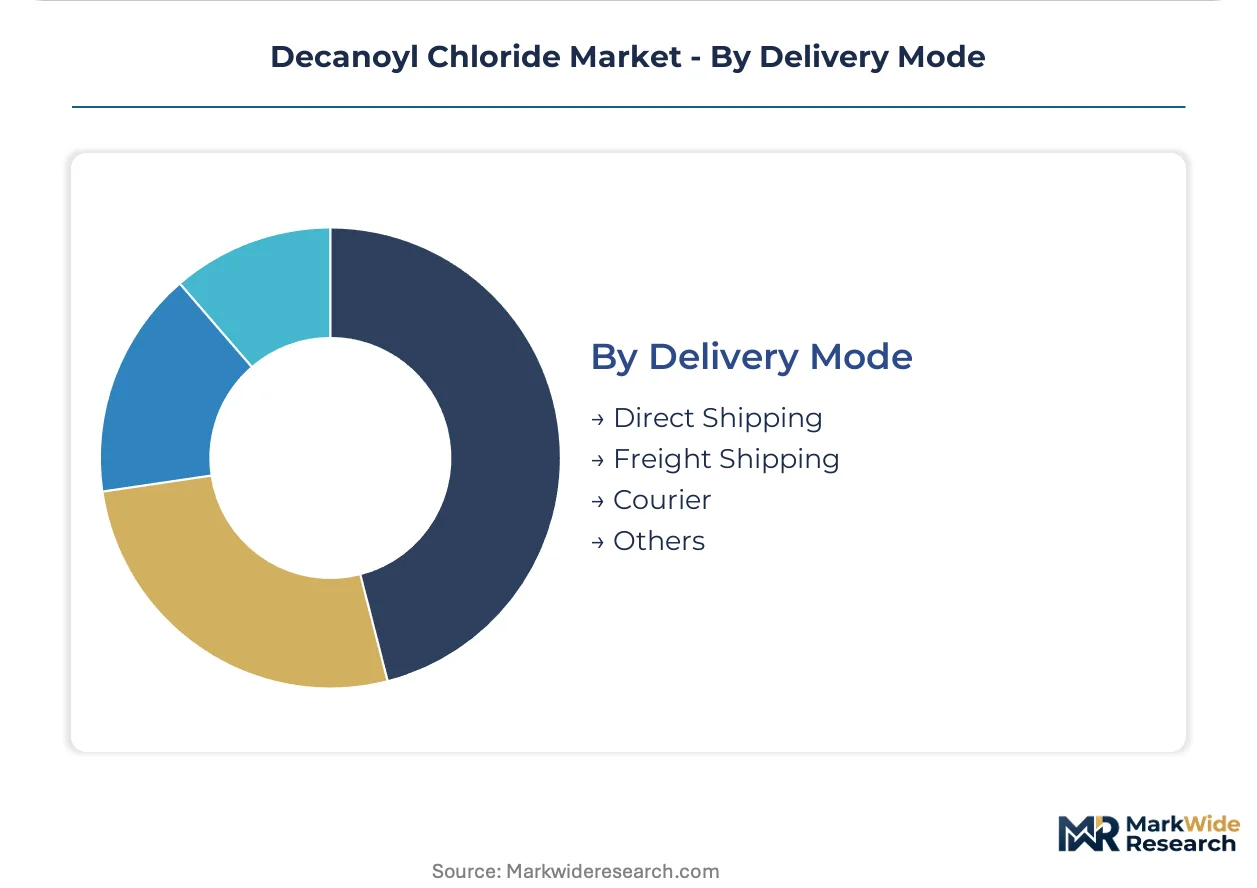
Logistics configuration reflects customer criticality and documentation requirements: pharmaceutical supply chains demand chain-of-custody tracking, while industrial buyers optimize for cost per kilogram.
- Direct Shipping:Producer-to-customer delivery eliminates intermediate handling for pharmaceutical-grade material requiring temperature monitoring and customs documentation continuity. Indian formulators in Mumbai and Hyderabad increasingly specify direct lanes for CDSCO-inspected facilities.
- Freight Shipping:Consolidated LTL and FTL movements serve chemical and agrochemical buyers with predictable demand patterns and established receiving infrastructure.
- Courier:Express delivery supports laboratory-grade and urgent R&D shipments with end-to-end tracking and controlled-temperature options.
- Others:Includes customer-arranged collection and third-party logistics managed through distributor inventory programs.
Freight shipping dominates installed base. Direct shipping is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO's tightening purity protocols for active pharmaceutical ingredient precursors have concentrated procurement attention on Indian chemical manufacturing corridors. Gujarat's industrial belt and Hyderabad's formulation clusters now drive regional demand patterns for pharmaceutical-grade acyl chlorides.
India
Pharmaceutical formulators in Hyderabad and Mumbai are scaling bulk intermediate output for FDA-regulated export markets. CDSCO's updated impurity profiling requirements for API precursors have forced procurement teams to source exclusively from inspected facilities. Gujarat's chemical corridor between Ahmedabad and Vadodara processes the highest throughput volumes, with drum-scale shipments feeding domestic formulation sites.
China
Jiangsu and Shandong provinces have narrowed the historical supply gap for C10 acyl chlorides across Asia-Pacific. MEE wastewater discharge limits on thionyl chloride-based manufacturing routes are pushing producers toward alternative chlorination technologies. Shanghai anchors regional distribution networks through dedicated intermediate supply contracts with domestic agrochemical formulators.
United States
EPA oversight of chlorinated intermediate emissions shapes production economics for domestic acyl chloride manufacturing. Pharmaceutical manufacturers require documented supply chain transparency for precursors under FDA-aligned protocols. The Gulf Coast petrochemical corridor maintains captive chlorination capacity serving surfactant and polymer additive producers.
South Korea
MFDS-aligned cosmetic-grade specifications support peptide surfactant derivatization in personal care manufacturing. Personal care compounders in Seoul metropolitan area are expanding decanoyl chloride procurement for specialty surfactant synthesis. The Incheon chemical processing zone concentrates import handling and batch-scale formulation operations.
Germany
REACH registration requirements govern import volumes and substitution incentives for acyl chloride derivatives across European pharmaceutical supply chains. ECHA's updated guidance on impurity qualification thresholds forces producers to generate chronic toxicity data on trace chlorinated byproducts. The Rhineland chemical cluster maintains integrated acyl chloride platforms serving registered producers with ECHA-aligned dossiers.
Decanoyl Chloride Market Competitive Landscape
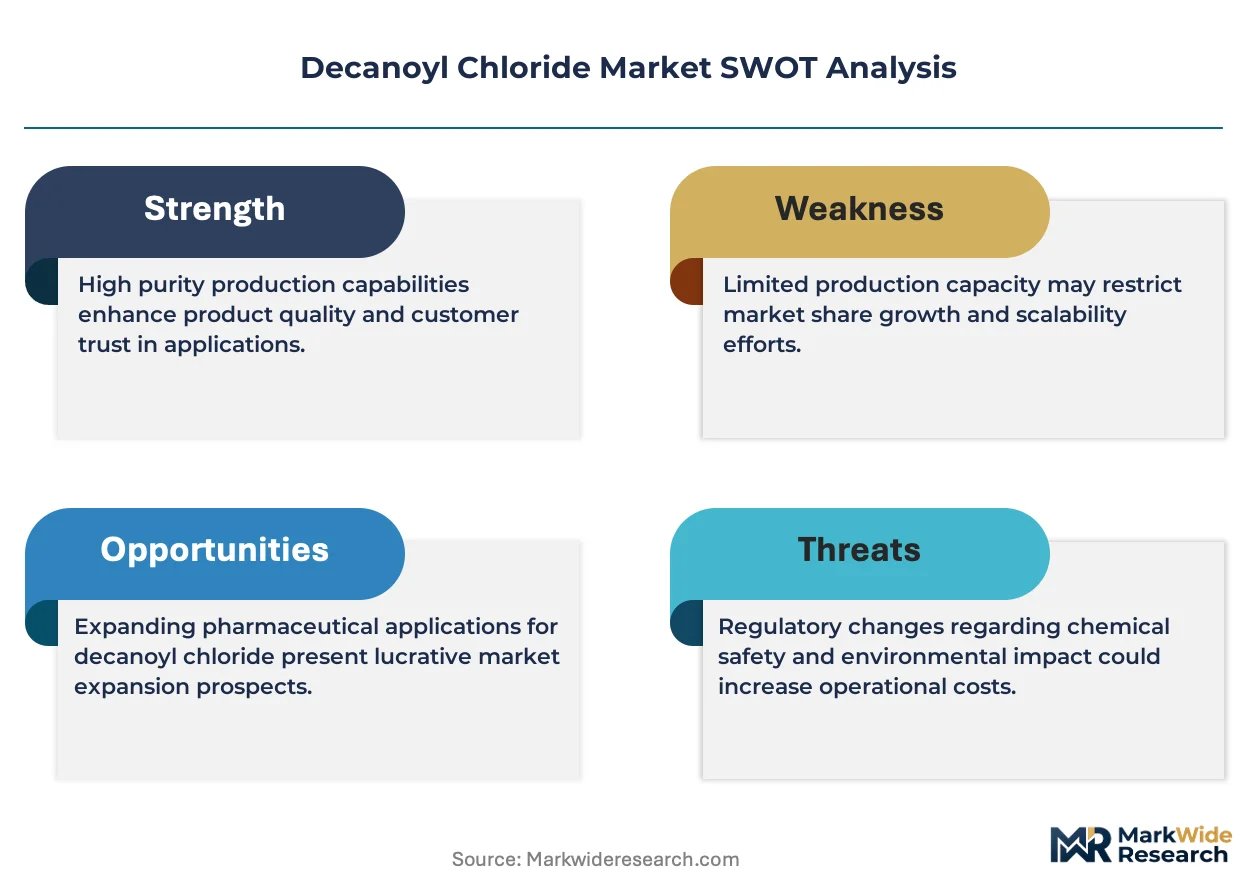
Integrated European producers and Asian merchant manufacturers split the market along regulatory compliance lines. European participants leverage REACH-registered status and ECHA-aligned documentation to capture pharmaceutical-grade premiums. Asian producers compete on scale economics for industrial-grade material. Three archetypes dominate: vertically integrated acyl chloride specialists, regional merchant distributors, and captive chlorination operators serving internal derivative demand. Competitive positioning hinges on multi-jurisdiction certification timelines and analytical chemistry capabilities rather than unit cost alone.
Within the integrated specialist tier, Seqens occupies a position exemplifying European pharmaceutical-grade production across multiple sites. Among Asia-Pacific fabricators, Shanghai Mayao Chemical represents the regional distribution innovation model through dedicated supply contracts. Shandong Yinglang Chemical sits within the scale-driven merchant manufacturing archetype serving bulk industrial applications. These three anchors illustrate the geographic and regulatory segmentation that structures competitive dynamics.
| Leading Market Players |
|---|
| Seqens |
| PMC Isochem |
| Shree Sulphurics |
| Actylis |
| Novaphene Specialities |
| Shanghai Mayao Chemical |
| Shandong Yinglang Chemical |
| Fengchen Group |
| Shanghai Shenju Chemical |
| Others |
Value Network & Pricing Analysis
Ahmedabad-Mumbai freight corridors transmit cost dynamics from Gujarat's chemical belt to formulation clusters, compressing margins for drum-scale industrial shipments while amplifying price premiums for pharmaceutical-grade material with CDSCO documentation.
Pricing Analysis
Price spreads between Indian and Chinese pharmaceutical-grade material reflect assay guarantee differentials and regulatory audit costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and volume commitment. Pricing pressure stems from thionyl chloride input volatility transmitting through thionyl-based manufacturing routes. Agrochemical buyers in Jiangsu demonstrate highest price sensitivity; CDSCO-inspected facilities supplying FDA-regulated export markets show least.
Supply Chain Analysis
Contract manufacturing concentration rests with Seqens across European integrated sites and Shanghai Mayao Chemical's dedicated synthesis arrangements. Geographic supply concentration centers on China, India, and Germany. Raw material dependencies draw from thionyl chloride, decanoic acid feedstocks, and catalytic chlorination reagents. Single-source vulnerability concentrates in Jiangsu-Shandong thionyl chloride supply. Distribution runs through direct producer-to-formulator lanes for pharmaceutical-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flow chemistry reactor adoption is disrupting batch-wise acyl chloride economics, compressing capital barriers for mid-scale pharmaceutical-grade production.
For Market Incumbents: Build regulatory documentation moats through simultaneous CDSCO, FDA, and ECHA dossier alignment. Secure captive chlorination capacity in Gujarat's chemical corridor to offset thionyl chloride input volatility. Defend against enzymatic catalysis substitutes by embedding continuous-flow reactor technology for carbon footprint reduction. For New Entrants and Emerging Players: Pursue cosmetic-grade peptide synthesis white space in South Korean personal care manufacturing. Target agrochemical intermediate channels through dedicated supply contracts bypassing merchant distributors. Penetrate via MFDS-aligned impurity specifications with lower certification burden than pharmaceutical tiers. For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical conglomerates divesting non-core acyl chloride platforms. Long-term viability favors producers with multi-jurisdiction certification capabilities and flow chemistry retrofit potential. Monitor MEE wastewater enforcement intensity as inflection signal for alternative chlorination technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thionyl Chloride | Captive SOCl2 supply insulates Seqens from Chinese input volatility and MEE enforcement. |
| Flow Chemistry Reactor Deployment | Corning Advanced-Flow adoption collapses capital intensity for CDSCO-compliant ton-scale output. |
| Dual-Grade Certification Investment | Simultaneous CDSCO and MFDS compliance unlocks premium pricing across pharmaceutical and cosmetic pools. |
| Direct-to-Formulator Distribution | Producer-to-customer lanes displace merchant channels for documentation-critical pharmaceutical supply. |
| Alternative Chlorination Technology Licensing | Phosgene-free catalytic routes attract regulatory tailwind as China's MEE tightens wastewater limits. |
Research Methodology
Operator-level perspectives from plant managers at acyl chloride facilities, procurement leads at Indian API formulators, distribution channel partners, and technical R&D directors anchored the qualitative base. Secondary validation drew from CDSCO inspection records, ECHA registration databases, customs trade flows, and SEC filings of listed chemical producers. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates.
Scenario-bracketing framed projections across the analysis window with base, upside, and downside regulatory enforcement assumptions. Segmentation dimensions modeled include grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from compound growth mechanics applied to baseline capacity and demand build-ups. Forecast inputs incorporated MEE wastewater policy trajectory and flow chemistry adoption curves.
Sensitivities concentrate around thionyl chloride supply interruptions, CDSCO inspection intensity revisions, and enzymatic substitution rates in cosmetic applications. Quarterly review of ECHA impurity guidance updates, MEE enforcement actions in Jiangsu, and Indian API export licensing velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Global White Oil Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
US Esters Market
Oleochemicals
Isopropyl Esters Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Lauric Aldehyde Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Ethoxylated Castor Oil Market
Oleochemicals
Ethoxylates Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Glycerol Esters of Wood Rosins Market