
 2-Hexyldecanol Market | 2026-2036
2-Hexyldecanol Market Size, Share, and Industry Trends Forecast 2026-2036
2-Hexyldecanol Market Outlook
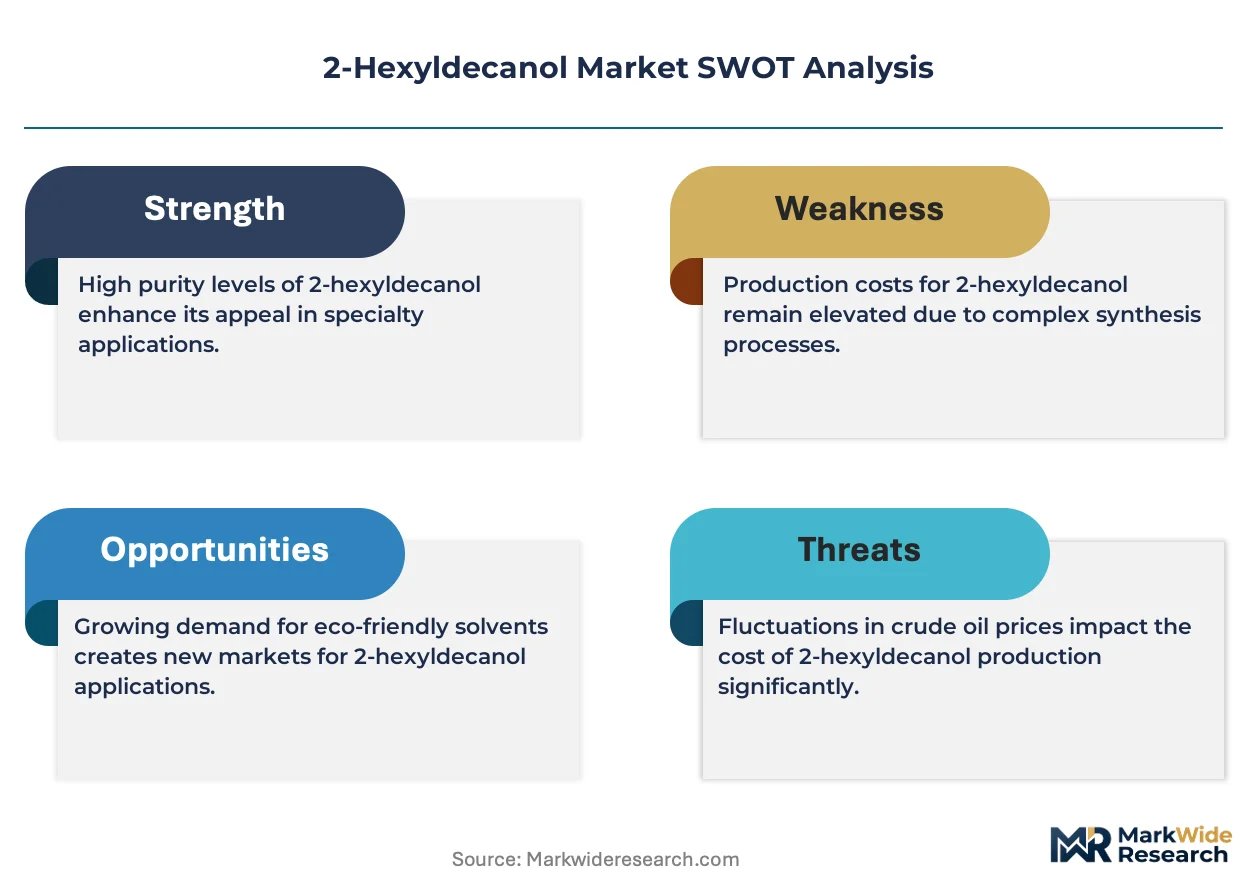
Asset-light toll manufacturing and third-party Guerbet alcohol processing agreements is tilting competitive dynamics toward firms with flexible feedstock access rather than fixed-asset dominance. Sasol Ltd leverages its Fischer-Tropsch-derived oleochemical platform to sustain captive supply of high-purity C16-C20 alcohols. BASF SE anchors European demand through integrated oxo-alcohol chemistry and downstream personal care formulation partnerships. Evonik Industries differentiates via specialty esterification technology that extends 2-hexyldecanol into pharmaceutical-grade intermediates.
2-Hexyldecanol is a branched-chain C16 Guerbet alcohol synthesized via base-catalyzed condensation of two shorter-chain alcohols, yielding a liquid product with melting point below room temperature and superior oxidative stability versus linear equivalents. Its primary industrial purpose centers on serving as a low-viscosity emollient and solvent carrier in cosmetic formulations, plus a plasticizer co-boosters in coatings and adhesive systems. The emollients segment leads value capture due to premium positioning in skin-care and sun-care formulations, while the intermediates segment records the fastest trajectory as pharmaceutical and agrochemical esterification demand expands. Industrial grade occupies the volume base, though cosmetic and pharmaceutical grades concentrate margin pools through certification-intensive qualification barriers.
EPA oversight of chemical manufacturing under TSCA shapes domestic production standards for 2-hexyldecanol in the United States, while REACH registration requirements in Europe govern import and formulation access across the EU27. China's GB standards and evolving MEE environmental compliance protocols increasingly determine export qualification for Asian-manufactured volumes destined for personal care and coatings applications. Stakeholders must monitor regulatory divergence between these jurisdictions to anticipate reformulation costs and qualification timelines.
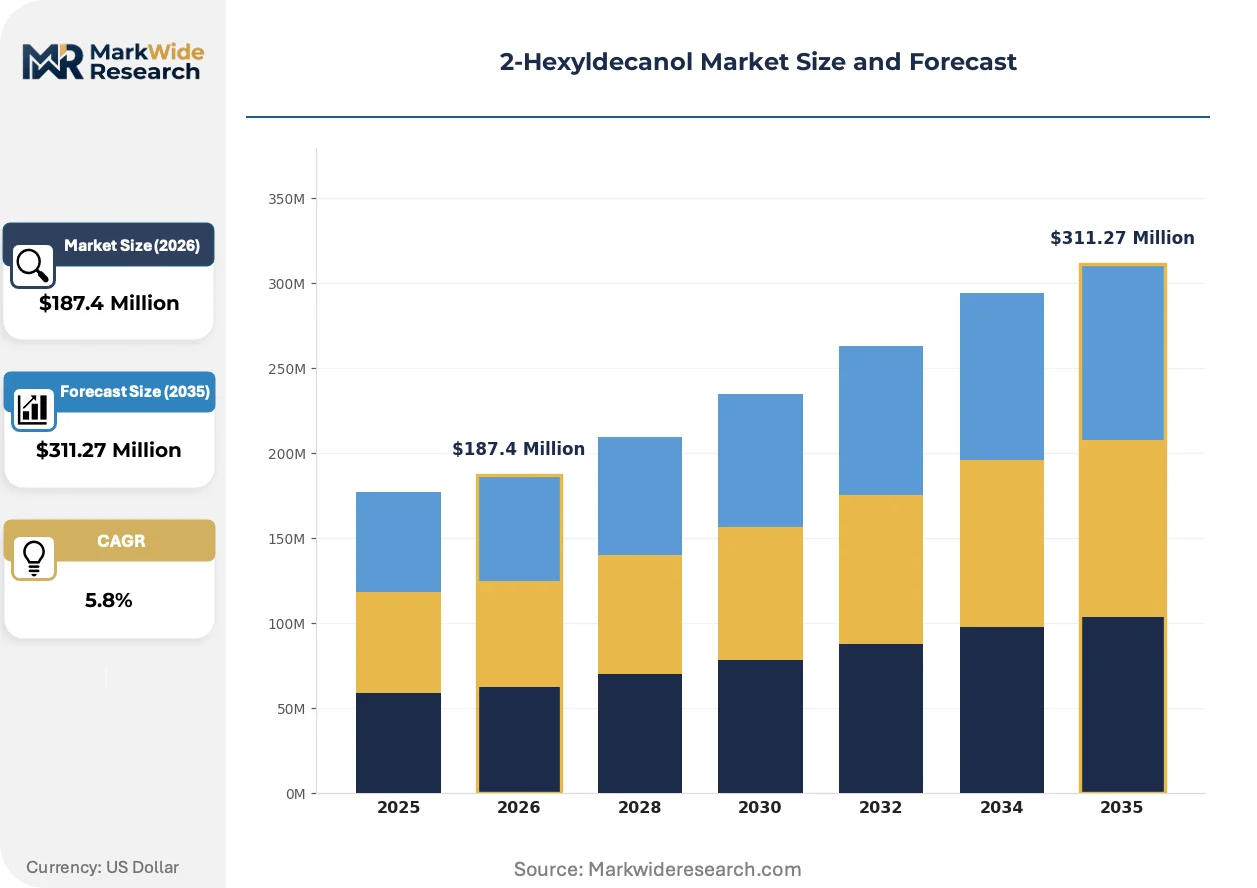
Market Dynamics
REACH registration requirements and evolving FDA cosmetic ingredient standards are forcing reformulation cycles across personal care and pharmaceutical applications, compressing supplier qualification timelines and favoring asset-light toll manufacturers with flexible feedstock access over fixed-asset incumbents.
Growth Catalysts
- Emollient premiumization in skin-care:Personal care formulators in Germany and the United States are specifying Guerbet alcohols for low-viscosity, room-temperature-stable formulations that outperform linear C16 equivalents in oxidative stability.
- REACH compliance as market access gate:ECHA registration mandates for C16-C20 alcohols create qualification barriers that filter out non-compliant Asian exporters, tightening effective supply and supporting margin pools for registered European producers.
- Pharmaceutical esterification expansion:Agrochemical and pharmaceutical intermediates demand is accelerating as specialty esterification technology extends 2-hexyldecanol into high-purity pharmaceutical-grade applications.
Market Restraints
- Oleochemical feedstock volatility:Palm kernel and coconut oil price swings directly compress margins for producers lacking Fischer-Tropsch or oxo-alcohol captive supply.
- Supply concentration in Fischer-Tropsch platforms:South African and German production clusters control disproportionate volumes of high-purity C16-C20 alcohols, creating geographic chokepoints.
- Linear C16 alcohol substitution:Lower-cost linear fatty alcohols from Southeast Asian oleochemical complexes threaten volume share in industrial-grade plasticizer and coatings applications.
Strategic Opportunities
- Chinese domestic personal care expansion:GB standards compliance and MEE environmental protocols are creating first-mover advantages for registered suppliers to domestic formulators in Shanghai and Guangdong clusters.
- Biobased Guerbet synthesis:Enzymatic condensation routes using renewable feedstocks are converging with carbon accounting requirements under EU Green Deal corporate sustainability frameworks.
- Third-party toll processing partnerships:Asset-light manufacturing agreements allow specialty chemical distributors to capture margin without fixed-asset exposure in high-cost jurisdictions.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA pre-manufacture notifications, REACH dossier submissions, and China MEE environmental impact assessments stretch regulatory affairs teams.
- Pharmaceutical-grade validation complexity:GMP compliance for excipient-grade 2-hexyldecanol requires dedicated equipment trains and analytical method transfers that extend qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Hexyldecanol Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Emollients, Plasticizers, Intermediates End Use Industry: Personal Care, Automotive, Coatings, Adhesives Grade: Industrial, Cosmetic, Food Grade, Pharmaceutical Packaging Type: Drums, IBC Totes, Bulk Containers, Cans |
| Companies Covered | Lonza Group, Sasol Ltd, BASF SE, INEOS, Eastman Chemical Company, Evonik Industries, Croda International, New Japan Chemical Co., Ltd, KLK OLEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Hexyldecanol Market Strategic Shifts
Guerbet alcohol production technology and downstream qualification pathways are undergoing simultaneous compression, with enzymatic routes and regulatory automation tools reshaping cost structures and market access speed.
Continuous-flow enzymatic condensation is collapsing batch-cycle times for Guerbet alcohol synthesis. Specialty chemical manufacturers in the Netherlands and Switzerland are piloting immobilized-lipase fixed-bed reactors that halve solvent use and eliminate caustic waste streams. This technology is collapsing the capital-intensity gap between biobased and petrochemical routes, enabling mid-scale entrants to achieve cost parity with Fischer-Tropsch incumbents.
ECHA's SCIP database requirements for Substances of Very High Concern are tightening downstream traceability obligations. Cosmetic and coatings formulators must now document 2-hexyldecanol provenance through full supply chains, forcing toll manufacturers to deploy blockchain-linked batch records. German and French personal care brands are responding by consolidating supplier bases to registered producers with automated compliance architectures.
Specification-driven procurement is compressing traditional distributor layers in North American personal care supply chains. Large formulators in New Jersey and California are establishing direct toll-processing agreements with Guerbet alcohol manufacturers, bypassing merchant chemical distributors. This disintermediation is most visible in sun-care and prestige skin-care verticals where lot-size flexibility and certificate-of-analysis customization outweigh volume discounts.
2-Hexyldecanol Market Segmentation
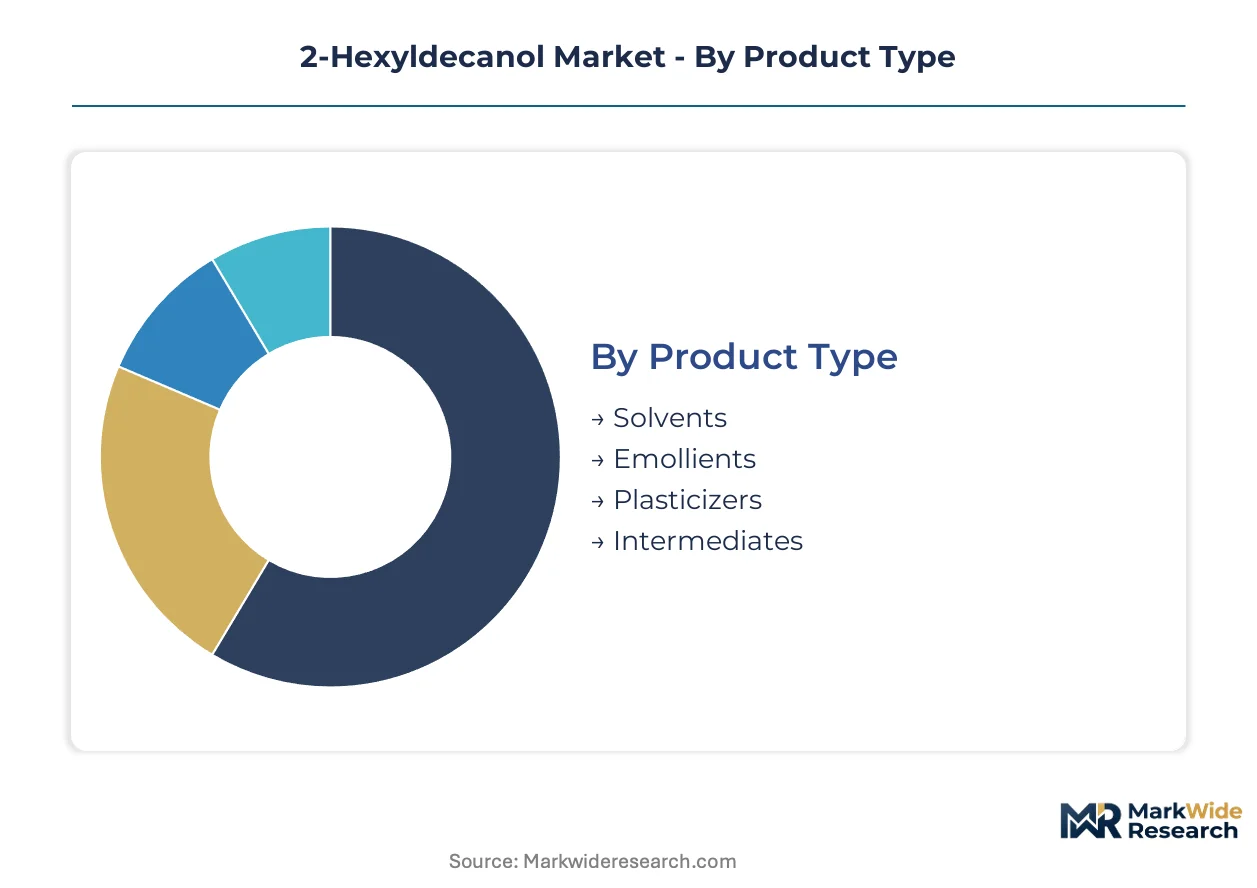
Segmentation in 2-hexyldecanol markets reveals how qualification intensity and formulation specificity fragment procurement patterns. Personal care formulators demand pharmaceutical-grade certificates of analysis, while industrial buyers prioritize drum-scale flexibility and freight optimization.
Product Type:
After-sales service intensity varies sharply across product types, with pharmaceutical intermediates requiring analytical method transfers and regulatory dossier support that solvents never demand.
- Emollients:Low-viscosity Guerbet alcohol formulations with melting points below room temperature serve premium skin-care and sun-care applications. German and United States formulators specify these for oxidative stability advantages over linear C16 equivalents in prestige positioning.
- Intermediates:Specialty esterification feedstocks for pharmaceutical and agrochemical synthesis carry GMP compliance burdens and dedicated equipment train requirements. Evonik Industries extends 2-hexyldecanol into this high-purity segment through proprietary technology, with demand climbing fastest in Swiss and German pharmaceutical clusters.
- Solvents:Liquid carriers for active ingredients in topical formulations.
- Plasticizers:Co-boosters in coatings and adhesive systems with industrial-grade tolerance bands.
By volume, emollients lead. By growth pace, intermediates are ahead.
End Use Industry:
Cost tier stratification separates personal care qualification investments from automotive procurement scale economics.
- Personal Care:Premium emollient absorption drives specification of cosmetic-grade 2-hexyldecanol with full REACH dossier documentation. New Jersey and California formulators establish direct toll-processing agreements, bypassing distributors for lot-size flexibility.
- Coatings:Industrial-grade plasticizer demand concentrates in German and Chinese manufacturing clusters with MEE environmental compliance protocols.
- Automotive:Adhesive and sealant applications with specification tolerance for industrial-grade material.
- Adhesives:Pressure-sensitive and structural bonding formulations with volume-driven procurement.
Personal care commands the steepest premium tier. Coatings deliver the broadest volume base.
Grade:
Customer type fragmentation separates certification-intensive pharmaceutical buyers from industrial procurement desks.
- Cosmetic:REACH-registered material with oxidative stability specifications for room-temperature-stable formulations. ECHA registration mandates filter non-compliant Asian exporters, tightening effective supply for European personal care brands.
- Pharmaceutical:Excipient-grade material requiring GMP compliance, dedicated equipment trains, and extended analytical method transfers. FDA cosmetic ingredient standards and EPA TSCA oversight shape domestic United States production pathways.
- Industrial:Volume base grade with plasticizer and coatings application tolerance.
- Food Grade:Specialized regulatory compliance for incidental contact applications.
Cosmetic grade captures the widest margin pool. Pharmaceutical grade shows the steepest expansion trajectory.
Packaging Type:
Supply concentration in Fischer-Tropsch platforms shapes packaging economics through freight radius calculations.
- Drums:Standard 200-liter units for mid-scale formulators requiring lot-size flexibility and certificate-of-analysis customization. Specification-driven procurement in North American personal care verticals favors drum-scale direct agreements over volume discounts.
- Bulk Containers:Tanker and flexitank deliveries for industrial-scale coatings and adhesives producers with captive storage infrastructure.
- IBC Totes:Intermediate bulk solutions for regional toll manufacturers.
- Cans:Small-format packaging for laboratory and sampling requirements.
Drums dominate personal care procurement. Bulk containers lead industrial volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price leverage tilts toward German producers commanding REACH-registered premium tiers, while Chinese manufacturers absorb margin compression from MEE environmental compliance costs and GB standards alignment investments.
Germany
Personal care formulators in Hamburg and Frankfurt specify Guerbet alcohols for prestige skin-care lines. ECHA registration mandates filter non-compliant imports, tightening effective supply. The Ludwigshafen chemical cluster anchors captive oxo-alcohol production with downstream formulation partnerships.
United States
New Jersey and California sun-care manufacturers establish direct toll-processing agreements for lot-size flexibility. EPA TSCA pre-manufacture notifications shape domestic production standards. The Gulf Coast petrochemical corridor supplies Fischer-Tropsch-derived feedstocks to specialty alcohol producers.
China
Shanghai and Guangdong personal care clusters drive domestic emollient absorption. MEE environmental impact assessments and evolving GB standards determine export qualification. Yangtze River Delta specialty chemical manufacturers pilot enzymatic condensation routes for biobased Guerbet synthesis.
Switzerland
Pharmaceutical-grade esterification demand concentrates around Basel and Zurich. Swissmedic oversight of excipient-grade materials extends qualification cycles. Swiss specialty chemical manufacturers leverage proprietary technology to serve agrochemical intermediate buyers.
South Africa
Fischer-Tropsch platforms sustain captive supply of high-purity C16-C20 alcohols for export markets. Sasol Ltd's Secunda complex controls disproportionate volumes of industrial-grade material. Durban-Johannesburg logistics corridors channel volumes toward European and Asian personal care formulators.
2-Hexyldecanol Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in feedstock and toll-processing niches. The market structures around three tiers: Fischer-Tropsch incumbents with captive oleochemical supply, oxo-alcohol integrators with European formulation partnerships, and asset-light toll manufacturers with flexible batch-scale capacity. Strategic moves concentrate on backward integration into renewable feedstocks and geographic expansion through third-party processing agreements rather than greenfield capacity.
Within the Fischer-Tropsch archetype, Sasol Ltd anchors African supply positions. Among European oxo-alcohol integrators, BASF SE exemplifies downstream formulation partnerships. Specialty esterification technology sits with Evonik Industries, representing the pharmaceutical-grade intermediate tier. These three occupy distinct competitive spaces without direct overlap in customer qualification requirements or production technology.
| Leading Market Players |
|---|
| Lonza Group |
| Sasol Ltd |
| BASF SE |
| INEOS |
| Eastman Chemical Company |
| Evonik Industries |
| Croda International |
| New Japan Chemical Co., Ltd |
| KLK OLEO |
| Others |
Value Chain & Pricing Dynamics
Oleochemical feedstock volatility determines both pricing tier spreads and supply chain shape across 2-hexyldecanol markets. Palm kernel and coconut oil price swings compress margins for producers lacking Fischer-Tropsch or oxo-alcohol captive supply, forcing asset-light toll manufacturers to prioritize flexible feedstock access over fixed-asset dominance.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across cosmetic, pharmaceutical, and industrial grade tiers. Price differentiation hinges on REACH registration status and GMP compliance level, with cosmetic-grade material commanding widest spreads due to ECHA-mandated qualification barriers. Cost compression in industrial-grade segments intensifies as Southeast Asian linear C16 alcohols threaten volume share. Personal care formulators in Germany and the United States demonstrate least price sensitivity, prioritizing certificate-of-analysis customization over volume discounts.
Supply Chain Analysis
Specialty chemical toll manufacturers in the Netherlands and Switzerland hold pilot-scale enzymatic condensation capacity, while Sasol Ltd's Secunda complex and BASF SE's Ludwigshafen cluster anchor Fischer-Tropsch and oxo-alcohol supply respectively. Production draws from palm kernel oil, coconut oil, and Fischer-Tropsch-derived olefin feedstocks. Single-source vulnerability concentrates in South African and German high-purity C16-C20 alcohol production. Distribution runs through direct toll-processing agreements in North America and registered merchant channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA TSCA, REACH, and China MEE protocols creates specialist niches for qualified producers. Personal care formulators' specification-driven procurement disintermediates traditional distributor layers, opening margin capture opportunities for agile entrants.
For Market Incumbents: Pre-empt linear C16 substitution threats by deepening captive Fischer-Tropsch supply positions and accelerating pharmaceutical-grade GMP validation. Consolidate formulation partnerships with New Jersey and California sun-care manufacturers through dedicated equipment trains. Prioritize backward integration into renewable feedstocks to align with EU Green Deal carbon accounting frameworks.
For New Entrants and Emerging Players: Mid-scale enzymatic condensation capacity in the Yangtze River Delta represents the most penetrable entry point for biobased Guerbet alcohol production. Chinese domestic personal care clusters in Shanghai and Guangdong offer first-mover advantages through GB standards compliance. Establish direct toll-processing agreements with asset-light manufacturing partners to bypass fixed-asset exposure in high-cost jurisdictions.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialty esterification technology holders with pharmaceutical-grade qualification architectures. Long-term viability hinges on regulatory automation capabilities and blockchain-linked batch record systems. Watch for ECHA SCIP database compliance automation as the inflection signal separating scalable platforms from manual compliance burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstocks | Captive biobased supply aligns with EU Green Deal corporate sustainability frameworks for premium tier access. |
| Pharmaceutical-Grade GMP Validation | Excipient-grade qualification opens Swiss and German pharmaceutical cluster demand with extended margin pools. |
| Direct Toll-Processing Partnerships | Lot-size flexibility and certificate customization capture specification-driven procurement from New Jersey formulators. |
| Enzymatic Condensation Scale-Up | Immobilized-lipase fixed-bed reactors halve solvent use and eliminate caustic waste for cost parity achievement. |
| Blockchain-Linked Compliance Architecture | Automated batch records satisfy ECHA SCIP traceability obligations and consolidate supplier bases for European brands. |
Study Parameters
A standing panel of personal care formulators, pharmaceutical procurement managers, specialty chemical plant managers, and regulatory affairs directors provided ongoing calibration throughout the research process. Primary interviews combined with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing across feedstock price volatility bands and regulatory compliance cost trajectories shaped projections across the analysis window. Segmentation dimensions included grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from historical trajectory analysis and elasticity-adjusted demand modeling. Forecast inputs incorporated oleochemical feedstock futures curves and personal care formulation pipeline disclosures.
Stress conditions across palm kernel oil price spikes, REACH dossier rejection rates, and MEE environmental audit timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory stability and feedstock supply continuity. Quarterly review of ECHA registration processing times and Chinese GB standards revision schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Triisostearyl Citrate Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Isodecyl Citrate Market
Oleochemicals
Global Chlorinated Paraffin Market
Oleochemicals
Esters Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Ethyl Linalool Market
Oleochemicals
Alcohol Ethoxylates Market
Oleochemicals
Isooctyl Chloride Market
Oleochemicals
Glycerol Diacetate Market
Oleochemicals
Squalane Market
Oleochemicals
Lactic Acid Esters of Mono and Diglycerides of Fatty Acids Market
Oleochemicals
Octanoyl Chloride Market
Oleochemicals
Global Hexyl Cinnamal Market