
 Isodecanol Market | 2026-2036
Isodecanol Market Size, Share, and Industry Trends Forecast 2026-2036
Isodecanol Market Outlook
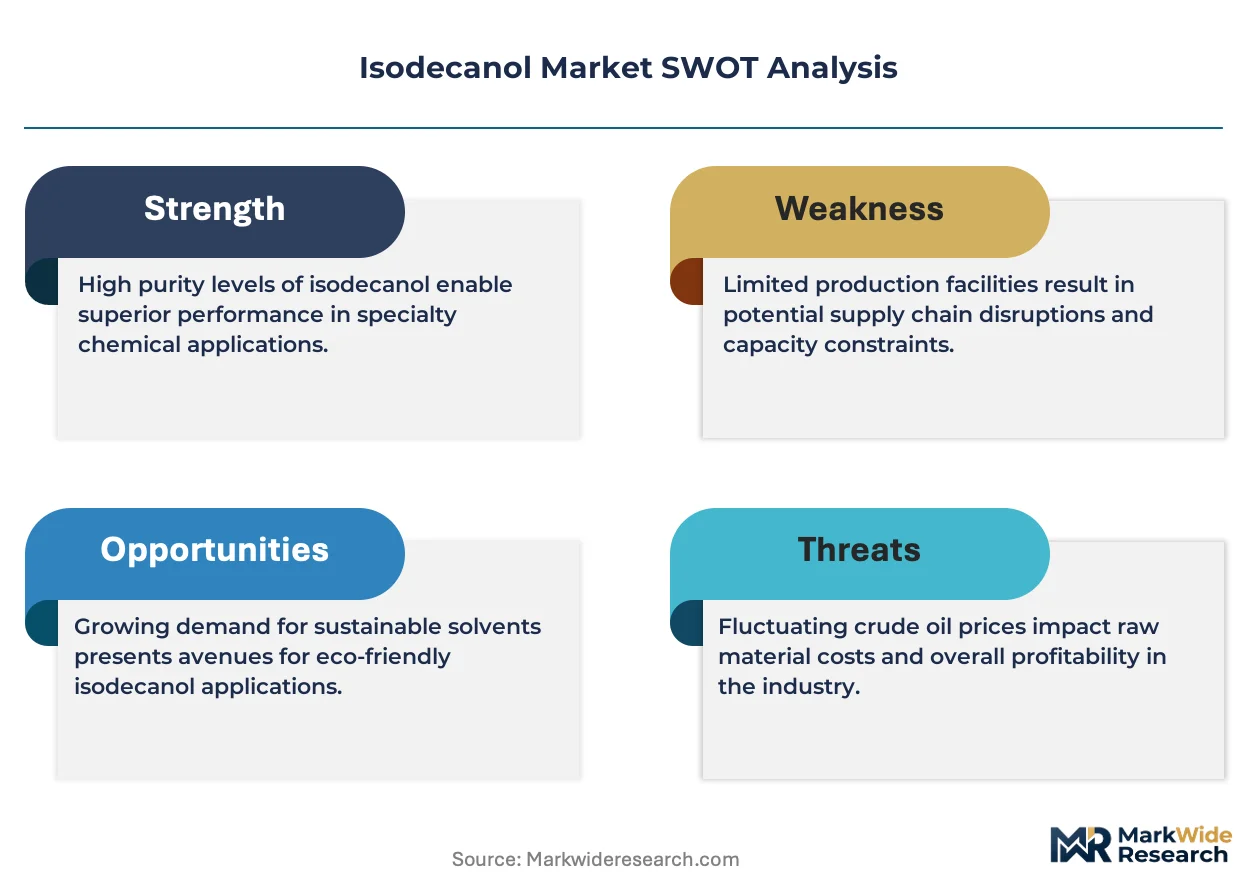
ISO 16128 certification for natural and organic cosmetic ingredients is bifurcating supplier access across the isodecanol value chain. BASF SE leverages integrated C10 alcohol streams from its Ludwigshafen complex to sustain pharmaceutical-grade output. Sasol Limited anchors African supply through its Fischer-Tropsch-derived alcohol platform, while Evonik Industries AG differentiates via high-purity specialty grades for European personal care markets.
Isodecanol is a branched-chain C10 fatty alcohol with a molecular weight of approximately 158 g/mol, produced primarily through hydroformylation of nonene followed by hydrogenation, serving as a critical intermediate for ester-based lubricants, surfactant feedstocks, and cosmetic emollients. Industrial-grade material dominates volume throughput for agrochemical and lubricant applications, whereas cosmetic-grade isodecanol commands premium positioning amid ISO 16128-aligned formulation trends. Surfactant applications are expanding fastest as formulators seek low-irritancy alternatives in personal care, while pharmaceutical-grade supply remains structurally constrained by compendial purity requirements.
REACH registration mandates under ECHA govern substance identity and impurity profiles for European market access, while EPA TSCA Section 5 notifications shape new chemical introductions in the United States. FDA cosmetic ingredient regulations and impending MoCRA fragrance allergen disclosure rules are elevating documentation burdens for personal care-grade suppliers. Stakeholders must monitor regulatory divergence between European hazard-based frameworks and U.S. risk-assessment approaches when configuring regional product portfolios and compliance investments.
Market Dynamics
REACH registration deadlines under ECHA are compressing supplier margins as purity documentation costs escalate for cosmetic-grade isodecanol destined for European personal care formulations.
Growth Catalysts
- ISO 16128 certification:Natural and organic cosmetic standards are expanding addressable market for plant-derived C10 alcohols in premium skincare lines across Germany and France.
- Surfactant formulators:Personal care manufacturers are substituting traditional alcohol ethoxylates with isodecanol-based alternatives to achieve lower dermal irritation profiles in rinse-off products.
- Fischer-Tropsch platform expansion:Gas-to-liquid technology is diversifying feedstock origins beyond petrochemical routes, enabling supply security for lubricant and agrochemical intermediates.
Market Restraints
- Nonene feedstock volatility:Propylene oligomerization costs fluctuate with cracker operating rates, squeezing hydroformylation economics for integrated producers.
- Pharmaceutical-grade purity thresholds:USP-NF and Ph.Eur. monograph compliance requires dedicated hydrogenation trains, limiting multi-product asset flexibility.
- Linear C10 alcohol substitution:1-decanol from natural oil sources competes in surfactant applications where linearity enhances biodegradation performance.
Strategic Opportunities
- Indian personal care expansion:BIS standards alignment and CDSCO cosmetic ingredient pathways create first-mover positioning for pharmaceutical-grade suppliers.
- MoCRA fragrance allergen rules:FDA disclosure mandates are elevating documentation premiums for compliant cosmetic-grade alcohols in US formulations.
- Bio-based hydroformylation:Renewable nonene from biomass gasification is converging with conventional hydrogenation infrastructure to unlock carbon-intensity certifications.
Industry Challenges
- Compendial certification timelines:Ph.Eur. and USP monograph updates require 18-24 month validation cycles, delaying new capacity commercialization.
- Multi-grade campaign switching:Industrial, cosmetic, and pharmaceutical grades demand separate quality systems, complicating asset utilization planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isodecanol Market |
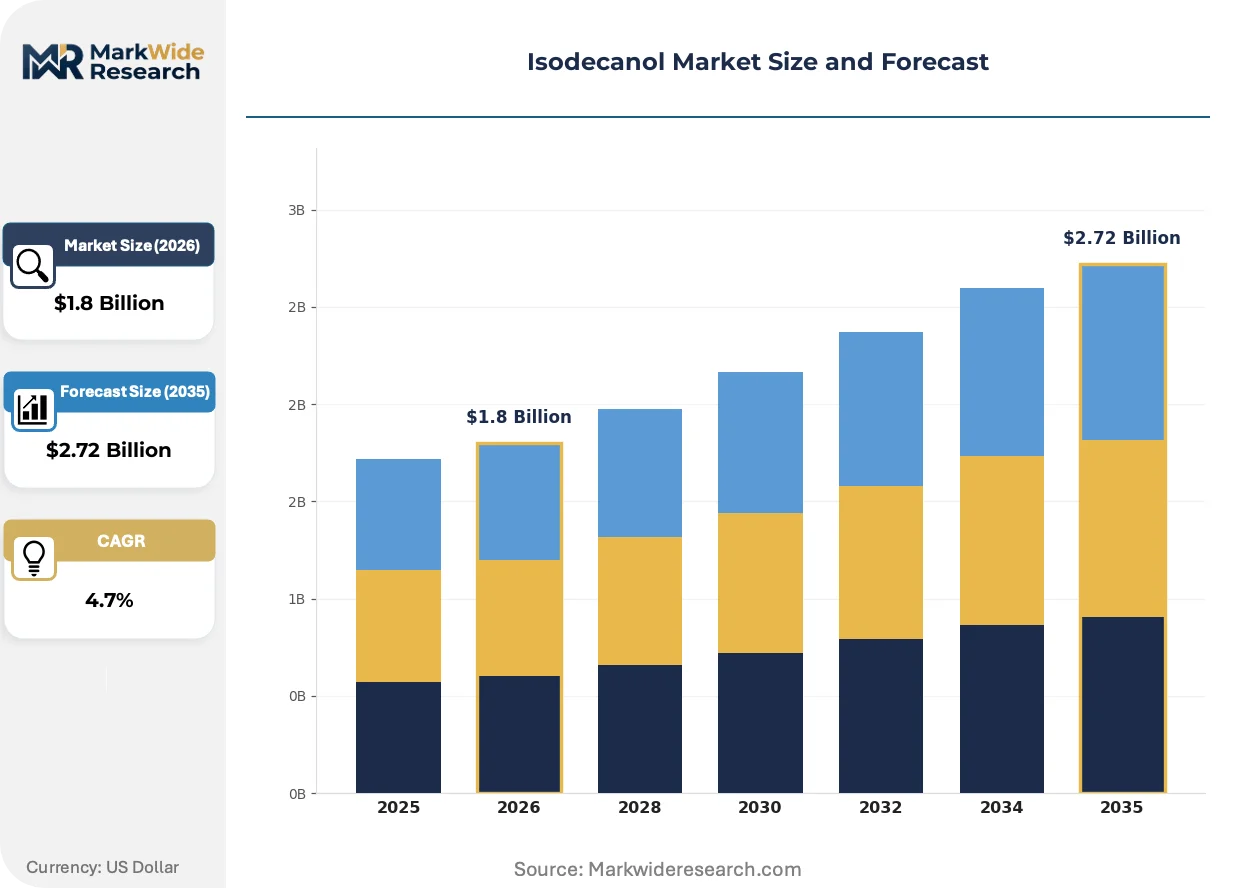
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Industrial Grade, Food Grade, Pharmaceutical Grade End Use Industry: Personal Care, Pharmaceuticals, Agrochemicals, Lubricants Application: Solvent, Emollient, Surfactant, Thickener Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | BASF SE, Sasol Limited, Evonik Industries AG, Jarchem Industries Inc, New Japan Chemical Co, Kokyu Alcohol Kogyo, Kisco Ltd, ExxonMobil Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isodecanol Market Strategic Shifts
Process intensification and regulatory disclosure mandates are bifurcating the isodecanol value chain into commodity lubricant feedstocks and certified cosmetic intermediates with diverging technical requirements.
Membrane-based hydrogenation catalyst recovery is fragmenting conventional fixed-bed reactor economics. Specialty chemical producers in Ludwigshafen and Marl are piloting ceramic membrane units that cut precious metal losses by half. This technology is compressing capital intensity barriers for mid-scale pharmaceutical-grade entrants.
EPA TSCA Section 5 notification requirements are extending lead times for new chemical introductions in US surfactant applications. The agency's systematic review of C10 alcohol ethoxylates is forcing reformulation documentation for cleaning product manufacturers. Personal care brands are accelerating pre-manufacture notice submissions to secure 2026-2027 formulation windows.
Specification-driven procurement is consolidating buyer power among multinational personal care houses. Tier-1 formulators in Germany and France now mandate ISO 16128-compliant certificates of origin, displacing spot-market sourcing for premium skincare lines. This pattern is most pronounced in emollient applications where brand positioning depends on ingredient traceability claims.
Isodecanol Market Segmentation
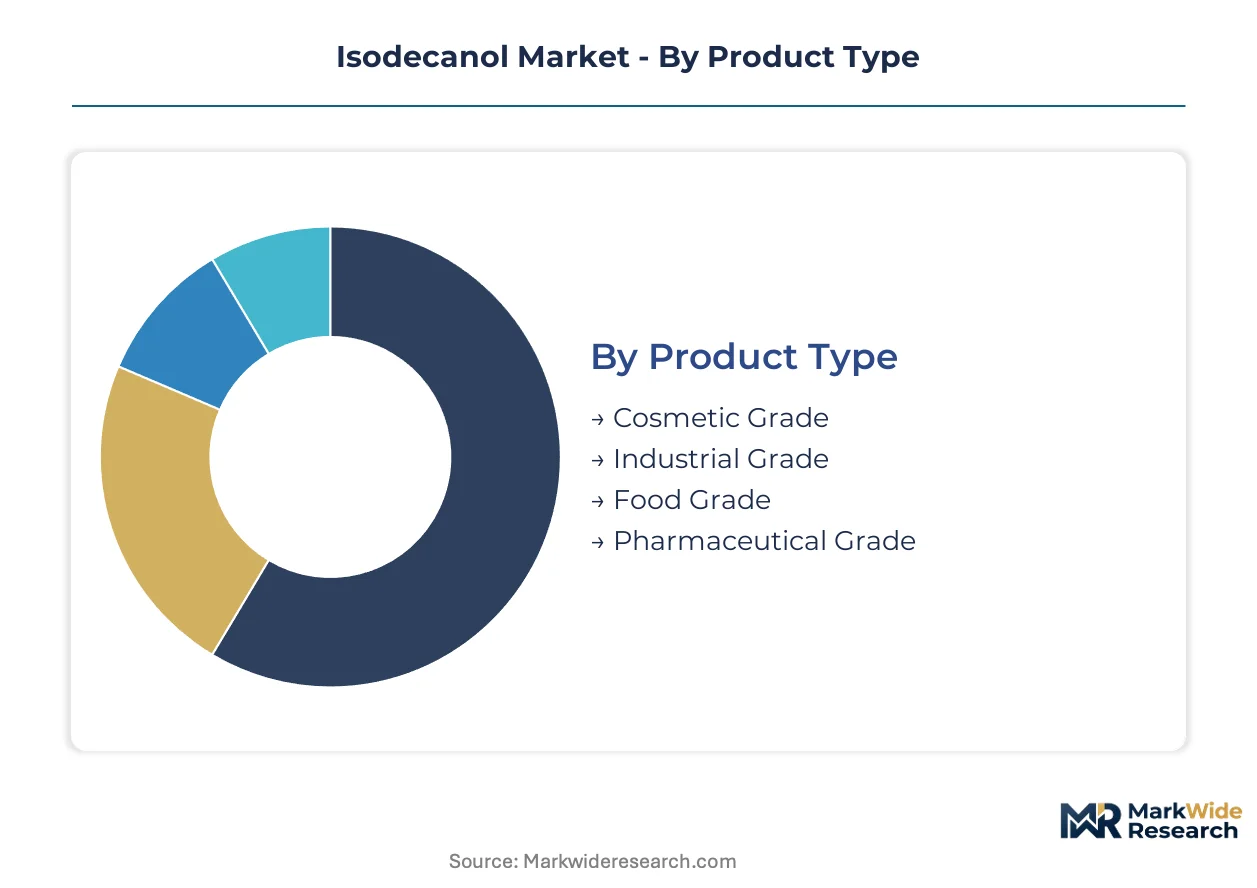
Isodecanol grades diverge sharply in purity thresholds, regulatory documentation, and customer procurement behavior. Segmentation by certification tier and end-use specification determines supplier margin structures and asset configuration decisions across the value chain.
Product Type:
Domestic consumption concentrates on industrial-grade material for agrochemical and lubricant intermediates, while cosmetic and pharmaceutical grades flow predominantly to export-led personal care and drug manufacturing hubs in Germany and France.
- Cosmetic Grade:ISO 16128-compliant material with sub-100 ppm impurity ceilings for premium skincare emollients. German formulators in Ludwigshafen and Düsseldorf anchor demand as brand houses mandate traceable C10 alcohol certificates for clean-label positioning.
- Industrial Grade:Standard hydroformylation output serving agrochemical ester intermediates and synthetic lubricant base stocks. Volume concentrates in domestic German chemical manufacturing clusters with integrated nonene supply.
- Food Grade:Limited application scope confined to food-contact packaging additives and processing aids. Regulatory clearance through EFSA and national food safety authorities constrains viable supplier pool.
- Pharmaceutical Grade:USP-NF and Ph.Eur. monograph-compliant material for active pharmaceutical ingredient synthesis and excipient applications. Dedicated hydrogenation trains and 18-24 month validation cycles restrict capacity expansion.
Industrial grade commands the established base. The steepest expansion runs through cosmetic grade.
End Use Industry:
Customer concentration patterns split between multinational personal care houses demanding certified grades and regional agrochemical blenders purchasing industrial material on spot contracts.
- Personal Care:Premium skincare and rinse-off formulations drive cosmetic-grade uptake. French and German brand owners enforce ISO 16128 documentation for emollient and surfactant applications, displacing uncertified supply.
- Pharmaceuticals:API synthesis and topical drug delivery systems require compendial-grade material. EMA marketing authorization pathways and USP monograph compliance create dual-hemisphere regulatory barriers for entrants.
- Agrochemicals:Ester-based adjuvants and solvent systems consume industrial-grade volumes. Seasonal planting cycles in European agricultural regions generate predictable but price-sensitive demand patterns.
- Lubricants:Synthetic ester base stocks for high-performance industrial and automotive applications. Fischer-Tropsch-derived C10 alcohols compete with petrochemical routes on carbon-intensity credentials.
Agrochemicals anchor volume throughput. Personal care generates the fastest margin expansion.
Application:
Functional performance requirements dictate grade selection, with emollient and surfactant applications commanding premium positioning against commodity solvent uses.
- Solvent:Industrial-grade material dissolving agrochemical actives and cleaning formulations. Cost-driven substitution pressure from linear decanol alternatives limits pricing power.
- Emollient:Branched-chain structure delivers spreadability and skin-feel properties in premium skincare. German and French formulators specify cosmetic-grade certificates for mass-market and prestige lines alike.
- Surfactant:Alcohol ethoxylate feedstocks for low-irritancy rinse-off products. EPA TSCA Section 5 notification requirements extend lead times for new US product introductions.
- Thickener:Viscosity modification in personal care and industrial formulations. Smaller addressable market with limited grade differentiation.
Solvent applications absorb the volume base. Surfactant deployment climbs fastest on personal care reformulation trends.
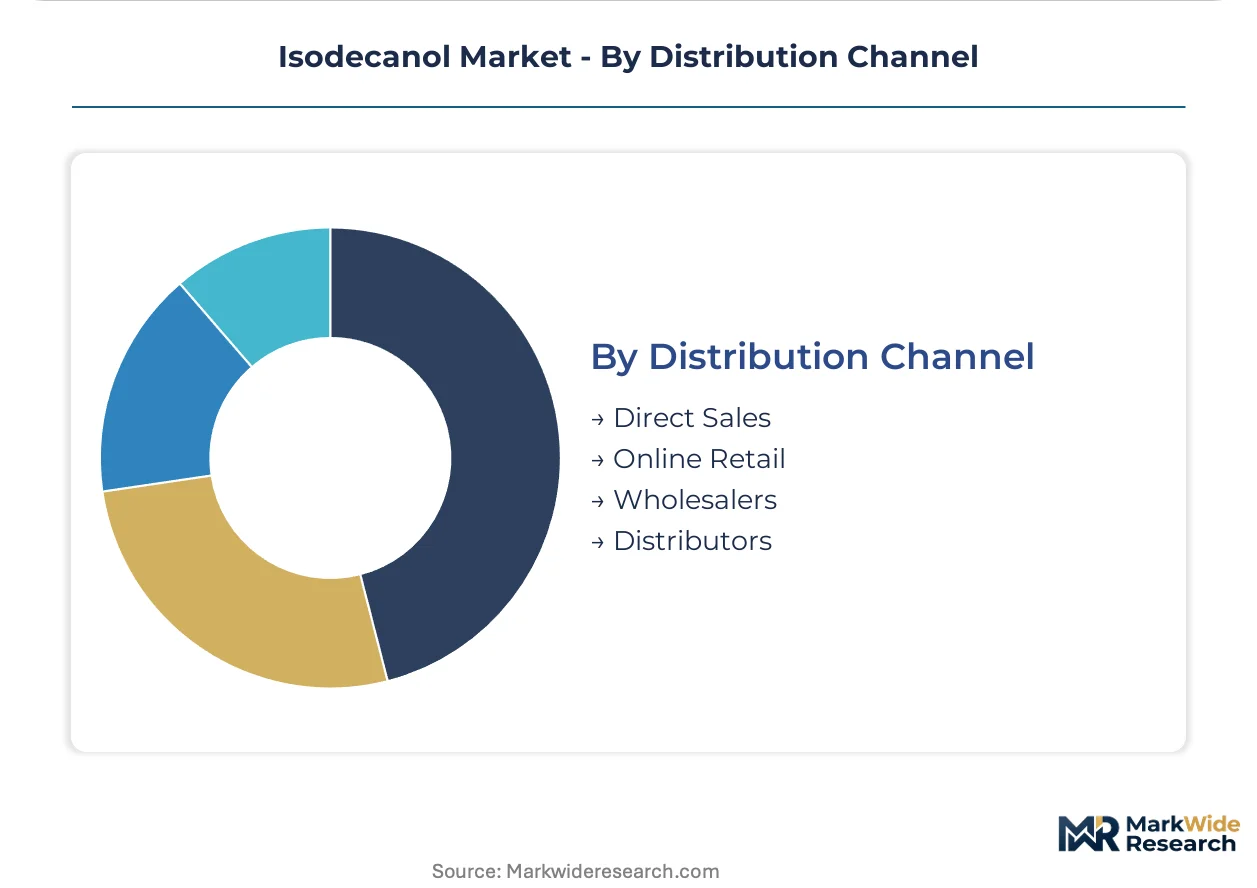
Distribution Channel:
Procurement patterns stratify by customer scale and certification requirements, with direct relationships dominating premium grades and intermediaries handling commodity flows.
- Direct Sales:Long-term contracts linking BASF SE and Evonik Industries AG outputs to multinational personal care and pharmaceutical manufacturers. Certificate-of-origin documentation and audit rights justify relationship investment.
- Online Retail:Emerging pathway for small-batch cosmetic-grade purchases by independent formulators and regional blenders. Limited current penetration constrained by hazardous material shipping regulations.
- Wholesalers:Industrial-grade volume aggregation for agrochemical and lubricant compounders. Price transparency and inventory availability drive selection criteria.
- Distributors:Regional coverage for mid-tier personal care manufacturers lacking direct supplier relationships. Technical support and local regulatory guidance add service value.
Direct sales lock in the premium tier. Distributor engagement expands most quickly among mid-scale formulators seeking certified supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration deadlines under ECHA are compressing supplier margins as purity documentation costs escalate for cosmetic-grade isodecanol destined for European personal care formulations.
Germany
Specialized alcohol production clusters in Ludwigshafen and Marl anchor European pharmaceutical-grade supply. ECHA REACH mandates govern substance identity and impurity profiles for substance registration. BASF SE and Evonik Industries AG sustain integrated C10 alcohol streams through dedicated hydrogenation trains serving cosmetic and drug manufacturing hubs.
United States
EPA TSCA Section 5 notification requirements extend lead times for new surfactant introductions in personal care and cleaning products. FDA cosmetic ingredient regulations and impending MoCRA fragrance allergen disclosure rules elevate documentation burdens for suppliers. Gulf Coast petrochemical corridors concentrate hydroformylation capacity for industrial-grade material serving agrochemical and lubricant compounders.
France
Premium skincare formulators in Paris and Lyon enforce ISO 16128-compliant certificates of origin for emollient applications. ANSM and CNIL oversight intersect with ECHA REACH implementation for cosmetic-grade market access. Brand houses mandate traceable C10 alcohol documentation, displacing spot-market sourcing for mass-market and prestige lines alike.
India
BIS standards alignment and CDSCO cosmetic ingredient pathways create first-mover positioning for pharmaceutical-grade suppliers targeting personal care expansion. Central Pollution Control Board mandates shape industrial alcohol production environmental compliance. Maharashtra and Gujarat chemical manufacturing zones concentrate surfactant intermediate demand from regional agrochemical blenders.
South Africa
Fischer-Tropsch-derived C10 alcohol platforms diversify feedstock origins beyond conventional petrochemical routes for lubricant and agrochemical intermediates. Department of Trade, Industry and Competition industrial policy supports gas-to-liquid technology deployment. Sasol Limited anchors African supply through its Secunda and Sasolburg integrated complexes serving domestic and export markets.
Isodecanol Market Competitive Environment
Player mix skews toward integrated petrochemical majors and specialty alcohol producers with compendial certification capabilities. Tier-1 suppliers command premium positioning through dedicated pharmaceutical-grade assets, while mid-scale operators compete on industrial-grade volume and spot-market responsiveness. Strategic archetypes include backward-integrated olefins producers, Fischer-Tropsch specialists, and high-purity cosmetic-grade formulators. Dominant competitive moves center on multi-grade campaign flexibility investments and regulatory documentation capabilities for REACH and FDA compliance.
Within the integrated petrochemical tier, BASF SE and Sasol Limited exemplify divergent feedstock strategies—hydroformylation of petrochemical nonene versus gas-to-liquid Fischer-Tropsch synthesis. Evonik Industries AG occupies a position among European specialty chemical producers focused on high-purity grades for personal care markets. These three entities represent the structural spectrum from commodity lubricant feedstocks through certified cosmetic intermediates with diverging technical requirements and margin profiles.
| Leading Market Players |
|---|
| BASF SE |
| Sasol Limited |
| Evonik Industries AG |
| Jarchem Industries Inc |
| New Japan Chemical Co |
| Kokyu Alcohol Kogyo |
| Kisco Ltd |
| ExxonMobil Corporation |
| Arkema |
| Others |
Value Chain & Pricing Dynamics
REACH registration mandates under ECHA simultaneously gate supplier qualification and amplify price differentiation across cosmetic-grade isodecanol tiers. Pharmaceutical and personal care formulators now pay substantial documentation premiums for REACH-compliant certificates, compressing spot-market viability for uncertified material.
Pricing Analysis
Certification level (ISO 16128 and USP-NF/Ph.Eur. compendial grades) creates the primary spread between commodity industrial material and premium cosmetic-pharmaceutical tiers. Three-tier pricing structure across pharmaceutical, cosmetic-certified, and industrial grades reflects hydrogenation train dedication and validation cycle investments. Cost compression in industrial-grade segments stems from nonene feedstock volatility and linear C10 alcohol substitution pressure. Agrochemical blenders exhibit highest price sensitivity on spot contracts, while multinational personal care houses absorb certification premiums for traceable supply security.
Supply Chain Analysis
Strategic stockpiling of nonene feedstock and precious metal catalysts dominates inventory strategy given 18-24 month pharmaceutical-grade validation timelines. Supply concentrates in Germany, South Africa, and the United States through integrated petrochemical and Fischer-Tropsch platforms. Hydroformylation catalysts, hydrogen supply, and compendial-grade packaging materials constitute critical input dependencies. Single-source vulnerability runs through Ludwigshafen and Secunda production clusters for European pharmaceutical-grade supply. Distribution runs through direct long-term contracts for premium tiers and wholesaler aggregation for industrial-grade spot volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isodecanol demand tracks agricultural planting cycles and personal care formulation refresh schedules, positioning the market for cyclical recovery as premium skincare investment resumes post-inventory destocking.
For Market Incumbents: Consolidate pharmaceutical-grade capacity through dedicated hydrogenation train investments in Ludwigshafen and Marl clusters to defend against Fischer-Tropsch platform expansion. Deepen backward integration into nonene supply or captive catalyst recovery systems to offset precious metal volatility. Lock multinational personal care houses into certificate-of-origin contracts before MoCRA disclosure mandates escalate documentation costs. For New Entrants and Emerging Players: Differentiate on bio-based hydroformylation pathways using renewable nonene from biomass gasification to capture carbon-intensity premiums in European cosmetic markets. Target Indian personal care expansion through CDSCO-aligned pharmaceutical-grade pathways where BIS standards create first-mover positioning. Pursue membrane-based catalyst recovery technology to compress capital barriers for mid-scale pharmaceutical-grade entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors with underutilized C10 alcohol streams lacking compendial certification infrastructure. Long-term viability hinges on regulatory documentation capabilities rather than commodity scale. Watch EPA TSCA Section 5 notification backlogs as inflection signal—clearance delays would accelerate reformulation demand for pre-qualified surfactant feedstocks.| Strategic Initiative | Industry Significance |
|---|---|
| Compendial Certification Investment | USP-NF and Ph.Eur. monograph compliance unlocks pharmaceutical-grade margins and restricts competitor entry. |
| Backward Integration into Nonene | Captive propylene oligomerization capacity insulates hydroformylation economics from cracker rate volatility. |
| Membrane Catalyst Recovery Deployment | Ceramic membrane pilots in Ludwigshafen cut precious metal losses and compress capital intensity for entrants. |
| Long-term Supply Agreement with Personal Care Houses | ISO 16128-compliant contracts with German and French formulators secure premium tier offtake visibility. |
| Bio-based Hydroformylation Pathway | Renewable nonene convergence with conventional hydrogenation infrastructure unlocks carbon-intensity certifications. |
Study Parameters
Desk research of trade flow databases, ECHA REACH registration filings, and SEC chemical sector disclosures preceded structured interviews with hydroformylation plant managers, personal care procurement leads, and pharmaceutical excipient sourcing directors. Primary fieldwork across Ludwigshafen, Marl, and Secunda production clusters validated capacity utilization and grade-switching economics. Secondary triangulation drew from customs data, Cefic alcohol market reports, and FDA MoCRA guidance documents. Bottom-up segmentation modeling and top-down macroeconomic anchoring converged on volume and value estimates.
Variance decomposition across grade tier, end-use industry, and regional production hub shaped the analytical framework over the projection horizon. Modeled dimensions span industrial-cosmetic-pharmaceutical grade stratification, personal care-pharmaceutical-agrochemical-lubricant end-use splits, and hydroformylation versus Fischer-Tropsch feedstock origin. CAGRs derived from segment-level growth rate aggregation with cross-validation against macroeconomic drivers including agricultural input costs and premium skincare consumption indices.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or personal care certification adoption would require recalibration. Forecasts reflect assumptions on regulatory documentation cost trajectories and nonene supply elasticity. Revision becomes warranted when EPA TSCA Section 5 notification timelines or ECHA monograph update cycles cross threshold delays that strand formulation investments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
Food Grade Calcium Phosphate Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Spain Food Enzymes Market
Food Additives and Ingredients
Africa Food Enzymes Market