
 Chymosine Market | 2026-2036
Chymosine Market Size, Share, and Industry Trends Forecast 2026-2036
Chymosine Market Analytics
Microbial rennet grade upgrades is bifurcating the Chymosine Market into premium fermentation-certified and conventional animal-derived tiers. Chr. Hansen Holding A/S leverages its bioscience platform to dominate recombinant chymosin supply for large dairy cooperatives. DSM Food Specialties anchors European demand through its proprietary fermentation strains and kosher certification coverage. DuPont de Nemours, Inc. competes on manufacturing scale across North American cheese processing corridors.
Chymosine is an aspartic protease enzyme traditionally extracted from calf stomach lining or produced via microbial fermentation, with recombinant variants achieving coagulation activity at pH 6.0-6.5 and temperatures between 30-35°C; its primary function remains milk clotting in cheese production, where it cleaves kappa-casein to initiate curd formation. Fermentation-derived chymosin now leads volume growth as microbial rennet displaces animal rennet in applications where vegetarian labeling commands retail shelf access. Dairy Products application segments concentrate margin pools in aged cheese varieties requiring precise proteolytic activity control, while Meat Processing represents a smaller but technically demanding outlet where chymosin aids protein restructuring.
FDA food enzyme regulations in the United States and EFSA novel food assessments in Europe govern recombinant chymosin approval pathways, with both frameworks tightening traceability requirements for genetically modified production strains. ISO 22000 and FSSC 22000 certification standards shape supplier qualification for multinational dairy manufacturers seeking uniform safety documentation across plants. Stakeholders must monitor evolving clean-label definitions and regional GMO disclosure mandates that could recalibrate sourcing strategies between animal, microbial, and fermentation-derived supply tiers.
Market Dynamics
Vegetarian certification requirements are compressing animal-derived chymosin procurement channels across European and North American retail dairy supply chains. Fermentation-derived alternatives now dominate new capacity investments as kosher, halal, and clean-label mandates recalibrate sourcing hierarchies.
Growth Catalysts
- EFSA novel food assessments:Streamlined approval pathways for recombinant chymosin strains accelerate commercialization timelines for fermentation-based suppliers targeting EU dairy cooperatives.
- Artisan cheesemaking clusters:Concentrated demand in France, Wisconsin, and the Netherlands creates volume anchors that justify dedicated microbial rennet production facilities.
- Precision proteolytic control:Aged cheese varieties requiring exact coagulation activity specifications pull premium-grade fermentation chymosin into high-margin product lines.
Market Restraints
- Input cost volatility:Fermentation media and bioreactor energy inputs expose microbial chymosin producers to commodity price swings that compress margin stability.
- Supply concentration risk:Three bioscience platforms control recombinant strain intellectual property, creating bottleneck vulnerability for dairy manufacturers seeking multi-source qualification.
- GMO disclosure mandates:Divergent national labeling requirements for genetically modified production strains fragment regulatory compliance costs across export markets.
Strategic Opportunities
- Meat processing applications:Protein restructuring uses in processed meat products represent underexploited technical outlets where chymosin functionality commands formulation premiums.
- ISO 22000 certification gaps:Mid-tier dairy processors in Eastern Europe lack standardized safety documentation, creating qualification service opportunities for certified suppliers.
- Clean-label convergence:Vegetarian, non-GMO, and allergen-free claim stacking enables product line extensions that capture shelf space in specialty retail channels.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in pharmaceutical and industrial enzyme sectors, forcing chymosin producers to compete for specialized personnel.
- Legacy animal rennet integration:Traditional cheesemaking facilities require capital-intensive retrofitting to accommodate microbial chymosin handling and storage protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chymosine Market |
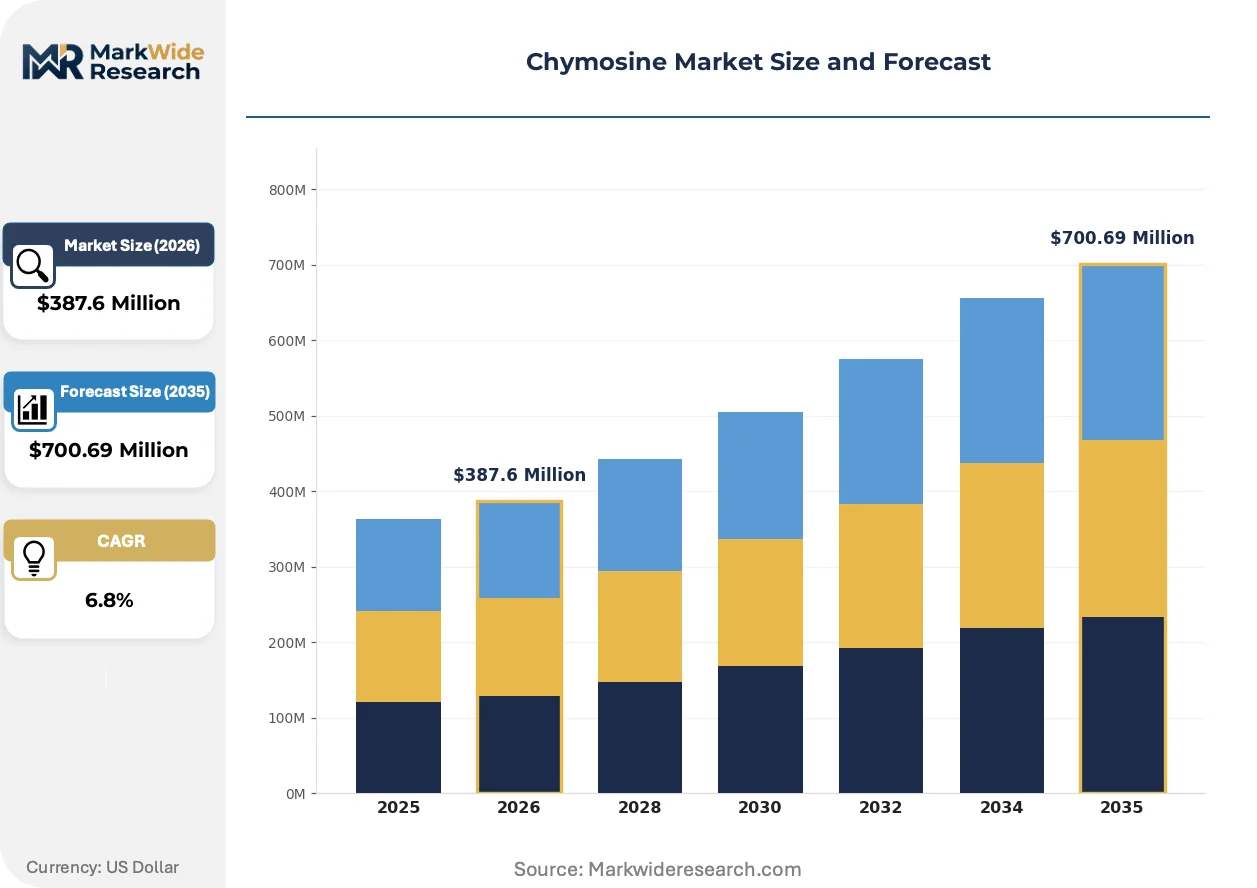
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Rennet, Microbial Rennet, Vegetable Rennet, Others Application: Dairy Products, Meat Processing, Fermentation, Beverages End User: Dairy Manufacturers, Food Processors, Restaurants, Household Distribution Channel: Online Retail, Supermarkets, Direct Sales, Distributors |
| Companies Covered | Chr. Hansen Holding A/S, DSM Food Specialties, DuPont de Nemours, Inc., Sacco S.r.l., Mayasan, Amano Enzyme Inc., Advanced Enzyme Technologies Ltd., Biocatalysts Ltd., Maysa Gida, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chymosine Market Evolving Landscape
Recombinant DNA platforms are fragmenting the supplier base by enabling specialized strain development outside incumbent bioscience conglomerates. This technological diffusion compresses barriers to entry while intensifying performance differentiation around coagulation specificity and thermal stability.
CRISPR-edited microbial strains is decomposing the traditional trade-off between fermentation yield and proteolytic precision. Artisan producers in the Netherlands and Wisconsin adopt these variants for heritage cheese varieties requiring exact curd texture control. The technology is decomposing volume-based procurement contracts by enabling batch-specific enzyme customization that commands spot-market premiums.
EU Green Deal agricultural sustainability metrics now extend to dairy processing inputs, requiring chymosin suppliers to document carbon intensity across fermentation and downstream processing stages. Large cooperatives in France and Germany embed these requirements into tender specifications, filtering supplier pools by lifecycle assessment compliance. Smaller microbial rennet producers face consolidation pressure as certification costs outpace revenue scale.
Direct strain licensing between biotech developers and dairy processors is compressing traditional distribution hierarchies. Large cheese manufacturers in Wisconsin and the Netherlands now negotiate proprietary fermentation contracts that bypass multi-product enzyme distributors. This channel disintermediation concentrates bargaining power with volume buyers while fragmenting price transparency across supply tiers.
Chymosine Market Segmentation
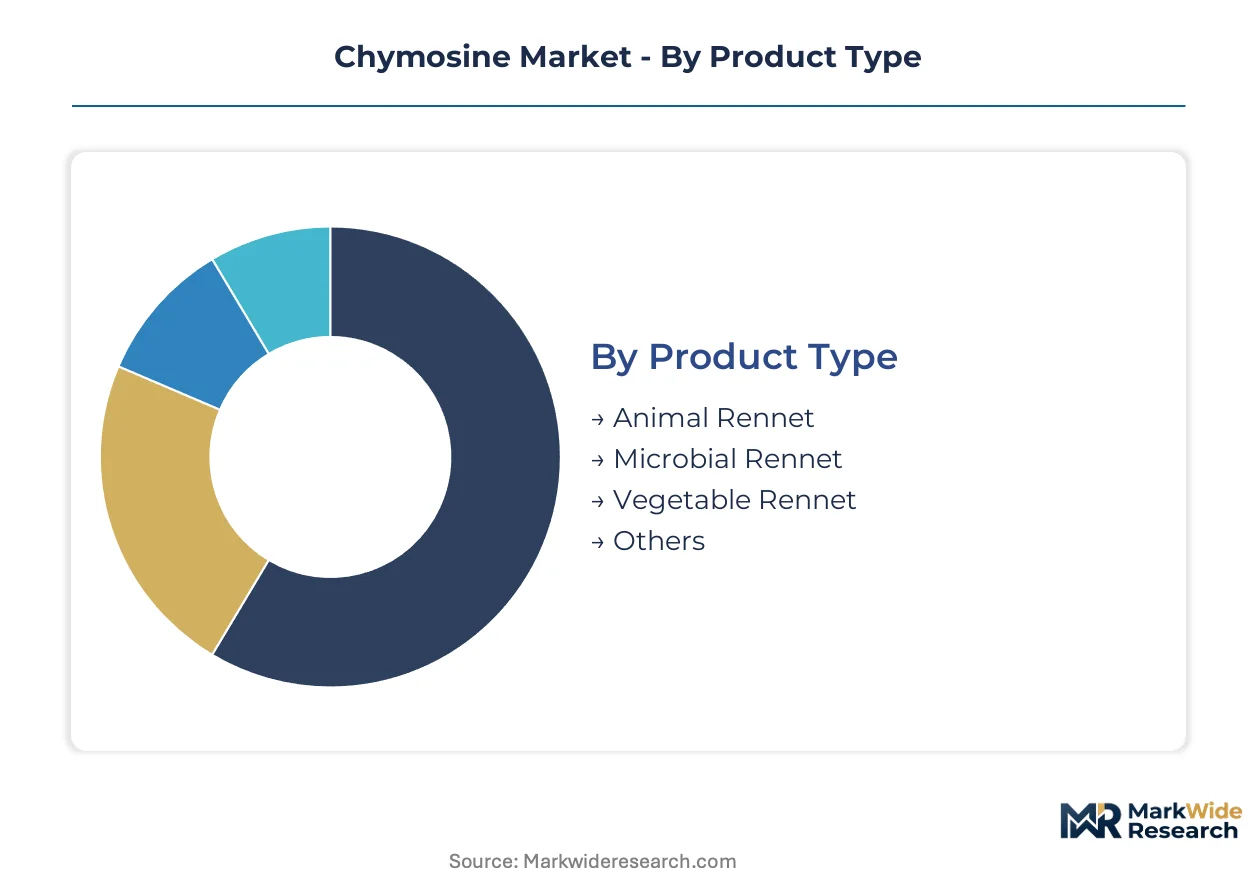
Chymosine procurement strategies diverge sharply across product origins and end-use specifications. Dairy cooperatives structure supplier contracts around certification tiers, while food processors prioritize thermal stability metrics for meat restructuring applications.
Product Type:
Margin pools concentrate in fermentation-derived grades where kosher, halal, and vegetarian certifications command formulation premiums over conventional animal extracts.
- Animal Rennet:Traditional calf stomach extracts deliver proteolytic activity calibrated for aged cheese varieties. Heritage producers in France and Wisconsin maintain contracted supply relationships with abattoir networks, though tightening vegetarian labeling standards compress retail channel access.
- Microbial Rennet:Fermentation-derived chymosin achieves coagulation specificity matching animal-derived equivalents at pH 6.0-6.5. DSM Food Specialties and Chr. Hansen dominate strain intellectual property, with recombinant variants displacing animal rennet in applications requiring clean-label positioning.
- Vegetable Rennet:Plant-derived proteases from thistle and fig extracts serve niche artisan cheesemaking segments where GMO-free claims outweigh coagulation efficiency trade-offs.
- Others:Synthetic peptide mimics and engineered enzyme variants occupy experimental formulation pipelines targeting meat processing applications.
Animal rennet holds installed capacity in traditional cheesemaking clusters. Microbial rennet is rotating up the share rankings as certification mandates reshape procurement hierarchies.
Application:
Volume concentrates in milk clotting operations, though protein restructuring functionality in meat processing commands higher per-kilogram pricing due to technical complexity.
- Dairy Products:Cheese production consumes chymosin for kappa-casein cleavage initiating curd formation. Precision proteolytic control requirements in aged varieties pull premium-grade fermentation chymosin into high-margin product lines across Wisconsin and Dutch processing corridors.
- Meat Processing:Protein restructuring applications exploit chymosin's aspartic protease activity to modify myofibrillar texture. Processed meat manufacturers in Germany and the United States adopt enzyme-assisted formulations for yield optimization and texture engineering.
- Fermentation:Chymosin serves as a processing aid in specialized fermentation protocols for protein hydrolysate production.
- Beverages:Limited application in protein stabilization for functional drink formulations, primarily in Asian markets seeking texture modification.
Dairy Products anchors volume demand through established cheesemaking infrastructure. Meat Processing is climbing the fastest as protein restructuring technology diffuses beyond traditional sausage applications.
End User:
Procurement scale and specification complexity separate industrial dairy manufacturers from fragmented food service and household segments.
- Dairy Manufacturers:Large cooperatives negotiate multi-year fermentation contracts with bioscience suppliers, embedding ISO 22000 certification and carbon intensity documentation into tender specifications. Direct strain licensing arrangements bypass traditional enzyme distributors in France and the Netherlands.
- Food Processors:Meat and alternative protein manufacturers source chymosin for texture engineering applications, with smaller volume requirements limiting supplier qualification leverage.
- Restaurants:Artisan pizzeria and farm-to-table operators in Italy and the United States purchase small-batch vegetable rennet for house-made cheese programs.
- Household:Home cheesemaking kits and specialty retail channels serve hobbyist segments with pre-measured enzyme packets.
Dairy Manufacturers concentrate purchasing power through volume aggregation. Restaurants are gaining share fastest as craft food movements expand enzyme literacy among culinary professionals.
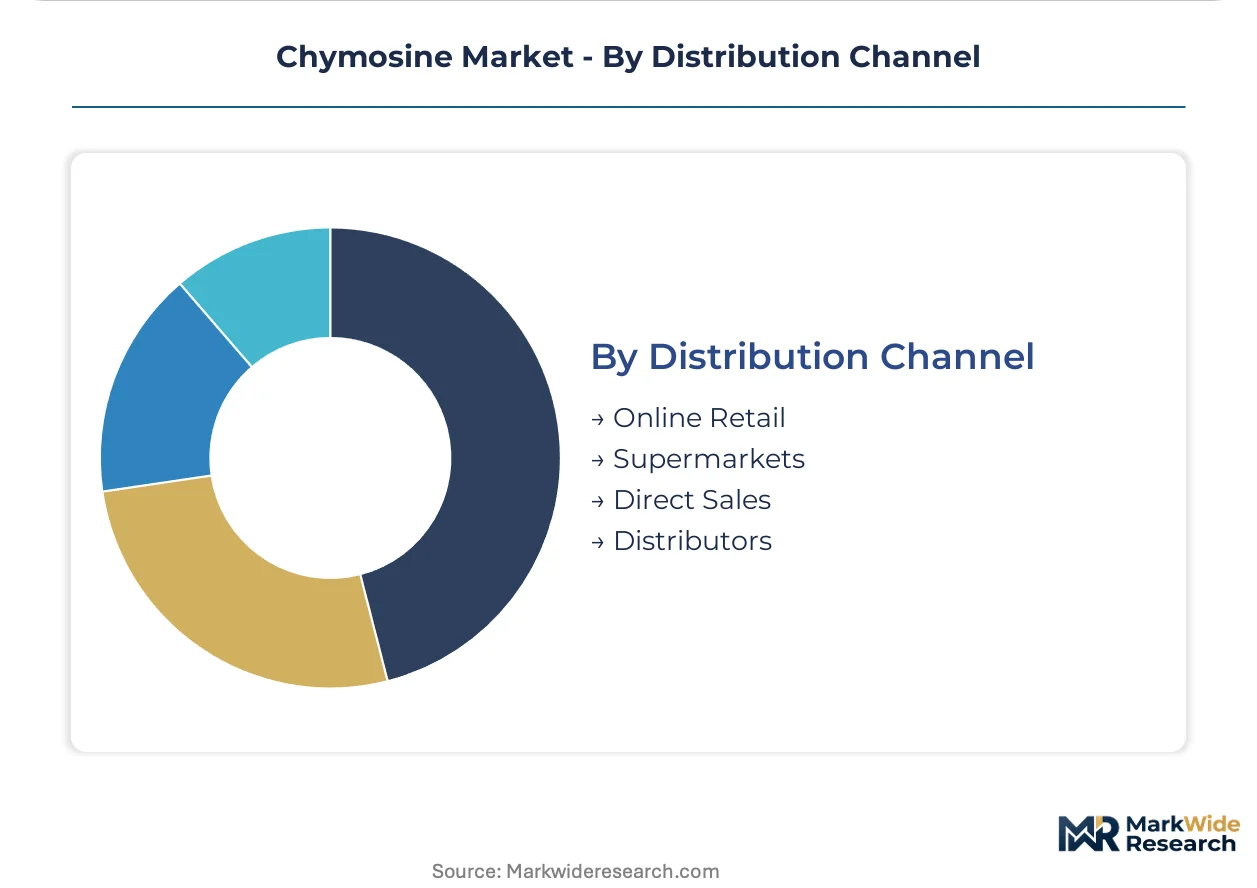
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to production clusters.
- Direct Sales:Large dairy cooperatives in Wisconsin and the Netherlands negotiate proprietary fermentation contracts bypassing multi-product distributors. Chr. Hansen and DSM Food Specialties deploy technical service teams for strain optimization support.
- Distributors:Regional enzyme distributors serve mid-tier processors requiring multi-product portfolios and consolidated logistics across Eastern European markets.
- Supermarkets:Retail channels supply household segments and small commercial kitchens with standardized enzyme preparations.
- Online Retail:E-commerce platforms aggregate specialty and artisan-grade products for home cheesemakers and small restaurant operations.
Direct Sales maintains pricing control for volume buyers. Online Retail is expanding most quickly as digital procurement penetrates specialty ingredient sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chr. Hansen and DSM Food Specialties concentrate microbial chymosin supply through fermentation facilities in Denmark and the Netherlands. Dairy cooperatives in France, Wisconsin, and the Netherlands anchor procurement volume as vegetarian labeling mandates reshape sourcing hierarchies across retail supply chains.
United States
Wisconsin cheese processing corridors and California dairy cooperatives drive fermentation-derived chymosin procurement as FDA food enzyme regulations govern recombinant strain approvals. The FDA maintains traceability requirements for genetically modified production strains. Large manufacturers in the Midwest negotiate direct strain licensing contracts that bypass traditional enzyme distributors.
France
Artisan and industrial cheesemaking clusters in Normandy and the Alps concentrate demand for premium-grade chymosin with precise proteolytic control. EFSA novel food assessments streamline approval pathways for fermentation-based suppliers targeting EU dairy cooperatives. The EU Green Deal agricultural sustainability metrics now extend to dairy processing inputs, requiring carbon intensity documentation from suppliers.
Netherlands
DSM Food Specialties anchors European microbial rennet supply through proprietary fermentation strains developed in Dutch biotechnology corridors. REACH regulations govern chemical substance registration for processing aids used in dairy applications. Direct proprietary fermentation contracts between biotech developers and large cheese manufacturers compress traditional distribution hierarchies in the Randstad region.
Germany
Meat processing manufacturers in Bavaria and North Rhine-Westphalia adopt chymosin for protein restructuring applications in processed sausage formulations. The German Federal Office of Consumer Protection and Food Safety enforces GMO disclosure mandates that fragment regulatory compliance costs across export markets. Industrial enzyme distributors serve mid-tier processors requiring consolidated logistics across Eastern European markets.
Denmark
Chr. Hansen Holding A/S dominates recombinant chymosin supply for large dairy cooperatives through bioscience platforms concentrated in Copenhagen-area research corridors. Danish Veterinary and Food Administration regulations align with EFSA frameworks for novel food assessments. Technical service teams deploy strain optimization support for fermentation contracts negotiated directly with volume buyers.
Chymosine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the chymosine supply base. Bioscience conglomerates with proprietary fermentation platforms control premium-grade recombinant strain intellectual property, while mid-tier enzyme specialists compete on price-accessible microbial rennet for conventional applications. The market structure separates into three strategic archetypes: integrated bioscience platforms, specialized enzyme manufacturers, and regional distributors with multi-product portfolios. Dominant competitive moves include direct strain licensing arrangements that bypass traditional distribution channels and capacity expansion in fermentation facilities serving kosher and halal certification requirements.
Among Denmark-based bioscience platforms, Chr. Hansen Holding A/S occupies a position exemplifying integrated fermentation technology leadership, while DSM Food Specialties represents the Dutch archetype of proprietary strain development. DuPont de Nemours, Inc. anchors the North American scale-driven tier. Sacco S.r.l. and Mayasan sit within specialized enzyme manufacturing archetypes serving regional dairy processing markets with certification-specific product lines.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DSM Food Specialties |
| DuPont de Nemours, Inc. |
| Sacco S.r.l. |
| Mayasan |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies Ltd. |
| Biocatalysts Ltd. |
| Maysa Gida |
| Others |
Value Network & Pricing Analysis
Fermentation-derived chymosin displacement of animal rennet is redrawing supply geography toward Danish and Dutch biotechnology corridors while compressing pricing premiums for kosher-certified grades. This substitution dynamic concentrates procurement leverage with Wisconsin and French dairy cooperatives that negotiate multi-year fermentation contracts.
Pricing Analysis
EFSA novel food assessments dictate the pricing tier structure by stratifying certification costs across animal, microbial, and recombinant grades. Three-tier pricing separates fermentation-certified premium from standard microbial and economy animal-derived tiers. Cost compression in animal rennet is intensifying because vegetarian labeling standards tighten retail channel access. Artisan producers in France demonstrate lowest price sensitivity, while Eastern European mid-tier processors face margin pressure from ISO 22000 qualification requirements.
Supply Chain Analysis
Strain inventory cycles and bioreactor lead times tether downstream dairy manufacturers to quarterly fermentation batch schedules. Supply concentrates in Denmark, the Netherlands, and Wisconsin, where Chr. Hansen and DSM Food Specialties anchor recombinant strain production. Raw material dependencies include fermentation media substrates, bioreactor energy inputs, and downstream filtration resins. Single-source vulnerability concentrates around proprietary strain intellectual property held by three bioscience platforms. Distribution runs through direct licensing arrangements for volume buyers and regional enzyme distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CRISPR-edited microbial strain development is accelerating fermentation yield improvements, creating a high-growth disruption window as precision proteolytic control commands formulation premiums in aged cheese varieties.
For Market Incumbents: Secure proprietary strain intellectual property through direct licensing arrangements with Wisconsin and Dutch dairy cooperatives. Expand fermentation capacity in Denmark to capture kosher and halal certification demand. Defend margin position by embedding carbon intensity documentation into EU Green Deal compliance tiers. For New Entrants and Emerging Players: ISO 22000 certification fast-tracks unlock Eastern European mid-tier dairy processors lacking standardized safety documentation. Target meat processing applications in Germany and the United States where protein restructuring functionality commands technical formulation premiums. Pursue spot-market batch customization for artisan producers in the Netherlands seeking heritage cheese texture control. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microbial enzyme specialists holding regional certification coverage but lacking recombinant strain platforms. Five-to-ten year viability hinges on fermentation scale-up expertise migration from pharmaceutical sectors. Watch for direct strain licensing deal flow between biotech developers and volume cheese manufacturers as channel disintermediation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Strain Licensing | Direct contracts with Wisconsin cooperatives bypass traditional enzyme distributors and compress pricing transparency. |
| Fermentation Capacity Expansion | Dutch and Danish facilities capture kosher and halal certification premiums across EU dairy supply chains. |
| CRISPR Strain Development Partnership | Precision proteolytic control enables batch-specific customization commanding spot-market premiums from artisan producers. |
| Carbon Intensity Documentation Program | EU Green Deal compliance filters supplier pools by lifecycle assessment metrics in French and German tenders. |
| Meat Processing Application Extension | Protein restructuring functionality in German sausage formulations opens technical formulation premium channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food enzyme filings, EFSA novel food assessments, SEC 10-K disclosures, and dairy cooperative procurement records. Primary interviews engaged fermentation technology directors at bioscience platforms, procurement leads at French and Wisconsin dairy cooperatives, regulatory affairs specialists navigating GMO disclosure mandates, and plant managers at mid-tier Eastern European processors. Bottom-up volume triangulation from cheese production data and top-down value estimation from fermentation capacity disclosures were cross-validated.
Segmentation dimensions modeled include product origin tier, application specificity, end-user procurement scale, and geographic certification cluster across the projection horizon. CAGRs were derived from production volume trajectories and pricing tier migration patterns. Forecast inputs incorporated EFSA approval timeline assumptions and EU Green Deal carbon intensity compliance adoption curves.
Decision-makers should treat outputs as directional under stable regulatory approval pathways and sustained vegetarian labeling adoption; material deviation in GMO disclosure mandate harmonization or fermentation energy cost volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Beverage Acidulants Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market