
 Food Grade Calcium Phosphate Market | 2026-2036
Food Grade Calcium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Calcium Phosphate Market Analytics
Clean-label beverage formulators are rotating away from traditional calcium sources toward food-grade calcium phosphates for neutral taste profiles and solubility control. Prayon leverages its integrated phosphate rock-to-specialty-chemicals chain to sustain cost-advantaged supply positions in European markets. Budenheim differentiates through high-purity precipitated calcium phosphates that meet pharmaceutical-adjacent food specifications. Jiangsu Kolod Food Ingredients dominates domestic Chinese distribution channels while extending technical service capabilities to Southeast Asian export customers.
Food grade calcium phosphates comprise purified inorganic salts—primarily dicalcium, tricalcium, and monocalcium phosphates—manufactured via controlled precipitation reactions between phosphoric acid and calcium carbonate or hydroxide, with final products meeting purity thresholds of 34-39% calcium content and strict heavy-metal limits below 10 ppm lead. These compounds function as leavening acids, nutritional fortificants, anti-caking agents, and pH buffers across processed foods, supplements, and prepared animal feeds. Dicalcium phosphate anchors the product type mix due to its established use in baking powders and mineral supplements, though tricalcium phosphate is gaining share in high-density tablet formulations where compressibility matters. Within applications, food fortification occupies the largest revenue pool while nutraceuticals represent the fastest-growing segment as functional food brands seek dual mineral-delivery systems.
The FDA's GRAS notification program and the EPA's effluent guidelines for phosphate manufacturing shape product standards and facility siting decisions for US-based producers. In Europe, EFSA's revised tolerable upper intake levels for calcium and the EU's REACH chemical registration requirements influence formulation ceilings and import documentation burdens. China's SAMR enforces GB standards for food-grade phosphates that increasingly align with Codex Alimentarius specifications, affecting cross-border certificate-of-analysis protocols. Stakeholders must monitor diverging purity standards between jurisdictions and decide whether to pursue multi-certification strategies or geographic specialization in compliance architecture.
Market Dynamics
Clean-label reformulation across beverage and bakery categories is compressing traditional calcium source supply chains while elevating food-grade phosphate specifications. Manufacturers face simultaneous pressure from FDA purity thresholds and EFSA intake ceilings, forcing dual-certification investments or geographic specialization.
Growth Catalysts
- GRAS Notification Pathways:FDA's streamlined self-affirmation process accelerates novel calcium phosphate ingredient approvals for functional food applications.
- Tablet Formulation Demand:Nutraceutical contract manufacturers specify tricalcium phosphate for high-density mineral delivery where compressibility and flow properties outperform carbonate alternatives.
- China Export Infrastructure:Jiangsu and Shandong province producers expand technical-grade capacity serving Southeast Asian fortification programs.
Market Restraints
- Phosphoric Acid Volatility:Sulfuric acid and phosphate rock input costs swing with Moroccan and Chinese mining output fluctuations.
- Heavy Metal Purity Friction:EPA effluent guidelines tighten allowable lead and arsenic residuals in precipitation processes, raising capital intensity for US-based facilities.
- Calcium Carbonate Substitution:Cost-sensitive bakery applications in Latin America retain traditional chalk-based leavening despite inferior neutral taste profiles.
Strategic Opportunities
- India Fortification Mandates:FSSAI's wheat flour and edible oil mineral enrichment directives create technical-grade phosphate demand from domestic and import suppliers.
- Plant-Based Dairy Analogues:Oat and pea protein beverage formulators require soluble calcium systems without grit or precipitation.
- Spray-Dried Agglomeration:Instant beverage premix manufacturers specify free-flowing calcium phosphate granules replacing conventional powder handling.
Industry Challenges
- Analytical Chemistry Talent:ICP-MS heavy metal testing and validation protocols require scarce technicians familiar with both FDA and EFSA certificate-of-analysis formats.
- Multi-Jurisdiction Certification Timelines:Parallel GB standard, REACH dossier, and GRAS notification submissions extend product launch cycles by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Calcium Phosphate Market |
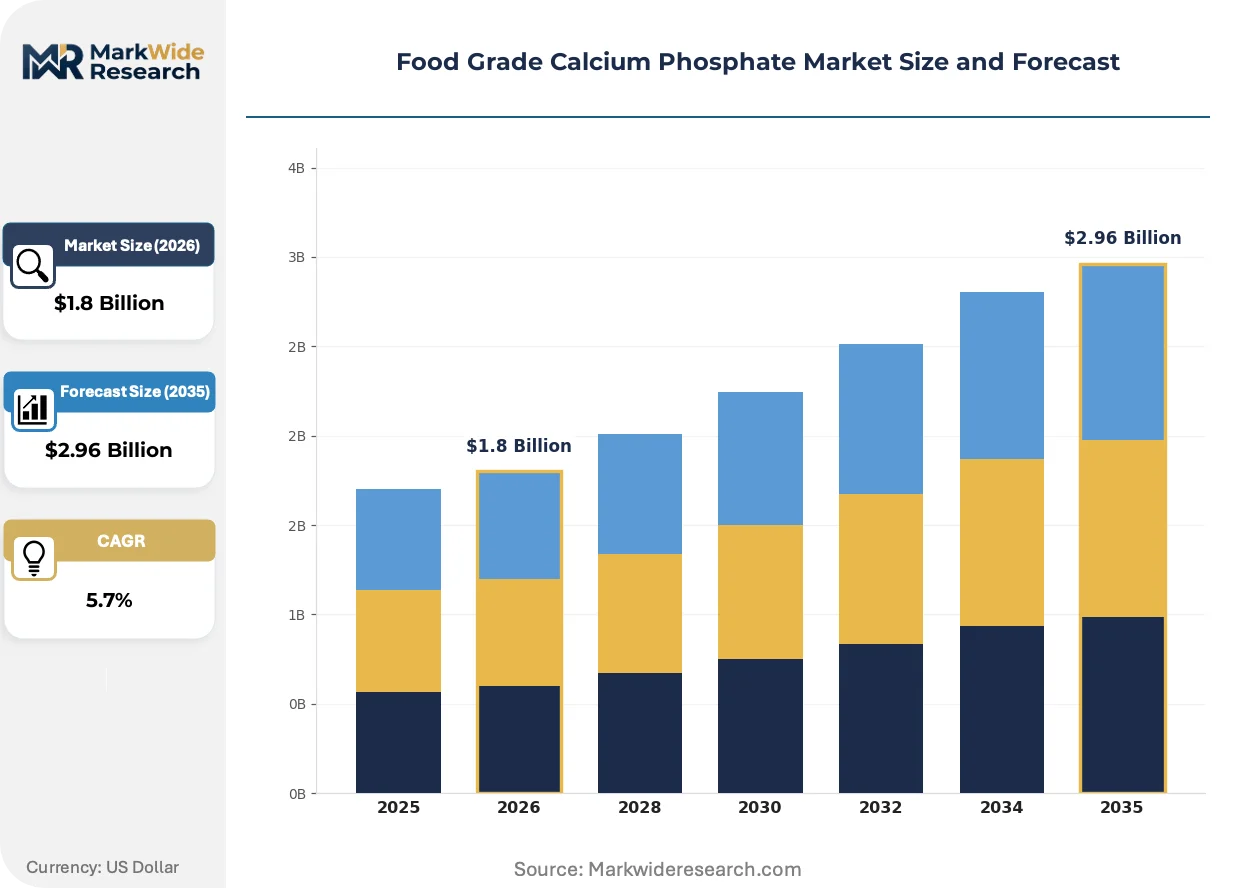
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dicalcium Phosphate, Tricalcium Phosphate, Monocalcium Phosphate, Calcium Phosphate Blends Application: Food Fortification, Dietary Supplements, Animal Feed, Nutraceuticals End User: Food Manufacturers, Pharmaceutical Companies, Feed Producers, Health Food Stores Distribution Channel: Online Retail, Supermarkets, Distributors, Direct Sales |
| Companies Covered | Innophos Holdings Inc., Prayon, Budenheim, ICL PP, Haifa Group, Gadot Biochemical, Hindustan Phosphates, Alfacal, Jiangsu Kolod Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Calcium Phosphate Market Evolving Landscape
Calcium phosphate manufacturing is pivoting from commodity precipitation toward engineered particle architectures that solve specific formulation failures in clean-label applications. Process control, regulatory data infrastructure, and buyer procurement models are shifting in parallel.
Controlled precipitation with real-time laser diffraction monitoring is miniaturizing particle size distributions to sub-10 micron specifications. Nutraceutical tablet manufacturers in Germany and Switzerland adopt these narrow-distribution grades for direct compression without granulation steps. The technology is compressing conventional milling and sieging process steps into single-unit operations.
EFSA's revised tolerable upper intake levels for calcium are forcing reformulation ceilings across EU member states. Food fortification manufacturers must now split mineral delivery across multiple ingredients rather than single high-dose phosphates. The policy is most acute in Scandinavian markets where dairy-calcium baselines already approach threshold levels.
Ingredient procurement through technical service partnerships is displacing transactional spot purchasing among Southeast Asian contract manufacturers. Buyers in Vietnam and Thailand now specify on-site application support and stability testing as contract prerequisites. This behavioral shift is most visible in beverage fortification programs where pH buffering and suspension stability require joint formulation development.
Food Grade Calcium Phosphate Market Segmentation
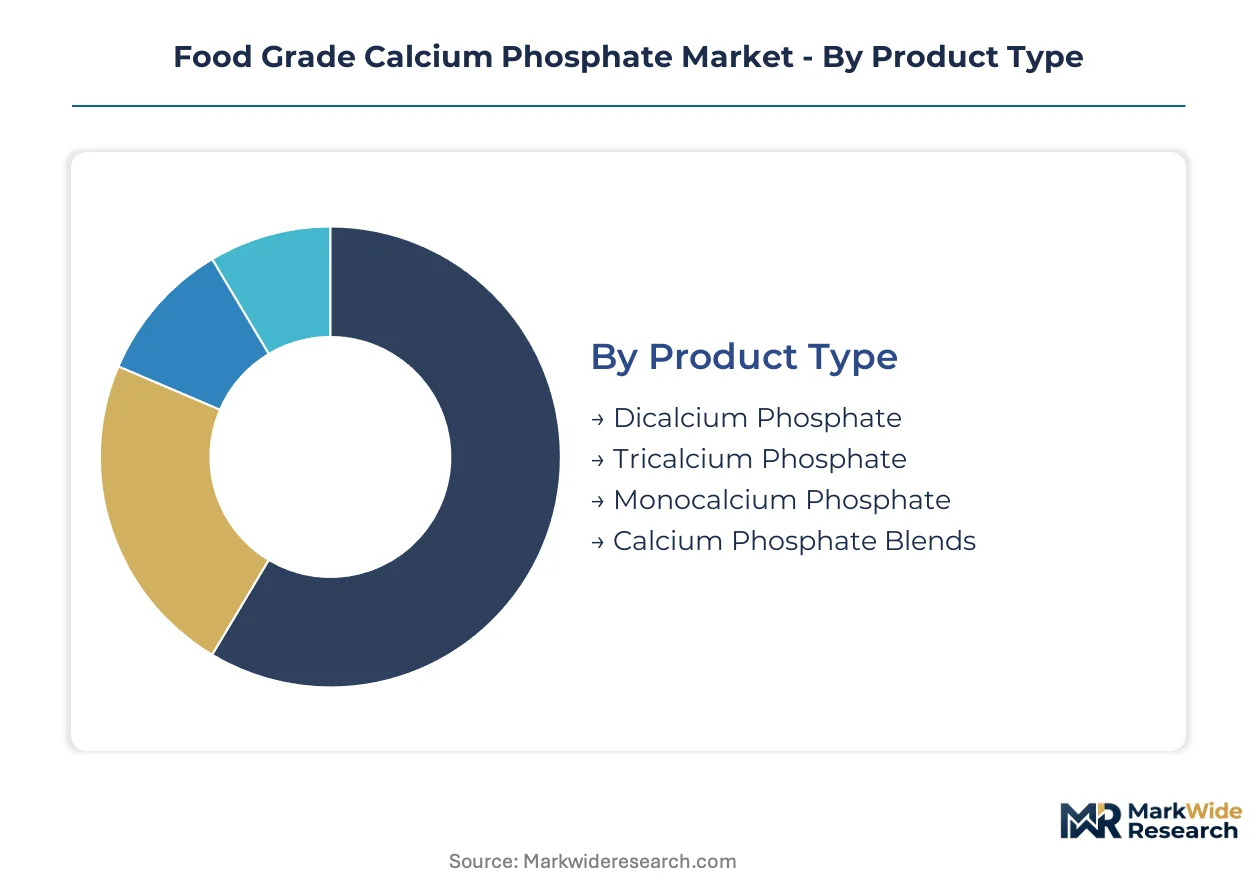
Calcium phosphate suppliers configure production lines around discrete purity grades and particle architectures. Segment boundaries determine which facilities qualify for pharmaceutical-adjacent food specifications versus technical-grade animal feed output.
Product Type:
Precipitated calcium phosphates generate divergent margin profiles based on purity thresholds and processing intensity.
- Dicalcium Phosphate:Manufactured via controlled reaction between phosphoric acid and calcium carbonate, yielding 34-39% calcium content with sub-10 ppm heavy metal limits. Baking powder manufacturers in Germany and Switzerland specify this grade for neutral taste profiles that avoid alkaline off-notes in clean-label formulations. The established supply base and mature specification standards compress margins relative to specialty precipitated grades.
- Tricalcium Phosphate:Higher calcium density (38-40%) and superior compressibility position this grade for high-load tablet formulations where flow properties and direct-compression compatibility reduce manufacturing steps. Nutraceutical contract manufacturers in North America and Western Europe are specifying sub-10 micron particle distributions to eliminate granulation requirements.
- Monocalcium Phosphate:Rapid acid-release kinetics suit double-acting baking powders and self-rising flour systems. US and Canadian bakery conglomerates dominate procurement volumes for this segment.
- Calcium Phosphate Blends:Custom ratios of di-, tri-, and mono- salts address specific pH buffering windows in plant-based beverage applications. Southeast Asian oat and pea protein formulators are driving specification development for this category.
The dominant share belongs to Dicalcium Phosphate, while Tricalcium Phosphate is gaining share fastest.
Application:
End-use concentration determines regulatory scrutiny intensity and certificate-of-analysis complexity.
- Food Fortification:Wheat flour, edible oil, and dairy analogue processors incorporate calcium phosphates to meet national enrichment mandates. India's FSSAI-directed wheat fortification programs are expanding technical-grade phosphate consumption from both domestic Jiangsu province suppliers and import channels.
- Dietary Supplements:Tablet and capsule manufacturers prioritize compressibility and disintegration profiles. German and Swiss nutraceutical producers specify narrow particle distributions that bypass granulation steps.
- Animal Feed:Livestock and poultry premix producers utilize technical-grade dicalcium phosphate for phosphorus supplementation. Chinese Shandong province capacity serves domestic feed compounders and Southeast Asian export markets.
- Nutraceuticals:Functional food brands seek dual mineral-delivery systems combining calcium with magnesium or zinc in single-matrix formats. Clean-label beverage formulators rotate toward this category for solubility control without grit or precipitation.
Food Fortification commands the largest revenue pool, though Nutraceuticals is expanding most quickly as functional food brands proliferate.
End User:
Procurement sophistication separates pharmaceutical-adjacent specifications from commodity feed-grade purchasing.
- Food Manufacturers:Multinational bakery and beverage processors enforce dual-certification requirements spanning FDA GRAS notifications and EFSA food additive approvals. These buyers specify real-time laser diffraction data and ICP-MS heavy metal certificates.
- Pharmaceutical Companies:cGMP-adjacent food ingredient sourcing demands excipient-grade documentation with batch-level traceability. European and North American buyers dominate this segment.
- Feed Producers:Volume-oriented procurement prioritizes cost position over particle architecture precision. Chinese domestic compounders and Southeast Asian integrators represent core demand.
- Health Food Stores:Private-label supplement brands source blended calcium phosphate systems through distributor networks. Online channel growth is concentrating procurement among specialized ingredient distributors with technical service capabilities.
Food Manufacturers retain the dominant procurement volume, while Pharmaceutical Companies are tightening specification requirements fastest.
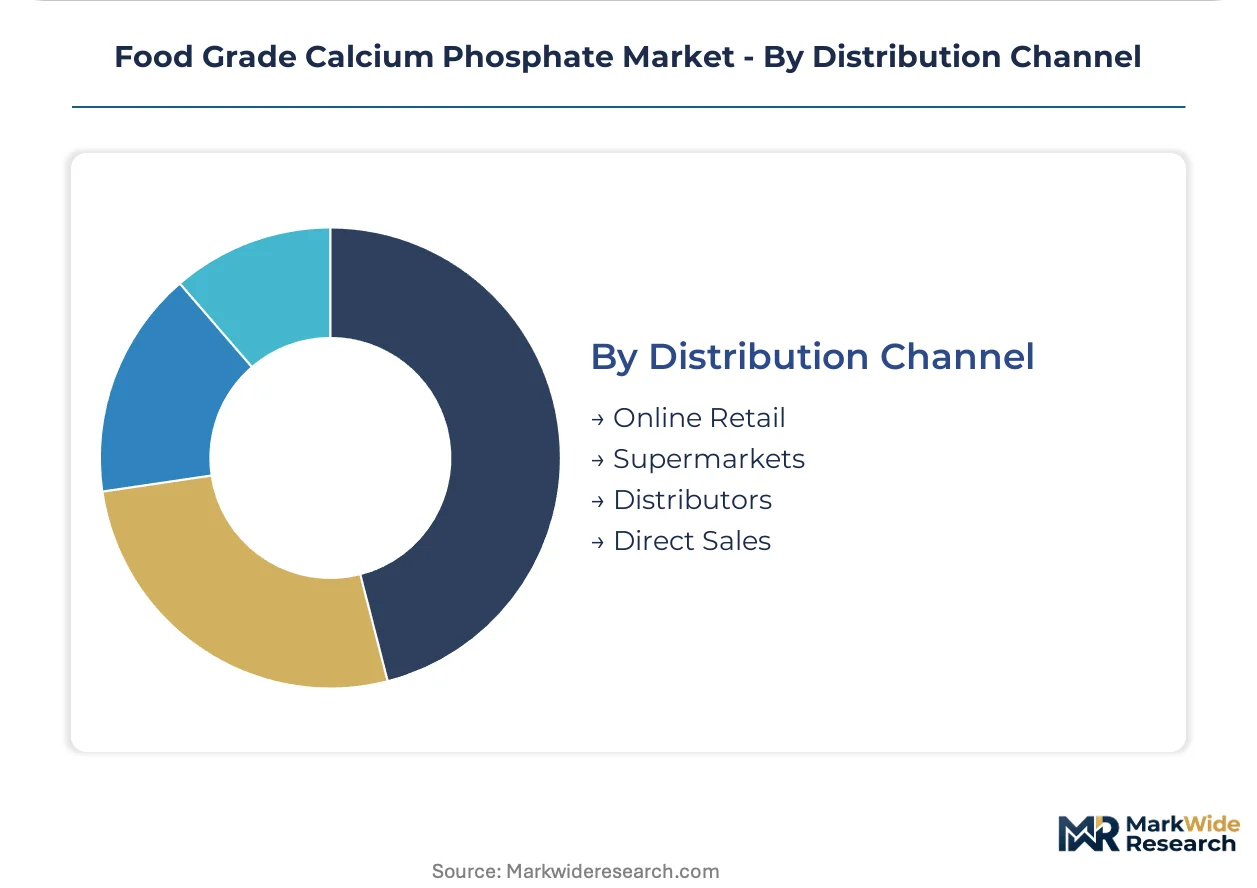
Distribution Channel:
Channel selection reflects buyer technical capability and volume scale.
- Online Retail:Specialized ingredient marketplaces serve small-scale nutraceutical startups and regional bakery formulators. Certificate-of-analysis transparency and sample ordering convenience drive adoption.
- Supermarkets:Limited to consumer-facing supplement SKUs rather than industrial ingredient volumes. Private-label mineral supplement brands represent the primary calcium phosphate exposure.
- Distributors:Technical service partnerships displace transactional spot purchasing among Southeast Asian contract manufacturers. Vietnamese and Thai beverage fortification programs now require on-site application support as contract prerequisites.
- Direct Sales:Integrated phosphate rock-to-specialty-chemicals producers leverage captive supply relationships with multinational food manufacturers. Prayon's European supply positions and Jiangsu Kolod's domestic Chinese channels exemplify this structure.
Distributors handle the dominant transaction volume, while Direct Sales is capturing the highest-value accounts fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers in Jiangsu and Shandong provinces export technical-grade calcium phosphates to Southeast Asian fortification programs, while European specialty manufacturers supply pharmaceutical-adjacent food specifications to German and Swiss nutraceutical tablet producers.
United States
Bakery conglomerates and beverage formulators drive demand for monocalcium phosphate in double-acting baking powders and clean-label mineral fortification systems. The FDA's GRAS notification program and EPA effluent guidelines for phosphate manufacturing shape facility siting decisions in the Gulf Coast chemical corridor. Texas and Louisiana host precipitation facilities serving domestic food manufacturers with heavy-metal testing protocols aligned to certificate-of-analysis requirements.
Germany
Nutraceutical contract manufacturers specify sub-10 micron tricalcium phosphate grades for direct-compression tablet formulations without granulation steps. EFSA's revised tolerable upper intake levels for calcium force reformulation ceilings across EU member states, compressing single high-dose phosphate applications. The Rhine-Main industrial cluster around Frankfurt anchors precipitated calcium phosphate capacity serving pharmaceutical-adjacent food specifications.
China
Domestic food ingredient producers scale technical-grade output for local consumption and Southeast Asian export channels, with Jiangsu Kolod Food Ingredients extending technical service capabilities to Vietnamese and Thai contract manufacturers. SAMR enforces GB standards for food-grade phosphates that increasingly align with Codex Alimentarius specifications, affecting cross-border certificate-of-analysis protocols. Shandong province capacity serves domestic feed compounders and regional fortification programs.
India
FSSAI-directed wheat flour and edible oil mineral enrichment directives create technical-grade phosphate demand from domestic suppliers and import channels. The country's food fortification mandates concentrate procurement among distributors with on-site application support capabilities. Maharashtra and Gujarat industrial corridors host premix manufacturers integrating calcium phosphates into wheat flour processing lines.
Switzerland
Swissmedic-adjacent food ingredient specifications attract high-purity precipitated calcium phosphate supply for pharmaceutical-grade nutritional applications. German and Swiss nutraceutical producers drive specification development for narrow particle distribution grades. The Basel pharmaceutical corridor influences purity benchmarks that cascade into food-grade phosphate documentation requirements.
Food Grade Calcium Phosphate Market Competitive Landscape
Player mix skews toward integrated phosphate rock-to-specialty-chemicals producers and regional precipitation specialists serving distinct purity tiers. The vendor base separates into three strategic archetypes: captive supply chain operators with upstream mining integration, regional precipitation specialists with technical service partnerships, and commodity-grade exporters competing on certificate-of-analysis compliance speed. Competitive moves concentrate on dual-certification investments spanning FDA GRAS and EFSA additive approvals, plus spray-dried agglomeration capacity for instant beverage premix applications.
Among integrated European operators, Prayon and Budenheim occupy positions representing cost-advantaged supply chain control and high-purity pharmaceutical-adjacent specifications respectively. Jiangsu Kolod Food Ingredients anchors the Chinese domestic distribution architecture while exemplifying technical service extension into Southeast Asian export markets.
| Leading Market Players |
|---|
| Innophos Holdings Inc. |
| Prayon |
| Budenheim |
| ICL PP |
| Haifa Group |
| Gadot Biochemical |
| Hindustan Phosphates |
| Alfacal |
| Jiangsu Kolod Food Ingredients |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day certificate-of-analysis lead times for multi-jurisdiction certification concentrate pricing power among integrated producers with captive laboratory infrastructure, while compressing margins for spot-market participants dependent on third-party validation. This inventory-to-certification lag rewards backward integration into phosphate rock mining and precipitation capacity, penalizing traders without upstream control.
Pricing Analysis
Current-generation sub-10 micron precipitated grades command 40-60% premiums over standard 50-100 micron commodity powders, while next-generation spray-dried agglomerates for instant beverage premixes are establishing fresh price ceilings. Three-tier pricing structure across pharmaceutical-adjacent, food-grade, and technical-feed levels segments buyers by certification burden and application criticality. Cost compression in technical-grade dicalcium phosphate is intensifying because Chinese Shandong province capacity expansion outpaces Southeast Asian demand absorption. Feed producers exhibit highest price sensitivity due to volume procurement and specification flexibility, while pharmaceutical-adjacent nutraceutical buyers tolerate premiums for batch-level traceability.
Supply Chain Analysis
Strategic stockpiling of phosphate rock concentrates prevails among integrated European producers, whereas just-in-time phosphoric acid sourcing dominates Chinese precipitation specialists with shorter conversion cycles. Manufacturing gravity centers on Morocco for phosphate rock mining, China for technical-grade precipitation capacity, and Germany for pharmaceutical-adjacent specialty grades. Production draws from sulfuric acid, calcium carbonate, and phosphate rock feedstocks with Moroccan mining output fluctuations transmitting directly to input cost volatility. Single-source vulnerability concentrates in Moroccan phosphate rock supply controlled by state mining entities. Distribution runs through technical service partnerships for high-specification grades and commodity distributors for feed-tier volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent calcium phosphate producers face substitution pressure from magnesium and zinc mineral delivery systems in functional food formulations, requiring defensive positioning around compressibility advantages and dual-certification moats.
For Market Incumbents: Secure dual FDA GRAS and EFSA additive approval portfolios to lock out regional competitors lacking parallel submission resources. Anchor backward integration into phosphate rock mining or captive phosphoric acid capacity to insulate margin structures from Moroccan supply volatility. Defend tablet formulation share against magnesium carbonate substitution by promoting tricalcium phosphate's superior flow properties and direct-compression compatibility. For New Entrants and Emerging Players: Lead with technical service partnerships targeting Vietnamese and Thai beverage fortification programs where on-site application support remains undersupplied. Penetrate India's FSSAI-directed wheat flour enrichment channels through distributors with premix formulation capabilities. Establish spray-dried agglomeration capacity for instant beverage premix manufacturers seeking free-flowing granule specifications absent from commodity powder suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with undermonetized food-grade phosphate divisions lacking standalone certification infrastructure. Five-to-ten-year viability hinges on regulatory divergence between FDA, EFSA, and SAMR standards creating multi-certification specialists with pricing power. Watch for Indian FSSAI enforcement acceleration in edible oil fortification as inflection signal for technical-grade phosphate demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Parallel FDA GRAS and EFSA submissions compress competitor entry timelines by 14-22 months. |
| Spray-Dried Agglomeration Capacity | Instant beverage premix manufacturers in Southeast Asia specify free-flowing granules replacing conventional powders. |
| Technical Service Partnerships | Vietnamese contract manufacturers now require on-site pH buffering and stability testing as contract prerequisites. |
| Backward Integration into Phosphate Rock | Captive Moroccan or Chinese mining access insulates margin structures from sulfuric acid cost volatility. |
| Sub-10 Micron Particle Architecture | German nutraceutical producers adopt narrow-distribution grades for direct-compression tablet manufacturing. |
Research Methodology
Desk research of customs trade databases, SEC filings from phosphate specialty chemical producers, and EFSA scientific opinions preceded structured interviews with plant managers at precipitation facilities, procurement leads at multinational bakery and beverage processors, technical R&D directors developing particle architecture specifications, and regulatory affairs specialists managing GRAS notification submissions. Bottom-up capacity and production estimates triangulated against top-down demand modeling from fortification program mandates and supplement formulation trends.
Variance decomposition across product type, application, purity grade, and regional regulatory cluster dimensions shaped volume and value outputs over the projection horizon. CAGRs derived from segment-level demand elasticity analysis and capacity expansion announcements. Forecast inputs incorporated FSSAI enforcement trajectories for Indian wheat flour fortification and EFSA calcium intake ceiling revisions affecting formulation ceilings.
Forecasts assume regulatory continuity in FDA GRAS notification pathways, EFSA additive approval frameworks, and SAMR GB standard alignment with Codex Alimentarius; material policy shifts in heavy metal purity thresholds or tolerable upper intake levels would require re-modeling. Revision becomes warranted when phosphoric acid input cost volatility exceeds historical bands or when Indian FSSAI enforcement accelerates beyond current mandate timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Methyl Oleate Market
Food Additives and Ingredients
Asia-Pacific Food Enzymes Market
Food Additives and Ingredients
Europe Food Additives Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
United Kingdom Food Emulsifier Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Food Grade Calcium Hydroxide Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Invertase Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Bread Preservatives Market