
 Africa Food Enzymes Market | 2026-2036
Africa Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Food Enzymes Market Outlook
The capital-intensity divergence between integrated biotech platforms and commodity traders is unwinding competitive order in the Africa Food Enzymes Market. Novozymes A/S leverages its microbial strain library to dominate high-performance amylase supply for industrial bakeries. DSM-Firmenich anchors regional presence through localized fermentation capacity and technical service networks. Kerry Group PLC competes by extending its enzyme-blend portfolio into meat processing applications where formulation complexity creates stickier customer relationships.
Food enzymes are protein-based biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions in food matrices without becoming consumed in the process. Their primary commercial purpose centers on improving process efficiency, modifying texture, enhancing flavor profiles, and extending product stability across manufactured food systems. Amylases command the largest volume share among type segments due to their indispensability in starch hydrolysis for baking and beverage applications. Microbial-sourced enzymes are expanding fastest within the source category because bacterial and fungal production systems offer superior batch consistency and lower allergen risk compared to animal-derived alternatives. Dairy applications represent a concentrated margin pool where lactase demand tracks formal retail expansion and lactose-free product proliferation.
South Africa's Department of Health, Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC), and Kenya's Bureau of Standards (KEBS) collectively enforce enzyme purity, labeling, and import documentation requirements that filter out substandard suppliers and elevate compliance costs for new entrants. These frameworks push multinational suppliers toward local registration partnerships and certified manufacturing arrangements rather than pure import models. Stakeholders must monitor how harmonization pressures from the African Continental Free Trade Area reshape national registration pathways and whether domestic fermentation capacity investments in Egypt and Nigeria alter import dependency structures.
Market Dynamics
NAFDAC's tightening purity thresholds for imported enzyme formulations are forcing multinational suppliers toward localized fermentation partnerships and certified manufacturing arrangements rather than pure import models.
Growth Catalysts
- Processed Food Corridor Expansion:Nigeria's domestic manufacturers seek alternatives to imported gluten and emulsifiers, pulling demand toward locally blended enzyme solutions.
- KEBS Standards Harmonization:Kenya's Bureau of Standards is elevating documentation requirements that filter out substandard suppliers and reward certified producers.
- Microbial Production Systems:Bacterial and fungal fermentation platforms offer superior batch consistency and lower allergen risk compared to animal-derived alternatives.
Market Restraints
- Import Dependency Structures:Egypt and Nigeria lack sufficient domestic fermentation capacity, locking supply chains to European and Asian manufacturing nodes.
- Regulatory Friction:South Africa's Department of Health maintains divergent purity thresholds from NAFDAC, fragmenting compliance pathways across the continent.
- Technical Limitation:Temperature-sensitive enzyme formulations degrade in Africa's ambient storage conditions without cold chain infrastructure.
Strategic Opportunities
- Meat Processing Applications:Enzyme-blend portfolios in meat processing create stickier customer relationships through formulation complexity barriers.
- AfCFTA Harmonization:African Continental Free Trade Area pressures are reshaping national registration pathways toward mutual recognition.
- Lactose-Free Dairy:Formal retail expansion in Kenya and Nigeria tracks lactase demand for lactose-free product proliferation.
Industry Challenges
- Technical Service Networks:Localized fermentation capacity requires skilled bioprocess engineers scarce in Nigeria's food science labor pool.
- Cold Chain Integration:Enzyme stability demands clash with existing distribution infrastructure, forcing reformulation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Food Enzymes Market |
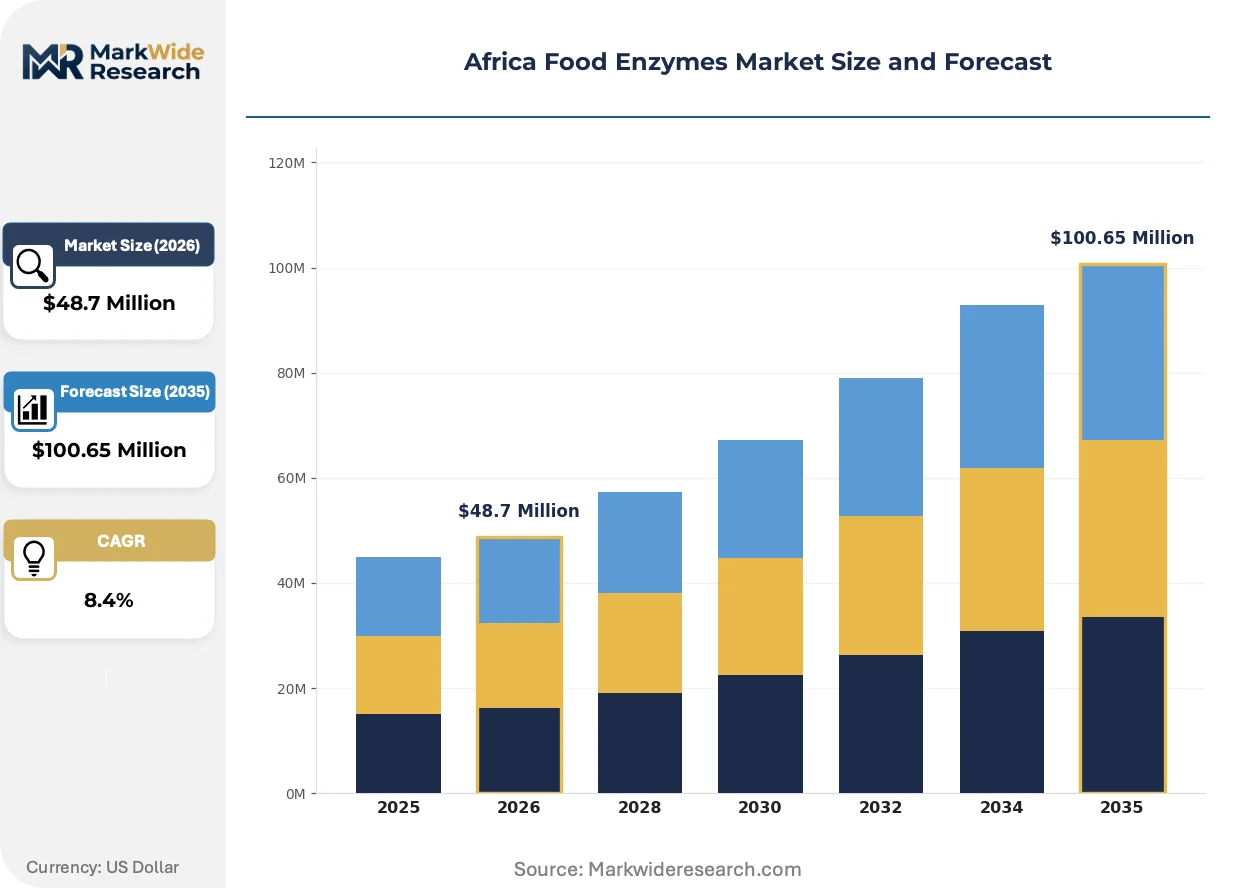
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $100.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Baking, Dairy, Beverages, Meat Processing Type: Amylases, Proteases, Cellulases, Lactases Source: Microbial, Plant, Animal, Fungal End User: Food Manufacturers, Restaurants, Retailers, Households |
| Companies Covered | Novozymes A/S, DSM-Firmenich, International Flavors and Fragrance Inc. (IFF), AB Enzymes GmbH, Chr. Hansen Holding A/S, Kerry Group PLC, BASF SE, Advanced Enzyme Technologies Ltd., Amano Enzyme Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Food Enzymes Market Strategic Shifts
Enzyme technology trajectories in Africa are converging around cold-stable formulations, regulatory pre-certification strategies, and direct technical service models that bypass traditional distributor layers.
Cell-free enzyme synthesis is fragmenting traditional microbial fermentation economics. Startups in South Africa and Egypt are piloting cell-free amylase production for industrial bakeries, compressing batch-to-batch variability and enabling on-demand manufacturing at smaller scales. This technology is fragmenting the capital barrier that previously locked out regional entrants.
NAFDAC's 2024 enzyme import documentation overhaul is compressing registration timelines for pre-certified suppliers while extending review periods for first-time entrants. Industrial bakeries in Lagos and Nairobi are consolidating procurement around suppliers with existing dossier approvals. Dairy processors face the steepest adaptation curve as lactase formulations require additional stability testing.
Direct technical service engagement is displacing traditional distributor-led sales in Kenya's bakery sector. Industrial buyers in Nairobi's processed food corridor now demand on-site dough optimization support rather than commodity transactions. This pattern is most visible among mid-scale manufacturers seeking to reduce formulation failure rates without internal R&D capacity.
Africa Food Enzymes Market Segmentation
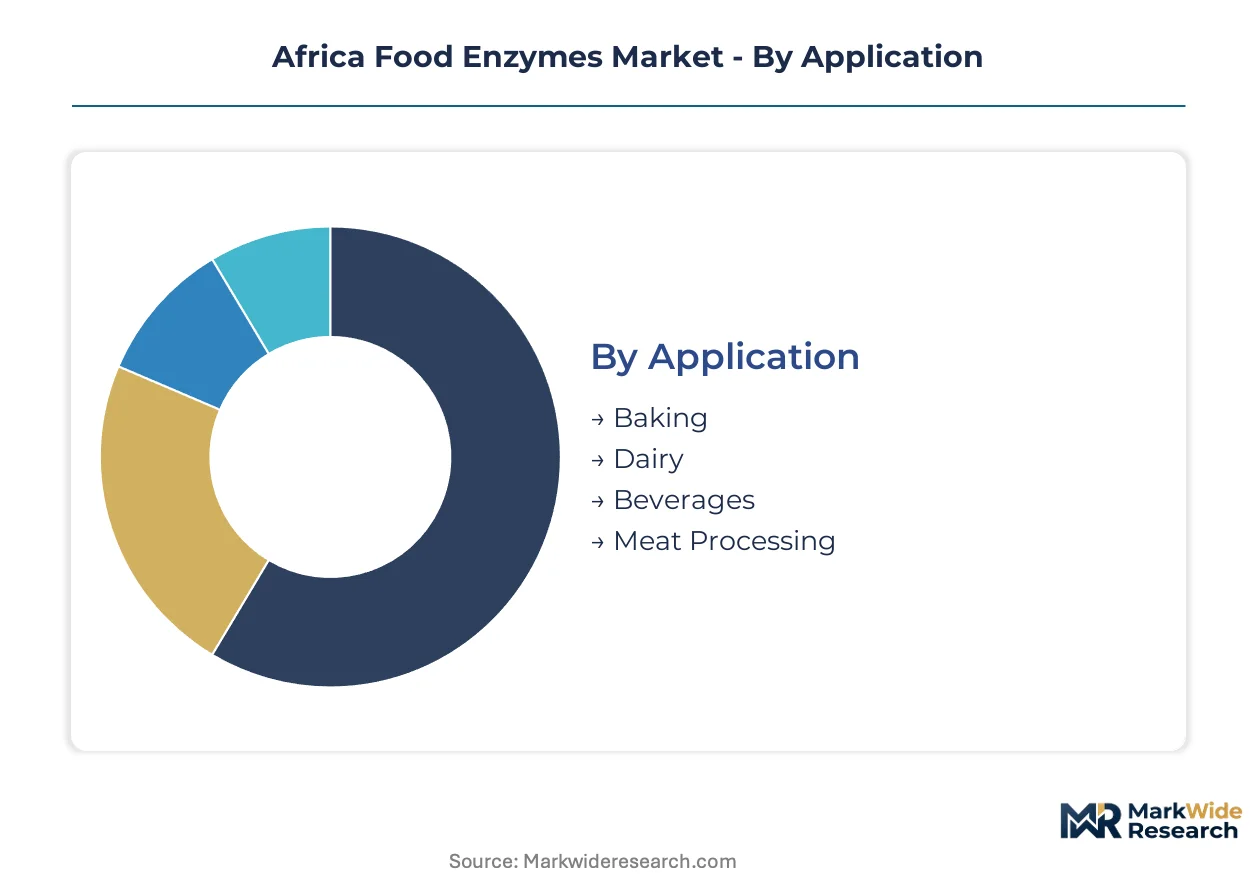
Enzyme procurement patterns in Africa diverge sharply between industrial-scale food manufacturers and fragmented retail channels. Understanding these pathway distinctions reveals where formulation complexity creates pricing power versus where commodity trading dominates.
Application:
Baking applications flow through distributor networks serving Lagos and Nairobi industrial corridors, while dairy enzymes reach processors via direct technical service relationships.
- Baking:Amylase and protease blends modify dough rheology and extend shelf life in bread and pastry production. Nigeria's processed food corridor pulls concentrated demand as domestic manufacturers replace imported gluten with enzyme-based alternatives.
- Dairy:Lactase catalyzes lactose hydrolysis for fluid milk and fermented products. Kenya's formal retail expansion drives lactose-free SKU proliferation, concentrating procurement among Nairobi-based processors with cold chain capabilities.
- Beverages:Pectinases and amylases clarify fruit juices and stabilize beer fermentation. Supply concentrates in South African brewing facilities and Nigerian soft drink bottlers.
- Meat Processing:Protease blends tenderize proteins and optimize curing reactions. Formulation complexity creates stickier supplier relationships among mid-scale processors in South Africa and Egypt.
Baking dominates installed base. Dairy is where expansion concentrates.
Type:
Cost tiers separate commodity amylases from premium lactases with stability certification requirements.
- Amylases:These starch-hydrolyzing enzymes operate optimally between 50°C and 70°C with pH tolerance from 4.5 to 7.0. Industrial bakeries across Nigeria and Kenya scale procurement for dough conditioning and anti-staling effects.
- Proteases:Protein-cleaving biocatalysts function across acidic to neutral pH ranges, enabling gluten modification and meat tenderization. Meat processing applications in South Africa concentrate demand for specialized blends.
- Cellulases:Cell wall-degrading enzymes improve juice extraction and fiber modification. Beverage processors in Egypt and Kenya represent primary uptake.
- Lactases:Beta-galactosidase enzymes hydrolyze lactose at 30°C to 40°C for dairy applications. Cold-stable formulations command premium positioning in lactose-free retail segments.
Amylases anchor volume throughput. Lactases capture margin expansion.
Source:
Microbial production systems scale through fermentation facilities, while animal-derived alternatives face allergen labeling constraints.
- Microbial:Bacterial and fungal fermentation platforms deliver batch consistency with lower allergen risk than animal alternatives. South African and Egyptian pilot facilities are compressing import dependency for industrial bakeries.
- Plant:Enzymes extracted from papaya, pineapple, and fig sources serve niche kosher and halal certification requirements. Limited commercial scale restricts deployment to specialized dairy and meat applications.
- Animal:Traditional rennet and pancreatic extracts face declining acceptance due to allergen documentation burdens. Kenya's Bureau of Standards elevation of purity thresholds accelerates displacement.
- Fungal:Aspergillus and Trichoderma-derived enzymes offer broad pH activity ranges for baking and brewing. Technical service networks in Nigeria prioritize fungal amylase supply for dough optimization support.
Microbial sources command manufacturing investment. Plant sources occupy certification niches.
End User:
Customer type determines whether procurement flows through distributor layers or direct technical engagement.
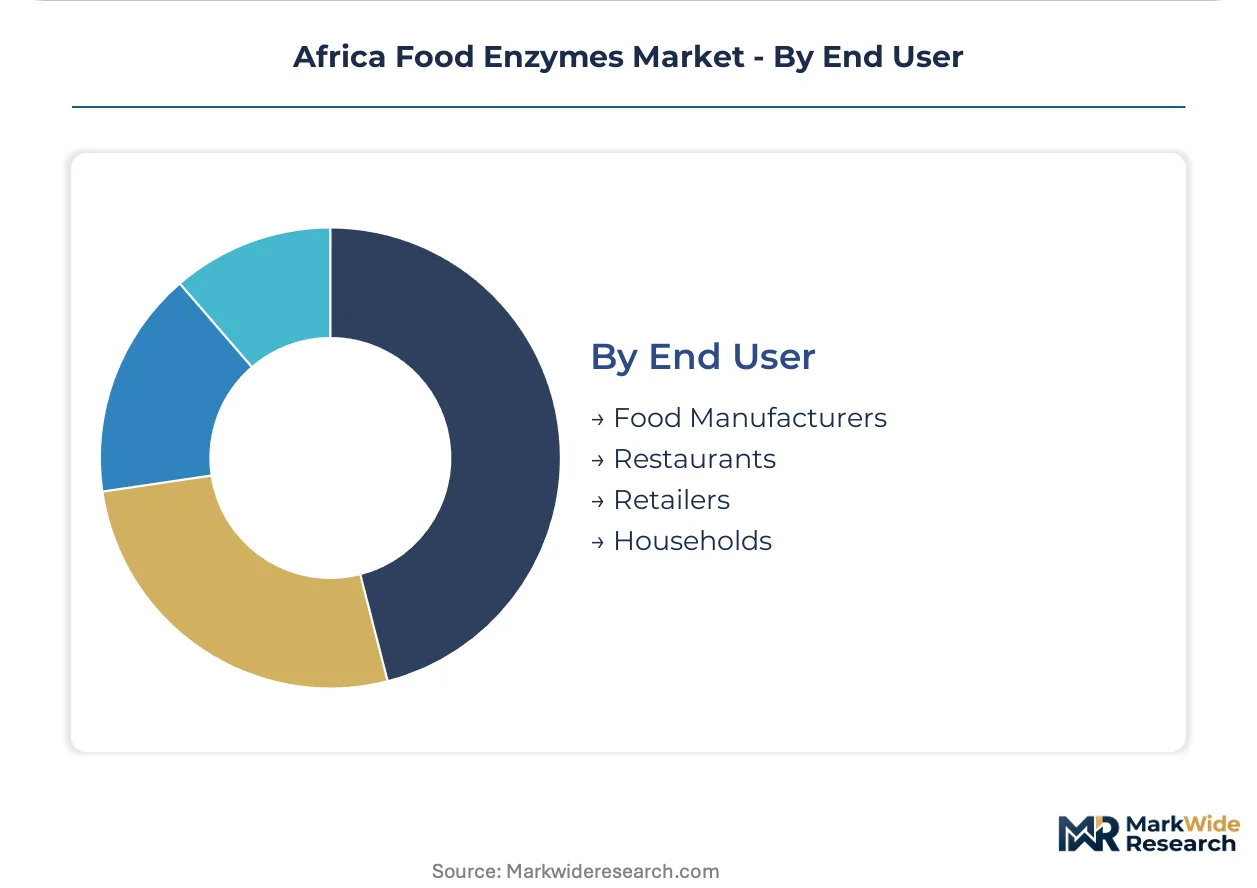
- Food Manufacturers:Industrial-scale bakeries, dairies, and meat processors constitute the primary demand pool. Nairobi and Lagos buyers now require on-site formulation support rather than commodity transactions.
- Restaurants:Limited enzyme penetration outside large-scale catering and hotel chains. South African hospitality groups represent isolated demand for specialized meat tenderization.
- Retailers:Supermarket private-label programs in Kenya and Nigeria drive lactose-free dairy enzyme procurement. Formal retail expansion tracks with processed food corridor development.
- Households:Negligible direct consumption; enzyme exposure occurs through packaged goods rather than home baking additives. Distribution infrastructure gaps prevent meaningful market development.
Food manufacturers absorb capacity deployment. Retailers are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across African markets. South African industrial buyers absorb premium pricing for certified stability, while Nigerian processors prioritize cost-efficient alternatives to imported gluten and emulsifiers.
South Africa
Industrial bakeries in Johannesburg and Cape Town drive concentrated demand for high-performance amylase formulations. The Department of Health maintains stringent purity thresholds that filter substandard imports and elevate compliance costs. Durban's brewing corridor anchors beverage enzyme procurement, with pectinase supply stabilizing fruit juice processing lines.
Nigeria
Lagos-based manufacturers scale enzyme adoption to replace imported gluten in bread and pastry production. NAFDAC's 2024 documentation overhaul compresses registration timelines for pre-certified suppliers while extending review for first-time entrants. The processed food corridor spanning Lagos to Ibadan concentrates procurement among mid-scale bakeries seeking dough optimization support.
Kenya
Nairobi's formal retail expansion pulls lactase demand for lactose-free dairy SKU proliferation. KEBS elevation of documentation requirements rewards certified producers with faster market access. The Rift Valley dairy belt concentrates cold-chain-dependent enzyme procurement among processors with stability-certified formulations.
Egypt
Cairo's beverage bottlers anchor pectinase and amylase demand for juice clarification and beer stabilization. The country's national food and drug regulator enforces import documentation that favors suppliers with existing dossier approvals. Alexandria's pilot fermentation facilities are compressing import dependency for industrial bakeries seeking localized supply.
Morocco
Casablanca's meat processing sector concentrates protease demand for protein tenderization and curing optimization. The national standards body aligns documentation requirements with broader regional harmonization pressures. Tangier's logistics corridor facilitates enzyme transit for re-export to West African markets.
Africa Food Enzymes Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence unwinding competitive order. Consolidation favors players with microbial strain libraries and localized fermentation capacity. Three archetypes dominate: integrated biotech platforms with proprietary production systems, regional blenders with technical service networks, and commodity traders with distributor-led reach. Capacity partnerships and regulatory pre-certification strategies represent the dominant competitive moves.
Among integrated biotech platforms, Novozymes A/S and DSM-Firmenich exemplify the capital-intensive tier with proprietary microbial production systems. Kerry Group PLC occupies a position bridging formulation complexity and technical service depth. These three anchors represent divergent pathways—strain-library dominance, localized fermentation investment, and application-specific blend portfolios—each capturing distinct margin pools across baking, dairy, and meat processing verticals.
| Leading Market Players |
|---|
| Novozymes A/S |
| DSM-Firmenich |
| International Flavors and Fragrance Inc. (IFF) |
| AB Enzymes GmbH |
| Chr. Hansen Holding A/S |
| Kerry Group PLC |
| BASF SE |
| Advanced Enzyme Technologies Ltd. |
| Amano Enzyme Inc. |
| Others |
Value Chain & Pricing Dynamics
NAFDAC's 2024 enzyme import documentation overhaul gates both supplier qualification and price differentiation simultaneously, compressing registration timelines for pre-certified suppliers while extending review periods for first-time entrants. Industrial bakeries in Lagos and Nairobi now consolidate procurement around certified producers, creating tiered access that separates stability-certified formulations from commodity alternatives.
Pricing Analysis
Technical service contracts and on-site dough optimization support drive lifetime value beyond initial enzyme sales. Pricing stratifies across premium, standard, and economy tiers based on cold-stability certification and formulation complexity. Cost compression in standard-grade amylases is intensifying because Egyptian and Nigerian pilot fermentation facilities are compressing import dependency. Mid-scale bakeries without internal R&D capacity show highest price sensitivity, while dairy processors with cold chain infrastructure absorb premiums for lactase stability certification.
Supply Chain Analysis
Port congestion at Lagos Apapa and Mombasa container terminals elevates inbound logistics costs for European and Asian enzyme shipments. Supply concentrates in Denmark, the Netherlands, and China for industrial-scale fermentation capacity, drawing from specialized microbial strain libraries and precision fermentation inputs. Single-source vulnerability runs through cold-chain-dependent lactase formulations where stability demands clash with ambient storage infrastructure. Distribution runs through certified distributor networks in Lagos and Nairobi industrial corridors, with direct technical service relationships displacing traditional layers in Kenya's bakery sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story. Nigeria's processed food corridor adoption of enzyme-based gluten alternatives provides the clearest penetration tailwind for volume growth.
For Market Incumbents: Consolidate microbial strain library advantages through localized fermentation partnerships in Egypt and Nigeria, compressing the capital barrier that previously locked out regional entrants. Deepen technical service networks to defend against cell-free synthesis startups piloting on-demand amylase production. Anchor certification investments to NAFDAC's pre-approval pathways, creating stickiness through dossier complexity. For New Entrants and Emerging Players: Anchor in Kenya's Rift Valley dairy belt where lactose-free retail expansion outpaces established supplier coverage. Target mid-scale meat processors in South Africa and Egypt where protease formulation complexity creates relationship barriers. Deploy direct technical service models that bypass distributor layers, offering on-site optimization support that incumbent commodity traders cannot match. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cell-free enzyme synthesis, fragmenting traditional microbial fermentation economics. The 5-to-10-year viability window favors acquisition targets with localized pilot facilities and existing regulatory dossiers rather than pure import models. Watch for AfCFTA harmonization momentum as the signal indicating when mutual recognition pathways will compress national registration costs.| Strategic Initiative | Industry Significance |
|---|---|
| Localized Fermentation Partnership | Egyptian and Nigerian pilot facilities compress import dependency for industrial bakeries. |
| Cold-Stable Formulation Development | Stability-certified lactases command premium positioning in Kenya's lactose-free dairy segments. |
| Direct Technical Service Deployment | On-site dough optimization support displaces distributor-led sales in Nairobi's bakery sector. |
| Regulatory Pre-Certification Investment | NAFDAC's compressed timelines reward suppliers with existing dossier approvals. |
| Cell-Free Synthesis Pilot Scale-Up | South African and Egyptian startups fragment capital barriers through on-demand manufacturing. |
Study Parameters
A spread of perspectives from bakery operations managers, dairy procurement leads, fermentation facility engineers, and regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, NAFDAC registration filings, KEBS documentation requirements, and industry association reports. Bottom-up enzyme volume estimates triangulated against top-down processed food production statistics across Nigeria, Kenya, South Africa, and Egypt.
Segmentation dimensions modeled include enzyme type, application vertical, source category, and end-user scale across the analysis window. CAGRs derived from regression analysis against bakery and dairy production indices, with cross-validation against retail expansion metrics in formal grocery channels. Industry-specific inputs incorporated cold chain penetration rates and regulatory harmonization progress under AfCFTA frameworks.
Material uncertainties — regulatory divergence between national agencies, fermentation capacity buildout delays, and cold chain infrastructure gaps — sit outside the modeled envelope. Forecasts reflect assumptions about stability certification adoption and technical service network expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Food Inclusions Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Salatrim Market
Food Additives and Ingredients
Non-GMO Citric Acid Market
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Vinasse Market