
 Flavored Whiskey Market | 2026-2036
Flavored Whiskey Market Size, Share, and Industry Trends Forecast 2026-2036
Flavored Whiskey Market Analysis
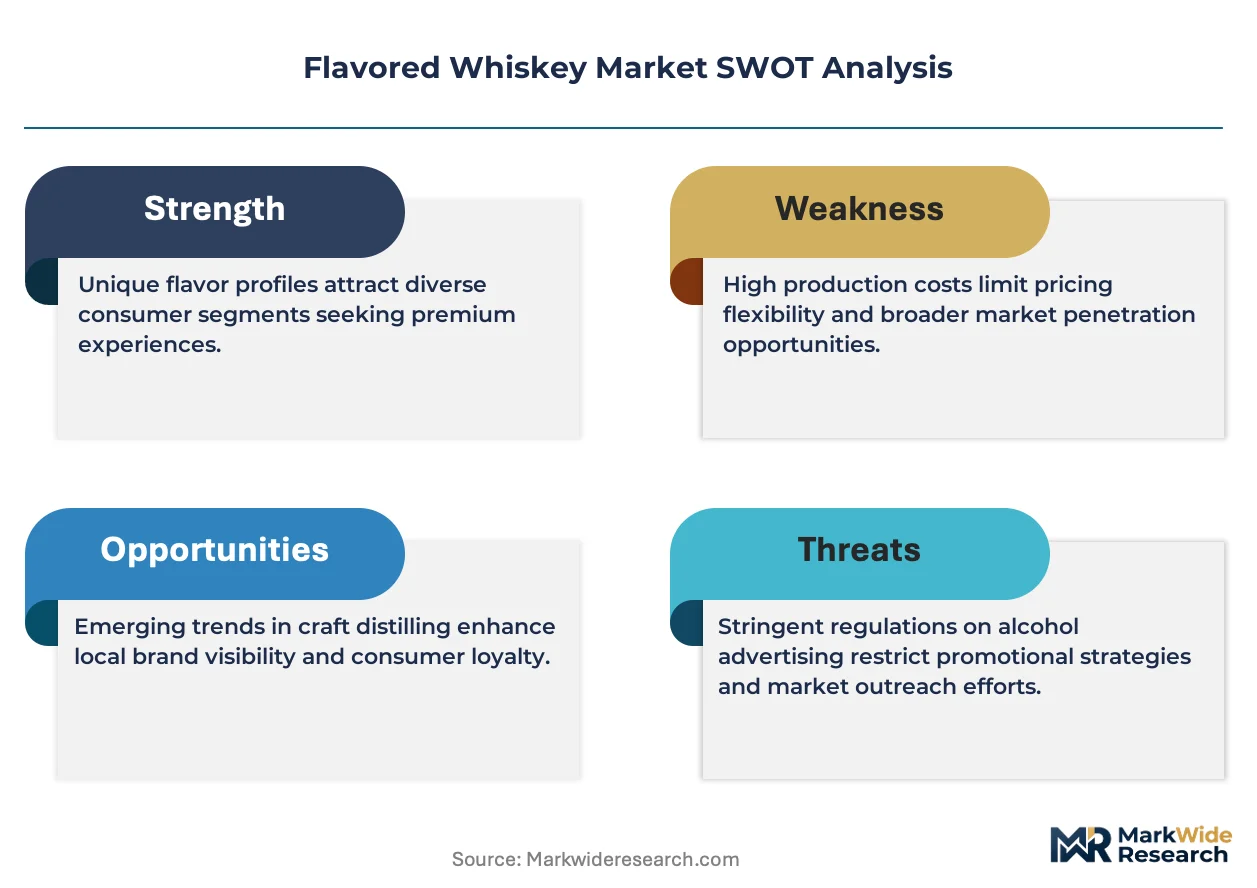
On-premise cocktail program revenue is reconfiguring margin pools as bars and restaurants reformulate classic drinks with flavored whiskey bases. Diageo leverages its Crown Royal portfolio to dominate Canadian whisky-infused flavor extensions across North American duty-free and domestic retail. Brown-Forman anchors its Jack Daniel's Tennessee Honey franchise through controlled distribution in travel retail and core American liquor stores. Pernod Ricard sustains Jameson Orange and other flavor variants through Irish whiskey heritage positioning in European and American on-trade channels.
Flavored whiskey denotes grain-distilled spirits with added natural or artificial flavoring agents, typically bottled at 35-40% ABV after post-distillation infusion or finishing processes, and functions primarily as an accessible entry point for newer whiskey consumers and a versatile cocktail ingredient. Fruit infused variants lead volume in American retail due to seasonal release cycles and berry-citrus flavor familiarity, while spiced expressions capture mature margin pools through year-round cinnamon and clove formulations. Vanilla and chocolate segments occupy premium positioning among affluent consumers seeking dessert-profile spirits, with glass bottle packaging reinforcing perceived quality against canned alternatives in gift and collector channels.
The Alcohol and Tobacco Tax and Trade Bureau governs American flavored whiskey labeling, requiring truthful statement of flavor additives and restricting health-related claims that could mislead consumers about composition. European spirits regulation under EFSA and national excise frameworks mandate minimum alcohol thresholds and geographic indication protections that shape which products qualify as whiskey versus spirit drinks. Stakeholders must monitor evolving FDA guidance on added-sugar disclosure and state-level distribution franchise laws that determine whether flavored whiskey innovations reach shelves through independent or controlled wholesale pathways.
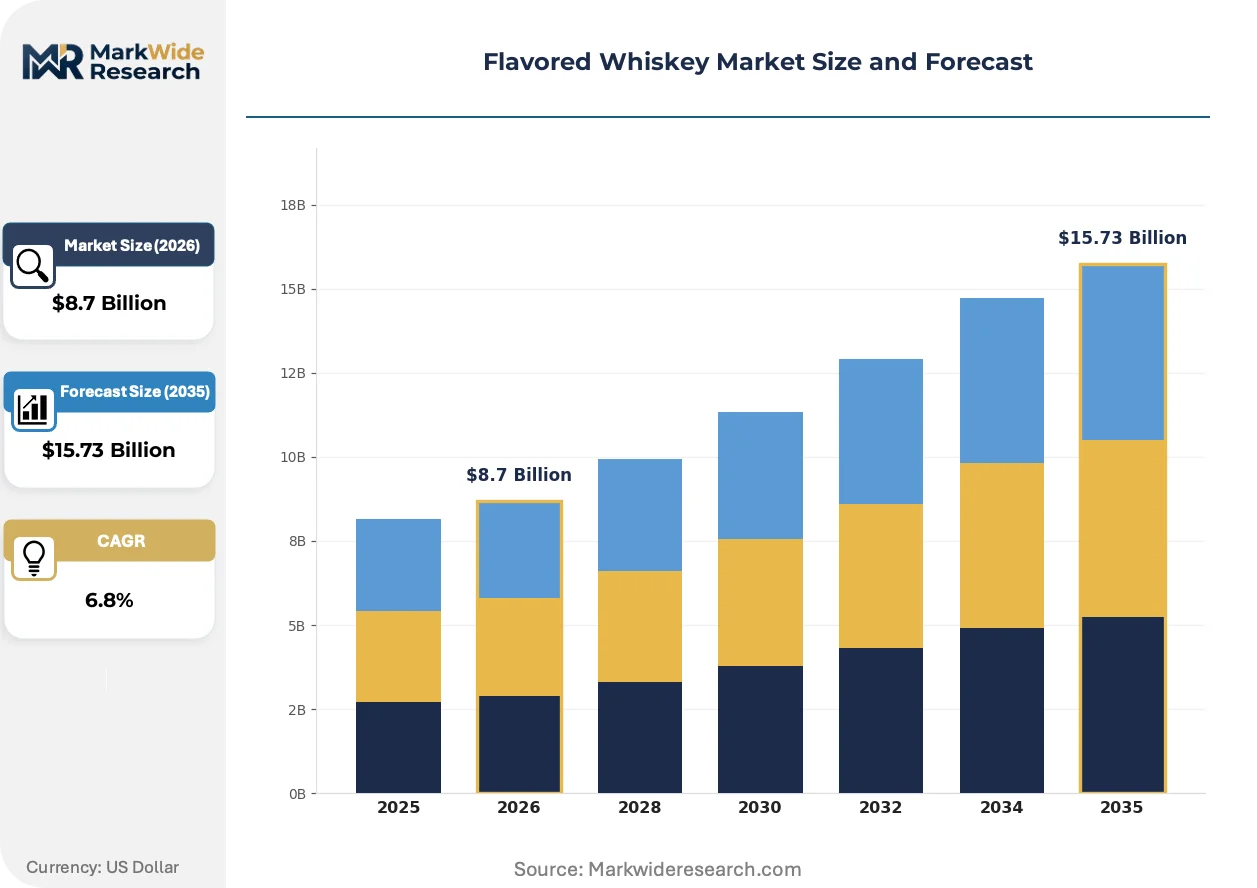
Market Dynamics
Millennial purchasing patterns are reconfiguring distribution priorities across on-premise and off-premise channels, forcing established distilleries to accelerate flavor pipeline development while TTB labeling scrutiny tightens formulation transparency requirements.
Growth Catalysts
- TTB Flavor Disclosure Mandates:The Alcohol and Tobacco Tax and Trade Bureau's truthful labeling requirements for additive statements are compelling cleaner ingredient sourcing, which premium-positioned brands leverage for differentiation in American retail formats.
- On-Premise Cocktail Program Expansion:Bars and restaurants in metropolitan clusters are reformulating classic cocktails with flavored whiskey bases, creating pull-through demand that drives volume commitments from distributors.
- Post-Distillation Infusion Techniques:Accelerated oak-finishing and vapor-infusion methods are compressing production cycles for seasonal fruit expressions, enabling faster response to berry-citrus flavor trends in American consumer panels.
Market Restraints
- Grain Input Cost Volatility:Corn and rye price fluctuations in American agricultural markets squeeze margin pools for mid-tier producers lacking long-term commodity hedging arrangements.
- Supply Concentration in Kentucky and Tennessee:Production gravity centers on specific American counties with established cooperage and maturation infrastructure, creating geographic vulnerability to climate-related warehouse losses.
- EFSA Minimum Alcohol Thresholds:European Food Safety Authority regulations mandating specific ABV floors for whiskey designation block some American flavored expressions from qualifying under protected categories, limiting export eligibility.
Strategic Opportunities
- Underpenetrated German On-Trade:Irish whiskey heritage positioning has established beachheads in Berlin and Munich cocktail bars, creating white space for Canadian whisky flavor extensions with cinnamon-spice profiles.
- Travel Retail Exclusives:Duty-free channels in Dubai International Airport and Singapore Changi reward controlled distribution with premium shelf placement and gift-format packaging opportunities.
- FDA Added-Sugar Disclosure Guidance:Anticipated transparency requirements for nutritional labeling create first-mover advantage for brands reformulating with natural fruit extracts rather than artificial sweetener systems.
Industry Challenges
- Master Blender Talent Scarcity:The specialized skill of balancing post-distillation flavor integration with base spirit character faces generational transfer gaps as experienced practitioners retire from American craft distillery operations.
- State Distribution Franchise Law Complexity:Wholesale pathway restrictions in control states versus open markets force parallel compliance frameworks, complicating national launch sequencing for new flavor variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavored Whiskey Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Infused, Spiced, Vanilla, Chocolate Customer Type: Millennials, Gen X, Baby Boomers, Affluent Consumers Packaging Type: Glass Bottle, Tetra Pak, Canned, Keg Sales Channel: Online Retail, Liquor Stores, Bars, Supermarkets |
| Companies Covered | Suntory Global Spirits (Jim Beam), Beam Suntory, Diageo (Crown Royal), Johnnie Walker, Buffalo Trace Distillery, Pernod Ricard (Jameson), Heaven Hill (Evan Williams), Compass Box, Brown-Forman (Jack Daniel's), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavored Whiskey Market Emerging Trajectories
Digital tasting protocols and accelerated maturation technologies are compressing traditional production timelines while regulatory transparency mandates reshape competitive positioning around ingredient provenance rather than heritage narrative alone.
Artificial intelligence-driven sensory mapping is virtualizing the traditional master blender role by predicting optimal flavor compound combinations before physical batching occurs. Mid-sized American craft distilleries are adopting these platforms to reduce iteration cycles for seasonal releases. This compression of formulation timelines is virtualizing the competitive moat that large-scale heritage maturation inventories previously provided.
REACH chemical registration requirements in the European Union are forcing reformulation of artificial flavoring agents used in export-bound American expressions. The industrial consequence is a bifurcation between domestic formulations using permitted synthetic compounds and European-compliant natural extract versions. Fruit-infused variants targeting Berlin and Amsterdam on-trade channels are most affected, with producers accelerating botanical sourcing partnerships to maintain shelf presence.
Direct-to-consumer subscription models are displacing traditional liquor store discovery pathways among urban millennial cohorts. Tasting clubs and curated delivery services in New York, Chicago, and Los Angeles are capturing trial occasions that previously occurred in retail aisles. This channel rotation is most visible in vanilla and chocolate premium segments where gift-giving occasions drive predictable replenishment cycles.
Flavored Whiskey Market Segmentation
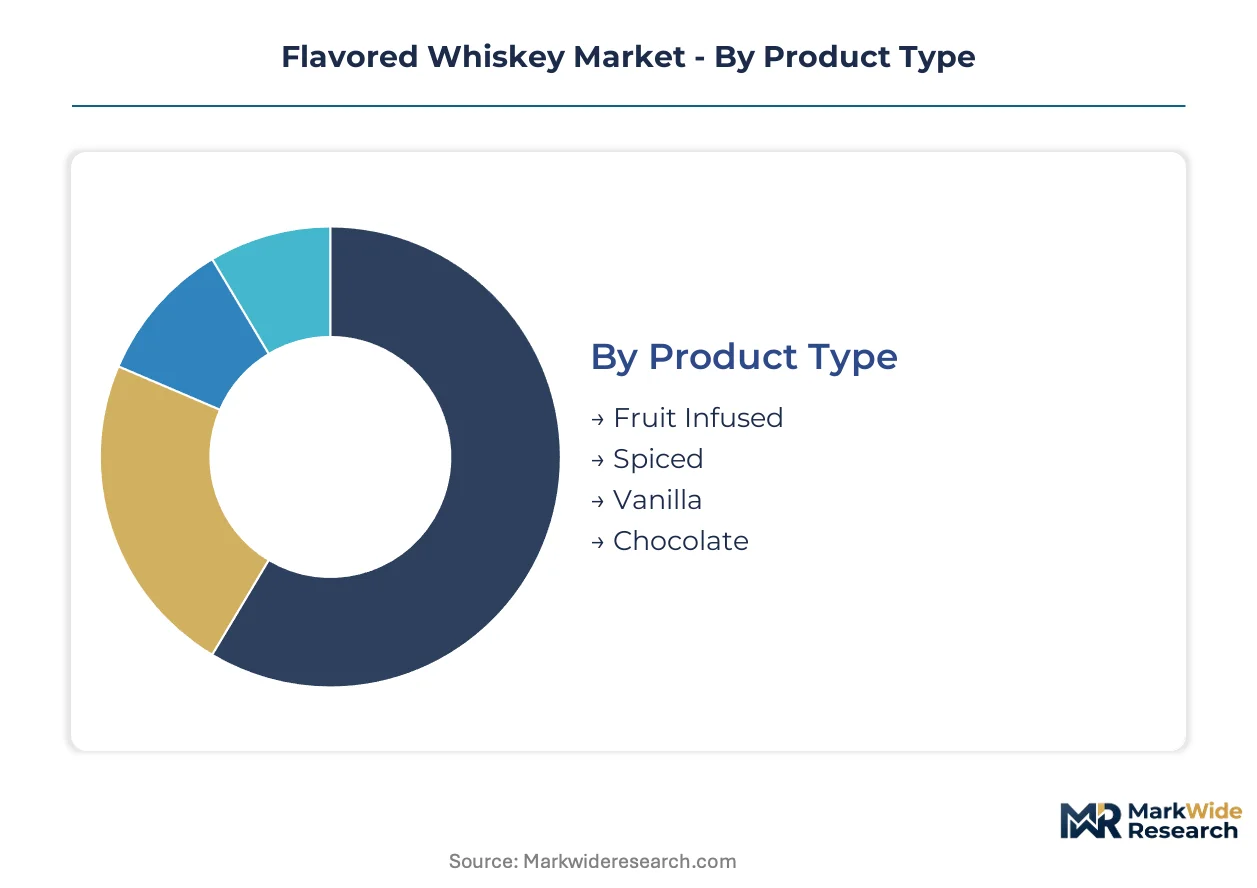
Segmentation in flavored whiskey reveals how formulation, demographic targeting, and channel strategy create distinct margin architectures. Understanding these divides enables producers to allocate maturation inventory and marketing spend against specific consumption occasions rather than treating the category as monolithic.
Product Type:
Mature spiced expressions anchor shelf stability while emerging fruit variants compress innovation cycles.
- Fruit Infused:Post-distillation berry-citrus and stone fruit infusions bottled at 35-40% ABV. Demand concentrates in American metropolitan retail clusters where seasonal release calendars drive trial frequency among newer whiskey entrants.
- Spiced:Cinnamon, clove, and nutmeg formulations finished through accelerated oak contact or vapor infusion. Year-round distribution in controlled American liquor states generates predictable revenue basins resistant to flavor fatigue.
- Vanilla:Dessert-profile expressions utilizing natural extract or synthetic vanillin systems targeting gift-format purchasing in premium glass packaging.
- Chocolate:Cocoa-derived flavoring agents creating after-dinner consumption occasions, primarily distributed through online retail and duty-free channels.
Spiced retains volume leadership; fruit infused holds the steepest expansion curve.
Customer Type:
Cost tier stratification separates accessible entry points from heritage-premium positioning.
- Millennials:Digital-native cohorts discovering whiskey through cocktail culture and subscription services, concentrated in urban on-premise channels.
- Gen X:Established palate owners seeking flavor diversity without abandoning base spirit familiarity, active in both liquor store and bar discovery.
- Baby Boomers:Traditional whiskey consumers occasionally trading into flavored expressions for social occasions rather than repertoire replacement.
- Affluent Consumers:Premium segment purchasers prioritizing packaging aesthetics and limited releases for collector and gifting purposes.
Millennials command the volume trajectory; affluent consumers deliver the highest per-unit margin realization.
Packaging Type:
Application context dictates material selection across on-premise versus off-premise consumption moments.
- Glass Bottle:Standard 750ml and 1L formats dominating American liquor store and supermarket shelves, with premium closures signaling quality tier.
- Tetra Pak:Aseptic cartons enabling single-serve and travel-size distribution in markets with relaxed spirits packaging regulations.
- Canned:Ready-to-drink formulations targeting outdoor consumption and convenience retail, expanding fastest among millennial trial occasions.
- Keg:On-premise dispense systems for high-volume bar programs, reducing per-ounce cost in metropolitan cocktail establishments.
Glass bottle maintains channel dominance; canned formats are climbing the fastest in new consumer acquisition.
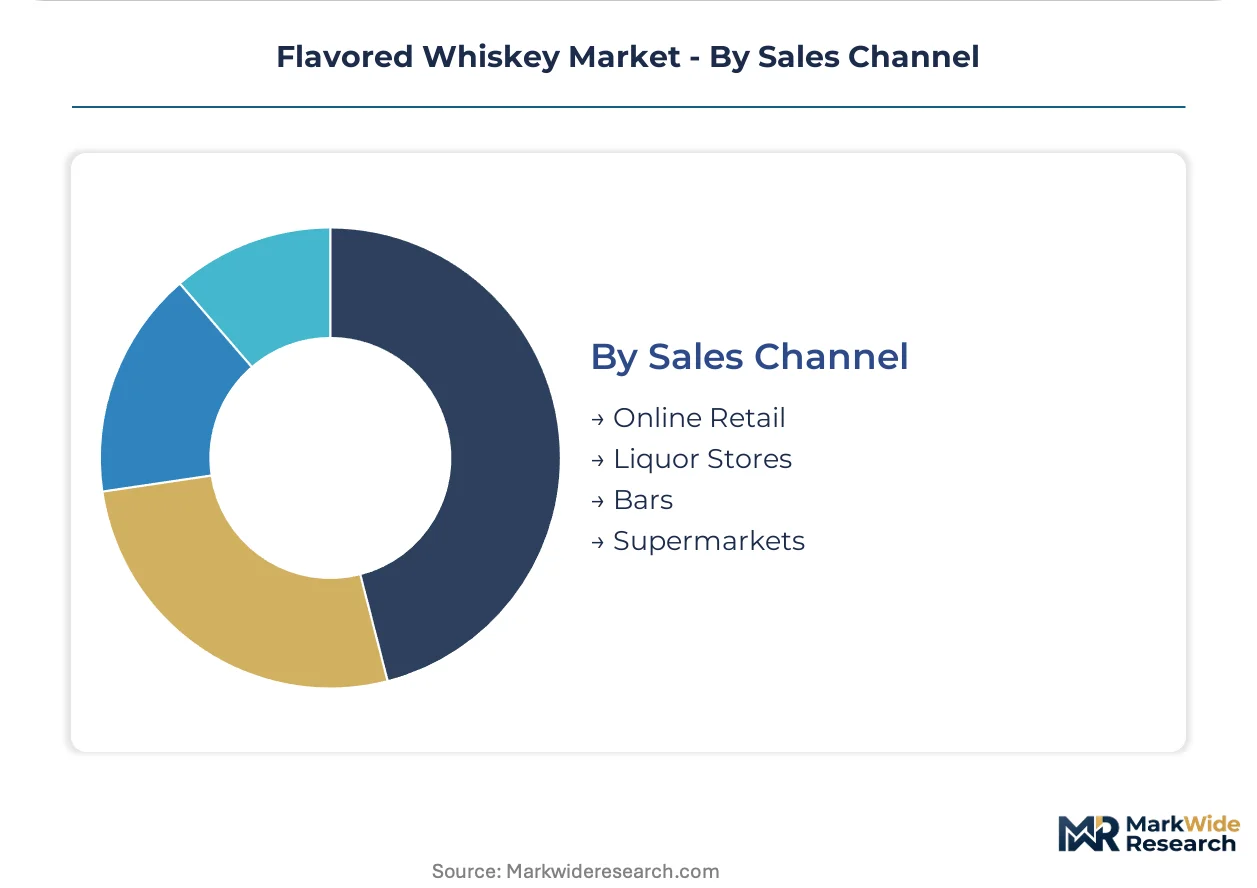
Sales Channel:
Geographic concentration of distribution infrastructure shapes regional availability patterns.
- Online Retail:Direct-to-consumer and third-party platforms capturing subscription replenishment and gift occasions in states permitting spirits shipping.
- Liquor Stores:Controlled and open-market independent retailers providing discovery browsing and staff recommendation influence.
- Bars:On-premise cocktail programs generating pull-through demand through reformulated classics and signature creations.
- Supermarkets:Grocery chains with spirits licenses in select American states, emphasizing convenience and promotional pricing.
Liquor stores retain volume leadership; online retail posts the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
American consumers demonstrate the highest price elasticity for entry-level fruit-infused expressions, while German and Japanese buyers absorb premiums for heritage-positioned spiced variants with minimal volume erosion.
United States
Millennial trial occasions concentrate in metropolitan cocktail bars across New York, Chicago, and Los Angeles, where reformulated classics drive pull-through demand. TTB labeling mandates for additive disclosure compel cleaner ingredient sourcing from domestic producers. Kentucky's bourbon corridor and Tennessee's whiskey belt anchor production gravity, with Louisville and Nashville clusters housing maturation warehouses and cooperage infrastructure.
Germany
Berlin and Munich on-trade channels exhibit accelerating demand for Irish whiskey heritage positioning, creating white space for cinnamon-spice flavor extensions. EFSA minimum alcohol thresholds and REACH chemical registration requirements force reformulation of artificial flavoring agents in export-bound American expressions. Hamburg's port infrastructure facilitates duty-free distribution into Northern European retail channels.
Japan
Affluent consumers in Tokyo and Osaka prioritize premium glass packaging for gift-format vanilla and chocolate segments, with limited releases commanding collector premiums. METI standards and national tax agency regulations govern spirits labeling and import classifications. The Kanto region's retail density supports specialized liquor boutiques with trained staff influencing discovery browsing.
United Kingdom
London's cocktail culture drives on-premise adoption of flavored whiskey bases in reformulated classics across Soho and Shoreditch establishments. HMRC excise frameworks and geographic indication protections shape which products qualify for protected whiskey designation versus spirit drink classification. Scotland's distilling heritage clusters around Speyside and Islay, though flavored expressions remain concentrated in English metropolitan retail.
Canada
Domestic consumers display strong affinity for Crown Royal flavor extensions, with duty-free channels at Toronto Pearson and Vancouver International capturing cross-border American purchasing. Health Canada and PMRA regulations govern additive safety assessments and labeling requirements. Ontario's provincial liquor control board structure determines wholesale pathway access for new flavor variants entering the market.
Flavored Whiskey Market Vendor Landscape
Capability concentration sits with heritage distilleries holding decades of maturation inventory; scale advantage sits with multinational spirits conglomerates controlling global distribution networks. The market structure tiers between mass-market flavor extensions and craft-positioned limited releases. Three archetypes dominate: diversified spirits giants with whiskey portfolios, regional distilleries with heritage positioning, and craft operators leveraging accelerated production techniques. Competitive moves center on controlled distribution negotiations for travel retail exclusives and portfolio diversification into seasonal flavor pipelines.
Among diversified spirits conglomerates, Diageo and Brown-Forman occupy positions exemplifying scale-driven market presence, while Suntory Global Spirits represents the transnational integration of American heritage brands with Japanese corporate ownership structures. Pernod Ricard anchors the European-centric competitive vector through Irish whiskey heritage positioning. These entities exemplify archetypal competitive strategies without constituting an exhaustive market census.
| Leading Market Players |
|---|
| Suntory Global Spirits (Jim Beam) |
| Beam Suntory |
| Diageo (Crown Royal) |
| Johnnie Walker |
| Buffalo Trace Distillery |
| Pernod Ricard (Jameson) |
| Heaven Hill (Evan Williams) |
| Compass Box |
| Brown-Forman (Jack Daniel's) |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Kentucky cooperage infrastructure is compressing maturation timelines and forcing distillers toward accelerated finishing techniques that reshape both cost structures and premium positioning strategies.
Pricing Analysis
After-sales revenue through duty-free exclusives and collector-format releases drives lifetime value more than standard retail turnover. Three-tier pricing structure across premium, standard, and economy levels separates heritage-positioned expressions from craft-limited releases and mass-market flavor extensions. Price differentiation hinges on maturation inventory depth and TTB-compliant additive transparency. Cost compression in mid-tier fruit-infused segments is intensifying because corn input volatility squeezes producers lacking long-term grain hedging. Millennials exhibit highest price sensitivity, while affluent collectors absorb premiums for vanilla and chocolate gift formats.
Supply Chain Analysis
Tariff exposure between American and European markets dominates supply chain risk planning for flavored whiskey exporters. Production gravity centers on Kentucky, Tennessee, and Ireland, with maturation warehouses clustering around Louisville, Nashville, and Dublin. Raw material dependencies include American corn and rye, European oak cooperage, and natural fruit extracts for REACH-compliant formulations. Single-source vulnerability in master blender talent pools threatens formulation consistency as experienced practitioners retire. Distribution runs through controlled state liquor boards in American markets and independent wholesalers in open jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavored whiskey operates as a cyclical recovery play, with millennial trial frequency and cocktail program expansion providing the demand pulse that lifts volume commitments from distributors.
For Market Incumbents: Pre-empt craft distillery encroachment by locking exclusive barrel contracts with Kentucky cooperage suppliers and accelerating AI-driven sensory mapping to compress seasonal release cycles. Vertical integration into natural extract sourcing hedges against REACH-driven reformulation costs for European export compliance.
For New Entrants and Emerging Players: Pursue German on-trade white space in Berlin cocktail bars where Irish whiskey heritage positioning has established trial behavior but Canadian cinnamon-spice variants remain underrepresented. Direct-to-consumer subscription models in American metropolitan clusters offer the most penetrable channel for vanilla and chocolate premium segments.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among craft distilleries with established tasting club memberships and predictable seasonal release calendars. Long-term viability over the coming decade favors operators with controlled distribution agreements in Dubai and Singapore travel retail. Watch FDA added-sugar disclosure guidance as the inflection signal separating first-mover natural extract adopters from laggard reformulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Tasting clubs in New York and Chicago capture trial occasions that previously occurred in retail aisles. |
| Natural Extract Reformulation | REACH compliance in European markets forces substitution of artificial flavoring agents with botanical partnerships. |
| Travel Retail Exclusive Development | Duty-free channels at Singapore Changi reward controlled distribution with premium shelf placement. |
| AI-Driven Sensory Mapping Investment | Virtualized master blender roles reduce iteration cycles for seasonal fruit expression launches. |
| Cooperage Supplier Integration | Captive oak sourcing secures maturation capacity against Kentucky warehouse undercapacity pressures. |
Methodological Framework
The analysis maps fruit-infused, spiced, vanilla, and chocolate sub-sectors, each validated through master blenders, distributor category managers, on-premise beverage directors, and retail liquor buyers. Primary interviews with these stakeholders combined secondary validation from TTB labeling filings, EFSA additive safety assessments, customs import records, and Nielsen off-premise retail audit data. Bottom-up volume triangulation against top-down value estimation ensures cross-verification of segment sizing.
Assumptions held fixed include TTB and EFSA regulatory frameworks, grain input cost corridors, and travel retail channel access terms, while millennial consumption velocity and AI adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled include flavor profile, customer cohort, packaging format, and sales channel across the analysis window. CAGRs derived from historical volume trajectories and projected trial-to-repurchase conversion rates, with specific inputs from seasonal release calendar density and cocktail program adoption curves.
Sensitivities concentrate around FDA added-sugar disclosure timing, state-level distribution franchise law amendments, and climate-related warehouse loss events in Kentucky. Forecasts reflect these documented assumptions with acknowledged revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Bottled Craft Beer Market
Alcoholic Beverages
Fruit Beer Market
Alcoholic Beverages
Home Brewing Systems Market
Alcoholic Beverages
Decanter Market
Alcoholic Beverages
South America Craft Beer Market
Alcoholic Beverages
Ready to Drink Cocktails Market
Alcoholic Beverages
Apple Wine Market
Alcoholic Beverages
Chocolate Liqueur Market
Alcoholic Beverages
Honey Wine Market
Alcoholic Beverages
Orange Wine Market
Alcoholic Beverages
Wine Destemmer Market
Alcoholic Beverages
Global Beer Market
Alcoholic Beverages
Organic Alcoholic Beverages Market
Alcoholic Beverages
Tonic Wine Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Dark Beer Market