
 GCC Beer Market | 2026-2036
GCC Beer Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Beer Market Intelligence
Aftermarket service revenue from draft system maintenance and keg logistics is tilting margin pools away from pure production toward equipment and service ecosystems. Heineken N.V. anchors its GCC position through captive distribution networks and licensed brewing partnerships. Aujan Group Holding dominates local manufacturing scale in Saudi Arabia, producing non-alcoholic malt beverages for regional export. Anheuser-Busch InBev leverages global procurement power to compete on imported premium lager positioning in Dubai and Abu Dhabi duty-free channels.
Beer comprises fermented cereal beverages typically brewed from malted barley, hops, water, and yeast through mashing, boiling, fermentation, and conditioning processes, yielding alcohol content ranging from zero percent in dealcoholized variants to approximately five percent in standard lagers, serving social consumption, food pairing, and hospitality refreshment functions across commercial and personal settings. Lager commands the volume base across GCC markets due to heat-climate refreshment preferences and mainstream palate familiarity, while non-alcoholic variants within consumer preference segments are expanding fastest as Saudi Arabia and Kuwait maintain prohibition frameworks. Supermarkets and online retail channels within distribution channel segmentation are capturing incremental share as Dubai and Bahrain modernize off-premise purchasing regulations.
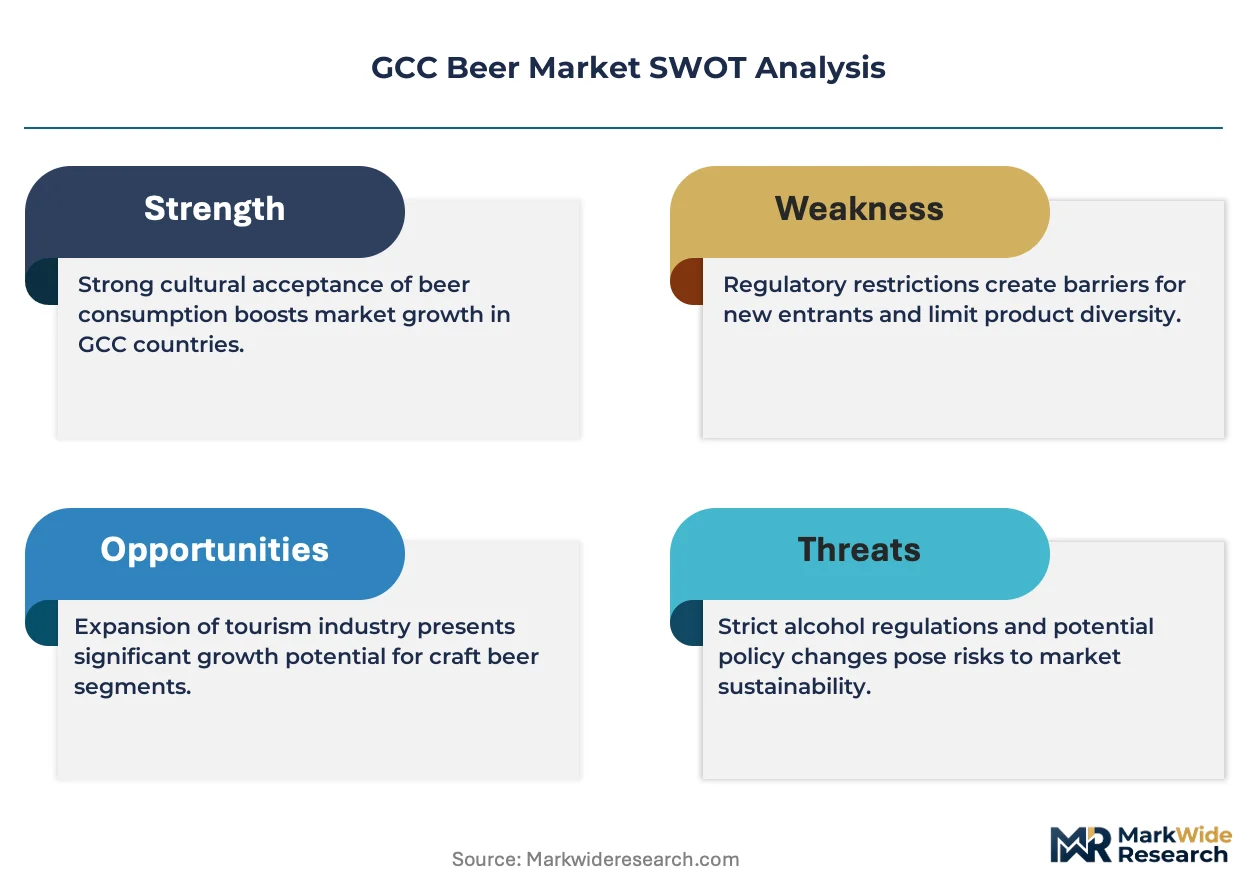
The UAE's Department of Culture and Tourism coordinates with municipal licensing authorities in Dubai and Ras Al Khaimah to regulate alcohol sales permits, while Saudi Arabia's General Authority for Food and Drug Administration enforces zero-alcohol standards that shape product formulation across regional manufacturing. Bahrain's National Health Regulatory Authority monitors labeling and import standards that govern cross-border trade flows. Stakeholders must monitor licensing liberalization trajectories in secondary emirates and evaluate non-alcoholic product line extensions as the primary vector for Saudi market participation.
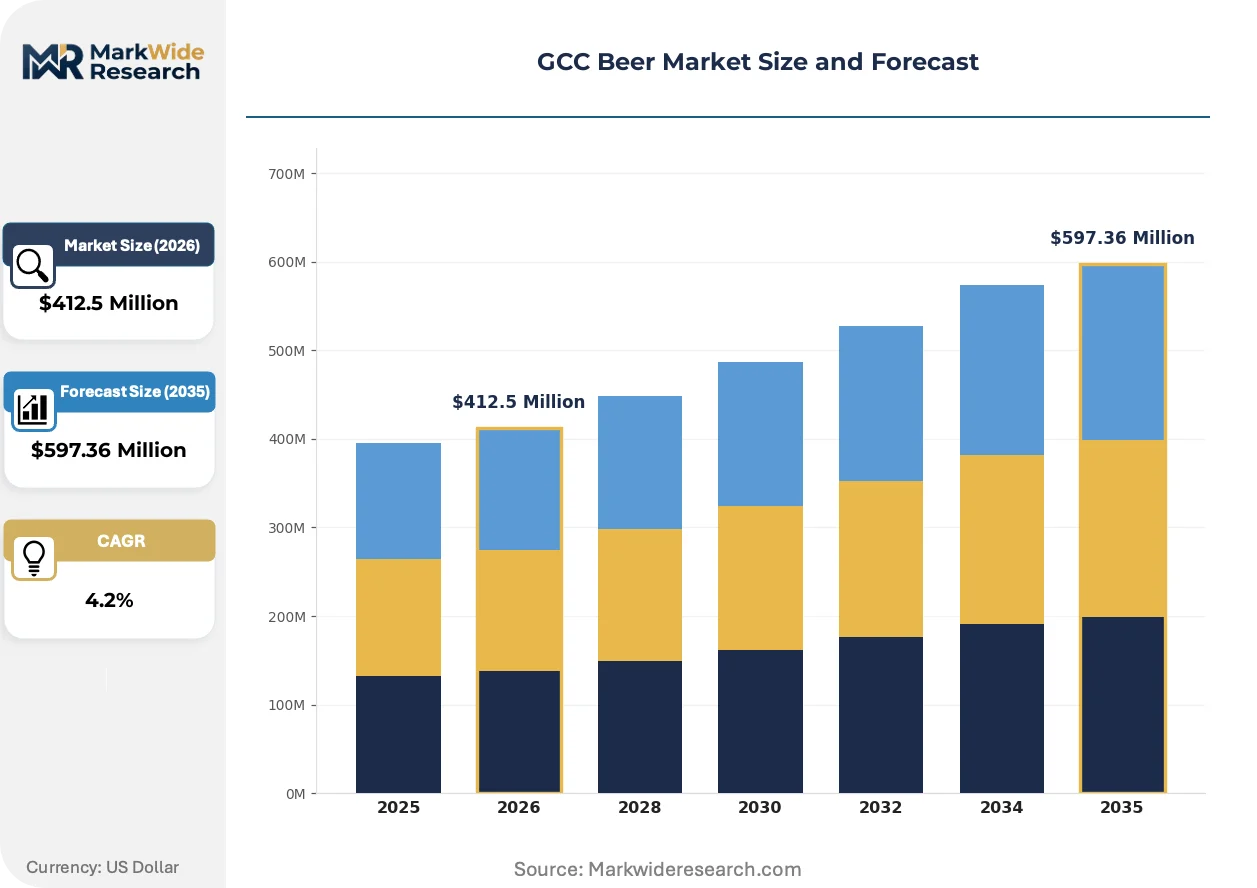
Market Dynamics
Tourism infrastructure maturation across the Gulf Cooperation Council is redirecting margin pools from packaged goods toward draft service ecosystems and hospitality-integrated supply chains. Licensing liberalization in secondary UAE emirates and Bahrain is compressing traditional distribution hierarchies.
Growth Catalysts
- Dealcoholization technology maturation:Membrane filtration and vacuum distillation processes now preserve flavor profiles in zero-alcohol variants, enabling compliant product lines for Saudi Arabia and Kuwait prohibition frameworks.
- Dubai's Department of Tourism and Commerce Marketing:Streamlined alcohol licensing for hotels and restaurants is expanding on-premise consumption venues and keg infrastructure deployment.
- Cross-border tourism corridors:Bahrain and the UAE are capturing weekend demand from Saudi residents through duty-free retail and hospitality destination positioning.
Market Restraints
- Barley import dependency:Regional brewing operations source malted barley from EU and Australian suppliers, exposing margin structures to agricultural commodity volatility and shipping lane disruptions.
- MOHAP licensing concentration:UAE alcohol permits remain concentrated in Dubai and Ras Al Khaimah, constraining distribution reach into Sharjah and Ajman where prohibition persists.
- Glass and aluminum packaging cost structures:Imported container materials face Gulf customs duties that inflate finished goods pricing versus locally manufactured non-alcoholic alternatives.
Strategic Opportunities
- E-commerce channel formalization:Dubai's updated off-premise regulations are enabling licensed supermarket chains to operate online ordering platforms with age-verification integration.
- Hotel and resort development pipelines:Abu Dhabi's Yas Island and Saadiyat Island projects are embedding draft system infrastructure requirements into hospitality construction specifications.
- Non-alcoholic flavor innovation:Hop-forward and craft-style malt beverages without fermentation are creating premium positioning vectors within Saudi Arabia's zero-tolerance regulatory environment.
Industry Challenges
- Sommelier and draft technician talent pipelines:Hospitality expansion is outpacing certified draft system maintenance professionals and beer service specialists across the UAE and Bahrain.
- Multi-jurisdiction compliance complexity:Manufacturers must maintain parallel formulation registries for alcoholic, dealcoholized, and zero-fermentation variants to satisfy SFDA, MOHAP, and Bahrain National Health Regulatory Authority standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Beer Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lager, Ale, Stout, Wheat Beer Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Bars Packaging Type: Bottle, Can, Keg, Draft Consumer Preference: Local Brands, Imported Brands, Craft Beer, Non-Alcoholic |
| Companies Covered | Anheuser-Busch InBev, Heineken N.V., Carlsberg Group, Diageo, Boston Beer Company, Aujan Group Holding, Clausthaler, Mahmood Saeed, Moussy, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Beer Market Strategic Shifts & Innovations
Product formulation and service delivery models across the GCC are pivoting toward regulatory compliance and hospitality integration rather than traditional retail scale. Technology adoption is concentrating in dealcoholization and draft system efficiency.
Membrane-based dealcoholization systems are migrating from laboratory-scale piloting to production-line integration across regional manufacturing facilities. Saudi-based producers are adopting these systems to supply both domestic zero-alcohol markets and export-compliant low-alcohol variants to Dubai and Bahrain. This technology compression is collapsing the traditional separation between alcoholic and non-alcoholic supply chains, enabling single-facility flexibility.
MOHAP's 2023 licensing framework revisions in Dubai introduced digital permit tracking and automated renewal systems that reduce administrative friction for hospitality venues. The industrial consequence is accelerated venue opening timelines and reduced compliance staffing requirements. Hotel groups in Abu Dhabi and Ras Al Khaimah are responding by front-loading draft infrastructure investment ahead of permit finalization.
Buyer concentration in hospitality procurement is displacing fragmented retail purchasing as the dominant demand signal. Large hotel operators in Dubai and Bahrain are consolidating beverage sourcing through centralized procurement platforms that bypass traditional distributor tiers. This channel compression is most visible in Abu Dhabi's Yas Island development cluster, where master development agreements embed exclusive supply relationships with single-source beverage service providers.
GCC Beer Market Segmentation
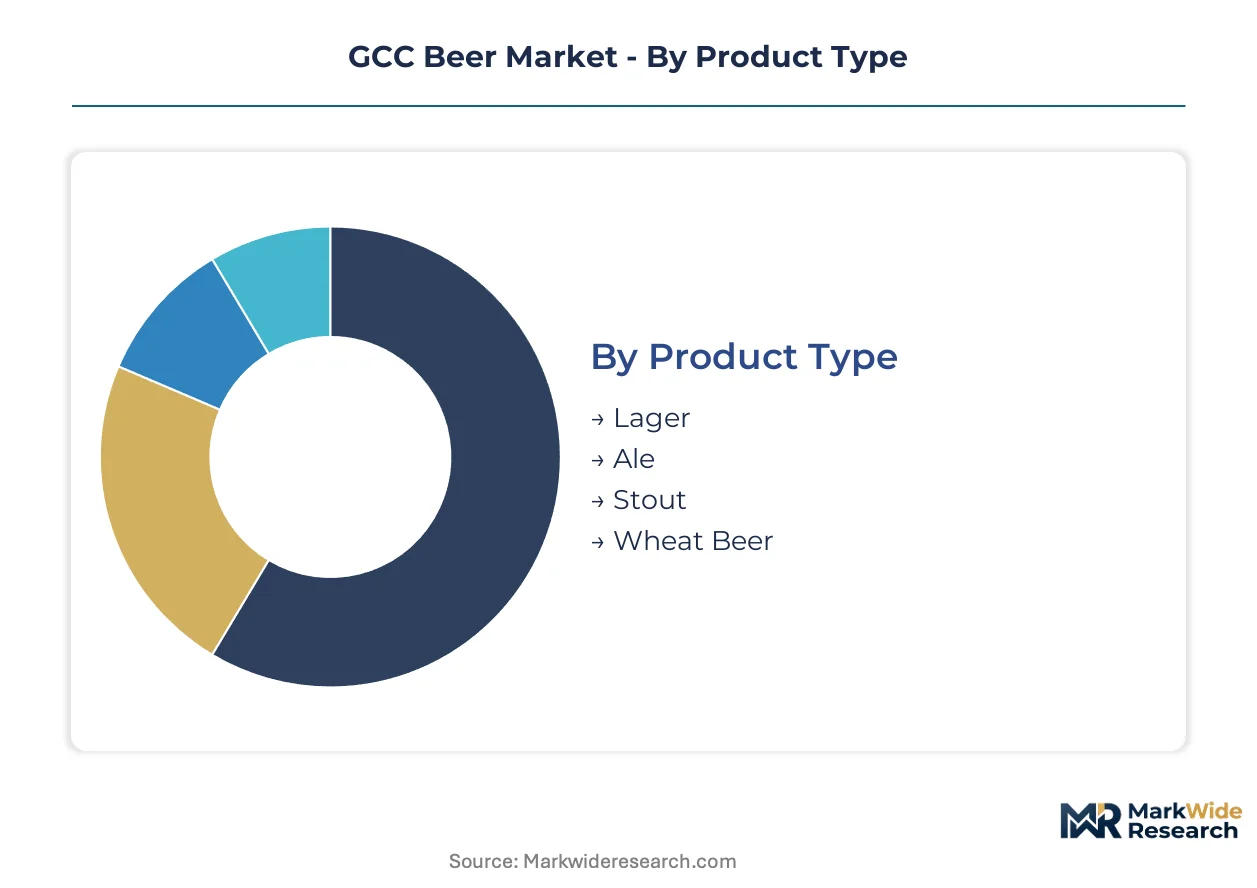
Segmentation reveals how regulatory fragmentation and hospitality infrastructure maturation are reshaping product mix and channel priorities across Gulf Cooperation Council markets. Understanding these divisions exposes where margin pools concentrate and where compliance complexity creates operational friction.
Product Type:
Lager cycles through inventory fastest due to volume turnover in Dubai and Bahrain hospitality venues, while stout and wheat beer move more slowly through specialized retail channels.
- Lager:Fermented at low temperatures using bottom-fermenting Saccharomyces pastorianus yeast, producing clean, crisp flavor profiles optimized for heat-climate refreshment. Demand concentrates in Abu Dhabi and Dubai hotel properties where draft infrastructure supports high-velocity service during peak tourism seasons. MOHAP licensing liberalization in Ras Al Khaimah is expanding keg deployment beyond traditional Dubai concentration zones.
- Non-Alcoholic:Dealcoholized through membrane filtration or vacuum distillation to preserve hop character while achieving zero percent ABV compliance. Saudi Arabia's SFDA zero-tolerance standards drive formulation investment here, with Aujan Group Holding scaling production for both domestic distribution and regional export to Kuwait. The segment's supply cycles align with Ramadan purchasing patterns and religious calendar constraints rather than weather-driven seasonality.
- Ale:Top-fermented at warmer temperatures yielding fruitier ester profiles, occupying niche positioning in Dubai craft-focused bars and licensed hotel lounges.
- Stout:Dark-roasted malt varieties with higher bitterness and body, serving limited demand in European expatriate communities and specialty import retailers.
- Wheat Beer:Unfiltered or filtered varieties brewed with significant wheat malt proportion, finding placement in German-themed hospitality venues and seasonal summer promotions.
Lager anchors the volume base while non-alcoholic gains share at the steepest rate.
Distribution Channel:
Cost tier separation distinguishes capital-intensive on-premise draft systems from lower-barrier retail packaging, with channel selection directly determining licensing compliance burden and margin structure.
- Bars:On-premise consumption venues requiring MOHAP or Bahrain National Health Regulatory Authority alcohol service permits, with keg infrastructure representing the highest capital deployment per outlet. Dubai's Department of Tourism and Commerce Marketing streamlined licensing is accelerating venue openings on Sheikh Zayed Road and Dubai Marina corridors, compressing distributor margins through direct procurement relationships.
- Supermarkets:Licensed off-premise retail requiring age-verification systems and segregated alcohol sections, with Spinneys and Choithrams chains in Dubai capturing incremental share as online integration matures.
- Online Retail:E-commerce platforms with embedded digital age verification, enabled by Dubai's 2023 regulatory revisions permitting licensed supermarket chains to operate delivery services.
- Convenience Stores:Smaller-format retail with limited SKU breadth, concentrated in Bahrain and select Dubai free zones where licensing permits broader distribution reach.
Bars command the premium margin tier while online retail climbs fastest as regulatory formalization progresses.
Packaging Type:
Volume concentration separates high-throughput draft systems from individual-serve formats, with packaging choice determining logistics complexity and import duty exposure.
- Keg:Stainless steel returnable containers in 30L and 50L formats, dominating hospitality procurement in Abu Dhabi's Yas Island and Saadiyat Island developments where master development agreements specify draft infrastructure. Aftermarket service revenue from line cleaning and tap maintenance is tilting margin pools toward equipment ecosystems.
- Can:Aluminum single-serve packaging with superior heat conductivity and lighter logistics burden, gaining preference in outdoor and beach-adjacent consumption settings across Dubai and Bahrain.
- Bottle:Glass packaging with higher customs duty exposure due to Gulf import tariffs on container materials, concentrated in premium positioning and hotel minibar placements.
- Draft:Direct-from-tank service requiring permanent installation, embedded in construction specifications for new hospitality developments rather than retrofit opportunities.
Keg systems capture the hospitality volume base while can packaging expands most quickly in outdoor and tourism-adjacent channels.
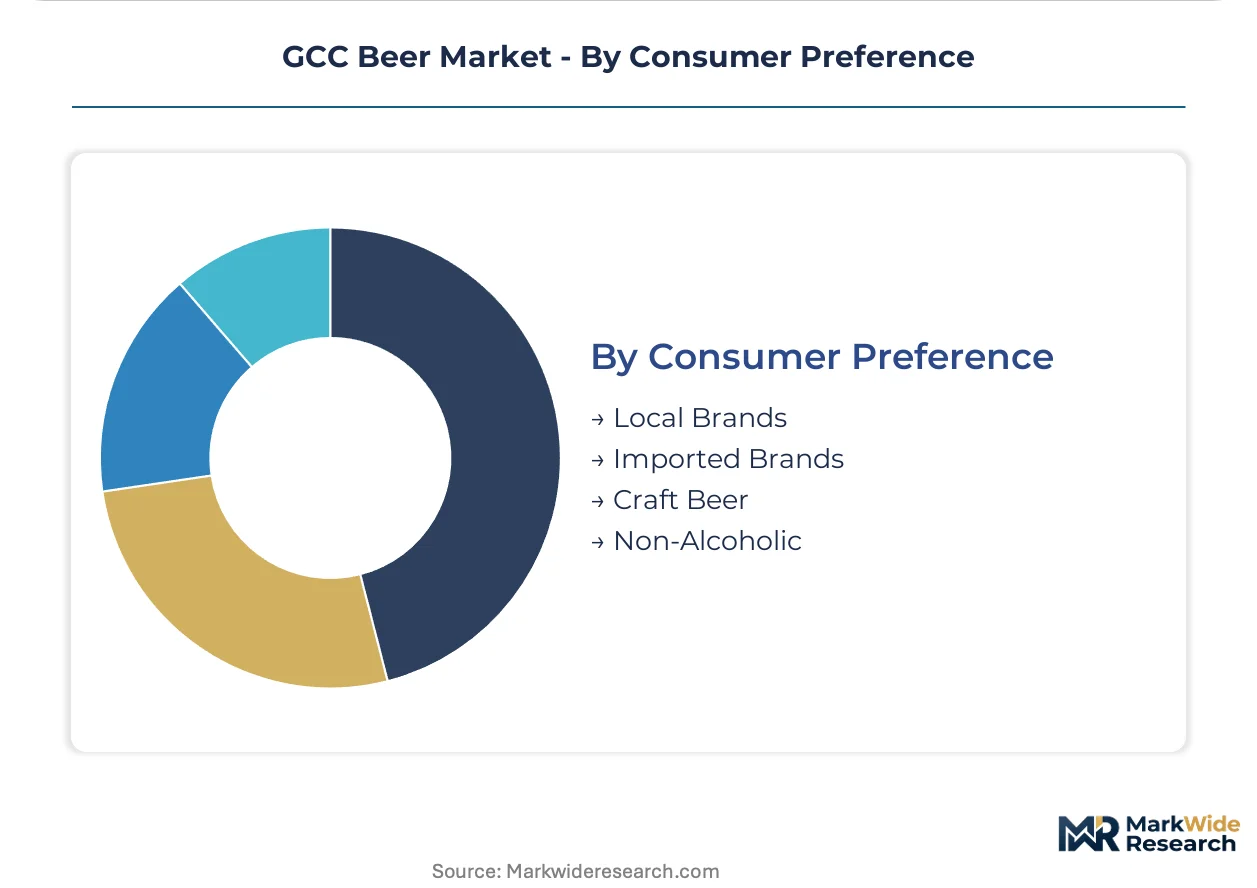
Consumer Preference:
Customer type fragmentation separates price-sensitive local manufacturing from premium import positioning, with preference signaling directly mapping to regulatory compliance strategy.
- Imported Brands:Heineken N.V. and Anheuser-Busch InBev products entering through Dubai and Abu Dhabi duty-free channels, commanding premium positioning through global procurement scale and brand recognition. Cross-border tourism corridors from Saudi Arabia into Bahrain and the UAE concentrate demand here.
- Local Brands:Aujan Group Holding manufactured non-alcoholic malt beverages produced within Saudi Arabia for regional export, leveraging SFDA compliance as competitive moat against import-dependent competitors.
- Craft Beer:Small-batch production emphasizing hop-forward profiles and style diversity, limited to Dubai and Bahrain where licensing permits microbrewery operations.
- Non-Alcoholic:Dealcoholized and zero-fermentation variants formulated specifically for Saudi Arabia and Kuwait prohibition frameworks, with flavor innovation in hop-forward profiles creating premium positioning within regulatory constraints.
Imported brands anchor the revenue base while non-alcoholic preference segments climb fastest as Saudi market participation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across GCC member states diverge sharply between alcoholic and non-alcoholic variants, with prohibition frameworks in Saudi Arabia and Kuwait redirecting demand toward dealcoholized alternatives while the UAE and Bahrain sustain full-strength hospitality markets.
United Arab Emirates
Dubai's tourism corridor drives keg infrastructure deployment across Sheikh Zayed Road and Marina districts, with MOHAP licensing reforms accelerating venue openings. Ras Al Khaimah's 2023 permit streamlining is expanding distribution reach beyond traditional Dubai concentration zones. Abu Dhabi's Yas Island and Saadiyat Island developments embed draft system specifications into master hospitality agreements.
Saudi Arabia
SFDA zero-tolerance standards concentrate demand entirely in non-alcoholic malt beverages, with Ramadan purchasing patterns replacing weather-driven seasonality. Aujan Group Holding scales manufacturing for domestic distribution and regional export to Kuwait. Cross-border weekend tourism flows into Bahrain and the UAE sustain parallel demand for full-strength variants.
Bahrain
The National Health Regulatory Authority monitors labeling and import standards governing duty-free retail channels serving Saudi visitors. Manama's hospitality cluster captures weekend demand through hotel-integrated beverage procurement. Keg logistics infrastructure supports high-velocity service during peak tourism periods.
Kuwait
Prohibition frameworks mirror Saudi regulatory architecture, channeling demand toward dealcoholized variants formulated for SFDA-equivalent compliance. Supermarket and convenience store distribution dominates off-premise purchasing. Regional manufacturing from Saudi Arabia supplies the majority of compliant product volume.
GCC Beer Market Key Industry Players
Capability concentration sits with multinational brewers possessing captive distribution networks; scale advantage sits with regional manufacturers leveraging local formulation compliance. The market structures around three tiers: global brand owners with integrated supply chains, licensed production partners serving prohibition markets, and hospitality-focused service providers capturing draft system aftermarket revenue. Consolidation pressure runs through direct procurement relationships between hotel operators and beverage suppliers, bypassing traditional distributor hierarchies. Portfolio diversification into non-alcoholic variants and keg infrastructure services represents the dominant competitive response.
Among global brand owners, Heineken N.V. and Anheuser-Busch InBev occupy positions anchored by duty-free channel presence and licensed brewing partnerships. Aujan Group Holding exemplifies the regional manufacturing archetype, with its Saudi-based production serving both domestic zero-alcohol requirements and export markets. These three entities represent distinct strategic postures: global procurement scale, hospitality-integrated distribution, and regulatory-compliant local manufacturing.
| Leading Market Players |
|---|
| Anheuser-Busch InBev |
| Heineken N.V. |
| Carlsberg Group |
| Diageo |
| Boston Beer Company |
| Aujan Group Holding |
| Clausthaler |
| Mahmood Saeed |
| Moussy |
| Others |
Cost & Logistics Intelligence
Barley import dependency from EU and Australian suppliers exposes margin structures to agricultural commodity volatility and shipping lane disruptions, compressing pricing tiers between premium imported lagers and locally manufactured non-alcoholic alternatives while forcing keg infrastructure investments to absorb customs duty exposure on glass and aluminum packaging.
Pricing Analysis
Long-term offtake agreements between Abu Dhabi hotel operators and beverage service providers anchor the hospitality procurement tier, while spot purchasing dominates duty-free retail channels serving cross-border Saudi demand. Price differentiation rests on import duty exposure and keg infrastructure bundling, with premium imported brands commanding widest spreads over local non-alcoholic variants. Cost compression in standard lager tiers is intensifying because glass packaging faces Gulf customs duties that inflate finished goods pricing. Hotel procurement managers exhibit lowest price sensitivity due to master development agreement specifications, while supermarket chains capture incremental share through volume scale negotiations.
Supply Chain Analysis
SFDA zero-tolerance standards and MOHAP licensing frameworks function as export-control regimes limiting alcoholic beverage flows into Saudi Arabia and Sharjah, redirecting supply chain configuration toward dealcoholization technology corridors. Manufacturing concentrates in Saudi Arabia for non-alcoholic variants, the UAE for licensed brewing partnerships, and Germany for premium imported lagers. Malted barley, hop extracts, and stainless steel keg hardware constitute critical input dependencies. Single-source vulnerability sits with EU barley suppliers exposed to agricultural commodity swings. Distribution runs through captive hospitality networks in Dubai and duty-free retail channels in Bahrain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Draft system maintenance and keg logistics aftermarket layers are expanding faster than pure production volumes, transforming the market into a service-attach opportunity where equipment ecosystems capture recurring revenue streams.
For Market Incumbents: Insulate margin pools by deepening backward integration into keg manufacturing and line cleaning service networks, countering direct procurement relationships between hotel operators and beverage suppliers. Prioritize certification investment for SFDA-compliant dealcoholization processes to maintain Saudi market access against emerging regional competitors. For New Entrants and Emerging Players: Establish a beachhead in Ras Al Khaimah's expanding licensing corridor, where MOHAP permit streamlining has compressed venue opening timelines below Dubai saturation levels. Target non-alcoholic flavor innovation for Kuwait's prohibition framework, leveraging Saudi manufacturing partnerships for regional export compliance. Deploy e-commerce platform integration with licensed supermarket chains as the primary go-to-market angle. For Investors and Strategic Acquirers: Hospitality-integrated beverage service providers with captive draft infrastructure deployments represent the most defensible acquisition archetype. Long-term viability across the analysis window hinges on regulatory liberalization trajectories in secondary UAE emirates and dealcoholization technology maturation. Watch for MOHAP licensing expansion into Ajman as the inflection signal for geographic margin pool redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Dealcoholization Technology Licensing | Membrane filtration partnerships enable SFDA-compliant production for Saudi Arabia and Kuwait prohibition markets. |
| Keg Infrastructure Expansion | Stainless steel returnable container networks capture aftermarket service revenue from Abu Dhabi Yas Island developments. |
| E-commerce Channel Formalization | Licensed supermarket digital platforms with age-verification integration unlock Dubai's off-premise regulatory modernization. |
| Cross-Border Tourism Corridor Positioning | Bahrain duty-free retail placement captures weekend demand flows from Saudi residents seeking full-strength variants. |
| Non-Alcoholic Flavor Innovation | Hop-forward malt beverages without fermentation create premium positioning within zero-tolerance regulatory constraints. |
Research Approach
A spread of perspectives from brewery operations directors, hospitality procurement managers, MOHAP licensing officials, and keg logistics providers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade records, SEC filings of multinational brewers, and tourism infrastructure development databases. Bottom-up triangulation across product type, distribution channel, and packaging format dimensions was cross-checked against top-down macroeconomic indicators and regulatory framework assessments.
Demand-supply balance modeling across the projection horizon integrated hospitality venue opening pipelines, dealcoholization technology adoption curves, and cross-border tourism flow estimates. Segmentation dimensions included product type, distribution channel, packaging format, and consumer preference archetypes. CAGRs were derived from volume trajectory analysis anchored in licensing liberalization scenarios and infrastructure deployment timelines. Forecast inputs incorporated MOHAP permit issuance rates and SFDA formulation compliance certification data.
Stress conditions across barley commodity price volatility, shipping lane disruption scenarios, and regulatory liberalization pacing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding tourism infrastructure maturation and dealcoholization technology cost curves. Material shifts in Saudi Arabia's prohibition framework or MOHAP licensing geography would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Vermouth Market
Alcoholic Beverages
Rum Market
Alcoholic Beverages
Europe Alcohol E-Commerce Market
Alcoholic Beverages
Sparkling Wine Market
Alcoholic Beverages
Champagne Market
Alcoholic Beverages
Canada Wine Coolers Market
Alcoholic Beverages
Mexico Tequila Market
Alcoholic Beverages
Brewing Enzymes Market
Alcoholic Beverages
Drinkware, Beverageware, and Barware Market
Alcoholic Beverages
Alcopop Market
Alcoholic Beverages
Premixed Margarita Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Balsam Bottle Market
Alcoholic Beverages
Canned Wine Market
Alcoholic Beverages
US Frozen Cocktail Popsicles Market
Alcoholic Beverages
Germany Alcohol E-Commerce Market