
 Europe Wine Market | 2026-2036
Europe Wine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Wine Market Foresight
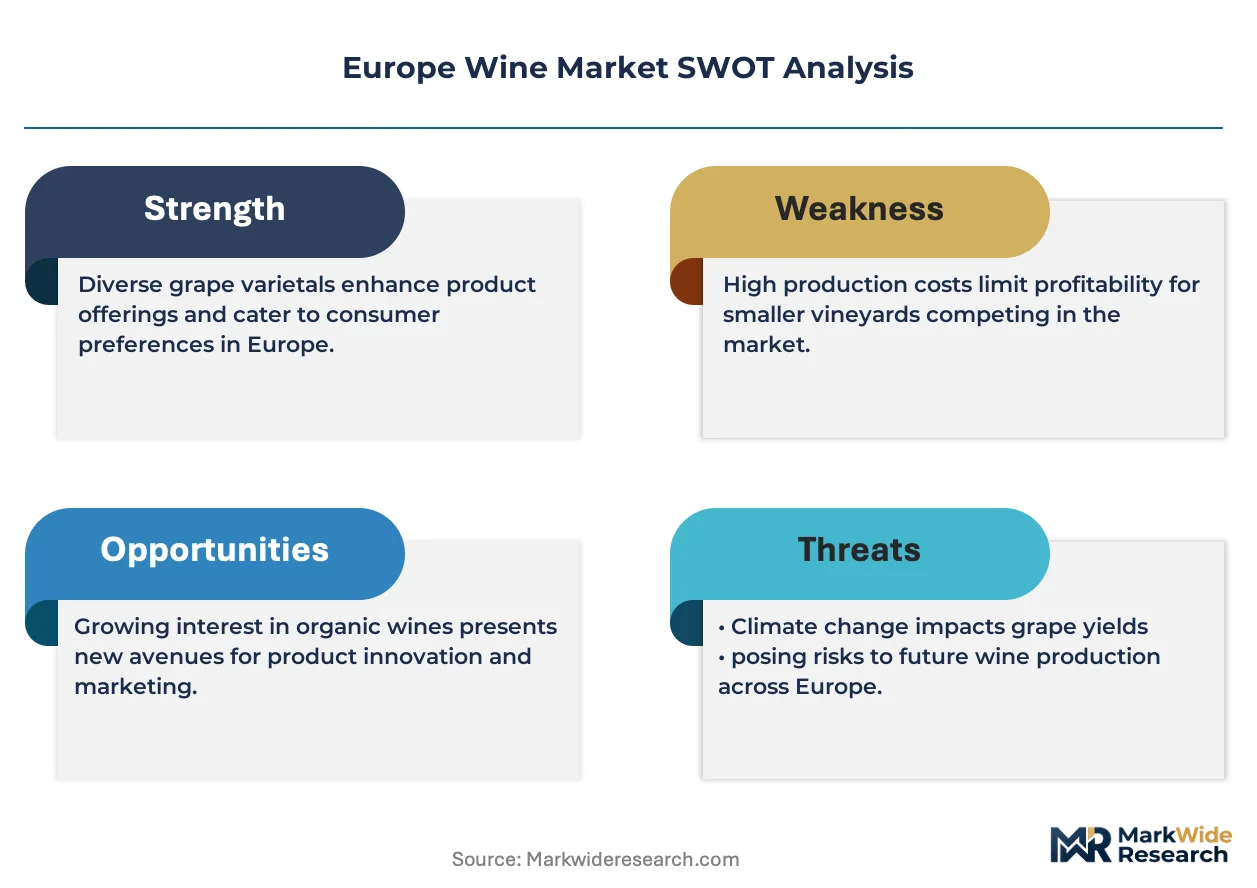
PDO and PGI certification under EU Regulation 1308/2013 is collapsing the field of legitimate market participants, forcing smaller producers into co-operative structures or private-label contracts. Moët Hennessy leverages its Champagne appellation control to sustain pricing power across European duty-free channels. Castel Group anchors volume supply through diversified sourcing across Languedoc-Roussillon and Bordeaux. Torres differentiates via organic and biodynamic estate bottling, competing directly with heritage houses on sustainability credentials.
Europe wine comprises fermented grape juice with alcohol content typically ranging from 9% to 15% ABV, produced through controlled yeast conversion of sugars and subject to strict appellation boundaries on varietal composition, yield limits, and aging protocols; its commercial purpose spans direct consumption, hospitality service, and investment-grade cellaring. Red wine occupies the largest volume share across European retail, while sparkling wine captures disproportionate margin concentration in export markets. Supermarkets dominate volume throughput, though online retail extends fastest as direct-to-consumer estate shipping gains regulatory clearance across member states.
EU Regulation 1308/2013, REACH, and the EU Green Deal's carbon-border adjustments collectively govern vineyard inputs, bottle labeling, and transport emissions, reshaping cost structures for cross-border trade. ECHA scrutiny of pesticide residues tightens maximum residue limits, forcing reformulation of vineyard management protocols. National regulators in France, Italy, and Spain enforce appellation compliance through INAO, MIPAAF, and ICEX respectively, creating fragmented but deepening compliance obligations. Stakeholders must monitor whether the EU AI Act's transparency requirements extend to algorithmic pricing tools deployed by major online retail platforms.
Market Dynamics
The EU Green Deal's carbon-border adjustments are forcing vineyard operators to reconfigure transport logistics and packaging materials, compressing margins for exporters while rewarding estate-bottled proximity supply.
Growth Catalysts
- EU Farm to Fork Strategy:Mandates for organic vineyard conversion accelerate premium positioning for certified producers. Compliance investments unlock access to green procurement channels.
- Sparkling wine demand:Italian Prosecco and Franciacorta sectors attract hospitality investment across France, Spain, and Germany. On-premise by-the-glass programs expand volume throughput.
- Direct-to-consumer shipping:Regulatory clearance for cross-border estate sales within member states bypasses traditional wholesale markups. Smaller producers capture margin previously lost to intermediaries.
Market Restraints
- Input cost volatility:Glass and cork supply concentration in Portugal and Spain exposes bottlers to energy-price pass-through. Alternative packaging adoption remains constrained by appellation labeling rules.
- PDO/PGI compliance burden:EU Regulation 1308/2013 documentation requirements consume administrative capacity at sub-scale producers. Certification costs disproportionately burden estates under fifty hectares.
- Climate yield compression:Heat stress in southern French and Spanish growing regions forces irrigation infrastructure investment where previously dry-farmed. Water access permits tighten under national drought protocols.
Strategic Opportunities
- Eastern European vineyard expansion:Romania and Bulgaria offer untapped terroir with lower land costs. Investment in local cooperative processing capacity builds supply optionality.
- Biodynamic certification convergence:Demeter and organic standards merge in consumer perception, allowing premium pricing without full biodynamic conversion. German and Austrian buyers lead this preference shift.
- Low-intervention wine formats:Pet-nat and pétillant naturel categories attract younger demographics through natural wine positioning. Urban retail in Lisbon, Copenhagen, and Berlin drives trial velocity.
Industry Challenges
- Viticulture labor scarcity:Seasonal harvest workforce availability contracts across Italy and Spain. Mechanization investment faces terrain limitations in steep-slope appellations like Douro and Mosel.
- Legacy distributor dependence:Established wholesale relationships block direct channel development. Breaking these ties risks temporary volume loss during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Wine Market |
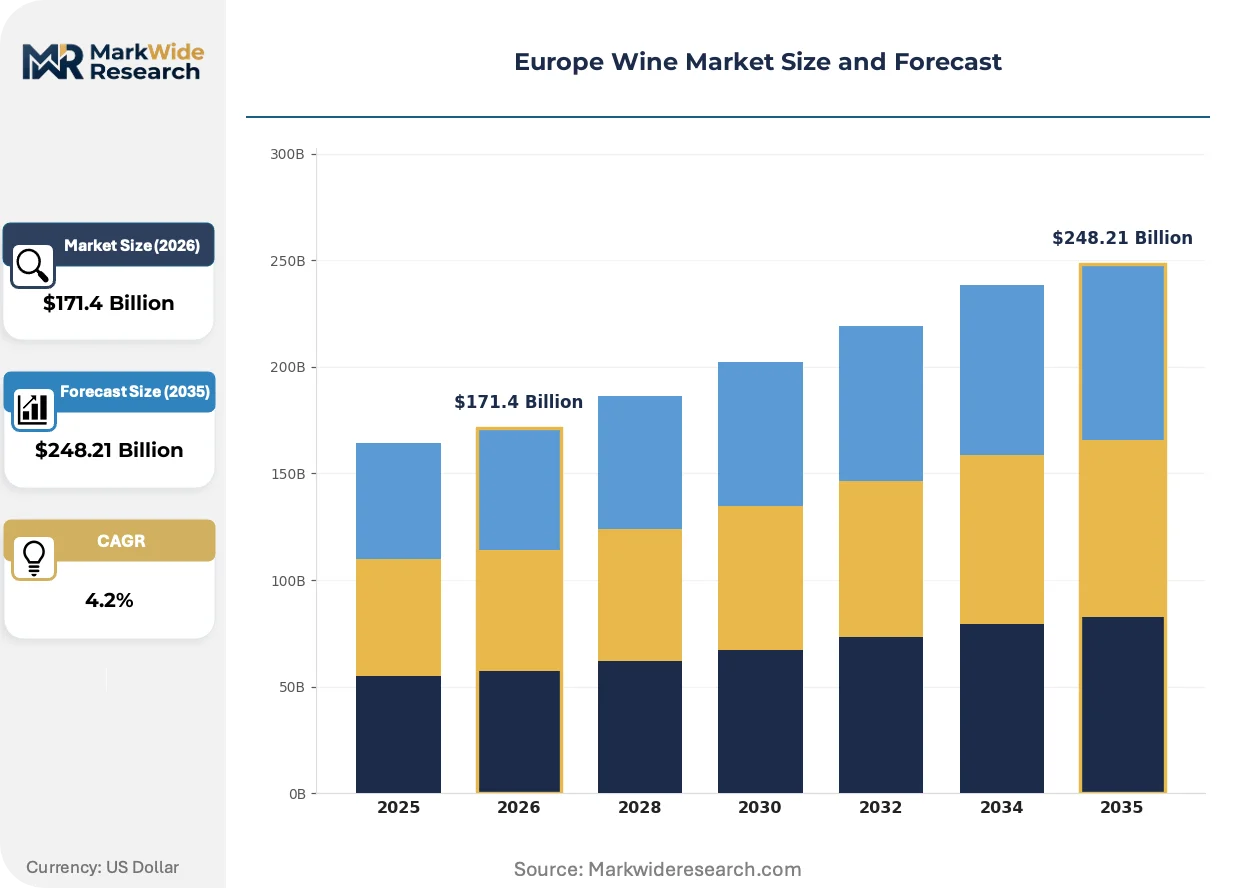
| Market Size in 2026 | $171.4 Billion |
| Market Size in 2035 | $248.21 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Wine, White Wine, Rosé Wine, Sparkling Wine Distribution Channel: Supermarkets, Wine Shops, Online Retail, Restaurants Wine Origin: French, Italian, Spanish, German Price Range: Premium, Mid-Range, Economical, Luxury |
| Companies Covered | Pernod Ricard, Moët Hennessy, Constellation Brands, Castel Group, Treasury Wine Estates, E. & J. Gallo Winery, Caviro, Freixenet, Torres, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Wine Market Shifts & Advancements
Precision viticulture tools and alternative packaging formats are compressing traditional production timelines while regulatory pressure on vineyard chemistry intensifies compliance costs.
Sensor-based canopy management systems are displacing manual vineyard monitoring protocols. Large estates in Bordeaux and Rioja deploy drone-mounted multispectral imaging to optimize irrigation timing. This technology is displacing experiential vineyard manager judgment with data-driven intervention schedules.
REACH and ECHA scrutiny of pesticide residues tighten maximum allowable limits for copper and sulfur formulations. French INAO inspectors now require documented alternative-treatment attempts before conventional chemical approval. Organic-certified producers in Languedoc-Roussillon accelerate biological control agent adoption to preempt regulatory exclusion.
Restaurant wine programs now unbundle glassware service from bottle procurement, with hospitality groups self-managing inventory through direct-import arrangements. Independent sommeliers in Paris and Milan bypass traditional distributor relationships. This pattern concentrates most visibly in Michelin-tier establishments seeking exclusive cuvée access.
Europe Wine Market Segmentation
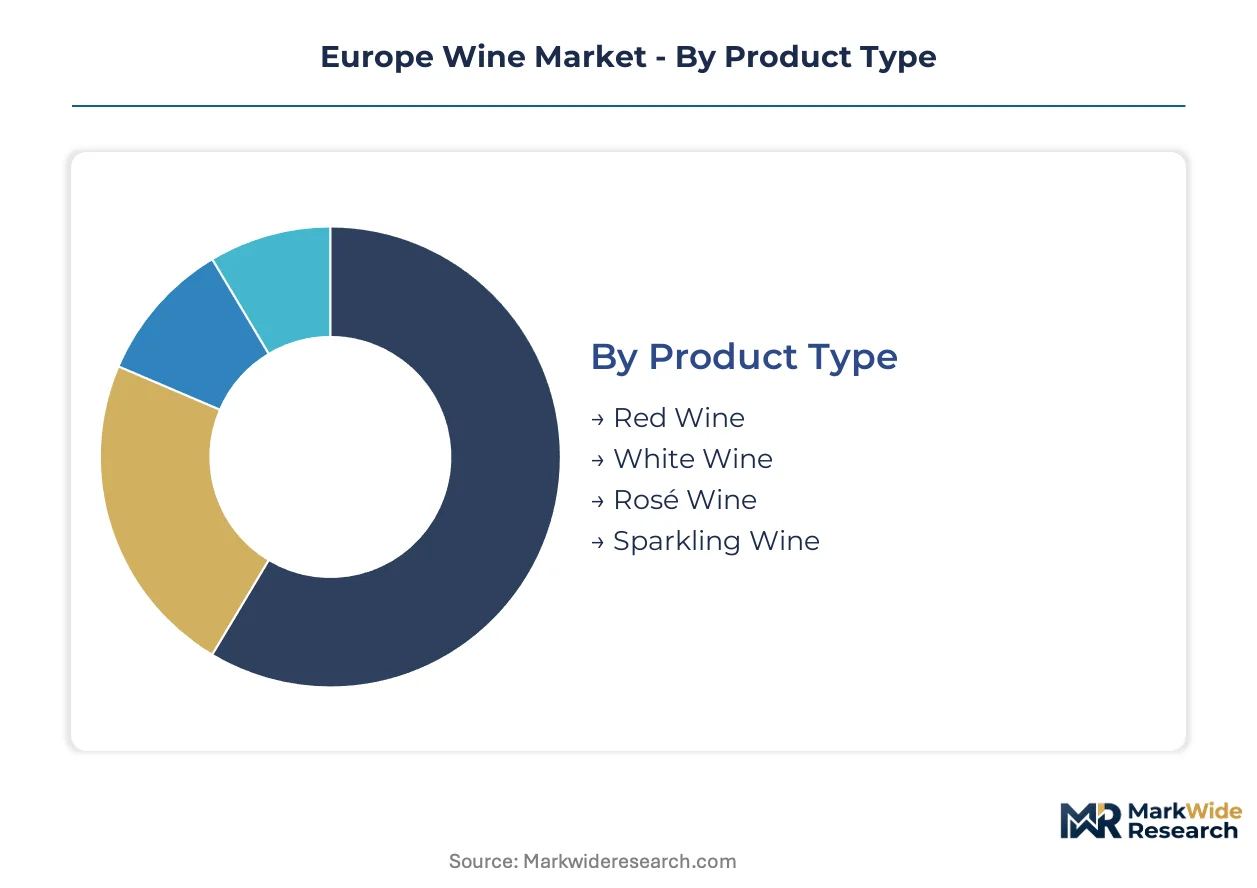
Segmentation in European wine reveals how regulatory frameworks, channel economics, and terroir hierarchies partition value capture. Distinct buyer behaviors across hospitality, retail, and direct channels force producers to configure separate margin architectures for each pathway.
Product Type:
Channel allocation varies sharply: supermarkets move red and white in volume, restaurants anchor sparkling programs, while online retail accelerates trial of low-intervention formats.
- Red Wine:Fermented with extended skin contact producing tannins and anthocyanin concentration. Italian Sangiovese and Spanish Tempranillo dominate supermarket shelves in Germany and the UK, though heat-stressed southern French vintages compress supply reliability.
- Sparkling Wine:Secondary fermentation creates dissolved CO2 through traditional method or Charmat process. Prosecco DOCG from Conegliano-Valdobbiadene and Franciacorta from Lombardy capture restaurant by-the-glass investment across France and Spain.
- White Wine:Pressed juice fermented without skin contact, ranging from light-bodied Riesling to oaked Chardonnay. German Mosel and French Chablis supply concentrate through specialist wine shops.
- Rosé Wine:Limited skin contact achieves pink coloration; Provence AOC sets quality benchmarks. Côtes de Provence shipments spike through summer retail promotions in northern European markets.
By volume, Red Wine leads. By growth pace, Sparkling Wine is expanding most quickly.
Distribution Channel:
Margin retention inversely correlates with channel control: direct estate shipping preserves the most value, while supermarket listing fees erode profitability at scale.
- Supermarkets:High-volume, low-margin throughput with concentrated buyer power. Carrefour and Tesco wine buyers negotiate exclusive label programs that displace branded estate bottling in France and the UK.
- Restaurants:On-premise service with markup multiples supporting sommelier-curated lists. Paris and Milan Michelin-tier establishments now self-import to bypass distributor tiers.
- Online Retail:Direct-to-consumer platforms and estate web shops. Regulatory clearance for cross-border shipping within the EU unlocks margin previously captured by wholesale intermediaries.
- Wine Shops:Specialist curation with educated staff driving premium conversion. Independent merchants in Copenhagen and Berlin accelerate natural wine category development.
Supermarkets dominate volume throughput. Online Retail gains share fastest as member-state shipping barriers dissolve.
Wine Origin:
PDO and PGI density correlates with pricing power: appellations with stricter yield limits and longer aging mandates command sustained premiums.
- French:INAO-governed appellation system with hierarchical cru classifications. Bordeaux and Burgundy estates leverage AOC status to maintain price architecture in export markets.
- Italian:MIPAAF oversight with DOCG, DOC, and IGT tiering. Prosecco and Franciacorta sectors attract hospitality investment; Barolo and Brunello anchor investment-grade cellaring.
- Spanish:ICEX promotion of DOCa Rioja and Priorat alongside emerging regions. Tempranillo-based reds dominate volume export to Germany and the UK.
- German:Prädikat system linking ripeness levels to quality designations. Mosel and Rheingau Riesling concentrate through specialist retail channels with lower supermarket penetration.
France leads by export value. Italy climbs fastest through sparkling wine volume expansion.
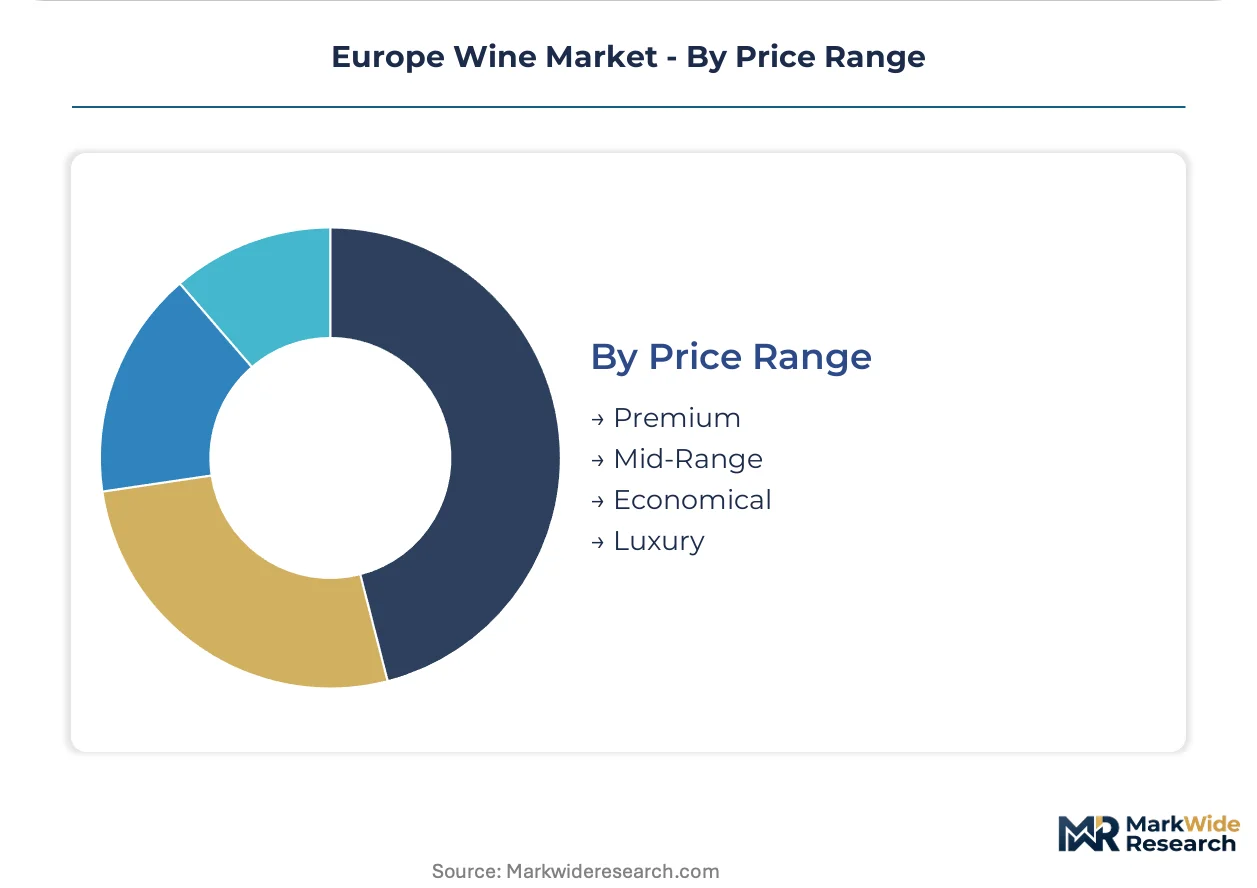
Price Range:
Cost tier alignment determines channel access: luxury and premium segments face supermarket delisting pressure, while economical tiers confront glass and cork input inflation.
- Premium:Estate-bottled wines with appellation certification and vintage declaration. French AOC and Italian DOCG producers in this band bypass wholesale through direct restaurant relationships.
- Luxury:Limited-production cuvées with provenance documentation and auction market liquidity. Champagne houses and classified Bordeaux growths sustain pricing through allocation scarcity.
- Mid-Range:Branded regional wines with consistent vintage blending. Castel Group and similar operators anchor volume supply through diversified Languedoc-Roussillon sourcing.
- Economical:Bulk-shipped wine with in-market bottling and private-label programs. Retailer-exclusive labels dominate this tier, compressing margins for contract producers.
Mid-Range captures greatest volume. Premium achieves steepest expansion trajectory as organic conversion unlocks green procurement channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-border adjustments and Farm to Fork Strategy subsidies are redirecting vineyard investment toward certified organic conversion and proximity-based supply chains across member states.
France
Champagne and Bordeaux appellations sustain export pricing power through INAO-enforced yield limits. The country's national wine regulator tightens documentation requirements for AOC status renewal. Languedoc-Roussillon cooperatives expand organic hectarage to capture green procurement premiums from German retail buyers.
Italy
Prosecco DOCG and Franciacorta sectors attract restaurant by-the-glass investment across France and Spain. MIPAAF oversight accelerates DOC-to-DOCG upgrades in Lombardy and Veneto. Conegliano-Valdobbiadene producers consolidate pressing capacity to meet hospitality demand spikes.
Spain
Tempranillo-based Rioja exports dominate volume shipments to Germany and the United Kingdom. ICEX promotion budgets shift toward emerging Priorat and Rías Baixas positioning. Catalan cava houses face margin pressure from Prosecco price competition in Northern European supermarkets.
Germany
Mosel and Rheingau Riesling producers concentrate distribution through specialist retail channels with limited supermarket penetration. The country's federal agriculture ministry expands organic conversion subsidies for steep-slope vineyards. Berlin urban retail accelerates natural wine category development through independent merchant curation.
Europe Wine Market Competitive Landscape
Player mix skews toward heritage appellation houses and diversified volume suppliers with co-operative processing networks. Market structure concentrates around tiered positioning: luxury Champagne and classified growth estates anchor pricing architecture, mid-scale branded operators secure retail shelf space, and co-operative federations aggregate sub-scale estate output. Dominant competitive moves include estate acquisition in emerging Eastern European terroirs and direct-to-consumer channel development bypassing wholesale markups.
Within the heritage house tier, Moët Hennessy and Pernod Ricard exemplify appellation-controlled pricing power through Champagne AOC dominance and duty-free channel leverage. Torres occupies a position bridging organic estate differentiation with scale sufficient for export market presence. Castel Group anchors the volume-supplier archetype through diversified sourcing across French regional appellations and private-label contract execution.
| Leading Market Players |
|---|
| Pernod Ricard |
| Moët Hennessy |
| Constellation Brands |
| Castel Group |
| Treasury Wine Estates |
| E. & J. Gallo Winery |
| Caviro |
| Freixenet |
| Torres |
| Others |
Supply & Pricing Matrix
Glass and cork capacity concentration in Portugal and Spain creates scale economies that simultaneously depress input costs for volume producers and erect barriers for estates seeking alternative packaging formats. This concentration compresses margins across the economical tier while reinforcing PDO-certified pricing power for heritage houses.
Pricing Analysis
Certification level under EU Regulation 1308/2013 creates the primary spread between luxury Champagne AOC estates and bulk-shipped private-label operators. Three-tier pricing structure across premium, standard, and economy levels stratifies by appellation density and organic conversion status. Cost compression in the economical tier intensifies because supermarket buyer power extracts listing fee concessions. Price-sensitive volume retailers in Germany and the United Kingdom drive hardest bargaining, while Michelin-tier restaurants in Paris and Milan exhibit lowest sensitivity.
Supply Chain Analysis
Inventory lead times for oak barrel aging extend eighteen to thirty-six months for classified Bordeaux growths, constraining supply responsiveness to demand spikes. Vineyard supply concentrates in France, Italy, and Spain, with secondary fermentation capacity clustering in Conegliano-Valdobbiadene for Prosecco and Reims for Champagne. Raw material dependencies center on French oak staves, Portuguese natural cork, and Italian glass. Single-source vulnerability runs through cork supply given Mediterranean forest disease pressure. Distribution runs through co-operative federations for volume tiers and direct estate shipping for premium positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe wine sits in early-cycle expansion as organic conversion subsidies under the EU Farm to Fork Strategy accelerate certified hectarage and unlock green procurement channels previously closed to conventional producers.
For Market Incumbents: Shield appellation-controlled pricing power by accelerating DOC-to-DOCG upgrades in Italian holdings and securing exclusive cuvée allocations for Michelin-tier restaurant direct-import arrangements. Vertical integration into Eastern European vineyard land in Romania builds supply optionality against climate yield compression in southern French growing regions. Certification investment in biodynamic conversion captures German and Austrian buyer preference shifts without full Demeter compliance burden. For New Entrants and Emerging Players: Lead with low-intervention wine formats targeting urban natural wine retail in Berlin, Copenhagen, and Lisbon where independent merchant curation accelerates trial velocity. Underpenetrated Romanian and Bulgarian terroirs offer lowest land-cost entry points with co-operative processing partnerships mitigating capital requirements. Go-to-market execution through direct-to-consumer estate shipping bypasses legacy distributor relationships that block channel development for established competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors estates with precision viticulture deployment and cross-border direct shipping regulatory clearance already secured. Long-term viability over the next decade hinges on water access permits and organic certification trajectory rather than brand heritage alone. Acquisition targets should demonstrate documented alternative-treatment protocols satisfying ECHA copper and sulfur scrutiny. The signal to watch is German retail buyer procurement policy shifts toward mandatory organic tiering.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Vineyard Conversion | Unlocks green procurement channels under EU Farm to Fork Strategy subsidies. |
| Direct-to-Consumer Shipping Expansion | Bypasses wholesale markups through regulatory clearance for cross-border estate sales. |
| Precision Viticulture Deployment | Displaces manual monitoring with drone-mounted multispectral imaging in Bordeaux and Rioja. |
| Eastern European Vineyard Acquisition | Builds supply optionality in Romanian and Bulgarian terroirs with lower land costs. |
| Biodynamic Certification Convergence | Captures premium pricing from German buyers without full Demeter conversion burden. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vineyard estate managers, co-operative federation directors, INAO and MIPAAF regulatory inspectors, supermarket category buyers at Carrefour and Tesco, and independent sommeliers in Paris and Milan. Secondary validation drew from EU Regulation 1308/2013 documentation, ECHA pesticide residue databases, customs export records, and organic certification registries. Bottom-up hectarage and yield estimates triangulated against top-down export value flows.
Across the analysis window, forecasts model product type segmentation by red, white, sparkling, and rosé; distribution channel splits across supermarkets, restaurants, online retail, and wine shops; wine origin tiering by French, Italian, Spanish, and German appellations; and price range stratification. CAGRs derive from vintage volume trajectories, hospitality investment patterns, and direct shipping regulatory diffusion curves. Climate yield compression scenarios and carbon-border adjustment cost pass-throughs inform sensitivity bounds.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal subsidy continuity or accelerated ECHA residue limit tightening would require recalibration. Forecasts reflect assumptions on organic conversion adoption curves and cross-border shipping regulatory harmonization. Specific risks include drought protocol water access permit revocation, glass and cork input cost volatility, and distributor relationship disruption during channel transition periods. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
South Africa Beverages Market
Alcoholic Beverages
Beer Adjuncts Market
Alcoholic Beverages
Global Food-Grade Alcohol Market
Alcoholic Beverages
Beer Keg System Market
Alcoholic Beverages
France Tequila Market
Alcoholic Beverages
Global Liquor Confectionery Market
Alcoholic Beverages
West Africa Alcoholic Beverages Market
Alcoholic Beverages
Alcoholic Tea Market
Alcoholic Beverages
Beer Mug Market
Alcoholic Beverages
Beer Brewing Machine Market
Alcoholic Beverages
Industrial Alcohol Market
Alcoholic Beverages
South Africa Tequila Market
Alcoholic Beverages
Herbal Distillates Market
Alcoholic Beverages
Middle East and Africa Fermented Drinks Market
Alcoholic Beverages
United States Spirits Market
Alcoholic Beverages
Wine Production Machinery Market