
 Global Butyric Acid Derivatives Market | 2026-2036
Global Butyric Acid Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butyric Acid Derivatives Market Foresight
Subscription-based technical advisory for feed formulation is hardening into a core revenue layer alongside commodity chemical sales. Perstorp Holding AB leverages its integrated esterification platform to sustain margin capture across sodium butyrate and butyrate esters. Nutreco N.V. anchors its position through captive demand from its animal nutrition division, while Kemin Industries Inc. differentiates via microencapsulation technology that controls release kinetics in ruminant and monogastric systems.
Butyric acid derivatives comprise organic compounds functionalized from butanoic acid through esterification, polymerization, or salt formation, typically yielding sodium butyrate with purity grades exceeding 98 percent for pharmaceutical and feed applications. These compounds primarily serve as gut health modulators, flavor precursors, and polymer plasticizers across industrial value chains. Sodium butyrate and butyrate esters command the deepest margin pools due to their validated efficacy in intestinal epithelial integrity for livestock, while butyrylated polymers remain nascent with growth tethered to biodegradable packaging mandates in the European Union. Animal feed additives as an application segment leads in volume throughput, whereas pharmaceutical-grade derivatives concentrate value due to CDMO qualification barriers and pharmacopeial compliance requirements.
The European Food Safety Authority and REACH frameworks govern additive approvals and chemical registration, respectively, with EFSA's re-evaluation of butyric acid as a feed additive reshaping product authorization pathways for non-EU suppliers. China's Ministry of Agriculture and Rural Affairs and the US FDA Center for Veterinary Medicine enforce divergent residue and efficacy standards that fragment market access protocols. Stakeholders must monitor regulatory divergence on novel delivery formats such as protected butyrates and their classification under evolving feed hygiene regulations.
Market Dynamics
The EU Green Deal's binding sustainability targets are compressing demand for petroleum-derived butyric acid while bio-fermentation capacity struggles to scale, creating a supply-demand asymmetry that favors integrated producers with captive carbohydrate feedstocks.
Growth Catalysts
- EFSA Re-evaluation Pathway:The European Food Safety Authority's streamlined approval for novel butyrate delivery formats is accelerating market access for protected sodium butyrate in poultry nutrition.
- Antibiotic Growth Promoter Phase-Out:Livestock producers across the EU and China are substituting AGPs with gut health modulators, concentrating procurement on validated butyrate derivatives.
- Microencapsulation Scale-Up:Advances in lipid-coating technologies are extending butyrate release kinetics through the ruminant fore-stomach, unlocking dairy and beef applications previously dominated by ionophores.
Market Restraints
- Feedstock Volatility:Corn and sugarcane molasses price swings directly compress fermentation economics for bio-based butyric acid producers in Brazil and India.
- REACH Registration Burden:Non-EU suppliers face escalating compliance costs for butyrylated polymer intermediates under ECHA's updated substance evaluation protocols.
- Chemical Synthesis Dominance:Petrochemical butyric acid maintains cost parity below $1,800 per metric ton, constraining bio-fermentation penetration in industrial plasticizer markets.
Strategic Opportunities
- India Poultry Integration:Contract farming consolidation in Telangana and Karnataka is creating direct-to-producer channels bypassing traditional distributor markups on feed additives.
- EU Packaging Mandates:The Single-Use Plastics Directive is generating pull for butyrylated starch blends in food-contact applications, a segment with limited incumbent supply.
- Precision Nutrition Convergence:Real-time rumen monitoring sensors paired with targeted butyrate supplementation protocols are enabling outcome-based pricing models in North American dairy operations.
Industry Challenges
- Pharmacopeial Qualification Timelines:USP and EP certification for pharmaceutical-grade sodium butyrate requires 18-24 month stability studies, freezing working capital for CDMO entrants.
- Cross-Contamination Protocols:Feed-grade and food-grade butyric acid derivatives demand segregated production lines, complicating capacity allocation for multi-product chemical processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butyric Acid Derivatives Market |
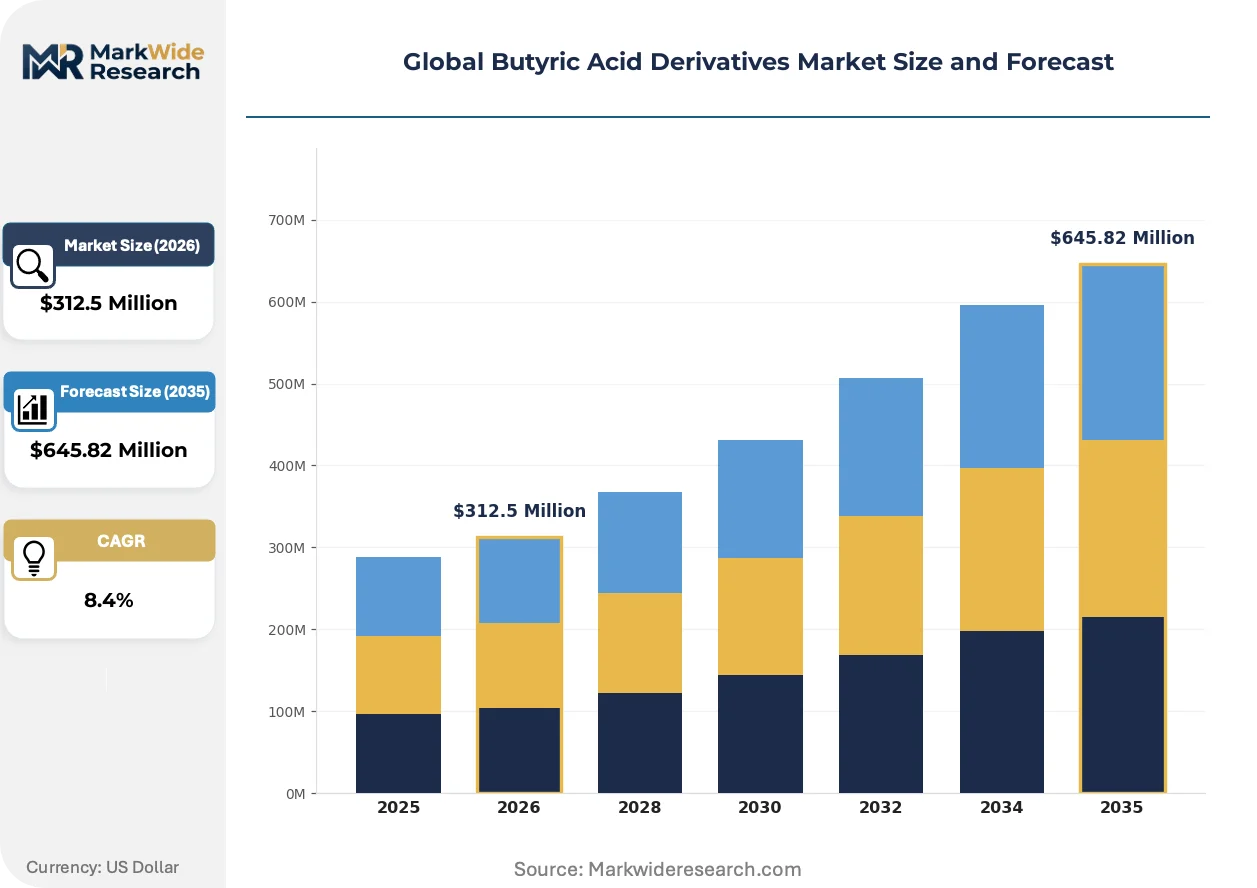
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyrate Esters, Butyrylated Polymers, Butyryl Chloride, Butyric Anhydride, Sodium Butyrate Application: Food Preservatives, Animal Feed Additives, Pharmaceuticals, Flavoring Agents, Polymer Additives End Use Industry: Agrochemicals, Pharmaceutical Manufacturing, Food Processing, Cosmetic Formulation, Packaging Materials Packaging Type: Drums, Bulk Containers, Bottles, Carboys, Intermediate Bulk Containers |
| Companies Covered | Kemin Industries Inc., Nutreco N.V., Perstorp Holding AB, Palital GmbH & Co. KG, Koninklijke DSM N.V., Innovad, Bioscreen Technologies S.R.L, Global Nutrition International, Zhejiang Yaofi Bio-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butyric Acid Derivatives Market Shifts & Advancements
Delivery technology maturation and regulatory preference for bio-based chemistries are bifurcating the competitive landscape between commodity ester producers and precision-formulation specialists.
Microencapsulated butyrate matrices with pH-responsive release triggers are rewriting intestinal targeting economics for monogastric species. Swine integrators in Denmark and the Netherlands are adopting these formats at 40% premium pricing over standard sodium butyrate. The technology is compressing dosage requirements by 60% while extending efficacy claims through the finisher phase, reshaping feed additive procurement specifications.
REACH's 2024 update to polymer registration requirements is forcing butyrylated plasticizer suppliers to submit extended toxicity dossiers for substances above 100 tons annually. Industrial compounders in Germany and Belgium are consolidating supplier lists to pre-registered sources, disqualifying smaller Chinese exporters. The regulation is accelerating backward integration among European packaging converters seeking supply security.
Subscription-based technical advisory is displacing transactional chemical sales in ruminant nutrition. Dutch and Irish dairy cooperatives now contract for formulation optimization services bundled with butyrate product supply, unbundling the traditional distributor role. This model concentrates buyer power with integrators managing 10,000+ head operations while fragmenting access for independent producers below 500 head.
Global Butyric Acid Derivatives Market Segmentation
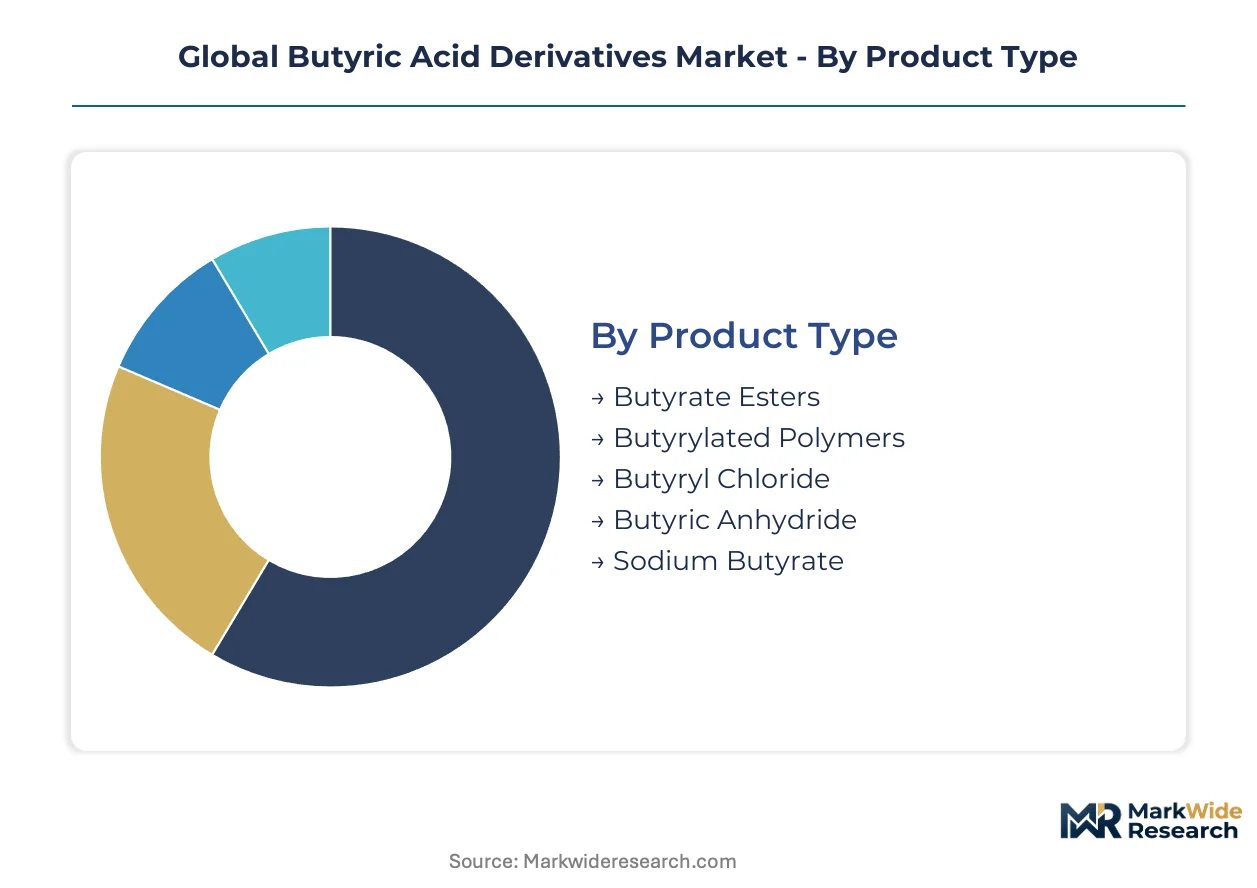
Butyric acid derivatives fragment across five distinct product chemistries, each commanding divergent margin structures and regulatory pathways. Volume throughput concentrates in commodity salts and esters, while specialty polymers and anhydrides capture premium pricing through technical qualification barriers.
Product Type:
Sodium butyrate dominates volume throughput, yet butyrate esters command the widest margin expansion as microencapsulation technologies mature.
- Sodium Butyrate:Crystalline salt form exceeding 98% purity for pharmaceutical and feed-grade specifications. Procurement from poultry integrators in China and India is accelerating as antibiotic growth promoter bans harden, with EFSA's streamlined approval pathway reducing market access friction for protected formats.
- Butyrate Esters:Esterified derivatives including tributyrin and glycerol butyrate with controlled-release kinetics for ruminant applications. Dairy cooperatives in the Netherlands and Ireland are adopting these formats at substantial premiums over standard salts, compressing dosage requirements while extending efficacy claims through the finisher phase.
- Butyrylated Polymers:Starch and cellulose derivatives functionalized for biodegradable packaging applications. EU Single-Use Plastics Directive mandates are generating pull for food-contact grades, though supply remains concentrated among pre-registered REACH-compliant European compounders.
- Butyryl Chloride:Highly reactive acyl chloride intermediate for pharmaceutical synthesis and agrochemical active ingredient production. Demand concentrates with CDMOs requiring pharmacopeial-grade starting materials.
- Butyric Anhydride:Dehydrated dimer form serving as acylating agent in flavor precursor and polymer modifier synthesis. Agrochemical formulators in India represent the primary offtake channel.
Mature deployment sits with sodium butyrate in standard feed applications. Newer deployment is concentrated in butyrate esters with precision delivery architectures.
Application:
Feed additive procurement is displacing flavor and polymer markets as the primary revenue engine, with gut health modulation claims hardening into specification requirements.
- Animal Feed Additives:Gut health modulators replacing antibiotic growth promoters across EU and Chinese livestock operations. Swine and poultry integrators in Denmark, the Netherlands, and China's Shandong province are specifying microencapsulated formats with pH-responsive release triggers.
- Pharmaceuticals:HDAC inhibitor applications in oncology and metabolic disease therapeutics, plus excipient-grade sodium butyrate for enteric coating formulations. USP and EP certification requirements freeze working capital for 18-24 months.
- Food Preservatives:Natural antimicrobial for processed meat and dairy applications, with FSSAI and FDA diverging on maximum permitted concentrations.
- Flavoring Agents:Buttery note precursors in confectionery and savory formulations, facing substitution pressure from synthetic alternatives in cost-sensitive markets.
- Polymer Additives:Plasticizers and compatibilizers for biodegradable packaging, with REACH 2024 updates forcing extended toxicity dossiers above 100 tons annually.
Established uptake clusters in flavoring applications. Steepest expansion trajectory is emerging in pharmaceutical-grade derivatives as CDMO qualification barriers concentrate supply among pre-certified producers.
End Use Industry:
Customer concentration diverges between fragmented food processors and consolidated pharmaceutical manufacturers, with feed compounders occupying an intermediate consolidation tier.
- Pharmaceutical Manufacturing:CDMOs and generic API producers requiring pharmacopeial-grade starting materials with full supply chain documentation. EMA and FDA divergence on impurity profiles complicates multi-territory filings.
- Food Processing:Meat and dairy processors seeking clean-label preservation solutions. FSSAI's evolving standards for natural additives in India are reshaping import specifications.
- Packaging Materials:European converters integrating butyrylated starch into food-contact films under EU Green Deal biodegradability mandates. REACH pre-registration is disqualifying smaller Chinese exporters.
- Agrochemicals:Formulators of crop protection actives using butyryl chloride and anhydride as acylating intermediates. Telangana and Karnataka contract farming consolidation is creating direct-to-producer channels.
- Cosmetic Formulation:Skin barrier repair claims in premium dermatological products, with EU Cosmetics Regulation restricting certain butyrate concentrations.
Volume concentration rests with food processing. Value capture is migrating toward pharmaceutical manufacturing as CDMO qualification timelines extend.
Packaging Type:
Logistics economics favor bulk formats for integrated producers, while specialty distributors retain drum and bottle channels for small-batch pharmaceutical and cosmetic customers.
- Bulk Containers:Tank trucks and rail cars for sodium butyrate and butyrate esters moving direct to feed compounders. Integrated producers with captive carbohydrate feedstocks in Brazil and India leverage this format for cost parity.
- Intermediate Bulk Containers:1,000-liter totes for mid-volume pharmaceutical and food processors requiring batch traceability without full tankage investment.
- Drums:200-liter steel and HDPE containers for agrochemical and flavoring agent distributors. REACH registration documentation must accompany each shipment into the EU.
- Carboys:Glass and fluoropolymer-lined vessels for high-purity butyryl chloride and anhydride requiring moisture exclusion.
- Bottles:Laboratory and pilot-scale quantities for R&D procurement in pharmaceutical and cosmetic formulation development.
Scale deployment favors bulk containers. Precision deployment requiring segregation protocols concentrates in carboys and bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and India dominate fermentation capacity for bio-based butyric acid, while China and the EU absorb the bulk of derivative consumption for feed and pharmaceutical applications. This geographic split between production and offtake is hardening supply chain dependencies.
China
Poultry integrators in Shandong province are specifying microencapsulated sodium butyrate at 40% premiums over standard salts. The Ministry of Agriculture and Rural Affairs enforces divergent residue standards that fragment import protocols for non-domestic suppliers. Feed compounders in Guangdong are consolidating procurement through direct contracts with Indian fermentation producers.
India
Contract farming consolidation in Telangana and Karnataka is creating direct-to-producer channels that bypass traditional distributor markups on feed additives. FSSAI's evolving standards for natural preservatives are reshaping import specifications for food-grade derivatives. Fermentation facilities in Gujarat leverage captive molasses feedstocks to sustain cost parity with petrochemical routes.
Germany
REACH 2024 updates on polymer registration are forcing butyrylated plasticizer suppliers to submit extended toxicity dossiers above 100 tons annually. Industrial compounders in North Rhine-Westphalia are consolidating supplier lists to pre-registered sources. The EU Green Deal's binding sustainability targets are compressing demand for petroleum-derived intermediates.
Netherlands
Dairy cooperatives in Friesland and Gelderland are adopting subscription-based technical advisory bundled with butyrate product supply. EFSA's streamlined approval pathway for protected sodium butyrate is accelerating market access for novel delivery formats. Unbundling the traditional distributor role is concentrating buyer power with integrators managing 10,000+ head operations.
United States
Precision nutrition convergence is pairing real-time rumen monitoring sensors with targeted butyrate supplementation protocols in Wisconsin and California dairy operations. The FDA Center for Veterinary Medicine enforces efficacy standards that diverge from EU benchmarks. CDMOs in the Boston-Cambridge corridor require 18-24 month pharmacopeial qualification timelines for pharmaceutical-grade sodium butyrate.
Global Butyric Acid Derivatives Market Competitive Landscape
Capital-heavy producers with captive fermentation capacity compete with asset-light formulation specialists who outsource intermediate production. The market structure concentrates around integrated chemical groups and animal nutrition conglomerates with backward control over carbohydrate feedstocks. Three archetypes dominate: fermentation-scale producers with upstream agricultural assets, precision-delivery technology licensors, and pharmaceutical-grade CDMOs with pharmacopeial certifications. Competitive moves center on microencapsulation patent licensing and direct-to-producer channel development bypassing traditional distribution.
Within the integrated chemical group tier, Perstorp Holding AB exemplifies the fermentation-scale archetype with upstream platform integration. Nutreco N.V. occupies a position bridging captive demand from animal nutrition divisions with external formulation services. Kemin Industries Inc. represents the precision-delivery technology tier, anchoring competitive differentiation through controlled-release architectures for ruminant and monogastric systems.
| Leading Market Players |
|---|
| Kemin Industries Inc. |
| Nutreco N.V. |
| Perstorp Holding AB |
| Palital GmbH & Co. KG |
| Koninklijke DSM N.V. |
| Innovad |
| Bioscreen Technologies S.R.L |
| Global Nutrition International |
| Zhejiang Yaofi Bio-Tech |
| Others |
Supply & Pricing Matrix
The EU Green Deal's binding sustainability targets gate both qualified supply and premium-tier pricing access, compressing demand for petroleum-derived butyric acid while bio-fermentation capacity struggles to scale. This regulatory asymmetry rewards integrated producers with captive carbohydrate feedstocks and REACH pre-registration status, while fragmenting procurement options for buyers seeking food-contact compliant grades.
Pricing Analysis
Margin tightening in pharmaceutical-grade sodium butyrate reflects pharmacopeial qualification barriers and extended stability study timelines. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated butyrate esters from standard sodium salts and unprotected commodity grades. Cost-down pressure on feed-grade derivatives accelerates because petrochemical butyric acid maintains cost parity below bio-fermentation routes. Poultry integrators in China and India demonstrate highest price sensitivity, while dairy cooperatives in the Netherlands and Ireland absorb substantial premiums for precision-delivery formats.
Supply Chain Analysis
Freight cost differentials between bulk tankage and drum shipments are reshaping channel economics for mid-volume pharmaceutical and food processors. Supply concentrates in Brazil, India, and China, with fermentation facilities in Gujarat and São Paulo drawing from captive molasses and corn starch feedstocks. Raw material dependencies on corn, sugarcane molasses, and petroleum-derived butanoic acid expose producers to commodity price volatility. Single-source vulnerability sits with REACH-registered European compounders for butyrylated polymer intermediates. Distribution runs through direct-to-producer contracts bypassing traditional distributor markups in Telangana and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH 2024 updates and pharmacopeial qualification timelines force sub-scale producers to exit. Regulatory compliance burdens are accelerating competitive separation between integrated fermentation operators and asset-light formulation specialists.
For Market Incumbents: Anchor market position through backward integration into captive carbohydrate feedstocks in Brazil and India, securing cost parity with petrochemical routes. Defend against emerging microencapsulation technology licensors by patenting pH-responsive release architectures for ruminant applications. Prioritize REACH pre-registration status for butyrylated polymer intermediates above 100 tons annually to disqualify smaller Chinese exporters from European packaging converter supply lists.
For New Entrants and Emerging Players: Precision-delivery technology licensing offers the most penetrable wedge, with microencapsulated butyrate matrices commanding 40% premiums over standard salts in Denmark and Netherlands swine operations. Target contract farming consolidation in India's Telangana and Karnataka for direct-to-producer channels bypassing traditional distributor markups. Pursue subscription-based technical advisory bundled with product supply to unbundle the distributor role and concentrate buyer relationships with 10,000+ head integrators.
For Investors and Strategic Acquirers: EFSA's streamlined approval pathway for protected sodium butyrate is the leading indicator that regulatory preference is hardening for novel delivery formats over commodity grades. Long-term viability favors integrated producers with fermentation scale and upstream agricultural assets over asset-light compounders. Watch for pharmacopeial qualification timeline extensions as the signal that CDMO certification barriers are concentrating supply among pre-certified producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Feedstocks | Fermentation facilities in Gujarat and São Paulo secure molasses supply against price volatility. |
| Microencapsulation Patent Licensing | pH-responsive release architectures unlock dairy applications previously dominated by ionophores. |
| REACH Pre-Registration Compliance | Extended toxicity dossiers above 100 tons annually disqualify smaller Chinese polymer exporters. |
| Direct-to-Producer Channel Development | Contract farming consolidation in Telangana and Karnataka bypasses traditional distributor markups. |
| Subscription-Based Technical Advisory | Dutch and Irish dairy cooperatives bundle formulation optimization with butyrate product supply. |
Research Methodology
Multi-period observation of antibiotic growth promoter phase-out trajectories, microencapsulation patent filings, and REACH registration timelines anchored the trend analysis, supplemented by interviews with fermentation plant managers, procurement leads at poultry integrators, distribution channel partners, and technical R&D directors at animal nutrition conglomerates. Secondary validation drew from EFSA additive re-evaluation dossiers, ECHA substance registration databases, customs and trade flow data, and SEC filings of listed chemical groups. Bottom-up volume modeling across product chemistries and applications triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed value and volume across sodium butyrate, butyrate esters, butyrylated polymers, butyryl chloride, and butyric anhydride chemistries, further disaggregated by animal feed additives, pharmaceuticals, food preservatives, flavoring agents, and polymer additives. End-use industry splits across pharmaceutical manufacturing, food processing, packaging materials, agrochemicals, and cosmetic formulation refined the demand architecture. CAGRs were derived from elasticity-adjusted consumption trajectories across the analysis window, incorporating feedstock cost scenarios, regulatory approval pathway timelines, and delivery technology adoption curves.
Several conditions sit outside the modeled scope, including abrupt shifts in corn and sugarcane molasses commodity prices, unilateral regulatory reversals on antibiotic growth promoter bans, and breakthrough synthetic biology routes to bio-based butyric acid. Forecasts reflect assumptions about sustained EFSA and REACH framework stability, continued EU Green Deal implementation, and gradual precision nutrition sensor adoption in North American dairy operations. Stakeholders should weight assumptions against their own operating context and monitor feedstock volatility, regulatory divergence, and technology substitution risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Biosaccharide Gum Market
Additives
Inorganic Rheology Modifiers Market
Additives
Citric Acid Market
Additives
Global UV Absorbers Market
Additives
Chelating Agents Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Oilfield Drilling Fluid Additive Market
Additives
Anti-Creasing Agent Market
Additives
Propyl Gallate Market
Additives
Sorbitan Oleate Market
Additives
Global Silica-Based Matting Agents Market
Additives
Glycol Acetate Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Anti Crystallizing Agents Market
Additives
Hexyl Acetate Market
Additives
Ammonium Acetate Market