
 Bromine Derivatives Market | 2026-2036
Bromine Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Bromine Derivatives Market Intelligence
The European Union's REACH regulation, with its stringent chemical registration and evaluation requirements, is expanding the compliance burden for new market entrants. LANXESS AG leverages its extensive regulatory expertise to navigate these complex frameworks across multiple jurisdictions. Albemarle Corporation sustains its market position through large-scale production facilities located near key bromine sources. Israel Chemicals Limited dominates specific high-purity segments through proprietary extraction and purification technologies.
Bromine derivatives are chemical compounds in which one or more hydrogen atoms are replaced by a bromine atom, created through direct bromination processes. These substances serve as highly effective reaction intermediates, flame retardants, and biocides in various industrial applications. Flame retardant applications for electronics manufacturing constitute the largest and most valuable use case for these derivatives. In contrast, the use of specific derivatives like bromomethane as drilling fluids in the oilfield services industry represents a more mature and volume-driven segment.
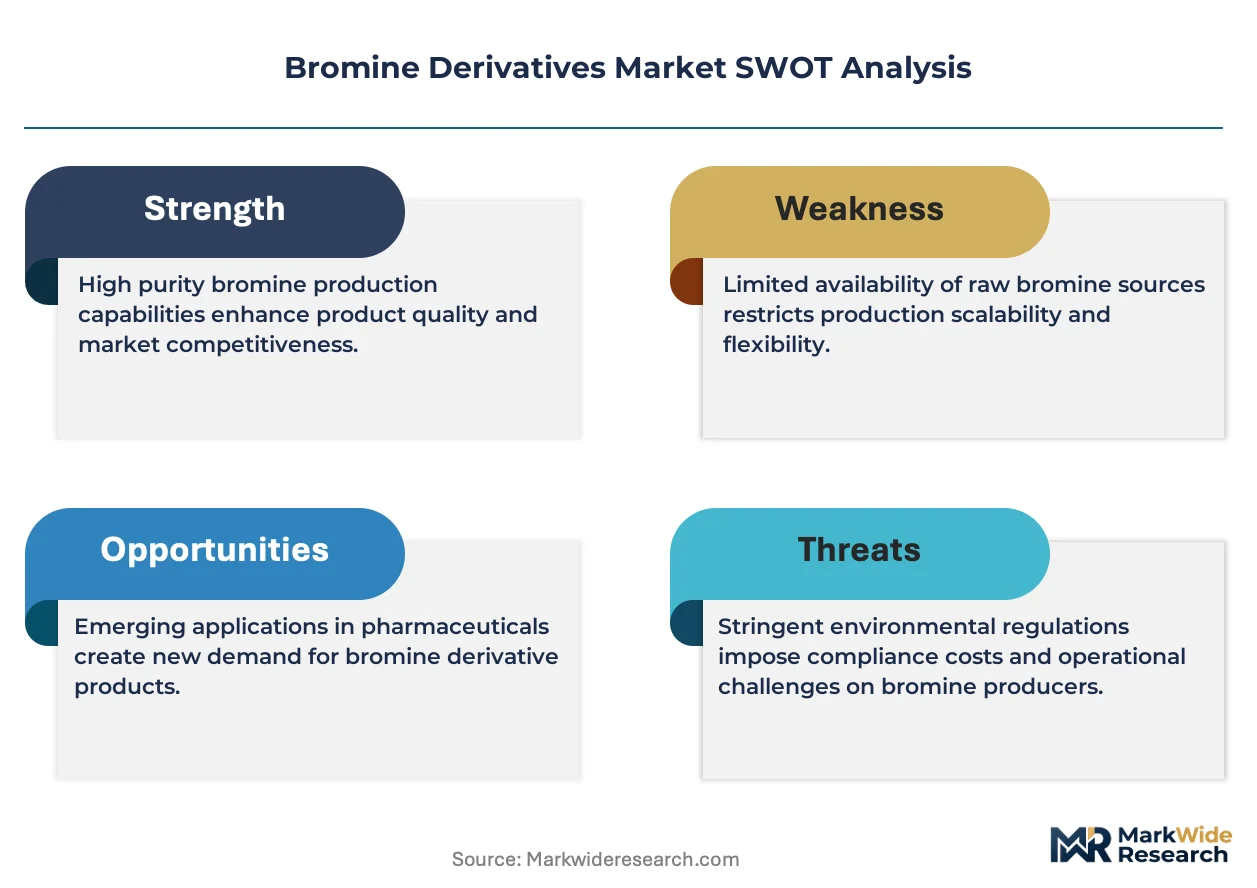
Regulatory oversight from bodies like the US EPA, the EU's ECHA under REACH, and China's MEE dictates market access and product viability. These agencies' classifications of specific brominated compounds as persistent organic pollutants directly influence which derivatives can be commercialized. Consequently, producers must align their product development pipelines with evolving environmental health and safety standards. The strategic challenge for suppliers is balancing investment in next-generation, compliant derivatives against the long lifecycle of established applications.
Market Dynamics
The market's central dynamic is the tension between stringent environmental health regulations, such as the EU's RoHS directive, and the indispensable performance of bromine derivatives as flame retardants in the global electronics supply chain centered in Asia.
Growth Catalysts
- Electronics Sector Demand:The requirement for effective flame retardants in printed circuit boards, connectors, and casings for consumer electronics and data center hardware provides a consistent volume driver.
- Regulatory Compliance Shifts:The ongoing phase-out of legacy compounds under frameworks like the Stockholm Convention on POPs creates demand for next-generation, compliant brominated alternatives.
- Production Infrastructure in China:The country's extensive and integrated chemical processing capabilities support large-scale, cost-effective production, anchoring the global supply chain for many essential bromine derivatives.
Market Restraints
- Substitution from Non-Halogenated Materials:The development of phosphorus-based and mineral-based flame retardants presents a viable substitution threat in specific applications where performance requirements are less stringent.
- Intensifying Regulatory Scrutiny:The classification of additional brominated substances as chemicals of concern by agencies like the US EPA and ECHA can lead to abrupt market restrictions and product obsolescence.
- Geographic Concentration of Resources:The world's primary bromine sources are concentrated in a few locations, including the Dead Sea and brine wells in Arkansas, creating potential supply chain vulnerabilities.
Strategic Opportunities
- Energy Storage Systems:The use of bromine in electrolytes for large-scale redox flow batteries represents a significant opportunity, aligning with the expansion of grid-scale renewable energy storage.
- Water Treatment and Biocides:Development of advanced bromine-based biocides for industrial water treatment systems, cooling towers, and pulp mills offers a pathway for diversification beyond flame retardants.
- Circular Economy Integration:Establishing efficient processes for recovering bromine from electronic waste (e-waste) can create a new, sustainable raw material source and address environmental concerns.
Industry Challenges
- Extensive Compliance Timelines:Navigating the complex registration, evaluation, and authorization process under the EU's REACH regulation requires significant investment in toxicological data and years of administrative effort.
- High Capital Investment:The corrosive nature of elemental bromine and hydrobromic acid necessitates the use of expensive, specialized alloys and glass-lined reactors, increasing the capital cost of new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bromine Derivatives Market |
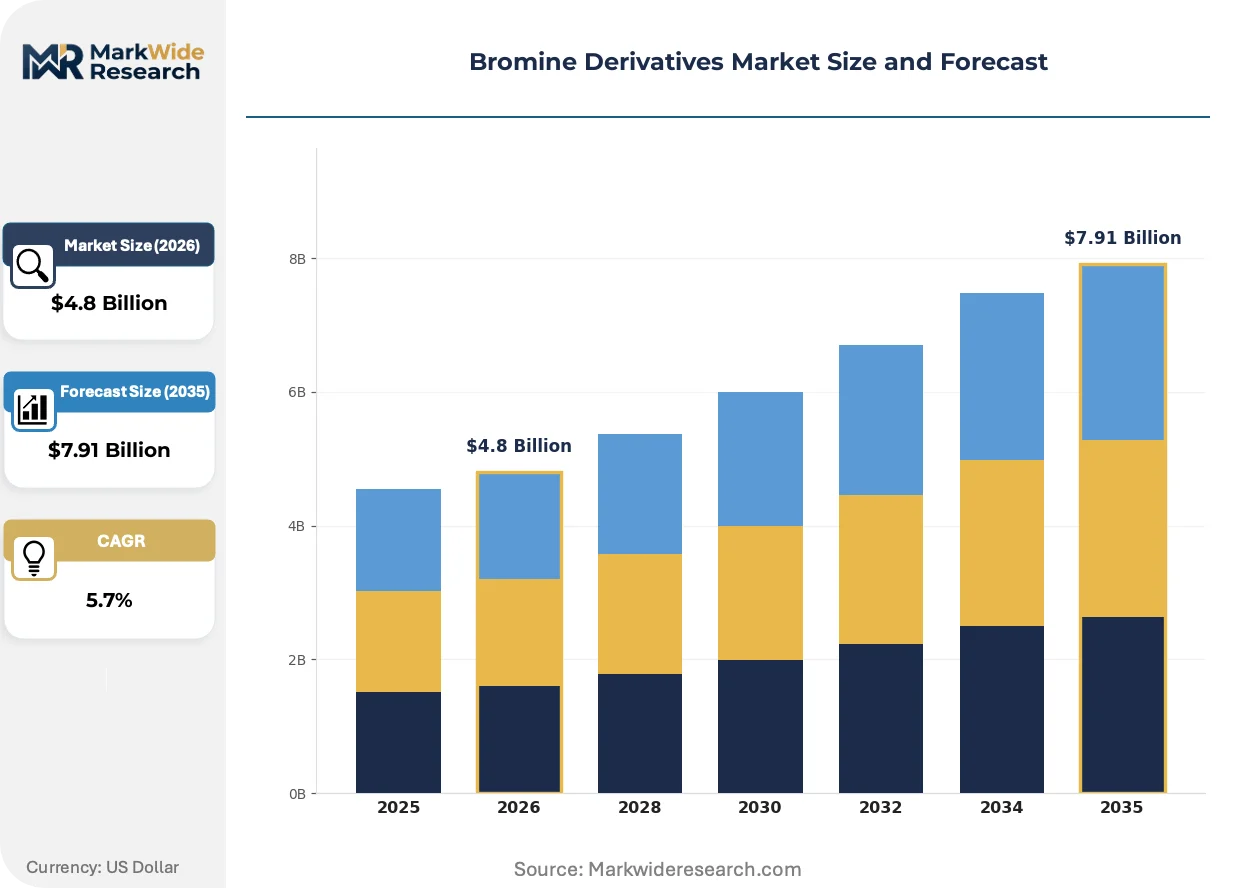
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bromoaziridine, Bromomethane, Bromophenol, Dibromomethane, Bromobenzene Application: Flame Retardants, Drilling Fluids, Water Treatment, Pesticides, Photography Chemicals End Use Industry: Electronics Manufacturing, Oilfield Services, Agriculture, Wastewater Management, Chemical Processing Packaging Type: Drums, Bulk Tanks, Intermediate Bulk Containers, Cylinders, Pails |
| Companies Covered | Jordan Bromine Company, Tosoh Corporation, Albemarle Corporation, Tata Chemicals Ltd., Honeywell International Inc., Israel Chemicals Limited, Gulf Resources Inc., Neogen Chemicals Limited, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bromine Derivatives Market Strategic Shifts & Innovations
The market is advancing through the development of specialized, higher-molecular-weight compounds designed to meet strict environmental standards without compromising fire safety performance. This evolution reflects a broader industry pivot from commodity chemicals toward application-specific, high-performance solutions.
Polymeric brominated flame retardants (Poly-FRs) offer a solution to legacy environmental concerns due to their large molecular size, which limits bioavailability. Electronics manufacturers are increasingly specifying these materials for components in servers, 5G infrastructure, and automotive electronics. The adoption of Poly-FRs is consolidating the flame retardant portfolio around a smaller set of high-performance, compliant materials.
The EU's Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH) regulation continues to set a global benchmark for chemical safety management. Its rigorous data requirements for substance registration forces producers to invest heavily in toxicological and environmental impact studies. The electronics and automotive sectors are most affected, as they must ensure every component in their complex supply chains is fully compliant.
A notable behavioral shift is the move toward specification-driven procurement in high-value segments, replacing traditional bulk purchasing. End-users in the pharmaceutical and semiconductor sectors now demand specific purity levels, particle sizes, and impurity profiles, often certified to exacting standards. This trend is most visible in North American and European markets where product traceability and quality assurance are paramount.
Bromine Derivatives Market Segmentation
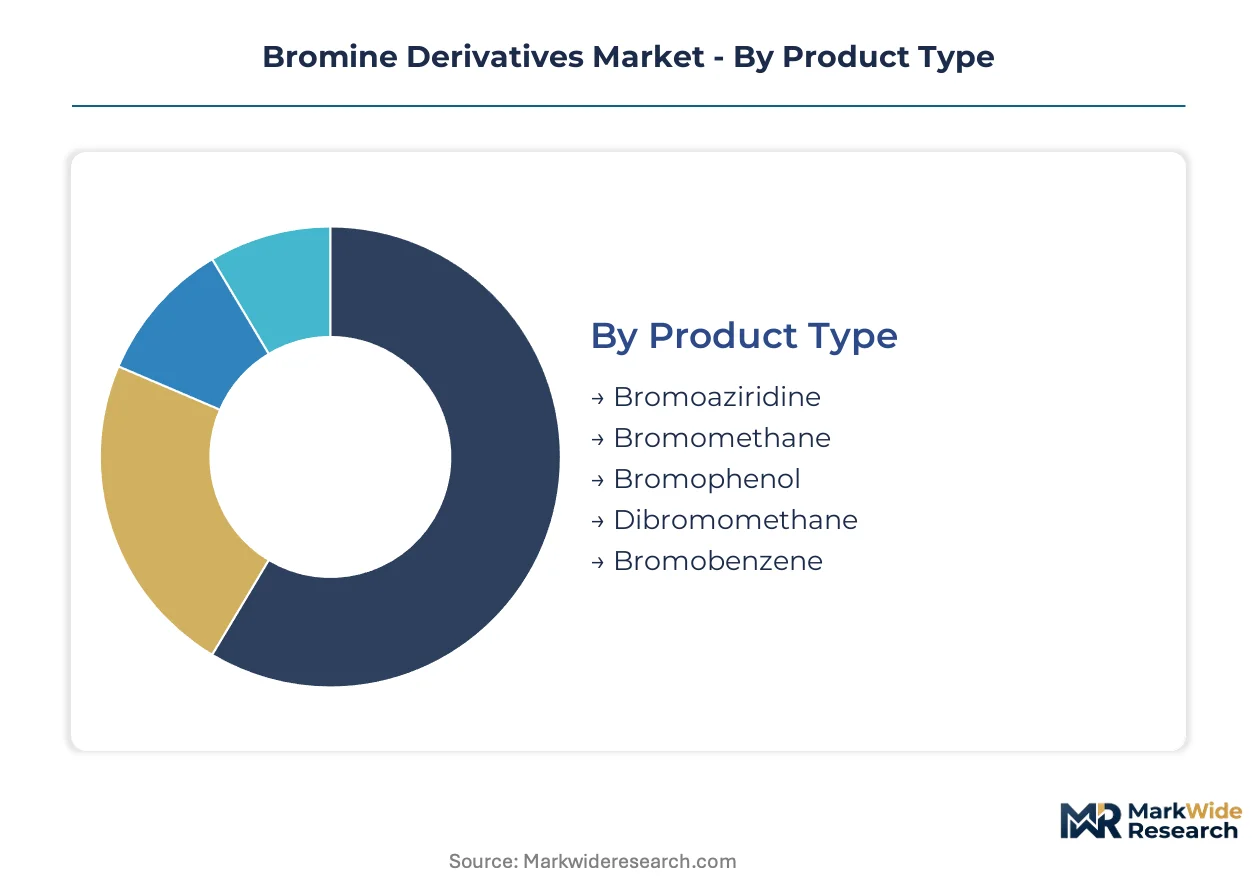
The Bromine Derivatives Market exhibits diverse segments, reflecting varied functional requirements and industrial applications. Understanding these distinctions helps stakeholders identify specific growth vectors and navigate regulatory complexities. Product characteristics, application performance, and end-use industry demands shape market dynamics and procurement patterns.
Product Type:
Buyer decisions for bromine derivative product types often hinge on specific chemical properties required for downstream synthesis or application performance. Purity, reactivity, and regulatory compliance are critical factors influencing selection.
- Bromoaziridine:This highly reactive cyclic amine serves as a crucial intermediate in advanced organic synthesis, particularly for pharmaceuticals and specialized polymers. Demand concentrates in high-value chemical processing sectors requiring precise molecular structures for novel compounds.
- Bromophenol:As a halogenated aromatic compound, bromophenol is a key precursor for various flame retardants, dyes, and pharmaceutical intermediates. Its versatility drives consistent demand from manufacturers developing next-generation compliant materials for electronics.
- Bromomethane:This alkyl halide functions primarily as a fumigant and a solvent, seeing use in mature agricultural and industrial cleaning processes.
- Dibromomethane:A dense, non-flammable solvent, dibromomethane finds application in niche laboratory settings and as a heavy liquid for mineral separation.
- Bromobenzene:This aryl halide is utilized as a solvent, an intermediate in Grignard reagents, and a precursor in the synthesis of other organic compounds.
Volume sits with Bromomethane due to its established use in agriculture; growth tilts toward Bromophenol for its role in next-generation flame retardants.
Application:
Application performance requirements dictate the selection of specific bromine derivatives, with fire safety and environmental compatibility being paramount in many industrial uses.
- Flame Retardants:These compounds are incorporated into materials to suppress or delay the spread of fire, primarily in electronic components, textiles, and building insulation. The electronics sector in Asia drives substantial demand for compliant, high-performance flame retardant solutions.
- Water Treatment:Bromine-based biocides effectively disinfect industrial water systems, cooling towers, and swimming pools by controlling microbial growth. Growing regulatory emphasis on water quality management across Europe supports the expansion of this application.
- Drilling Fluids:Brominated compounds serve as high-density brines in oil and gas exploration, providing wellbore stability and pressure control.
- Pesticides:Certain bromine derivatives are active ingredients in agricultural chemicals, protecting crops from pests and diseases.
- Photography Chemicals:Bromine compounds like silver bromide are essential for traditional photographic film and paper emulsions.
The segment for Flame Retardants continues its expansion, while Water Treatment demonstrates robust potential.
End Use Industry:
Customer type and their specific operational needs significantly influence the demand profile for bromine derivatives across various industrial sectors.
- Electronics Manufacturing:This industry integrates bromine derivatives into printed circuit boards, casings, and connectors to meet stringent fire safety standards for consumer devices and data center infrastructure. Global supply chains centered in China consistently drive demand for these essential components.
- Wastewater Management:Bromine compounds are employed for disinfection and biofouling control in municipal and industrial wastewater treatment facilities. Increasing global water scarcity and stricter discharge regulations propel demand in this sector.
- Oilfield Services:This sector utilizes bromine derivatives primarily as high-density drilling and completion fluids in oil and gas extraction operations.
- Agriculture:Bromine compounds find application in agricultural settings as fumigants and intermediates for crop protection agents.
- Chemical Processing:Various chemical manufacturers use bromine derivatives as essential reagents and intermediates for synthesizing diverse specialty chemicals.
Electronics Manufacturing represents the largest end-use, with Wastewater Management poised for significant growth.
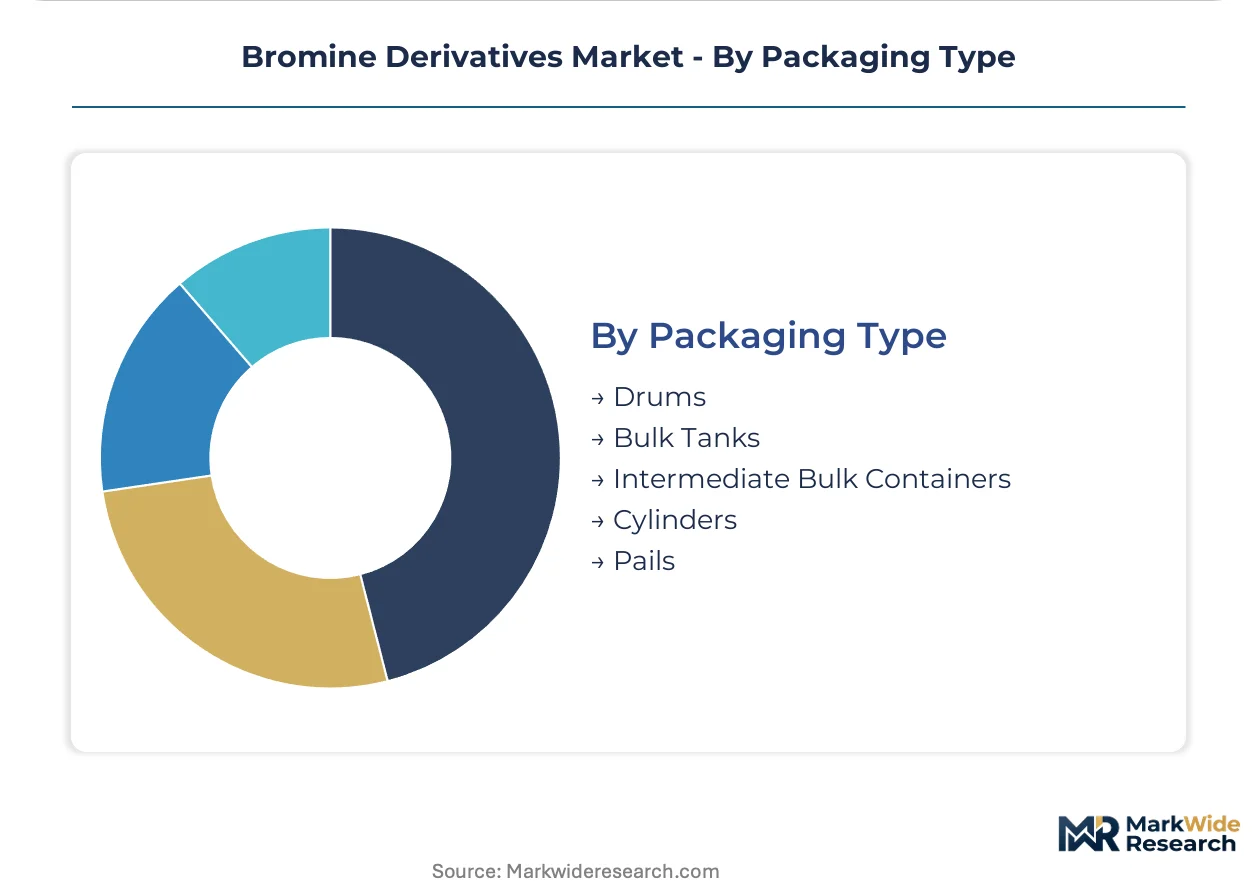
Packaging Type:
Volume requirements and safety protocols for transportation and storage determine the predominant packaging types used for bromine derivatives.
- Bulk Tanks:These large-capacity containers are utilized for transporting and storing significant volumes of liquid bromine derivatives, serving high-volume industrial consumers. Logistics for bulk tanks are optimized for cost efficiency in long-haul distribution.
- Intermediate Bulk Containers:IBCs offer a versatile solution for quantities larger than drums but smaller than bulk tanks, facilitating efficient handling and storage for mid-sized industrial users. These are frequently used for specialty chemical deliveries.
- Drums:Standard drums provide a common packaging solution for smaller industrial quantities, ensuring safe handling and transport of various bromine compounds.
- Cylinders:High-pressure cylinders are typically used for gaseous or highly volatile bromine derivatives, ensuring contained and safe delivery.
- Pails:Smallest in volume, pails are suitable for laboratory-scale quantities or highly specialized, low-volume applications of bromine derivatives.
Bulk tanks cater to large-scale industrial requirements, whereas intermediate bulk containers offer flexible distribution solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for bromine derivatives exhibits significant demand-side concentration in regions with robust electronics manufacturing and chemical processing. Asia, particularly China, drives substantial volume due to its extensive production infrastructure and consumer electronics industry. Regulatory frameworks globally also influence regional market dynamics and product adoption.
China
Electronics manufacturing in China generates substantial demand for compliant flame retardants in printed circuit boards. The Ministry of Ecology and Environment (MEE) dictates environmental standards for chemical production and use within the country. Industrial hubs like the Yangtze River Delta concentrate chemical processing and electronics assembly, supporting large-scale derivative consumption.
United States
The US market sees demand from oilfield services for drilling fluids and electronics for flame retardants. The Environmental Protection Agency (EPA) regulates the use and classification of brominated compounds, influencing product viability. Brine wells in Arkansas provide a primary source of raw bromine, supporting regional production capabilities.
Germany
Germany's advanced manufacturing sector, including automotive and electronics, requires high-performance bromine derivatives. The European Chemicals Agency (ECHA) implements REACH regulations, setting stringent safety standards for chemical substances. Chemical parks along the Rhine, such as Ludwigshafen, house significant chemical processing operations and research facilities.
Israel
Israel's market position is anchored by its access to the Dead Sea, a major global bromine source. The country's environmental regulations govern the extraction and processing of these natural resources. Specialized chemical firms in the Negev Desert region focus on high-purity bromine derivatives and proprietary extraction technologies.
India
India's expanding electronics assembly and chemical industries drive demand for various bromine derivatives. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for industrial chemicals and manufactured goods. Manufacturing clusters in states like Maharashtra and Gujarat are expanding chemical production and consumption capabilities.
Bromine Derivatives Market Key Industry Players
Chinese producers anchor one tier, leveraging extensive chemical processing infrastructure for large-scale commodity derivative production. European and North American specialists hold another, focusing on high-purity, application-specific compounds with strong regulatory expertise. The market encompasses large, vertically integrated chemical conglomerates and niche players specializing in specific derivative types. Companies pursue strategic partnerships to navigate complex regulatory landscapes and invest in next-generation compliant materials.
Large-scale integrated producers, such as Albemarle Corporation, sustain their market position through significant production facilities located near key bromine sources. Israel Chemicals Limited, an Israel-based entity, exemplifies specialization in high-purity segments, leveraging proprietary extraction and purification technologies. European chemical manufacturers like LANXESS AG occupy a strategic tier, emphasizing extensive regulatory expertise to navigate complex compliance frameworks across multiple jurisdictions for their diverse product portfolios.
| Leading Market Players |
|---|
| Jordan Bromine Company |
| Tosoh Corporation |
| Albemarle Corporation |
| Tata Chemicals Ltd. |
| Honeywell International Inc. |
| Israel Chemicals Limited |
| Gulf Resources Inc. |
| Neogen Chemicals Limited |
| LANXESS AG |
| Others |
Cost & Logistics Intelligence
The development of polymeric brominated flame retardants, shifting from legacy compounds, simultaneously reshapes cost economics through specialized synthesis and concentrates supply in regions with advanced chemical processing capabilities.
Pricing Analysis
Volume-driven commodity segments contrast sharply with high-purity, application-specific derivatives in pricing models. Contract-based long-term offtake agreements dominate for commodity bromomethane, while value-based pricing applies to specialized bromophenols. Purity levels and regulatory compliance certifications, such as those under EU REACH, drive price differentiation. Cost compression in commodity derivatives stems from intense competition among Chinese producers. Electronics manufacturers purchasing compliant flame retardants are less price-sensitive than agricultural users of fumigants.
Supply Chain Analysis
Reverse-logistics initiatives for recovering bromine from electronic waste are emerging, influencing future raw material flows. China and Israel dominate the supply of raw bromine and its derivatives due to extensive processing infrastructure and natural resources. The Dead Sea and Arkansas brine wells are primary sources for elemental bromine, creating raw material dependencies. Geographic concentration creates potential single-source vulnerability and logistics chokepoints. Large-scale bulk tanks and intermediate bulk containers characterize downstream delivery to industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bromine derivatives market is entering a technology-transition phase, with advanced polymeric flame retardants displacing older, less compliant compounds.
For Market Incumbents: Lock in long-term supply agreements with electronics manufacturers to secure consistent demand for compliant flame retardants. Establish partnerships with e-waste recyclers to develop circular economy bromine recovery processes, defending against regulatory shifts making legacy compounds obsolete. Invest in advanced R&D for next-generation, high-purity derivatives to meet evolving environmental health and safety standards.
For New Entrants and Emerging Players: Begin with niche applications in energy storage systems, leveraging bromine's role in redox flow batteries. Target the water treatment sector in Europe where regulatory emphasis on water quality management is growing. Develop specialized bromine-based biocides for industrial cooling towers. A go-to-market angle involves offering performance-based solutions certified to EU ECHA standards.
For Investors and Strategic Acquirers: Exit pathways concentrate in vertically integrated mid-cap specialists possessing proprietary extraction and purification technologies. Long-term viability for the bromine derivatives market hinges on sustained demand from electronics and the emerging energy storage sector. Acquisition targets include firms with strong intellectual property in compliant flame retardants or advanced biocide formulations. Watch for increased M&A activity among Chinese producers as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Bolsters supply security for critical flame retardants to electronics manufacturing hubs in China. |
| Green Manufacturing Transition | Reduces environmental footprint and enhances market access under stringent EU REACH regulations. |
| Joint Venture | Accelerates development of bromine-based electrolytes for grid-scale energy storage systems. |
| Long-term Supply Agreement | Stabilizes demand and pricing for high-volume derivatives with key electronics sector clients. |
| R&D for Next-Gen Materials | Addresses evolving regulatory requirements for compliant and sustainable flame retardant solutions. |
Research Approach
Multi-period observation of regulatory shifts, technology adoption rates, and production capacities anchored the trend analysis, supplemented by interviews with industry experts. This approach combined primary insights from chemical R&D directors, procurement leads at electronics OEMs, and environmental compliance officers with secondary validation. Secondary sources included EU ECHA reports, US EPA filings, customs data, and corporate financial disclosures. Bottom-up market sizing complemented top-down validation for robust data triangulation.
Segment-weighting across product types, applications, end-use industries, and packaging formats informed the quantitative modeling over the projection horizon. The analytical framework integrated historical consumption patterns with anticipated demand from emerging applications like energy storage. Compound annual growth rates were derived from a synthesis of supply-side capacity additions and demand-side end-user projections. Key forecast inputs included global electronics production volumes and water treatment infrastructure investments.
Underlying measurement precision varies by segment; flame retardants for electronics carry tighter precision than agricultural fumigants. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements. Geopolitical events impacting raw material supply chains present a specific risk factor. Practitioners should monitor new POPs classifications by agencies like the US EPA for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Ascorbyl Stearate Market
Additives
Combustion Clean-Up Additives for High-Mileage Fleets Market
Additives
Polyoxyethylene Sorbitan Monostearate Market
Additives
China Feed Additives Market
Additives
Anti-Foaming Agent Market
Additives
Marine Fuel Additives Market
Additives
Ethoxyquin Market
Additives
Europe Fuel Additives Market
Additives
Tragacanth Market
Additives
Carboxymethyl Cellulose Market
Additives
Global Slip Additives Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Plasticizer Alcohols Market
Additives
Liquid Thickeners Market
Additives
Polyethylene Terephthalate Additives Market
Additives
Global UV Stabilizers Market