
 Battery-Operated Knapsack Sprayer Market | 2026-2036
Battery-Operated Knapsack Sprayer Market Size, Share, and Industry Trends Forecast 2026-2036
Battery-Operated Knapsack Sprayer Market Insights
Subscription-based maintenance and battery-replacement programs is pivoting vendor economics from one-time hardware sales toward recurring revenue streams. Deere & Company leverages its dealer infrastructure to bundle sprayer sales with seasonal servicing contracts across North American farm belts. STIHL anchors its position through dense rental-shop networks that place battery sprayers within reach of occasional-use customers. Chapin International specializes in diaphragm-pump architectures that extend runtime per charge, competing on durability metrics against lower-cost Asian imports.
A battery-operated knapsack sprayer integrates an electric diaphragm or centrifugal pump, rechargeable lithium-ion or lead-acid battery pack, and adjustable nozzle wand into a wearable tank assembly, typically rated for 2-8 hours of continuous spray operation at 2-6 bar pressure. The system replaces manual lever-pumping with consistent motorized flow, reducing operator fatigue and improving chemical deposition uniformity across row crops, orchards, and turf applications. Backpack sprayers dominate unit volume due to ergonomic load distribution and tank capacity flexibility, while lithium-ion battery configurations command margin premiums over legacy lead-acid alternatives as energy density improves and cycle-life costs decline. Smart control technology represents the fastest-expanding technology tier, integrating pressure sensors and flow meters that enable variable-rate application and usage logging for compliance documentation.
EPA emissions standards and OSHA agricultural chemical exposure limits are tightening certification requirements for spray equipment sold into US commercial markets, pushing manufacturers toward sealed-system designs and precision-delivery validation. India's BIS safety markings and CEA battery-disposal rules add compliance layers for import and domestic assembly operations targeting South Asian distribution. The EU F-Gas Regulation and REACH chemical restrictions indirectly favor battery-electric platforms by raising regulatory friction for engine-driven alternatives that require fuel handling and exhaust management. Stakeholders must monitor how regional battery-recycling mandates and emerging carbon-accounting frameworks for farm inputs reshape total-cost-of-ownership calculations and procurement criteria across distributor and institutional buyer channels.
Market Dynamics
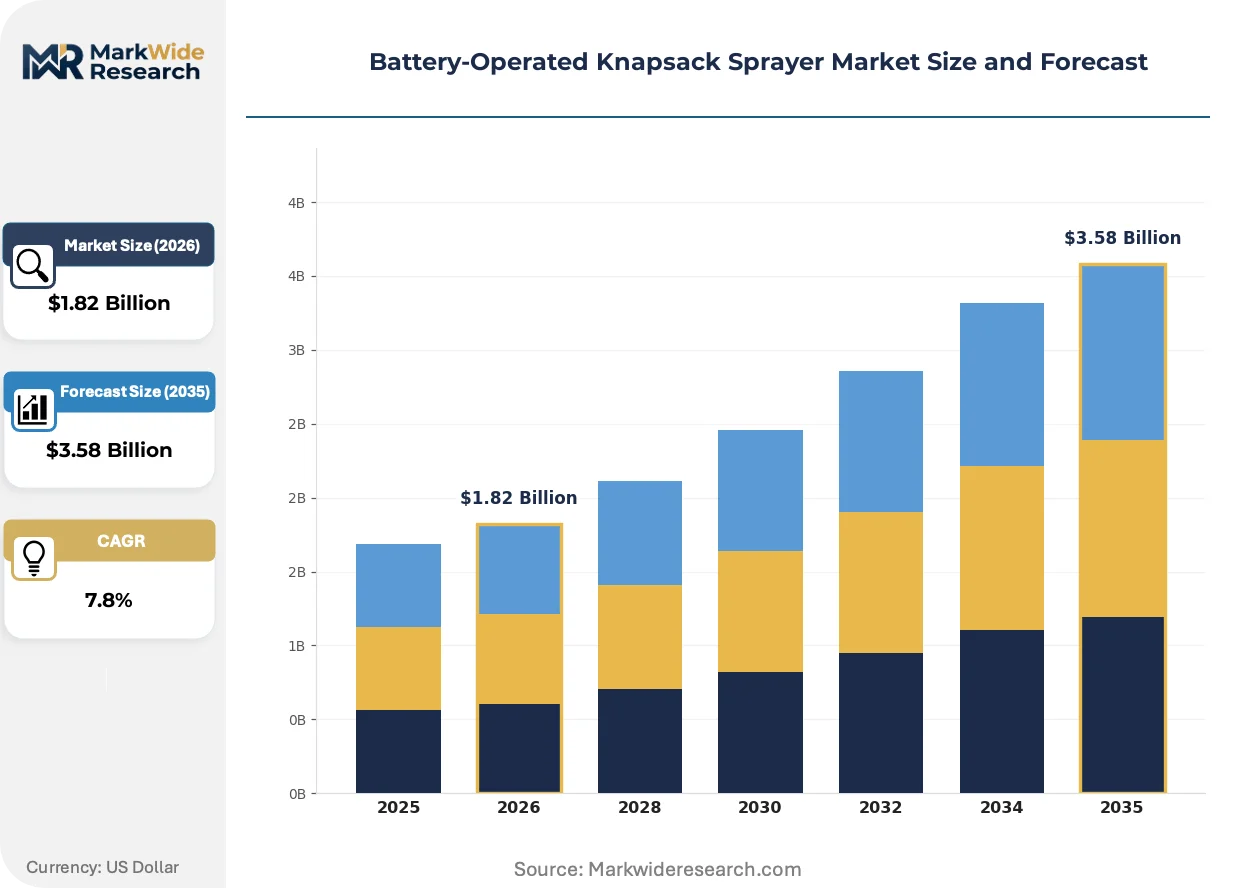
India's PLI scheme for agricultural mechanization and tightening EPA emissions rules on gasoline-powered equipment are accelerating the shift from engine-driven to electric sprayer platforms, compressing the payback period for smallholder farmers upgrading from manual pumps.
Growth Catalysts
- PLI scheme subsidies:India's Production-Linked Incentive scheme for farm mechanization reduces capital outlay for cooperative procurement programs in Maharashtra and Gujarat states.
- Diaphragm-pump runtime extension:Advanced pump architectures now deliver 6-8 hours of continuous operation per charge, matching full workday requirements for orchard and row-crop applications.
- OSHA exposure limits:Tighter agricultural chemical handling standards in US commercial markets mandate sealed-system designs that battery-electric platforms satisfy more readily than legacy manual equipment.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production concentrates among East Asian cell manufacturers, exposing assemblers to raw material volatility and freight cost swings.
- Lead-acid legacy installed base:Lower first-cost lead-acid configurations retain share in price-sensitive segments, slowing margin capture from premium lithium-ion upgrades.
- CEA battery-disposal compliance:India's Central Electricity Authority rules add reverse-logistics costs and documentation burdens for domestic assembly operations targeting South Asian distribution.
Strategic Opportunities
- Smart control integration:Pressure sensors and flow meters enabling variable-rate application are converging with usage logging systems for compliance documentation in precision agriculture segments.
- Subscription maintenance models:Seasonal servicing contracts bundling hardware with battery replacement programs create recurring revenue streams beyond one-time equipment sales.
- Rental-shop channel penetration:Dense equipment rental networks place battery sprayers within reach of occasional-use customers without capital purchase requirements.
Industry Challenges
- Technician certification timelines:EPA and OSHA equipment validation requirements extend product launch cycles for sealed-system designs entering US commercial channels.
- Dealer network reconfiguration:Transition from gasoline-powered inventory to battery-electric stock requires service bay retooling and staff retraining across agricultural equipment distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery-Operated Knapsack Sprayer Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Backpack Sprayer, Handheld Sprayer, Motorized Sprayer, Multi-Function Sprayer End User: Agricultural Producers, Commercial Landscapers, Professional Applicators, Home Gardeners Capacity: 5 Liters, 10 Liters, 15 Liters, 20 Liters Technology: Electric Pump System, Lithium-Ion Battery, Solar-Assisted, Smart Control |
| Companies Covered | Cub Cadet, AGCO Corporation, Deere & Company, Briggs & Stratton Corporation, Chapin International, ECHO Incorporated, Karcher, STIHL, Ryobi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery-Operated Knapsack Sprayer Market Trends and Innovations
Smart control technology is reshaping competitive positioning by enabling precision application and compliance documentation. Manufacturers are racing to integrate sensors and connectivity modules that transform standalone sprayers into data-capture nodes for farm management systems.
Lithium-ion battery chemistry is converging with diaphragm-pump efficiency improvements to extend runtime per charge while reducing pack weight. Orchard operators in California and Florida are adopting these configurations for full-day spraying without midday swaps. The technology is converging with precision agriculture platforms, compressing the addressable market for basic manual-pump alternatives.
EPA emissions standards and the EU F-Gas Regulation are tightening certification requirements for spray equipment in commercial markets. These rules raise regulatory friction for engine-driven alternatives requiring fuel handling and exhaust management. Battery-electric platforms capture share in US and European distribution channels as distributors face compliance documentation burdens for gasoline-powered inventory.
Cooperative procurement programs are consolidating smallholder demand into volume contracts that bypass traditional dealer networks. State-level agricultural departments in India aggregate orders through district-level tenders, compressing margins for intermediaries. This pattern concentrates most visibly in Maharashtra and Gujarat, where horticulture expansion pulls volume through regional dealer networks reconfigured as fulfillment agents rather than stocking distributors.
Battery-Operated Knapsack Sprayer Market Segmentation
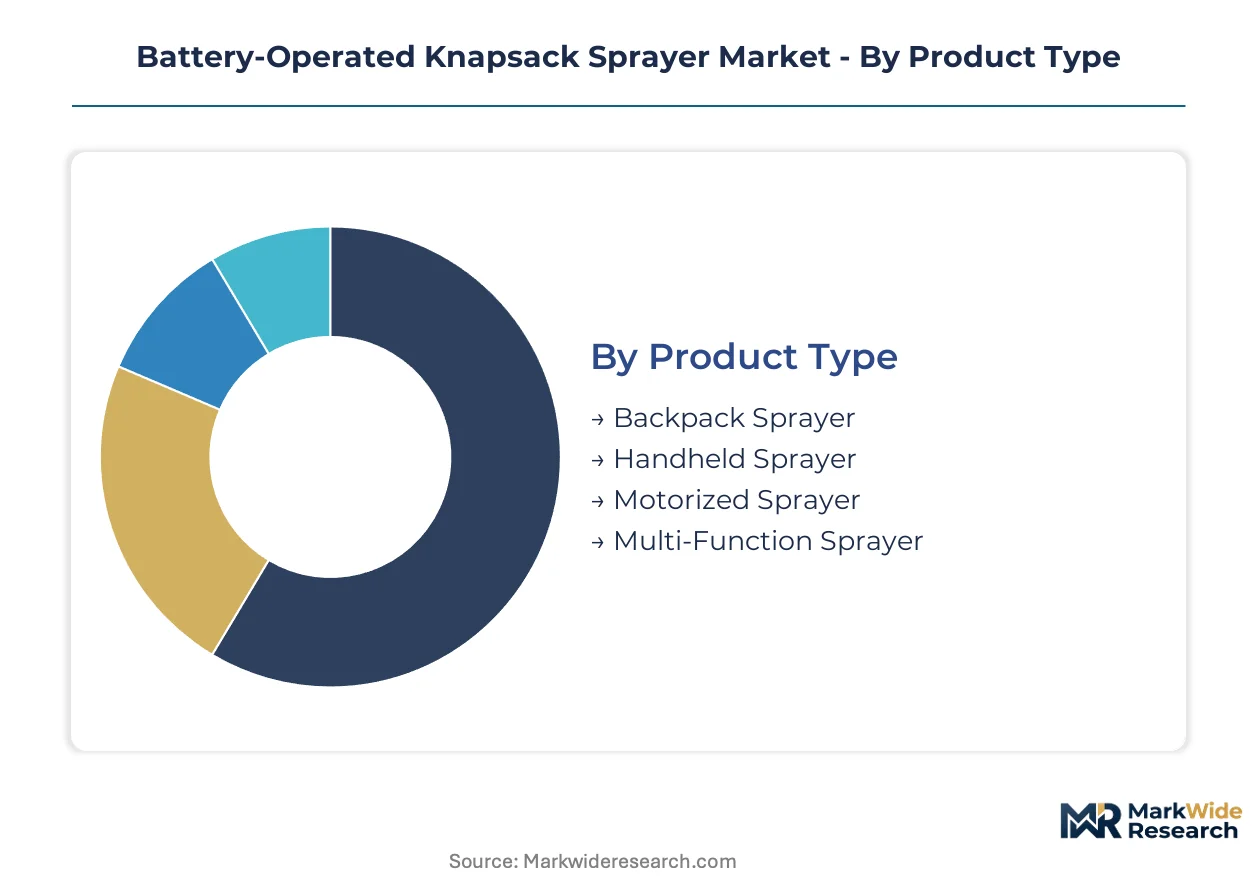
Segmentation in the Battery-Operated Knapsack Sprayer Market reveals how product architecture aligns with operator mobility needs, chemical volume requirements, and power source preferences. Distinct usage patterns across orchard spraying, turf maintenance, and smallholder field applications create divergent specifications for tank capacity, pump pressure, and battery runtime.
Product Type:
Standalone wearable configurations dominate commercial agriculture, while handheld variants serve embedded spot-treatment workflows in landscaping and home gardening segments.
- Backpack Sprayer:Ergonomic frame-mounted tank assemblies distribute 15-20 liter loads across shoulders and hips, enabling 6-8 hour spray sessions in Maharashtra vineyard corridors and Gujarat cotton belts. Cooperative procurement programs in these Indian states specify backpack units for their balance of mobility and chemical capacity.
- Handheld Sprayer:Compact 2-5 liter units with pistol-grip wands target precision spot applications in ornamental landscaping and greenhouse maintenance. Florida nursery operators favor these for targeted fungicide delivery between dense plantings where backpack maneuverability proves restrictive.
- Motorized Sprayer:High-pressure diaphragm pumps mounted on wheeled carts extend coverage to larger acreages without the physical load of tank carriage. California almond growers deploy these for inter-row herbicide application across orchard floors.
- Multi-Function Sprayer:Modular nozzle and tank configurations switch between foliar feeding, pesticide application, and sanitizing washdowns. These units gain traction in diversified smallholder operations across India's horticulture expansion zones.
Volume placements concentrate in Backpack Sprayer configurations; the faster expansion belongs to Multi-Function Sprayer systems.
End User:
Cost tier stratification separates capital-intensive commercial operations from price-sensitive occasional users, with procurement channel structure varying sharply across these boundaries.
- Agricultural Producers:Smallholder cooperatives and mid-scale orchard operators constitute the core revenue base, with India's PLI scheme subsidies compressing payback periods for farmers upgrading from manual lever pumps. These buyers prioritize runtime reliability and dealer service proximity over upfront cost minimization.
- Commercial Landscapers:Fleet operators maintaining municipal parks, golf courses, and corporate grounds demand standardized equipment pools with interchangeable batteries and rapid service turnaround. Rental-shop networks in North American metro markets serve this segment with seasonal equipment access.
- Professional Applicators:Licensed pest control and agricultural chemical contractors require sealed-system designs satisfying OSHA exposure documentation. EPA equipment validation requirements extend procurement cycles for this compliance-sensitive tier.
- Home Gardeners:Price-elastic residential buyers drive volume in 5-10 liter capacity brackets through retail hardware channels, with lithium-ion premiums resisted in favor of lead-acid first-cost economics.
Revenue concentration sits with Agricultural Producers; Commercial Landscapers are climbing the fastest as subscription maintenance models penetrate fleet accounts.
Capacity:
Tank sizing directly determines refill frequency, operator fatigue trade-offs, and chemical batch consistency across single-day spray schedules.
- 5 Liters:Ultra-portable configurations suit greenhouse workers and home gardeners requiring frequent repositioning without chemical spoilage from extended tank residence. These units sacrifice runtime for maneuverability in confined spaces.
- 10 Liters:The intermediate standard balances single-tank coverage area against wearable weight, dominating professional landscaping fleets in European municipal maintenance contracts.
- 15 Liters:Extended-capacity tanks align with half-day spray schedules in row-crop applications, minimizing refill downtime across California vegetable production fields.
- 20 Liters:Maximum-capacity configurations target full-day orchard operations where refill water access is limited, prevalent in Indian cooperative procurement specifications for Maharashtra mango and grape belts.
Procurement volume clusters at 15 Liters; 20 Liters configurations are gaining share fastest as battery runtime improvements eliminate midday tank swaps.
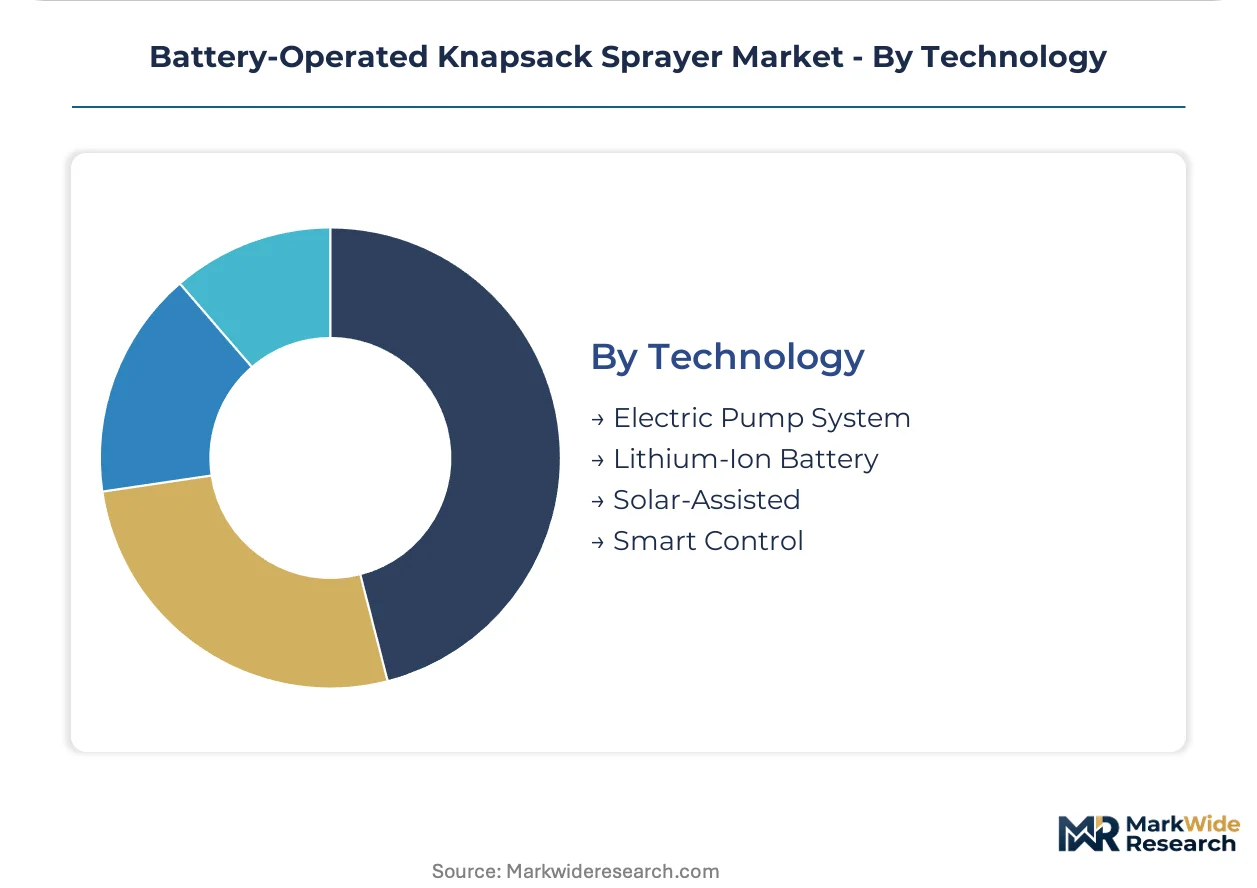
Technology:
Power source and control architecture differentiation separates mature commodity segments from emerging precision-application tiers with data-capture capabilities.
- Electric Pump System:Diaphragm and centrifugal pump mechanisms operating at 2-6 bar pressure deliver consistent flow rates without manual lever cycling. These systems anchor the base technology layer across all product tiers.
- Lithium-Ion Battery:Energy-dense cell chemistry extends runtime per charge while reducing pack weight versus legacy lead-acid alternatives. Orchard operators in Florida and California specify these for full-day spraying without battery swaps.
- Solar-Assisted:Photovoltaic panel integration extends field autonomy in off-grid smallholder contexts, with panel-integrated tank lids trickle-charging batteries between spray sessions in Indian solar-irrigated districts.
- Smart Control:Pressure sensors, flow meters, and Bluetooth connectivity enable variable-rate application and automated usage logging for compliance documentation. These precision-agriculture features command margin premiums in certified organic and restricted-chemical regimes.
Unit shipments concentrate in Electric Pump System configurations; Smart Control integration is expanding most quickly as farm management software platforms standardize equipment connectivity protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's grape and mango belts drive India's cooperative procurement volume, with district-level tenders consolidating smallholder demand into bulk contracts that bypass traditional dealer markups.
India
Maharashtra and Gujarat horticulture expansion pulls equipment volume through reconfigured dealer networks now operating as fulfillment agents. The PLI scheme for agricultural mechanization subsidizes cooperative purchases, compressing payback periods for farmers upgrading from manual lever pumps. Nashik district's vineyard corridors specify 20-liter backpack units for full-day spraying without midday tank swaps.
United States
California almond growers and Florida citrus operators specify lithium-ion configurations for orchard floor applications requiring 6-8 hour runtime reliability. EPA emissions standards and OSHA agricultural chemical exposure limits mandate sealed-system designs that battery-electric platforms satisfy more readily than gasoline-powered alternatives. Fresno County's inter-row herbicide contractors face extended equipment validation cycles for commercial channel entry.
Germany
Baden-Württemberg's precision agriculture clusters integrate smart control sprayers with farm management software platforms for variable-rate application documentation. The EU F-Gas Regulation raises regulatory friction for engine-driven alternatives requiring fuel handling protocols. Stuttgart-region equipment distributors retool service bays for battery-electric inventory transitions.
Brazil
São Paulo state's coffee and citrus belts generate demand for diaphragm-pump architectures extending runtime per charge across undulating terrain. Federal agricultural credit programs reduce capital barriers for mechanization upgrades among mid-scale producers. Campinas-region cooperatives aggregate orders through state-level agricultural department tenders.
Australia
Queensland's banana and macadamia orchards specify solar-assisted configurations trickle-charging batteries between spray sessions in off-grid districts. The national farm input carbon-accounting framework reshapes total-cost-of-ownership calculations for institutional buyers. Bundaberg-region pest management contractors prioritize sealed-system designs satisfying chemical exposure documentation requirements.
Battery-Operated Knapsack Sprayer Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent manufacturing footprints. Equipment assemblers with captive battery pack operations face different margin pressures than those sourcing cells from East Asian contract manufacturers. The vendor base separates into three strategic archetypes: integrated agricultural equipment conglomerates leveraging dealer infrastructure, specialized pump-technology specialists competing on runtime metrics, and power-tool platform owners extending battery ecosystems into adjacent outdoor equipment categories. Dominant competitive moves include subscription-based maintenance program rollouts and rental-shop channel penetration placing units within reach of occasional-use customers without capital purchase requirements.
Within the integrated equipment tier, Deere & Company and AGCO Corporation exemplify capital-heavy producers bundling sprayer sales with seasonal servicing contracts across North American farm belts. Chapin International occupies a position among pump-technology specialists, while STIHL represents power-tool platform owners extending battery ecosystems through dense rental-shop networks. ECHO Incorporated and Ryobi sit within the same archetype as ecosystem extenders, with Cub Cadet, Karcher, and Briggs & Stratton Corporation representing diversified equipment fabricators with varying degrees of vertical integration into powertrain components.
| Leading Market Players |
|---|
| Cub Cadet |
| AGCO Corporation |
| Deere & Company |
| Briggs & Stratton Corporation |
| Chapin International |
| ECHO Incorporated |
| Karcher |
| STIHL |
| Ryobi |
| Others |
Pricing and Supply Chain Analysis
Assembly technician clusters in Maharashtra's Nashik district and Shenzhen's manufacturing corridors create labor-cost differentials that stretch pricing-tier spreads between premium lithium-ion configurations and economy lead-acid alternatives. Indian domestic assemblers exploit lower wage floors to undercut East Asian imports on first-cost metrics, while EPA-certified sealed-system designs command margin premiums in US commercial channels.
Pricing Analysis
Runtime-per-charge guarantees anchor value-based pricing for orchard operators calculating payback through labor-hour savings. Three-tier pricing structure across premium smart-control, standard lithium-ion, and economy lead-acid levels separates buyers by certification burden and precision-agriculture readiness. Pricing pressure stems from cooperative procurement aggregation in Gujarat and Maharashtra compressing dealer markups. Smallholder cooperatives exhibit highest price sensitivity, while licensed commercial applicators absorb premiums for OSHA-compliant sealed systems.
Supply Chain Analysis
Dual-sourcing requirements from Deere and AGCO procurement teams mandate qualified cell suppliers across China, South Korea, and Japan to mitigate concentration risk. Battery pack assembly draws from East Asian lithium-cell foundries, Indian diaphragm-pump fabricators, and German pressure-sensor specialists. Single-source vulnerability in cylindrical cell formats exposes assemblers to freight cost volatility and raw material allocation shocks. Distribution runs through reconfigured dealer networks in Maharashtra and Gujarat now operating as fulfillment agents rather than stocking distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
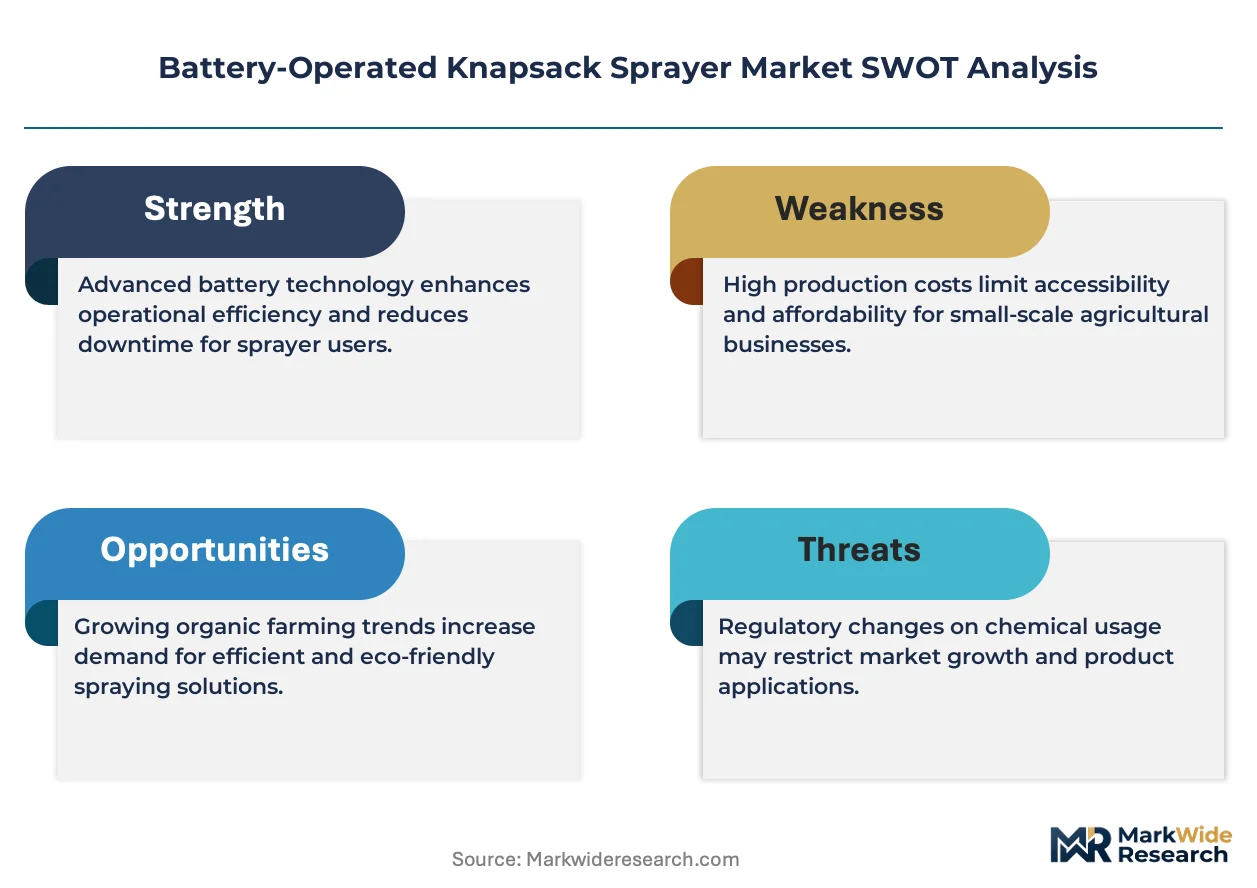
East Asian lithium-cell capacity constraints prop pricing power for assemblers with qualified dual-source relationships, compressing margins for single-source dependent competitors.
For Market Incumbents: Anticipate margin compression from cooperative procurement aggregation by securing exclusive service contracts with Maharashtra and Gujarat state agricultural departments. Backward integration into battery pack assembly in Indian tariff-advantaged zones defends position against low-cost Asian imports. Prioritize BIS certification investment to maintain channel access as India's CEA disposal rules tighten. For New Entrants and Emerging Players: Launch via rental-shop networks in North American metro markets to bypass capital-purchase barriers among occasional-use commercial landscapers. Target solar-assisted configurations in Queensland and Indian solar-irrigated districts where grid dependency creates white space. Pursue white-label partnerships with established pump-technology specialists to accelerate EPA validation timelines. For Investors and Strategic Acquirers: The window for entry favors pump-technology specialists with captive diaphragm-pump architectures and runtime-proven product lines. Long-term viability hinges on smart-control integration capabilities as farm management software platforms standardize equipment connectivity protocols. Watch lithium-cell supply allocation shifts as the dominant inflection signal for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Maintenance Program Rollout | Deere's seasonal servicing contracts in Fresno County transform one-time hardware sales into recurring revenue streams. |
| Smart Control Platform Integration | Pressure sensor and flow meter convergence with Bluetooth connectivity enables variable-rate application documentation for OSHA compliance. |
| Rental-Shop Channel Penetration | STIHL's dense equipment rental networks place battery sprayers within reach of occasional-use customers without capital purchase requirements. |
| Backward Integration into Battery Pack Assembly | Captive lithium-ion pack production in Indian PLI-advantaged zones reduces exposure to East Asian cell manufacturer allocation volatility. |
| Cooperative Procurement Partnership | Maharashtra state agricultural department tenders consolidate smallholder demand into volume contracts that bypass traditional dealer markups. |
Research Methodology
Trade databases, agricultural equipment customs records, and BIS certification filings formed the secondary backbone, cross-referenced with primary interviews of Maharashtra cooperative procurement officers, California almond grower association technical directors, and Stuttgart-region precision agriculture cluster managers. Bottom-up unit shipment tallies from Indian state tender databases and North American dealer inventory systems were triangulated against top-down value estimates derived from lithium-cell import manifests and pump component trade flows.
Historical trendline analysis of manual-to-battery sprayer replacement cycles across Maharashtra vineyard corridors and California Central Valley orchards established baseline penetration trajectories. The projection framework modeled segmentation dimensions across product architecture, battery chemistry tier, end-user procurement channel, and regional regulatory cluster. CAGRs were synthesized from runtime-extension technology adoption curves and cooperative procurement program expansion timelines.
Lithium-cell supply disruption, PLI scheme subsidy modification, and EPA equipment validation timeline extension are the dominant revision risks to modeled outcomes. Deviation in East Asian cell manufacturer allocation priority would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Intelligent Milking Robot Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Billhook Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Bucking Machine Market