
 Soil Mixer Market | 2026-2036
Soil Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Soil Mixer Market Analytics
REACH compliance is pivoting the European cost-of-entry calculus for soil mixer imports, requiring material certifications and emissions documentation that smaller exporters struggle to assemble. Mitchell Ellis Products leverages its domestic manufacturing footprint to sustain CE-marked product lines without cross-border certification delays. Demtec anchors its competitive position through specialized continuous mixing systems designed for peat-substrate integration in Dutch horticulture. AgriNomix differentiates by controlling distribution through direct dealer networks across North American nursery clusters.
Soil mixers are industrial blending machines engineered to homogenize organic and mineral substrates with moisture content typically ranging from 40% to 65%, employing rotating augers, paddle assemblies, or drum tumbling mechanisms to achieve uniform particle distribution for root-zone applications. Batch mixers occupy the largest installed base due to their operational flexibility across variable recipe formulations, while continuous mixers are gaining traction in high-throughput greenhouse operations where conveyor-fed systems reduce labor touchpoints. Automated mixers command premium positioning as nurseries and contract growers integrate recipe management software with batch weighing and moisture sensing to reduce substrate variability.
The EPA regulates particulate emissions from agricultural processing equipment under Clean Air Act provisions, while OSHA standards govern worker exposure to respirable silica and organic dust during soil handling operations. The EU F-Gas Regulation and associated national implementations constrain refrigerant choices in climate-controlled mixing environments, indirectly affecting equipment specifications for enclosed systems. Stakeholders must monitor how emerging state-level carbon accounting rules for agricultural inputs reshape capital allocation between mechanical and automated mixing platforms.
Market Dynamics
Contract growing obligations from large retailers are compressing batch cycle times and forcing nurseries to abandon manual mixing in favor of conveyor-fed continuous systems with integrated moisture sensing and recipe management software.
Growth Catalysts
- EPA Particulate Standards:The EPA's evolving Clean Air Act enforcement on agricultural equipment emissions is compelling greenhouse operators to replace open mixing drums with enclosed housing systems featuring dust collection integration.
- Peat-Substrate Integration:Dutch floriculture and vegetable propagation operations require precision blending of peat-based substrates at industrial throughput, pulling demand toward specialized continuous mixing architectures.
- Contract Growing Concentration:Large retail procurement contracts for live goods are forcing commercial nurseries in the United States to mechanize soil preparation capacity to meet volume and consistency obligations.
Market Restraints
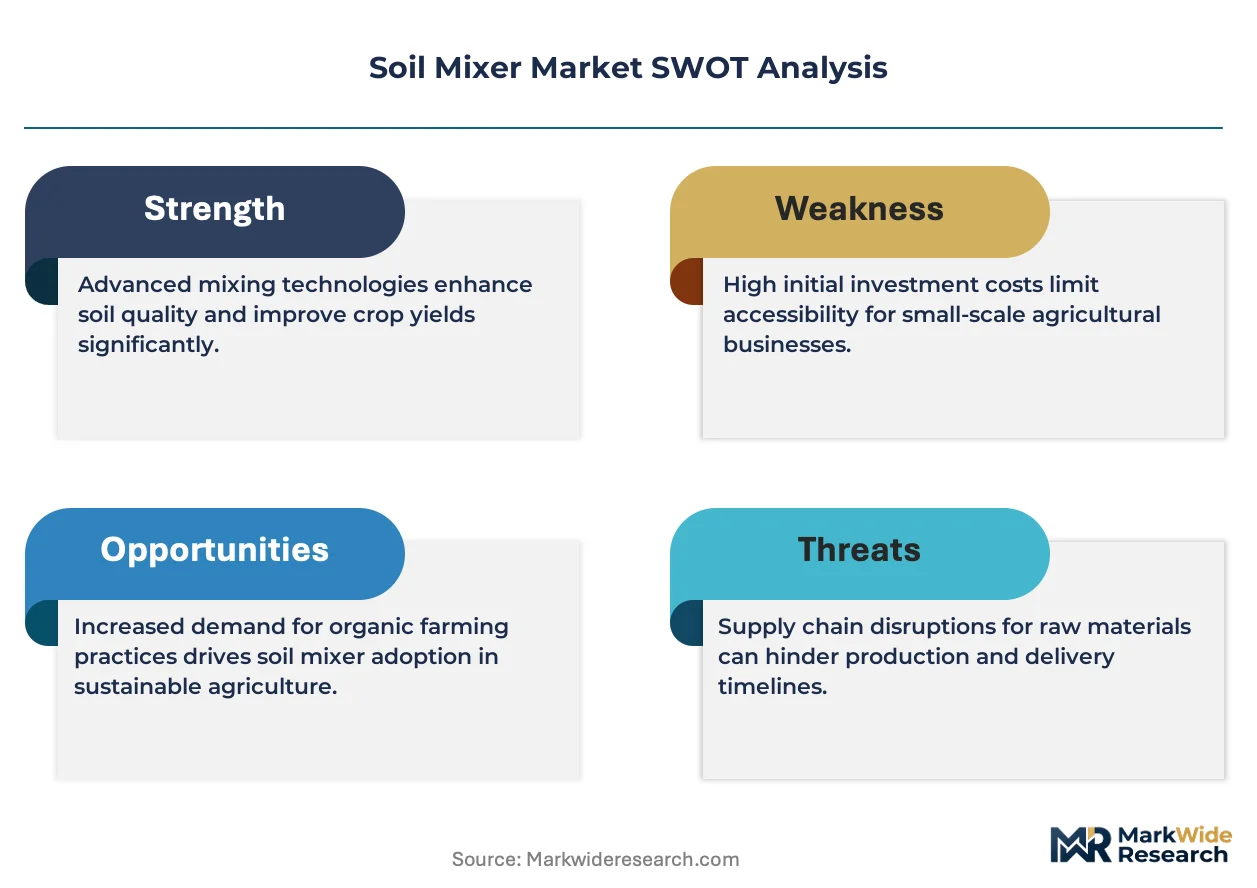
- Steel Input Volatility:Carbon steel and stainless steel price swings directly compress mixer fabrication margins, particularly for batch mixer manufacturers serving mid-sized nursery operations.
- REACH Documentation Burden:European REACH compliance requirements for material certifications and emissions documentation create cost-of-entry barriers that smaller exporters cannot assemble, constraining import competition.
- Used Equipment Circulation:Secondary markets for refurbished batch mixers extend replacement cycles among price-sensitive growers, delaying new equipment adoption in mature nursery clusters.
Strategic Opportunities
- Controlled Environment Agriculture:Vertical farming and containerized greenhouse startups in the United Arab Emirates and Saudi Arabia require compact, automated mixing systems for custom substrate formulations.
- EU F-Gas Regulation:Climate-controlled mixing environments face refrigerant constraints under the EU F-Gas Regulation, creating specification opportunities for equipment vendors offering enclosed systems with alternative cooling architectures.
- Recipe-as-a-Service Models:Subscription-based substrate formulation software integrated with automated batch weighing hardware offers recurring revenue streams beyond equipment sales to large contract growers.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of load cells, moisture sensors, and programmable logic controllers requires controls engineers that agricultural equipment manufacturers struggle to recruit from automotive and robotics sectors.
- CE Marking Timeline Compression:European market entry demands conformity assessment documentation that extends product launch cycles by 8-14 months for manufacturers without established notified body relationships.
- Legacy System Interoperability:Retrofitting automated recipe management onto existing batch mixer fleets requires custom mechanical and electrical engineering that erodes project margins for mid-tier nursery operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soil Mixer Market |
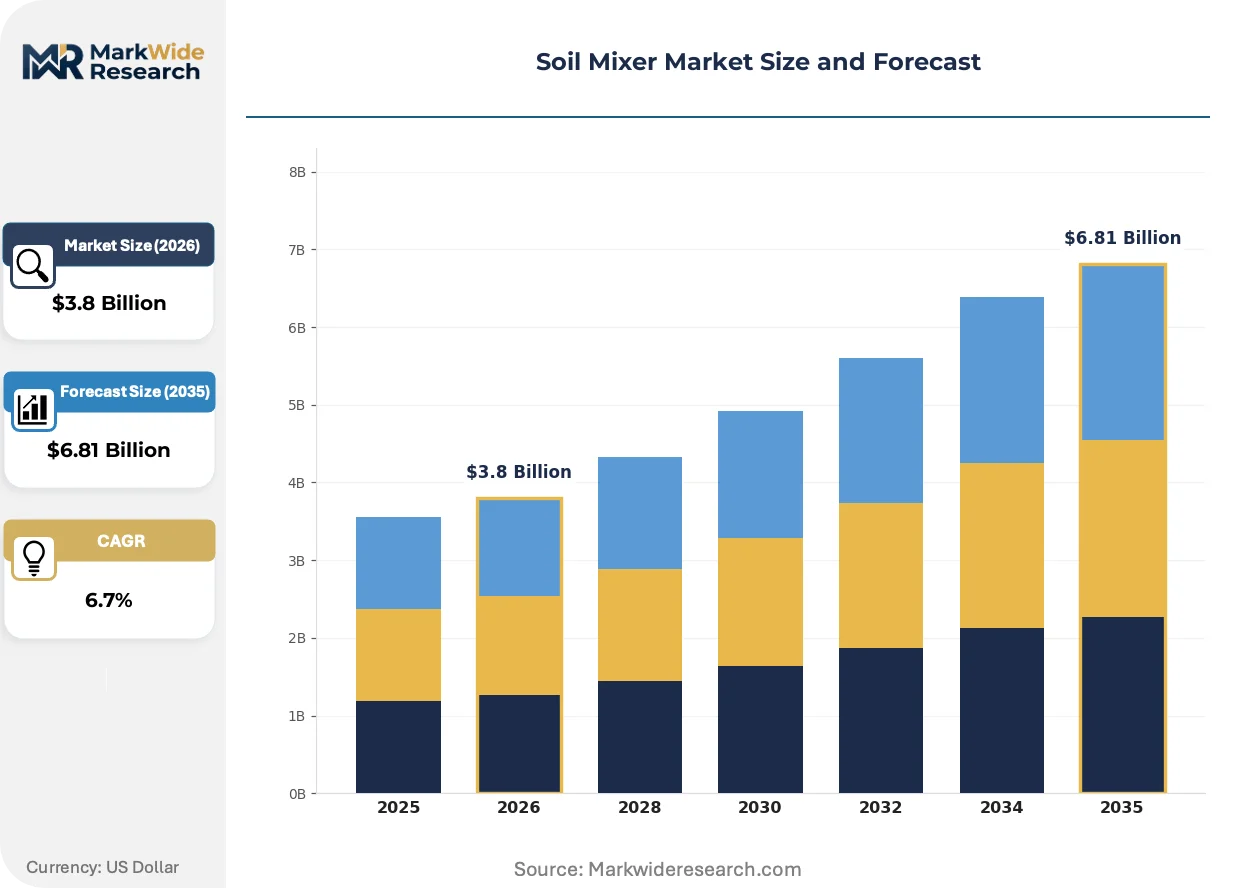
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Mixers, Continuous Mixers, Vertical Mixers, Horizontal Mixers Application: Agriculture, Landscaping, Construction, Horticulture End User: Farmers, Contractors, Garden Centers, Nurseries Technology: Mechanical Mixers, Automated Mixers, Batch Production, Transportable Mixers |
| Companies Covered | Mitchell Ellis Products, Bouldin & Lawson, C-Mac Industries, H.C. Davis Sons Manufacturing, Kase Horticulture, Pack Manufacturing, AgriNomix, Javo, Demtec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soil Mixer Market Evolving Landscape
Automation architectures are displacing manual batch operations across greenhouse and nursery facilities, while regulatory pressure on emissions and worker exposure reshapes equipment specifications and enclosure designs.
Recipe management software paired with automated batch weighing and real-time moisture sensing is automating substrate variability reduction for contract growers. Large commercial nurseries in the United States and the Netherlands are deploying these systems at replacement cycle points to meet retailer consistency requirements. The technology is automating labor out of formulation oversight while compressing batch-to-batch deviation windows.
The EU F-Gas Regulation and associated national implementations are constraining refrigerant choices for climate-controlled mixing environments. Equipment manufacturers must redesign enclosed housing systems to accommodate alternative cooling architectures or face market exclusion from Dutch and German greenhouse operations. Dutch horticulture equipment suppliers are responding fastest, leveraging proximity to regulatory intelligence and customer feedback loops.
Service unbundling is fragmenting traditional equipment-plus-support contracts into separate hardware, software subscription, and technical service lines. Large nursery operations in California and Florida are negotiating direct software licenses with automation vendors while sourcing mixer hardware through independent distributors. This pattern is most visible among contract growers managing multiple facility locations who require centralized recipe control across dispersed mixing operations.
Soil Mixer Market Segmentation
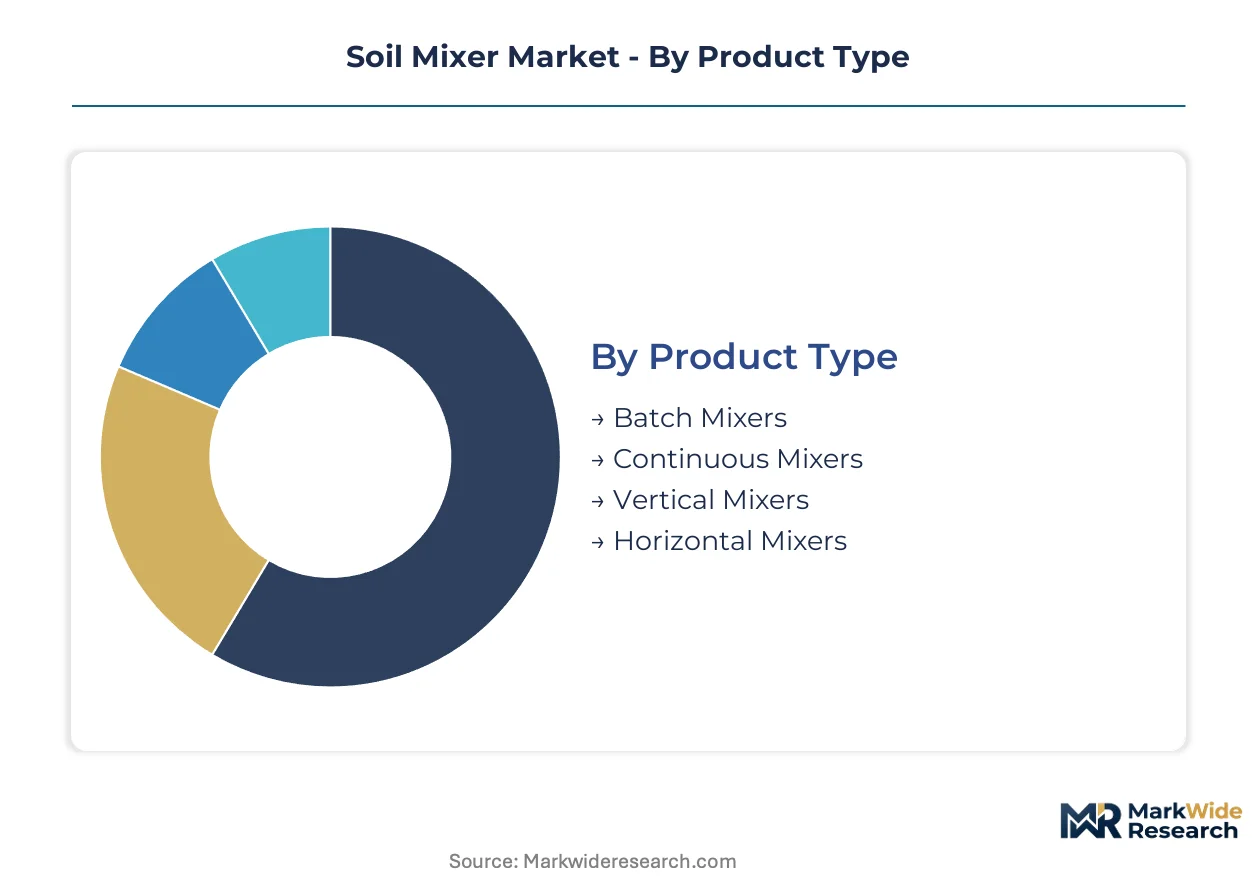
Segmentation in soil mixing equipment reveals how regulatory complexity, automation intensity, and end-use scale reshape procurement patterns across substrate preparation workflows. Distinct certification burdens, operational cost structures, and throughput requirements separate customer groups and drive equipment specification divergence.
Product Type:
Batch Mixers carry CE marking obligations for European nursery sales, while Continuous Mixers face additional EPA particulate compliance for enclosed housing designs in US commercial operations. Vertical and Horizontal configurations trigger varying OSHA exposure assessments depending on drum orientation and dust containment architecture.
- Batch Mixers:Rotating drum or paddle assemblies process discrete substrate loads of 0.5 to 5 cubic yards per cycle, enabling recipe flexibility for variable peat-perlite-vermiculite formulations. Demand concentrates among mid-sized US nurseries serving regional retail contracts, where batch cycle compression and manual labor substitution drive replacement decisions.
- Continuous Mixers:Conveyor-fed auger or screw mechanisms blend substrates at throughputs exceeding 20 cubic yards per hour with integrated moisture sensing and automated recipe management. Dutch greenhouse vegetable propagation operations pull demand toward these architectures, where conveyor integration eliminates labor touchpoints and substrate consistency satisfies retailer quality audits.
- Vertical Mixers:Upright drum configurations with gravity-fed discharge reduce floor space requirements for compact nursery operations. Garden centers in Japan and South Korea specify these units for limited-footprint substrate preparation.
- Horizontal Mixers:Trough-style auger systems handle high-moisture substrates up to 65% water content without bridging. Contractors in Australian landscaping applications favor these for coarse soil amendment blending.
Batch Mixers sits at the top of the volume ranking, with Continuous Mixers climbing the fastest.
Application:
Cost tier stratification separates premium automated systems in Horticulture from mechanical units in Landscaping, with Agriculture occupying the mid-tier and Construction demanding the most ruggedized specifications.
- Agriculture:Field-scale soil amendment blending for row crops and specialty vegetable production, typically involving tractor-pulled or stationary PTO-driven units. US Midwest grain operations and Brazilian soybean cooperatives represent core demand clusters.
- Landscaping:On-site soil conditioning for commercial and residential development projects, requiring transportable or skid-mounted configurations. Australian and Canadian contractors specify these for erosion control and turf establishment.
- Construction:Engineered fill preparation and contaminated soil remediation blending, demanding reinforced drum construction and abrasion-resistant liners. German infrastructure projects and UAE desert stabilization contracts drive specification intensity.
- Horticulture:Precision substrate formulation for greenhouse vegetable propagation, floriculture, and nursery stock production. Dutch greenhouse clusters and US contract growing operations command premium automation integration.
Horticulture captures the steepest expansion trajectory, while Agriculture maintains the largest installed base.
End User:
Customer type determines automation penetration, with Nurseries adopting recipe management software fastest and Farmers remaining most price-sensitive to steel input volatility.
- Farmers:Owner-operated agricultural enterprises prioritizing capital efficiency over throughput maximization. Indian and Brazilian smallholders favor manual or mechanically simple batch configurations.
- Contractors:Project-based landscaping and earthmoving firms requiring equipment mobility and rapid site relocation. Australian and Canadian civil contractors specify transportable mixer-trailer combinations.
- Garden Centers:Retail-oriented operations blending bagged substrates for consumer sale, with seasonal demand spikes driving rental over purchase preferences. UK and French garden center chains concentrate procurement.
- Nurseries:Commercial propagation facilities managing contract growing obligations for large retailers, where batch consistency and documentation traceability command automation investment. US Southeast and Netherlands operations lead adoption.
Nurseries sit at the top of the volume ranking, with Garden Centers climbing the fastest.
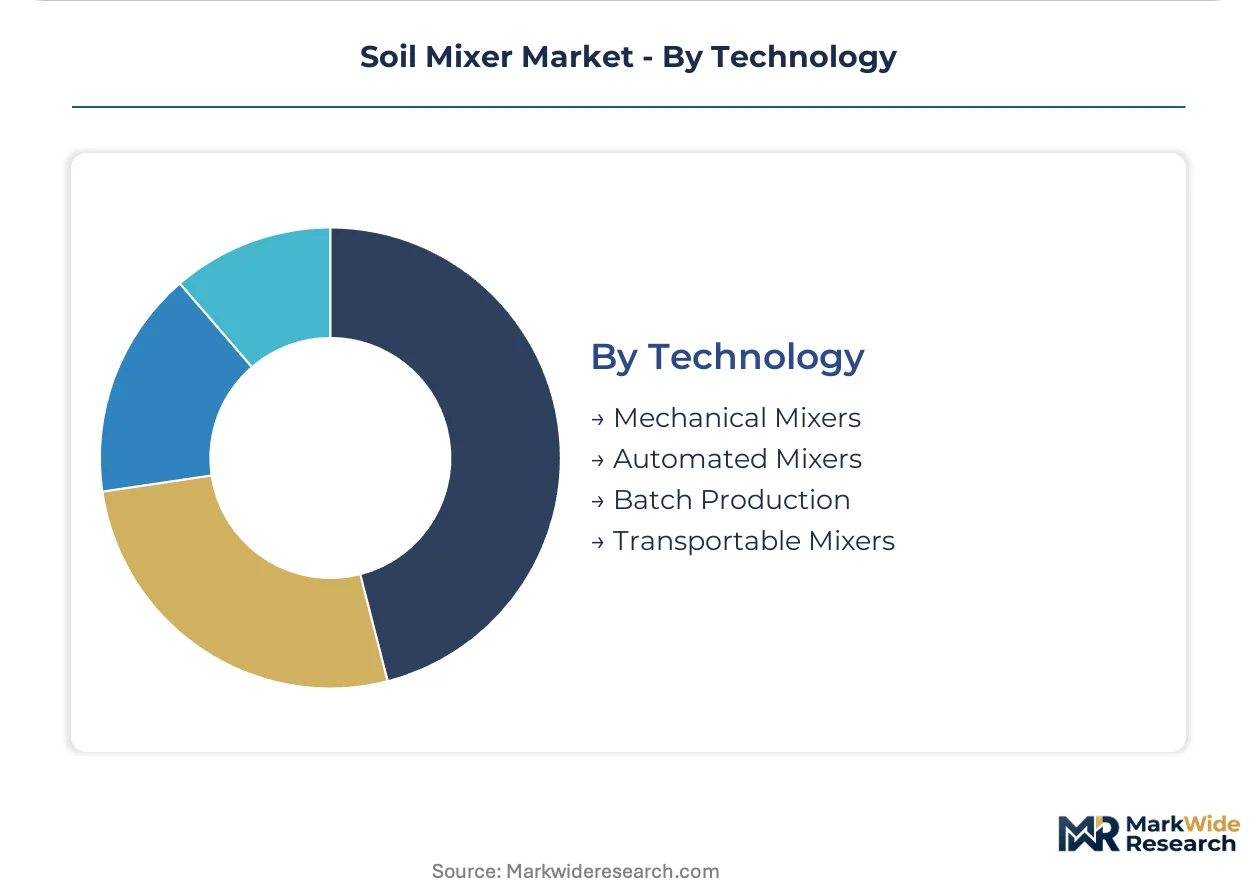
Technology:
Maturity stage separates legacy Mechanical Mixers from emerging Automated architectures, with Transportable configurations addressing geographic dispersion and Batch Production serving as the dominant operational mode.
- Mechanical Mixers:Human-operated drum or paddle systems without programmable control, representing the legacy installed base. Price-sensitive growers in Eastern Europe and Southeast Asia extend replacement cycles for these units.
- Automated Mixers:PLC-controlled systems integrating load cells, moisture sensors, and recipe management software for substrate variability reduction. US contract growers and Dutch greenhouse operators deploy these at replacement points.
- Batch Production:Discrete processing mode enabling recipe changeover between substrate formulations. Mid-sized nurseries across Germany and Poland rely on this operational flexibility.
- Transportable Mixers:Skid-mounted or trailer-integrated configurations for multi-site operations and rental fleets. UAE and Saudi Arabia vertical farming startups specify compact transportable units for containerized greenhouse deployment.
Batch Production sits at the top of the volume ranking, with Automated Mixers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized equipment fabricators cluster in the Netherlands, Germany, and the United States, where horticultural engineering talent concentrates near greenhouse operations and agricultural machinery corridors. Regional procurement patterns diverge sharply between European REACH-regulated markets and North American EPA jurisdictions.
United States
Commercial nurseries in Florida and Georgia mechanize soil preparation to fulfill contract growing obligations for big-box retailers. EPA Clean Air Act enforcement on particulate emissions drives replacement of open mixing drums with enclosed housing systems. The Southeast nursery belt anchors domestic demand for conveyor-fed continuous mixers with integrated dust collection.
Netherlands
Greenhouse vegetable propagation and floriculture operations require precision peat-substrate blending at industrial throughput. EU F-Gas Regulation constrains refrigerant choices for climate-controlled mixing environments, favoring enclosed system architectures. Westland municipality hosts the densest concentration of specialized continuous mixing system deployments.
Germany
Engineered fill preparation for infrastructure projects and contaminated soil remediation sustain demand for reinforced drum constructions. CE marking timelines extend product launch cycles by 8-14 months for manufacturers without established notified body relationships. Bavaria's construction equipment fabricators supply abrasion-resistant liner specifications for desert stabilization exports.
China
Domestic greenhouse expansion and vertical farming pilots in the Yangtze River Delta pull demand toward compact automated batch configurations. National dual carbon goals reshape capital allocation toward energy-efficient mixing platforms. Zhengzhou machinery clusters produce mechanically simple batch units for price-sensitive growers across Southeast Asia.
Australia
Landscaping contractors and erosion control specialists specify transportable skid-mounted mixers for rapid site relocation. National work health and safety regulations govern respirable silica exposure during soil handling operations. Queensland civil contractors favor horizontal trough-style auger systems for coarse soil amendment blending in rehabilitation projects.
Soil Mixer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers in soil mixing equipment. The vendor base separates into three strategic archetypes: domestic manufacturers leveraging proximity to nursery clusters, European specialists commanding premium positioning through regulatory compliance expertise, and diversified agricultural machinery houses extending into substrate preparation. Consolidation pressure concentrates among mid-tier batch mixer fabricators facing steel input volatility. Competitive moves center on geographic expansion into controlled environment agriculture markets and backward integration into recipe management software.
Among North American fabricators, Mitchell Ellis Products occupies a position serving domestic nursery operations with CE-marked product lines, while AgriNomix anchors distribution through direct dealer networks across regional growing clusters. Demtec represents the European specialist archetype, with Dutch horticulture proximity enabling rapid response to F-Gas regulatory evolution. These three exemplify how geographic positioning and regulatory intelligence separate competitive tiers.
| Leading Market Players |
|---|
| Mitchell Ellis Products |
| Bouldin & Lawson |
| C-Mac Industries |
| H.C. Davis Sons Manufacturing |
| Kase Horticulture |
| Pack Manufacturing |
| AgriNomix |
| Javo |
| Demtec |
| Others |
Value Network & Pricing Analysis
Contract growers in the US Southeast and Dutch greenhouse operators command divergent pricing models based on automation intensity requirements and regulatory compliance burdens. Their procurement concentration toward enclosed continuous systems with integrated dust collection and recipe management software establishes premium tier anchoring, while mid-sized nurseries in Eastern Europe and Southeast Asia extend replacement cycles for mechanical batch units.
Pricing Analysis
Service unbundling now separates hardware procurement from software subscription and technical support lines. Pricing stratifies across premium automated tiers with PLC-controlled recipe management, standard enclosed batch configurations with CE marking, and economy mechanical units without programmable control. Cost compression in the economy tier intensifies because steel input volatility directly compresses fabrication margins for carbon steel drum constructions. Farmers and smallholder cooperatives in India and Brazil exhibit the highest price sensitivity, while US contract growers managing retailer obligations show the least.
Supply Chain Analysis
CE marking and EPA particulate compliance documentation function as qualification gates that filter supplier participation in regulated markets. Equipment fabrication concentrates in the Netherlands, Germany, and the United States, where horticultural engineering talent clusters near greenhouse operations and agricultural machinery corridors. Steel drum and auger assemblies draw from carbon steel and stainless steel suppliers, while load cells and moisture sensors feed from precision instrumentation manufacturers. Single-source vulnerability runs through specialized continuous mixing system engineering talent concentrated in Dutch horticulture equipment clusters. Distribution runs through direct dealer networks across North American nursery belts and independent distributors serving European greenhouse operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between REACH-regulated European entry costs and EPA-enforced US replacement cycles, with the compliance documentation burden in the former creating margin capture opportunities for domestic manufacturers in the latter.
For Market Incumbents: Lock in dealer network exclusivity across US Southeast nursery clusters to defend against direct software licensing patterns fragmenting traditional equipment-plus-support contracts. Deepen backward integration into recipe management software development to capture recurring revenue streams beyond hardware sales. The emergence of subscription-based substrate formulation platforms from independent automation vendors threatens margin capture in the premium tier.
For New Entrants and Emerging Players: Begin with compact automated batch configurations for vertical farming and containerized greenhouse startups in the United Arab Emirates and Saudi Arabia, where controlled environment agriculture expansion outpaces established supplier presence. Controlled environment agriculture represents the most penetrable segment due to specification flexibility and absence of legacy equipment lock-in. A direct-to-grower software licensing model paired with third-party hardware sourcing bypasses capital-intensive manufacturing scale requirements.
For Investors and Strategic Acquirers: Diversified agricultural machinery houses are the most active acquirer in this space, extending into substrate preparation through bolt-on automation capabilities. The five-to-ten year viability window favors platforms with demonstrated recipe management software integration and established notified body relationships for CE marking acceleration. Acquisition targets should display specialized continuous mixing expertise for peat-substrate integration or direct dealer network control across regional nursery clusters. The signal to watch is state-level carbon accounting rule emergence for agricultural inputs, which would reshape capital allocation between mechanical and automated mixing platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Recipe Management Software Integration | Captures recurring revenue from US contract growers managing retailer consistency obligations. |
| CE Marking Acceleration Investment | Compresses product launch cycles by 8-14 months for European greenhouse market entry. |
| Enclosed Housing System Redesign | Satisfies EPA Clean Air Act particulate enforcement for US commercial nursery replacement demand. |
| Direct Dealer Network Expansion | Controls distribution across North American nursery clusters against unbundling patterns. |
| Peat-Substrate Integration Specialization | Addresses Dutch floriculture and vegetable propagation precision blending requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with nursery operations managers, greenhouse procurement directors, agricultural equipment dealers, and aftermarket service heads with secondary validation from customs and trade data, SEC equipment manufacturer filings, and EPA enforcement documentation. Bottom-up demand modeling from individual nursery capacity expansion plans triangulated against top-down market sizing from regional greenhouse construction permits and agricultural machinery shipment records.
Segment-weighting approaches distributed volume and value estimates across product type, application, end user, and technology dimensions, with additional modeling for automation intensity tiers and regulatory compliance categories. CAGRs were derived from replacement cycle analysis, capacity expansion announcements, and penetration rate assumptions across the projection horizon. Industry-specific forecast inputs included steel price index trajectories, EPA enforcement pattern shifts, and EU F-Gas Regulation implementation timelines for climate-controlled mixing environments.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting steel input costs, unanticipated REACH documentation requirement expansions, and breakthrough substrate formulation technologies eliminating mechanical mixing requirements. Forecasts reflect documented assumptions about replacement cycle timing and automation adoption rates. A model refresh is warranted upon material change in EPA particulate enforcement intensity or state-level carbon accounting rule promulgation for agricultural inputs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Global Subsoiler Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Wet Fertilizer Spreaders Market
Agricultural Equipment
Soil Testing Equipment Market
Agricultural Equipment
Plows Market