
 Flexible Silos Market | 2026-2036
Flexible Silos Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Silos Market Foresight
Advanced textile engineering in high-tenacity polypropylene woven fabrics is reshaping load-bearing capacity and weather resistance in flexible silo construction. Walter Krause leverages vertical integration across membrane production and steel frame fabrication to sustain cost leadership in Central European supply chains. Coima Group anchors its competitive position through specialized PVC-coated fabric formulations that dominate Mediterranean agricultural markets. Pneu Powders Systems differentiates via pneumatic filling integration, occupying a technical niche in automated bulk handling systems.
Flexible silos are collapsible textile storage vessels, typically fabricated from woven polypropylene or polyethylene fabrics with tensile strengths exceeding 1,500 N/5cm, designed for temporary or semi-permanent containment of free-flowing agricultural and industrial bulk solids. Their primary purpose centers on protecting harvested commodities from moisture ingress, pest infestation, and UV degradation while enabling rapid deployment without permanent foundations. Tubular silos command the largest installed base due to simplified erection protocols and minimal site preparation, though bell-shaped configurations capture premium margin pools where complete discharge and residue minimization drive purchasing decisions. Polypropylene dominates material selection for grain storage applications given its favorable strength-to-weight ratio and compliance with food-contact regulatory frameworks, while PVC-coated fabrics lead in fertilizer storage where chemical resistance requirements are most stringent.
REACH registration requirements govern chemical composition disclosures for European-manufactured polymer fabrics, directly influencing material substitution patterns and supplier qualification timelines. EPA grain handling facility standards under OSHA mandate specific dust containment protocols that elevate demand for sealed flexible silo designs over open bunker alternatives. BIS certification requirements in India impose mechanical testing benchmarks that filter import eligibility and shape domestic manufacturing investment. Stakeholders must monitor evolving biodegradability mandates and extended producer responsibility frameworks as these will increasingly determine material specification decisions and regional sourcing strategies.
Market Dynamics
REACH registration requirements and EPA grain dust standards are compressing supplier qualification timelines while bioenergy producers intensify polyethylene and polypropylene fabric procurement across Brazil's soybean belt and the Indo-Gangetic Plain.
Growth Catalysts
- REACH compliance mandates:European chemical composition disclosure rules are filtering import eligibility and accelerating material substitution toward certified polymer fabrics.
- Bioenergy sector expansion:Rising grain storage needs among ethanol and biogas producers are intensifying procurement of high-tenacity woven silos for feedstock containment.
- Indo-Gangetic rice-wheat systems:Double-cropping intensity across Punjab and Haryana is driving demand for rapid-deployment temporary storage without permanent foundations.
Market Restraints
- Polypropylene resin volatility:Feedstock price swings tied to naphtha and propylene markets compress margin predictability for fabric manufacturers.
- Steel frame supply concentration:Galvanized structural component production clusters in China's Hebei province create single-source vulnerability for European assemblers.
- Sealed-design technical limitations:Hermetic closure systems struggle to maintain pressure differentials during pneumatic filling above 15 meters of grain depth.
Strategic Opportunities
- Brazilian Cerrado expansion:Matopiba region soybean production growth outpaces permanent silo construction, creating white space for collapsible textile alternatives.
- Fertilizer chemical resistance:PVC-coated fabric formulations for ammonium nitrate and urea storage command premium pricing above grain applications.
- EU Green Deal biodegradability mandates:Extended producer responsibility frameworks will advantage suppliers with recyclable polymer recovery programs.
Industry Challenges
- Textile engineering talent scarcity:Weaving technicians skilled in high-tenacity polypropylene loom calibration remain concentrated in legacy industrial regions.
- BIS mechanical testing timelines:Indian certification benchmarks for tensile strength and UV resistance extend product launch cycles by 8-14 months.
- Pneumatic integration complexity:Automated bulk handling system retrofits face interoperability gaps with legacy grain elevator infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Silos Market |
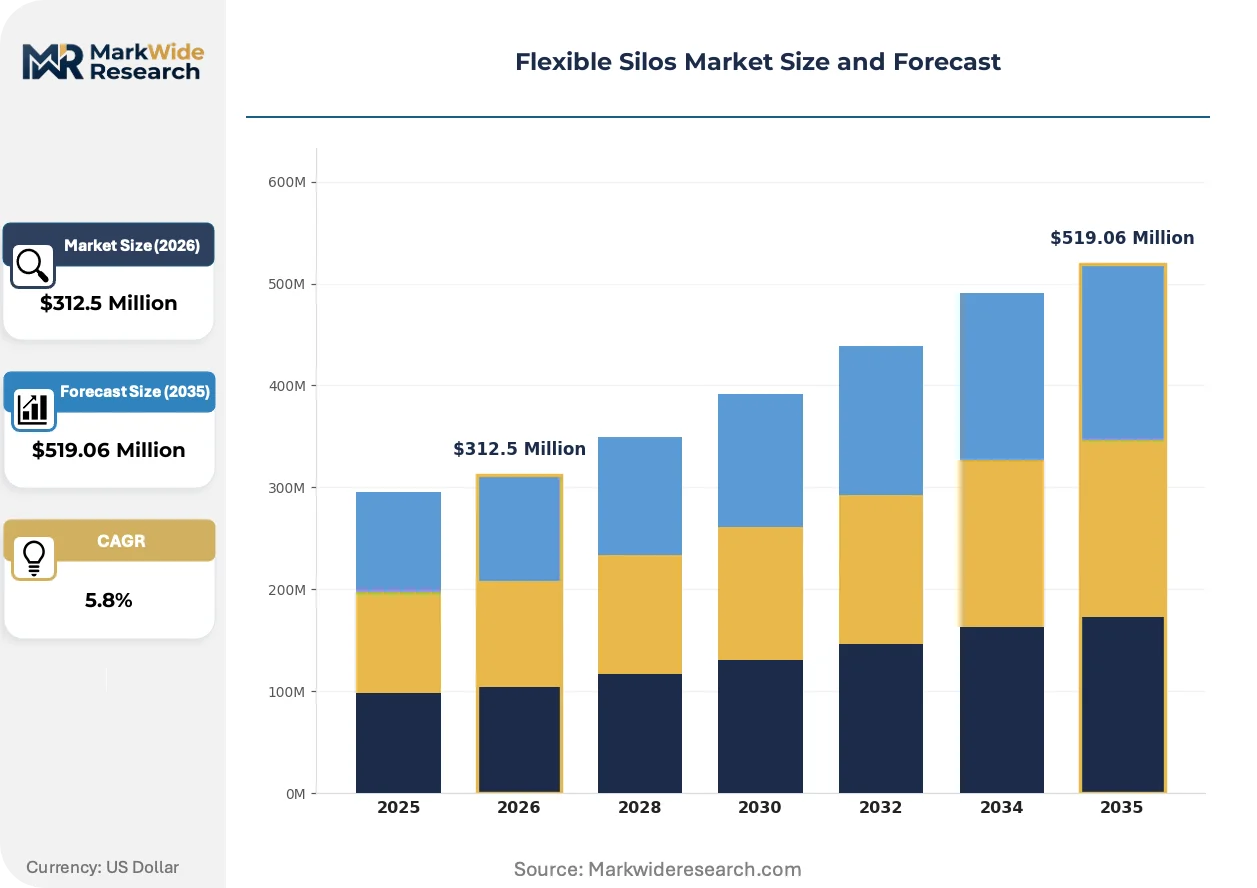
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubular Silos, Bag Silos, Flat-Bottom Silos, Bell-Shaped Silos Material: Polyethylene, Polypropylene, PVC Coated Fabric, Nylon, Polyurethane Application: Grain Storage, Feed Storage, Fertilizer Storage, Seed Storage, Biomass Storage End User Industry: Agriculture, Livestock Operations, Bioenergy Producers, Seed Suppliers |
| Companies Covered | Walter Krause, Coima Group, Pneu Powders Systems, Palamatic Process, Ambros Schmelzer, CEPI, Siloanlagen Achberg, Powder DS, Akkaya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Silos Market Shifts & Advancements
Advanced membrane engineering and automated filling integration are compressing deployment timelines while regulatory material mandates reshape supplier qualification protocols across agricultural and industrial bulk handling.
High-tenacity polypropylene woven fabrics with tensile strengths exceeding 1,500 N/5cm are rendering obsolete lower-grade polyethylene alternatives in grain storage applications. Large-scale cooperative buyers across the US Corn Belt and Ukrainian Black Sea ports are specifying these membranes for 500-tonne-plus capacity installations. The structural consequence is compressing price competition into certified-supplier tiers while marginalizing uncertified regional fabricators.
EPA grain handling facility standards under OSHA are mandating specific dust containment protocols that elevate demand for sealed flexible silo designs. The industrial consequence is disqualifying open bunker alternatives from federally inspected elevator facilities. US terminal operators are responding by retrofitting pneumatic filling systems with hermetic closure mechanisms to maintain compliance.
Buyer procurement patterns are consolidating toward outcome-based rental contracts rather than capital purchase for seasonal storage needs. Agricultural cooperatives in France's Beauce region and Argentina's Pampas are displacing ownership models with third-party managed silo-as-a-service arrangements. This shift is most visible where harvest timing volatility and working capital constraints intersect.
Flexible Silos Market Segmentation
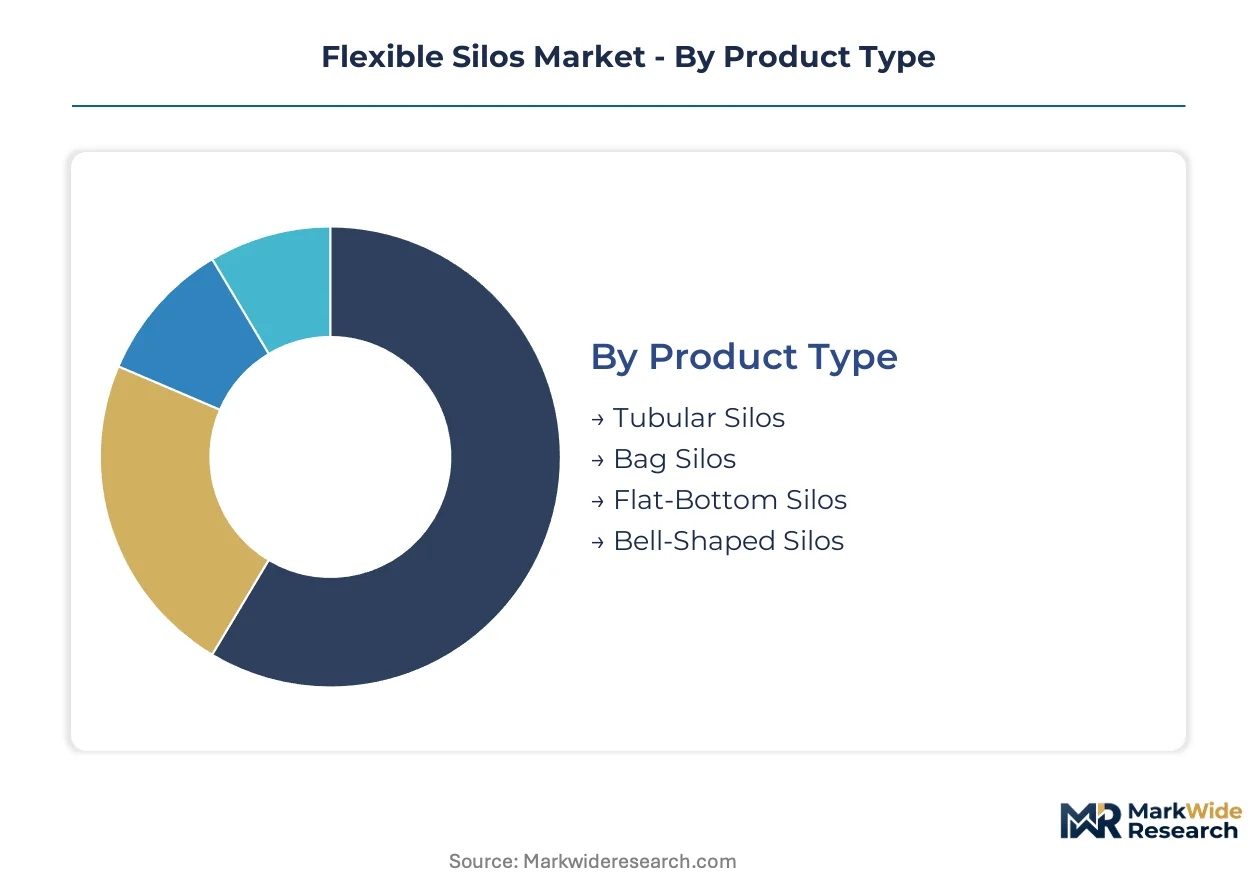
Segmentation in flexible silos reveals how procurement cycles, material specifications, and end-use durability requirements create distinct commercial pockets. Buyers optimize across deployment speed, chemical compatibility, and regulatory compliance rather than treating storage as a commodity purchase.
Product Type:
Cycle times vary dramatically: tubular configurations deploy in hours while bell-shaped installations require days of site preparation and foundation work.
- Tubular Silos:Cylindrical woven fabric membranes tensioned over minimal steel hoops dominate temporary grain storage. Demand concentrates among Ukrainian Black Sea port operators needing rapid throughput expansion without permanent construction permits.
- Bag Silos:Elongated sausage-shaped designs enable field-edge storage directly at harvest. French Beauce region cooperatives favor these for wheat and rapeseed containment where elevator capacity bottlenecks during peak intake windows.
- Flat-Bottom Silos:Ground-resting designs with integrated aeration floors suit long-duration storage. Indian Punjab rice mills specify these for government procurement buffer stocks requiring six-month holding periods.
- Bell-Shaped Silos:Tapered discharge profiles eliminate residue accumulation for seed and high-value crops. Premium pricing reflects complete emptying capability critical for Argentina's Pampas seed multiplication operations.
Tubular silos anchor the volume base while bell-shaped configurations gain share at the steepest rate.
Material:
Cost tiers separate commodity polymers from engineered coatings, with food-contact certification requirements filtering supplier eligibility.
- Polyethylene:Lower-tenacity woven grades serve short-duration feed storage where UV exposure remains limited. Brazilian Matopiba soybean operations use these for 90-day holding before export terminal transfer.
- Polypropylene:High-tenacity woven fabrics exceeding 1,500 N/5cm tensile strength dominate certified grain storage. REACH-registered formulations from Central European suppliers command preference among EU bioenergy feedstock handlers.
- PVC Coated Fabric:Chemical-resistant membranes withstand ammonium nitrate and urea exposure. Mediterranean fertilizer distributors specify these formulations for coastal storage yards with high humidity and salt air corrosion.
- Nylon:Abrasion-resistant weaves suit seed handling with frequent loading cycles. US Corn Belt seed suppliers deploy these for conditioning facility surge capacity during harvest rush.
- Polyurethane:Elastomeric coatings enable extreme low-temperature flexibility. Canadian Prairie operations specify these for winter canola storage where membrane brittleness risks catastrophic failure.
Polypropylene captures the largest revenue pool while PVC-coated fabrics expand most quickly on chemical resistance premiums.
Application:
Volume scale and margin structure diverge sharply: grain storage runs on thin margins at massive tonnage while seed and biomass applications support price premiums.
- Grain Storage:Wheat, corn, and soybean containment drives baseline demand. Indo-Gangetic Plain double-cropping systems generate seasonal procurement spikes requiring 500-tonne-plus temporary installations.
- Feed Storage:Dairy and poultry operations need moisture-protected silage and compound feed. German Lower Saxony livestock cooperatives favor rapid-deployment alternatives to permanent tower silos for expansion flexibility.
- Fertilizer Storage:Ammonium nitrate and urea handling demands chemical-resistant fabric formulations. Brazilian Cerrado input distributors specify these for pre-planting season inventory positioning.
- Seed Storage:Certified germination preservation requires hermetic sealing and temperature stability. Ukrainian seed multiplication farms deploy these for winter wheat and sunflower stock prior to spring distribution.
- Biomass Storage:Wood pellet and agricultural residue containment supports bioenergy feedstock security. Scandinavian district heating plants specify large-diameter configurations for strategic fuel reserves.
Grain storage anchors the volume base while biomass applications climb the fastest on renewable energy policy support.
End User Industry:
Customer sophistication and procurement authority separate centralized agricultural cooperatives from fragmented livestock operations.
- Agriculture:Large-scale grain farming and cooperative storage drives standardized procurement. French cooperative groups specify certified membranes through centralized buying pools.
- Livestock Operations:Dairy and feedlot enterprises prioritize rapid deployment for seasonal forage preservation. Argentine feedlot concentration in Buenos Aires province generates clustered demand.
- Bioenergy Producers:Ethanol and biogas facilities require certified feedstock security. German biogas associations specify REACH-compliant materials for maize silage and cereal grain intake.
- Seed Suppliers:Germination preservation mandates drive premium membrane specifications. US Midwest seed companies enforce lot traceability through hermetic storage protocols.
Agriculture anchors the volume base while bioenergy producers gain share at the steepest rate on renewable fuel mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian soybean exports to Chinese crushing mills are reshaping temporary storage procurement patterns across both origin and destination markets. Black Sea grain corridors through Ukrainian ports are accelerating demand for rapid-deployment silo infrastructure. Indo-Gangetic rice-wheat systems are generating seasonal procurement spikes that outpace permanent construction capacity.
United States
Corn Belt ethanol producers are expanding feedstock security inventories ahead of renewable fuel mandate revisions. EPA grain dust standards under OSHA are disqualifying open bunker designs from federally inspected elevator facilities. Terminal operators in Iowa and Illinois are retrofitting pneumatic systems with hermetic closure mechanisms to maintain compliance.
Germany
Biogas associations are specifying REACH-compliant membranes for maize silage and cereal grain intake across Lower Saxony and Bavaria. ECHA registration requirements are filtering import eligibility toward Central European fabric suppliers. Walter Krause anchors cost leadership through captive membrane production and steel frame fabrication in Thuringia.
Brazil
Matopiba region soybean production growth is outpacing permanent silo construction in Tocantins and western Bahia. ANVISA food-contact certification requirements are shaping polymer fabric import specifications. Input distributors across the Cerrado are positioning chemical-resistant PVC formulations for pre-planting fertilizer storage.
India
Punjab and Haryana rice mills are deploying flat-bottom designs for government procurement buffer stocks requiring six-month holding periods. BIS mechanical testing benchmarks for tensile strength and UV resistance are extending product launch cycles by 8-14 months. Coimbatore textile engineering clusters are concentrating high-tenacity polypropylene weaving capacity.
Ukraine
Black Sea port operators are installing 500-tonne-plus tubular configurations for rapid throughput expansion without permanent construction permits. National agricultural safety inspectors are enforcing hermetic sealing protocols for seed multiplication operations. Odesa and Mykolaiv terminal clusters are prioritizing collapsible textile alternatives to bypass wartime construction material shortages.
Flexible Silos Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supplier categories. The vendor base clusters around membrane manufacturers with captive weaving capacity, steel frame fabricators with galvanizing capabilities, and system integrators with pneumatic filling expertise. Three archetypes dominate: vertically integrated European industrial groups, Asia-Pacific scale fabricators, and niche automation specialists. Consolidation is accelerating through backward integration into polymer resin compounding and geographic expansion into Brazilian and Indo-Gangetic agricultural corridors.
Among Central European industrial groups, Walter Krause exemplifies the membrane-to-frame integration archetype. Coima Group anchors Mediterranean positioning through specialized coating formulations. Pneu Powders Systems occupies the automation-integration tier, representing technical differentiation through pneumatic system compatibility. These three players collectively illustrate how competitive positioning separates material science capabilities, regional regulatory compliance, and bulk handling system interoperability.
| Leading Market Players |
|---|
| Walter Krause |
| Coima Group |
| Pneu Powders Systems |
| Palamatic Process |
| Ambros Schmelzer |
| CEPI |
| Siloanlagen Achberg |
| Powder DS |
| Akkaya |
| Others |
Supply & Pricing Matrix
Polypropylene resin volatility tied to naphtha and propylene markets compresses margin predictability for fabric manufacturers while simultaneously widening spreads between certified REACH-compliant membranes and uncertified alternatives. This feedstock instability forces buyers toward long-term offtake contracts with Central European weavers who maintain captive resin compounding capabilities.
Pricing Analysis
The technology-generation pricing gap separates high-tenacity polypropylene woven fabrics exceeding 1,500 N/5cm tensile strength from lower-grade polyethylene alternatives and emerging biodegradable polymer formulations. Pricing stratifies across premium, standard, and economy tiers based on REACH registration status and UV resistance certification grade. Cost compression in the economy tier is intensifying because Brazilian and Indian buyers are consolidating procurement through cooperative buying pools. Grain storage cooperatives in the Indo-Gangetic Plain exhibit the highest price sensitivity, while seed multiplication operations in Argentina's Pampas tolerate premium pricing for complete discharge capabilities.
Supply Chain Analysis
Contract manufacturing concentration rests with Thuringia-based membrane weavers, Coimbatore textile engineering clusters, and Hebei province steel galvanizing facilities. Geographic supply concentration draws from Germany, India, and China. Raw material dependencies center on polypropylene resin, galvanized structural steel, and PVC coating compounds. Single-source vulnerability in China's Hebei province for galvanized frame components creates chokepoint exposure for European assemblers. Distribution runs through agricultural cooperative buying pools and bulk handling system integrators rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flexible silos market sits in early-cycle expansion as bioenergy feedstock security mandates across the EU and Brazil outpace permanent infrastructure construction capacity.
For Market Incumbents: Entrench cost leadership through backward integration into high-tenacity polypropylene weaving and captive steel frame galvanizing. Walter Krause's Thuringia-based membrane-to-frame integration provides the defensive template. Prioritize REACH registration maintenance as ECHA disclosure requirements filter import eligibility toward certified suppliers. For New Entrants and Emerging Players: Establish a beachhead in Brazilian Cerrado fertilizer storage applications where ANVISA certification requirements have delayed incumbent penetration. Target PVC-coated fabric formulations for ammonium nitrate and urea containment in Matopiba region input distribution. Pursue pneumatic filling system integration partnerships to differentiate from commodity membrane suppliers. For Investors and Strategic Acquirers: EU Green Deal extended producer responsibility mandates reshape the acquisition landscape toward suppliers with recyclable polymer recovery programs. The five-to-ten-year viability window favors membrane manufacturers with captive weaving capacity and regional regulatory compliance infrastructure. Monitor biodegradability mandate implementation timelines as the inflection signal for material substitution premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Compounding | Captive resin supply insulates Walter Krause from naphtha price volatility in Central European markets. |
| REACH-Compliant Membrane Certification | ECHA registration accelerates supplier qualification timelines for German biogas association procurement. |
| Pneumatic Filling System Integration | Pneu Powders Systems' automated bulk handling compatibility commands technical niche premiums. |
| PVC-Coated Fabric Formulation Expansion | Chemical resistance specifications for Brazilian ammonium nitrate storage unlock margin pools above grain applications. |
| Biodegradable Polymer R&D Partnership | EU Green Deal mandates position recyclable recovery programs for future regulatory advantage. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, BIS mechanical testing records, and SEC filings from listed agricultural equipment manufacturers. Primary interviews engaged membrane production managers, agricultural cooperative procurement leads, bioenergy facility operations directors, and steel frame galvanizing plant engineers. Secondary validation drew from ECHA REACH registration databases, EPA grain handling facility inspection reports, and ANVISA food-contact certification filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs include product type deployment velocity, material substitution patterns under evolving biodegradability mandates, and end-user industry procurement consolidation trends. The analytical framework models capacity utilization, chemical compatibility requirements, and regional regulatory cluster adoption curves throughout the forecast period. CAGRs were derived from segment-level volume trajectories and value-per-ton pricing dynamics. Industry-specific inputs incorporate bioenergy feedstock security inventory cycles and double-cropping intensity indices for rice-wheat systems.
Sensitivities concentrate around polypropylene resin price volatility, BIS certification timeline extensions, and wartime construction material shortages affecting Black Sea port infrastructure deployment. Forecasts reflect assumptions regarding regulatory implementation cadence and cooperative buying pool consolidation. Quarterly review of ECHA substance restriction proposals and Brazilian ANVISA certification queue lengths is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Stock Tanks Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Air Seeder Market