
 Global Subsoiler Market | 2026-2036
Global Subsoiler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subsoiler Market Outlook
Skilled tractor-operator shortages across the North American farm belt is unwinding seasonal equipment utilization rates and pushing buyers toward automated hydraulic systems. John Deere leverages its precision agriculture ecosystem to bundle subsoilers with telemetry-enabled tractors. LEMKEN GmbH & Co. KG anchors its position through German-engineered multi-bottom configurations optimized for heavy clay soils. Kverneland Group competes via Scandinavian-designed ripper variants built for shallow draft applications on rented farmland.
A subsoiler is a deep tillage implement featuring curved or straight shanks that fracture compacted soil layers at depths typically exceeding 30 centimeters without inverting the topsoil, thereby improving water infiltration and root penetration for subsequent crops. The implement operates through high-strength alloy steel construction and replaceable wear points to endure abrasive soil conditions across thousands of hectares. Multi-bottom subsoilers lead volume sales among broadacre grain operations where field efficiency metrics dominate procurement decisions. Automated technology variants represent the fastest-expanding segment as ISO 11783-compatible controls enable variable-depth operation mapped to real-time soil compaction sensors. Traditional mechanical systems still occupy substantial share in developing markets where capital constraints limit hydraulic upgrade cycles.
EPA agricultural equipment emissions standards in the United States and EU F-Gas Regulation governing hydraulic system refrigerants are tightening compliance requirements for subsoiler-tractor integration packages. Brazil's national agricultural regulator and India's BIS tillage equipment standards are converging on shank fatigue-testing protocols that favor certified manufacturers over unbranded fabricators. Stakeholders must monitor soil carbon credit program eligibility rules, as emerging verification frameworks could restrict qualifying tillage practices and reshape equipment specification priorities across major grain-producing regions.
Market Dynamics
Precision agriculture adoption is compressing equipment replacement cycles across broadacre grain operations, forcing manufacturers to integrate ISO 11783-compatible controls and real-time soil sensing into subsoiler-tractor bundles.
Growth Catalysts
- EU Green Deal soil mandates:Member states are rewriting tillage equipment specifications to prioritize soil health outcomes, creating specification pull for deep-tillage implements that minimize topsoil inversion.
- Brazilian cerrado compaction protocols:Deep tillage requirements in Mato Grosso's soybean belt are standardizing subsoiler deployment as a prerequisite for yield recovery on degraded oxisols.
- Automated hydraulic systems:Skilled tractor-operator shortages across the North American farm belt are accelerating demand for automated depth-control subsoilers that reduce labor dependency.
Market Restraints
- High-strength alloy steel volatility:Abrasion-resistant shank and wear-point materials face input cost pressure from mining supply concentration in select geographies.
- Capital intensity of hydraulic upgrades:Smallholder operations in developing markets face structural barriers to migrating from mechanical to automated subsoiler systems.
- F-Gas Regulation compliance friction:EU hydraulic system refrigerant standards are tightening integration requirements for subsoiler-tractor packages sold into member states.
Strategic Opportunities
- Soil carbon credit eligibility frameworks:Emerging verification protocols in North America and Europe may restrict qualifying tillage practices, favoring certified subsoiler specifications.
- India BIS tillage standards convergence:Shank fatigue-testing protocols are elevating certified manufacturers above unbranded fabricators in a historically price-driven market.
- Variable-depth sensor convergence:Real-time compaction mapping combined with GPS-guided hydraulic control creates premium positioning for telemetry-integrated subsoiler systems.
Industry Challenges
- Skilled operator scarcity:Seasonal equipment utilization rates are unwinding across the North American farm belt as experienced tractor operators exit the workforce.
- Multi-system integration complexity:ISO 11783 compatibility requirements are extending certification timelines for subsoiler manufacturers targeting precision agriculture bundles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subsoiler Market |
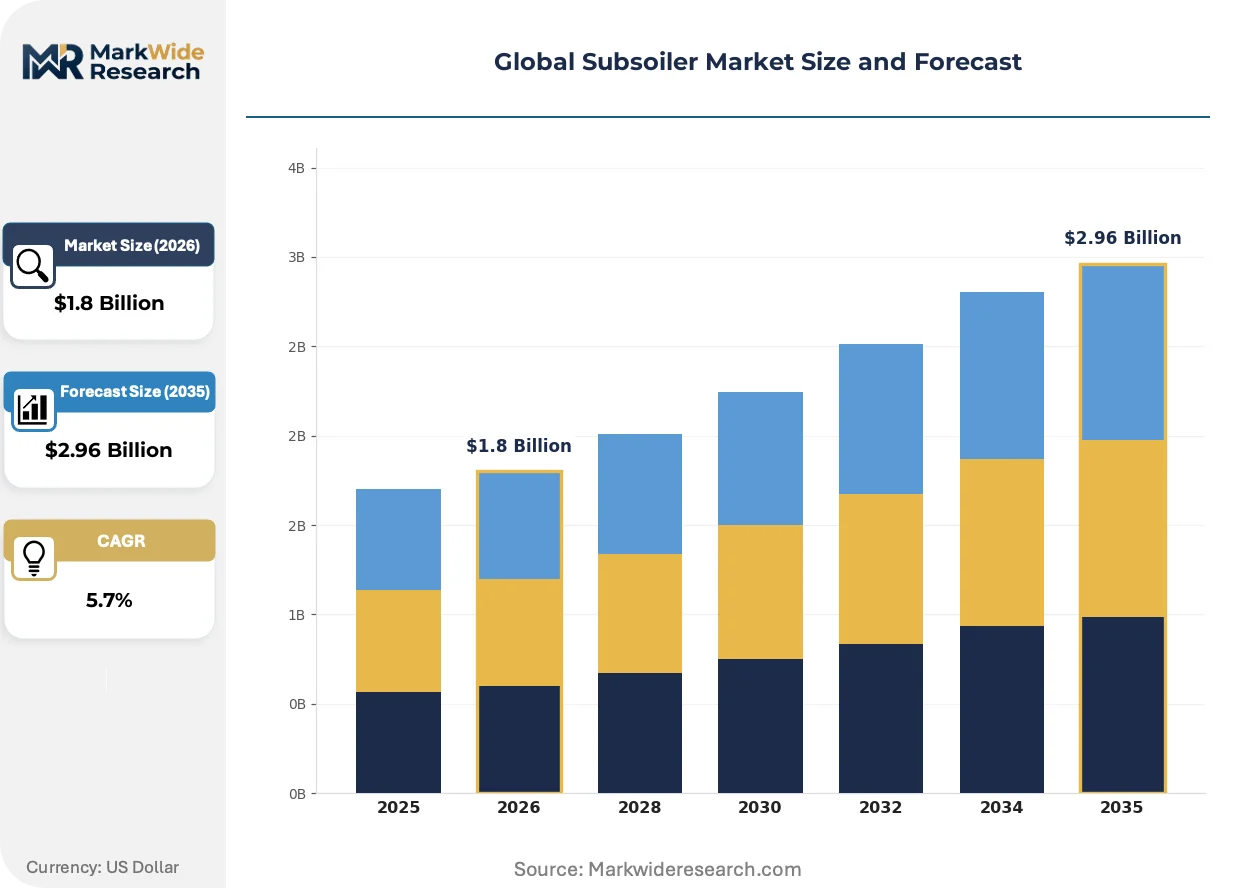
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Bottom, Multi-Bottom, Ripper, Combination Application: Agriculture, Landscaping, Construction, Land Reclamation End User: Farmers, Contractors, Government, NGOs Technology: Traditional, Hydraulic, Mechanized, Automated |
| Companies Covered | John Deere, LEMKEN GmbH & Co. KG, Landol Company, LLC, LAFORGE Groupe, Maschio Gaspardo S.p.A., Rome Plow Equipment Co., LLC, Great Plains, Orthman, Kverneland Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subsoiler Market Strategic Shifts
Subsoiler technology trajectories are diverging between premium automated systems and cost-optimized mechanical variants, with regulatory pressure and labor scarcity determining which path dominates in each geography.
Variable-depth operation mapped to real-time soil compaction sensors is fragmenting the traditional subsoiler category. Large-scale grain operations in Brazil and the United States are adopting ISO 11783-compatible controls at accelerating pace. This capability split is compressing mid-tier mechanical offerings while expanding the premium automated segment.
EPA agricultural equipment emissions standards are tightening subsoiler-tractor integration requirements in the United States. Engine tier compliance is forcing manufacturers to bundle tillage implements with certified power units rather than selling standalone attachments. The North American broadacre segment is absorbing these compliance costs through extended financing structures.
Equipment-as-service models are emerging among precision agriculture adopters who prefer operational expenditure over capital deployment. Dealer networks in Germany and the Netherlands are piloting subscription-based subsoiler access with bundled maintenance. This shift is most visible in rented farmland operations where equipment utilization uncertainty previously discouraged ownership.
Global Subsoiler Market Segmentation
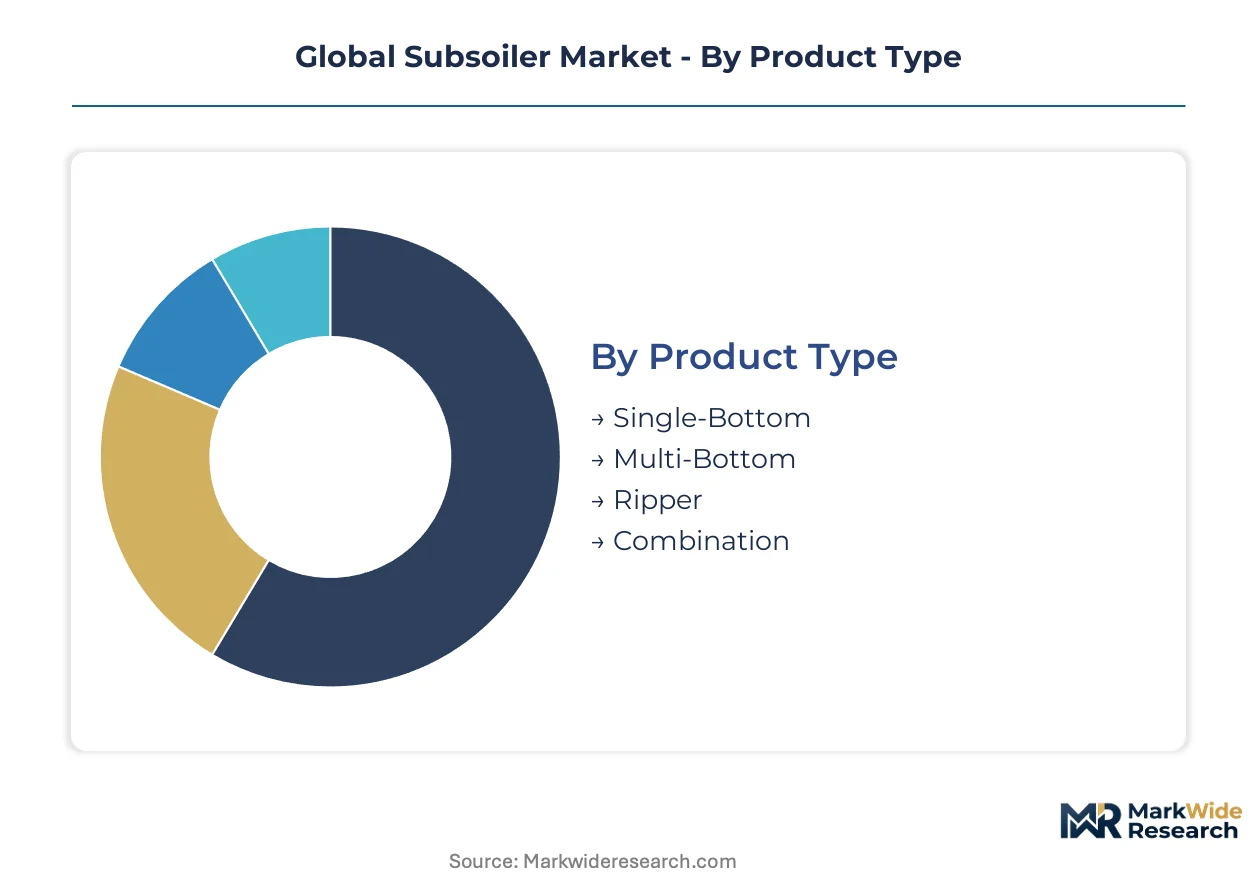
Subsoiler procurement patterns diverge sharply across operator scale and soil conditions, with precision agriculture bundles reshaping specification priorities among large grain operations while mechanical systems retain dominance in developing markets.
Product Type:
EU F-Gas Regulation compliance costs and ISO 11783 certification requirements are fragmenting manufacturer portfolios between premium automated configurations and cost-optimized mechanical variants.
- Multi-Bottom:Configurations with five to eleven shanks dominate broadacre grain operations where field efficiency metrics determine procurement decisions. Brazil's Mato Grosso soybean belt and the US Corn Belt concentrate replacement demand as deep tillage protocols combat compacted oxisols and glacial till soils.
- Single-Bottom:Compact units with one to three shanks serve specialty crop operations and vineyard renovation where maneuverability outweighs throughput. Adoption concentrates in France's Burgundy wine region and Italy's Emilia-Romagna vegetable belt where tight row spacing limits implement width.
- Ripper:Straight-shank variants engineered for shallow draft applications on rented farmland where capital recovery cycles are compressed.
- Combination:Integrated subsoiler-cultivator systems reduce pass counts in Germany's heavy clay regions but face higher certification burdens under EU machinery directives.
Established volume favors Multi-Bottom configurations; emerging adoption favors Combination systems as fuel efficiency regulations tighten.
Application:
Soil carbon credit eligibility frameworks in North America and Europe are restricting qualifying tillage practices, elevating certified specifications in carbon-conscious procurement.
- Agriculture:Deep tillage for yield recovery on degraded soils accounts for dominant equipment deployment. India's BIS tillage standards convergence is elevating certified manufacturers above unbranded fabricators in a historically price-driven market.
- Land Reclamation:Post-mining restoration and wetland rehabilitation require specialized shank configurations for extreme compaction. Australia's coal seam gas rehabilitation projects and Canadian oil sands reclamation drive specification innovation for abrasive subsoil conditions.
- Landscaping:Golf course renovation and urban green space preparation favor compact tractor-mounted units.
- Construction:Site preparation and utility trench backfill compaction remediation represent episodic demand with irregular replacement cycles.
Procurement volume clusters in Agriculture; Land Reclamation exhibits the steepest expansion trajectory as environmental remediation obligations intensify.
End User:
Capital intensity barriers and financing access shape distinct specification tiers across operator categories.
- Farmers:Owner-operators dominate volume demand, with large-scale grain producers in Brazil and the United States absorbing precision agriculture bundles through extended financing structures.
- Contractors:Custom tillage service providers prioritize equipment durability and rapid field turnaround over technology integration. Seasonal utilization pressure in Ukraine's black earth region and Argentina's pampas drives wear-point standardization across mixed fleets.
- Government:Public land management agencies in Australia and South Africa specify corrosion-resistant coatings for conservation tillage programs.
- NGOs:Development agriculture projects in sub-Saharan Africa face structural constraints migrating from mechanical to hydraulic systems.
Contractor procurement is climbing the fastest as farm consolidation expands outsourced tillage services.
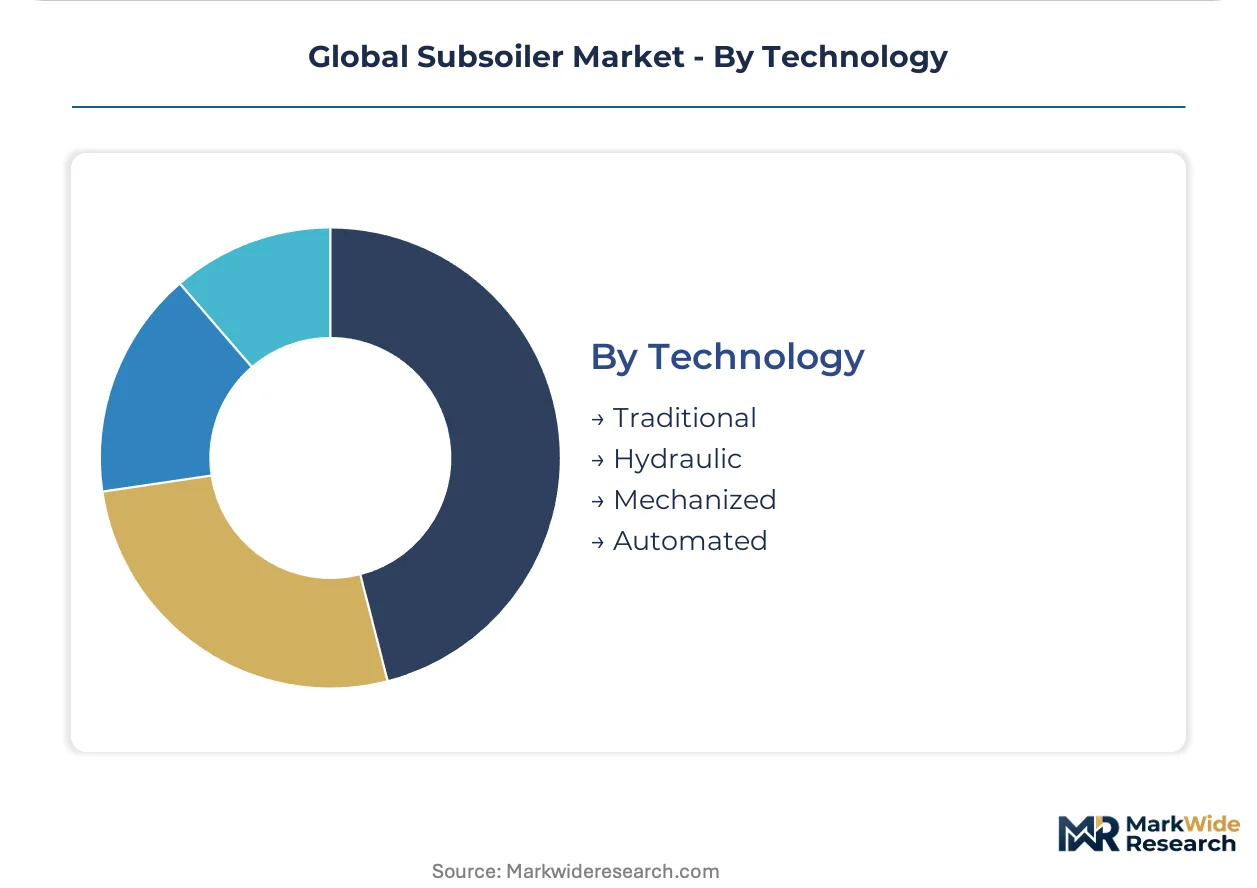
Technology:
Skilled tractor-operator shortages across the North American farm belt are compressing mid-tier mechanical offerings while expanding premium automated positioning.
- Automated:ISO 11783-compatible controls with variable-depth operation mapped to real-time soil compaction sensors represent technology leadership. John Deere leverages its precision agriculture ecosystem to bundle telemetry-enabled configurations with hydraulic depth adjustment.
- Hydraulic:Automated depth-control systems reduce labor dependency in Germany's sugar beet regions and the Netherlands' potato belt where operator scarcity constrains seasonal field windows.
- Mechanized:Three-point hitch mechanical systems retain substantial share in developing markets where capital constraints limit upgrade cycles.
- Traditional:Fixed-depth mechanical units persist in smallholder operations across India's Indo-Gangetic Plain and China's North China Plain.
Mechanized systems retain installed base dominance; automated configurations gain share fastest as precision agriculture adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Brazilian markets where precision agriculture bundles command premiums, while Indian and Chinese buyers face structural cost compression from unbranded fabricators.
United States
EPA agricultural equipment emissions standards and skilled tractor-operator shortages are accelerating automated hydraulic adoption across the Corn Belt. The USDA conservation programs in Iowa and Illinois subsidize deep tillage equipment for soil health outcomes. John Deere's precision agriculture ecosystem dominates specification-setting in Moline, Illinois, where telemetry-enabled tractor-subsoiler bundles originate.
Germany
EU F-Gas Regulation compliance costs and the EU Green Deal soil mandates are reshaping tillage equipment specifications toward low-disturbance deep tillage. LEMKEN GmbH & Co. KG anchors German-engineered multi-bottom configurations from Alpen, North Rhine-Westphalia, optimized for heavy clay soils across the EU sugar beet belt.
Brazil
Deep tillage protocols in Mato Grosso's soybean belt standardize subsoiler deployment on compacted cerrado oxisols. ANVISA and the national agricultural regulator are converging on shank fatigue-testing protocols that favor certified manufacturers. Equipment demand clusters around Rondonópolis where yield recovery on degraded soils drives replacement cycles.
India
BIS tillage equipment standards are elevating certified manufacturers above unbranded fabricators in the Indo-Gangetic Plain. Smallholder capital constraints limit hydraulic upgrade cycles, preserving mechanical system dominance. Punjab and Haryana's wheat-rice rotation generates seasonal compaction remediation demand for three-point hitch units.
Australia
Coal seam gas rehabilitation projects and environmental remediation obligations drive specialized shank innovation for abrasive subsoil conditions. The country's national agricultural regulator specifies corrosion-resistant coatings for conservation tillage programs. Western Australia's Pilbara region demands extreme-duty configurations for post-mining land restoration.
Global Subsoiler Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision agriculture integrators occupying premium positioning while regional fabricators compete on mechanical simplicity. The market structure splits between consolidated tractor-OEM bundlers and fragmented implement specialists. Three archetypes dominate: precision ecosystem integrators, German-engineered durability specialists, and cost-optimized regional fabricators. Competitive moves center on ISO 11783 certification races and extended financing structures for bundled equipment packages.
Among precision ecosystem integrators, John Deere exemplifies the telemetry-enabled bundling archetype. German-engineered durability specialists include LEMKEN GmbH & Co. KG and Kverneland Group, occupying positions defined by soil-specific configuration expertise. Maschio Gaspardo S.p.A. represents the European multi-market specialist archetype with Italian S.p.A. structure.
| Leading Market Players |
|---|
| John Deere |
| LEMKEN GmbH & Co. KG |
| Landol Company, LLC |
| LAFORGE Groupe |
| Maschio Gaspardo S.p.A. |
| Rome Plow Equipment Co., LLC |
| Great Plains |
| Orthman |
| Kverneland Group |
| Others |
Value Chain & Pricing Dynamics
Equipment utilization rates across North American broadacre operations establish minimum efficient scale thresholds that compress price floors for subsoiler manufacturers below fifty thousand annual units. This scale dynamic concentrates supply among German and Brazilian production clusters while forcing smaller fabricators toward unbranded mechanical variants in price-sensitive developing markets.
Pricing Analysis
The customization-premium spread spans forty to sixty percent above base mechanical configurations for ISO 11783-compatible automated systems with telemetry integration. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes: large grain operations in Brazil and the United States absorb premium bundles through extended financing, while Indian and Chinese smallholders drive economy-tier volume. Cost compression in economy mechanical tiers intensifies because unbranded fabricators in the Indo-Gangetic Plain undercut certified manufacturers on shank fatigue-testing compliance. Contractors in Ukraine's black earth region exhibit highest price sensitivity due to compressed capital recovery cycles on rented farmland.
Supply Chain Analysis
Strategic stockpile preferences dominate subsoiler supply chains as seasonal field windows and abrasive soil conditions drive wear-point inventory buffers at dealer networks. High-strength alloy steel supply concentrates in Germany, Sweden, and China, with abrasion-resistant shank materials drawing from mining supply concentration in select geographies. Component dependencies center on hydraulic control systems, GPS guidance modules, and replaceable wear-point alloys. Single-source vulnerability in specialty steel grades creates procurement risk for European manufacturers under EU F-Gas Regulation compliance timelines. Distribution runs through OEM-authorized dealer networks in developed markets and regional fabricator-direct channels in price-driven developing economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 11783 certification capacity and precision agriculture integration expertise constitute scarce assets that fragment competitive advantage between telemetry-enabled bundlers and mechanical cost leaders. The capability gap in real-time soil sensing integration creates asymmetric positioning opportunities across buyer segments.
For Market Incumbents: Compound defensive positioning through captive supply of high-strength alloy wear-points and accelerated ISO 11783 certification timelines for subsoiler-tractor bundles. Threats from emerging precision agriculture entrants and skilled operator scarcity demand vertical integration into hydraulic control manufacturing. Certification investment in India's BIS tillage standards and Brazil's ANVISA protocols anchors channel control against unbranded fabricators.
For New Entrants and Emerging Players: Aftermarket telemetry retrofit kits for installed mechanical subsoilers represent underserved white space where incumbents under-serve capital-constrained smallholders. India's Punjab and Haryana wheat-rice belt offers most penetrable geography given BIS standards elevation and mechanical system replacement demand. Go-to-market through regional dealer networks with subscription-based equipment-as-service models reduces upfront capital barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision ecosystem integrators with ISO 11783-compliant control architectures over pure-play mechanical fabricators. Long-term viability across the projection horizon rests on telemetry-enabled variable-depth capabilities and soil carbon credit program eligibility. Acquisition targets with certified shank fatigue-testing protocols and established ANVISA or BIS registrations command premium positioning. Watch soil carbon credit verification framework adoption rates in North America and Europe as inflection indicator for specification demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11783 Certification Acceleration | Enables precision agriculture bundling with John Deere and LEMKEN tractor ecosystems. |
| Backward Integration into Alloy Steel | Captures wear-point margin and insulates against mining supply concentration volatility. |
| Equipment-as-Service Launch | Converts capital-constrained renters in Germany and Netherlands to recurring revenue. |
| India BIS Certification Investment | Elevates positioning above unbranded fabricators in Punjab and Haryana procurement. |
| Soil Carbon Credit Program Alignment | Qualifies specifications for emerging North American and European verification frameworks. |
Study Parameters
The analysis maps automated hydraulic, mechanized, and traditional mechanical subsoiler configurations, each validated through equipment procurement directors at broadacre grain operations, aftermarket service heads at dealer networks, and regulatory affairs leads at certification bodies. Primary interviews with maintenance directors, plant engineers at alloy steel foundries, and OEM procurement teams combined with secondary validation through customs/trade data, SEC 10-K filings from listed agricultural equipment manufacturers, and ANVISA regulatory databases. Bottom-up unit shipment estimates triangulated against top-down equipment replacement cycle modeling across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs through cross-referencing with machinery registration databases and dealer inventory disclosures. The analytical framework spans product type, application, end user, and technology dimensions across the projection horizon, with CAGRs derived from equipment replacement intensity indices and precision agriculture adoption curves. Industry-specific forecast inputs include seasonal utilization rate compression in North America and EU Green Deal soil mandate implementation timelines.
Forecasts assume regulatory continuity in EPA emissions standards, EU F-Gas Regulation, and India BIS tillage equipment protocols; material policy shifts would require re-modeling certification burden impacts on manufacturer cost structures. Revision becomes warranted when soil carbon credit verification adoption crosses fifty percent penetration in major grain-producing regions or when alloy steel supply concentration triggers sustained input cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
United States Grain Storage Silos Market
Agricultural Equipment
Horse Drawn Farming Equipment Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Fly Trap Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Flexible Silos Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Agriculture Container and Tank Cleaning Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Global Rice Transplanter Market