
 Chemochromic Material Market | 2026-2036
Chemochromic Material Market Size, Share, and Industry Trends Forecast 2026-2036
Chemochromic Material Market Insights
Pharmaceutical labeling is realigning chemochromic material procurement toward temperature-indicating solutions that verify cold chain integrity. Merck KGaA leverages its pigment synthesis heritage to dominate high-purity dye production for medical applications. Milliken & Company sustains competitive positioning through textile-focused thermochromic polymer development. OliKrom anchors its presence in defense and aerospace with irreversible hydrochromic coatings for moisture detection.
Chemochromic materials reversibly or irreversibly change optical properties when exposed to chemical stimuli such as pH shifts, redox reactions, or solvent vapor, with typical response times ranging from milliseconds to several minutes depending on matrix porosity and activator concentration. These materials serve primarily as passive indicators in quality assurance, anti-counterfeiting, and environmental monitoring systems where visual state change replaces electronic sensing. Thermochromic technology leads volume consumption due to mature integration protocols across packaging and textiles, while hydrochromic applications in moisture-sensitive logistics represent the fastest structural expansion. Solvent-based formulations retain margin concentration in security printing despite environmental compliance pressures favoring waterborne polymer alternatives.
EPA guidelines on volatile organic compound emissions constrain solvent-based ink formulations in the United States, pushing reformulation toward compliant polymer carriers. REACH registration requirements in Europe enforce full toxicological disclosure for dye intermediates, elevating compliance costs for imported chemochromic raw materials. FDA 21 CFR regulations for indirect food contact materials limit migratable substance thresholds in packaging applications, directly shaping product qualification pathways. Stakeholders must monitor evolving chemical hazard classifications under ECHA and EPA frameworks to anticipate reformulation mandates before they disrupt qualified material lists.
Market Dynamics
Cold chain integrity mandates from pharmaceutical regulators are compressing qualification timelines for temperature-indicating chemochromic systems, forcing material suppliers to synchronize dye synthesis with packaging line validation protocols.
Growth Catalysts
- REACH Registration:ECHA's full toxicological disclosure requirements for dye intermediates are elevating compliance costs for imported raw materials, advantaging integrated European pigment manufacturers with captive synthesis capabilities.
- Smart Packaging:Food and beverage producers are specifying reversible thermochromic inks for freshness verification, creating pull-through demand for polymer-stabilized leuco dye formulations.
- Germany:Specialty chemical clusters in Ludwigshafen and Leverkusen support integrated development pipelines spanning dye synthesis to coated film production, reducing time-to-market for qualified medical-grade materials.
Market Restraints
- Input Cost Volatility:Spirooxazine and fluoran leuco dye precursors face supply concentration from Chinese intermediate manufacturers, exposing formulators to raw material price swings.
- Technical Limitation:Reversible thermochromic systems exhibit fatigue after 10,000-50,000 thermal cycles, constraining deployment in reusable logistics containers requiring extended service life.
- Regulatory Friction:FDA 21 CFR indirect food contact limits on migratable substances force reformulation of solvent-based security inks, extending product qualification timelines by 12-18 months.
Strategic Opportunities
- India:PLI scheme incentives for domestic pharmaceutical packaging are creating localized demand for temperature-indicating labels, with CDSCO streamlining medical device material approvals.
- Hydrochromic Convergence:Moisture detection coatings for aerospace logistics are integrating with RFID inlays to create dual-mode sensing systems for defense supply chains.
- Waterborne Formulation:EPA VOC emission guidelines are accelerating adoption of aqueous polymer carriers in security printing, opening margin expansion for compliant ink developers.
Industry Challenges
- Formulation Chemistry Expertise:Shortage of specialists in microencapsulation and polymer-dye compatibility is constraining R&D throughput at mid-scale material suppliers.
- Certification Timeline Compression:Pharmaceutical customers are demanding qualified material status within 6-9 months, conflicting with ECHA substance evaluation periods that extend 12-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemochromic Material Market |
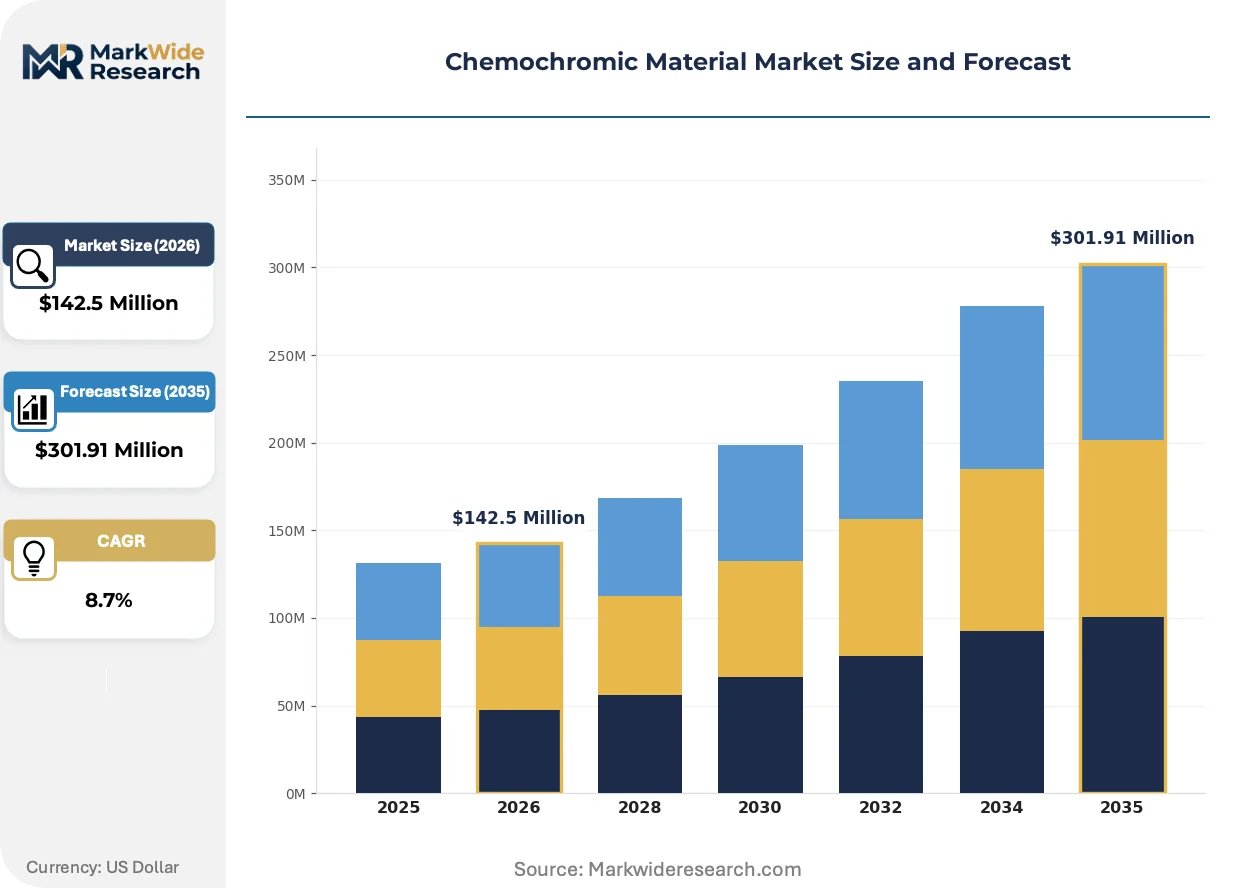
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvents, Polymers, Dyes, Inks Application: Packaging, Coatings, Textiles, Security Features Technology: Electrochromic, Photochromic, Thermochromic, Hydrochromic End User: Consumer Goods, Pharmaceuticals, Automotive, Defense |
| Companies Covered | Merck KGaA, Milliken & Company, Tokuyama Corporation, Flint Group, Chromatic Technologies Inc, OliKrom, QCR Solutions Corp, SpotSee, LCR Hallcrest LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemochromic Material Market Trends and Innovations
Digital printing integration is compressing minimum order quantities for customized chemochromic indicators, while regulatory hazard reclassifications are forcing anticipatory reformulation investments ahead of mandated compliance deadlines.
Microencapsulated leuco dye systems are integrating with UV-curable inkjet platforms to enable on-demand production of temperature-sensitive labels. Pharmaceutical contract packagers in the United States are adopting these systems to reduce inventory obsolescence for SKU-diverse cold chain products. The technology is integrating variable data printing with color-change authentication, collapsing the distinction between functional indicator and brand security element.
REACH candidate list expansions for endocrine-disrupting substances are capturing certain phthalate-based polymer plasticizers used in thermochromic masterbatches. ECHA's 2024-2025 substance evaluation roadmap is forcing reformulation of textile-grade color-change fibers ahead of potential authorization requirements. German chemical distributors are stockpiling legacy formulations while qualifying bio-based alternatives, creating a bifurcated supply environment through the transition window.
Consolidated buying by multinational food retailers is compressing supplier qualification cycles from 18 months to 8-10 months for packaging material categories. Procurement teams at European grocery chains are bundling chemochromic freshness indicators with primary film contracts, displacing independent label converters. Japanese convenience store operators are piloting direct sourcing relationships with dye houses to secure capacity for seasonal promotional packaging with tight launch windows.
Chemochromic Material Market Segmentation
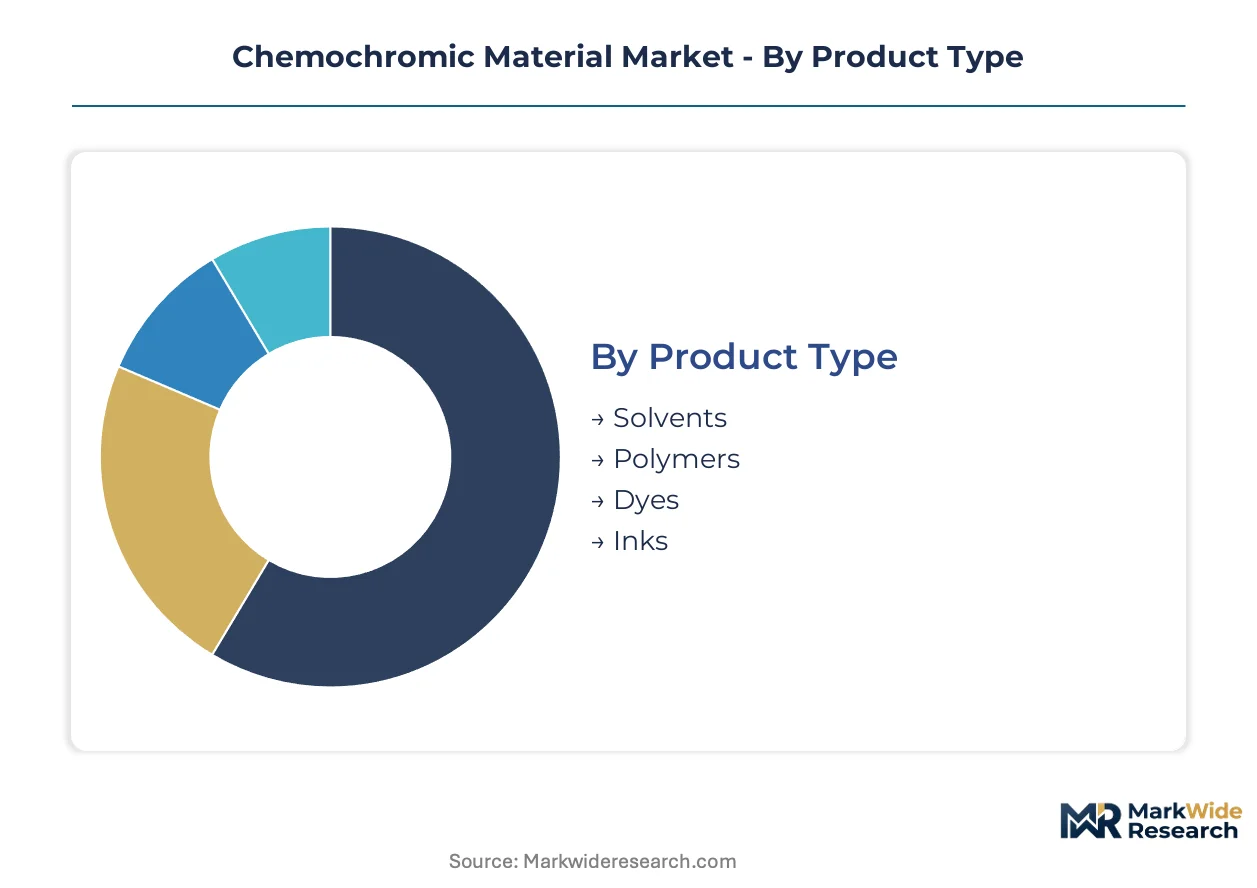
Chemochromic material segmentation reveals distinct integration architectures. Standalone indicator systems dominate commodity applications while embedded formulations penetrate high-value verticals demanding seamless functional integration.
Product Type:
Integration depth separates commodity inputs from formulated systems requiring compounding expertise.
- Solvents:Volatile organic carriers dissolve leuco dye precursors for security printing applications. EPA emission guidelines are accelerating reformulation toward compliant alternatives in the United States.
- Polymers:Polymer matrices stabilize reversible thermochromic systems through microencapsulation, extending cycle life in reusable logistics containers. REACH candidate list expansions for phthalate plasticizers are forcing anticipatory reformulation investments across European textile supply chains.
- Dyes:Spirooxazine and fluoran leuco dye precursors face supply concentration from Chinese intermediate manufacturers.
- Inks:UV-curable inkjet platforms integrate microencapsulated systems for on-demand pharmaceutical label production.
Thermochromic dyes lead volumes today; polymer-stabilized formulations are gaining share fastest.
Application:
Cost stratification separates premium authentication systems from mass-market freshness indicators.
- Packaging:Food and beverage producers specify reversible thermochromic inks for freshness verification. Japanese convenience store operators pilot direct dye house relationships for seasonal promotional capacity.
- Coatings:Irreversible hydrochromic moisture detection coatings serve aerospace logistics with dual-mode RFID integration. Defense supply chain mandates in Germany and the United States anchor procurement concentration.
- Textiles:ECHA substance evaluation roadmaps force reformulation of color-change fibers ahead of potential authorization requirements.
- Security Features:Variable data printing collapses functional indicator and brand authentication into single substrate layers.
Packaging applications dominate current consumption; coating systems for moisture detection are climbing the fastest.
Technology:
Maturity curves separate established thermochromic protocols from emerging hydrochromic deployment.
- Electrochromic:Electrically activated color-change systems require conductive substrates and power integration, constraining deployment to premium automotive and architectural glass segments.
- Photochromic:UV-triggered transitions serve eyewear and architectural applications with reversible darkening functionality.
- Thermochromic:Temperature-activated systems achieve millisecond response times through optimized matrix porosity. Pharmaceutical cold chain integrity mandates compress qualification timelines for leuco dye formulations.
- Hydrochromic:Moisture-responsive coatings exhibit irreversible state change upon water contact. OliKrom anchors defense and aerospace presence with specialized formulations for mission-critical logistics.
Thermochromic technology commands the largest installed base; hydrochromic systems show the steepest expansion trajectory.
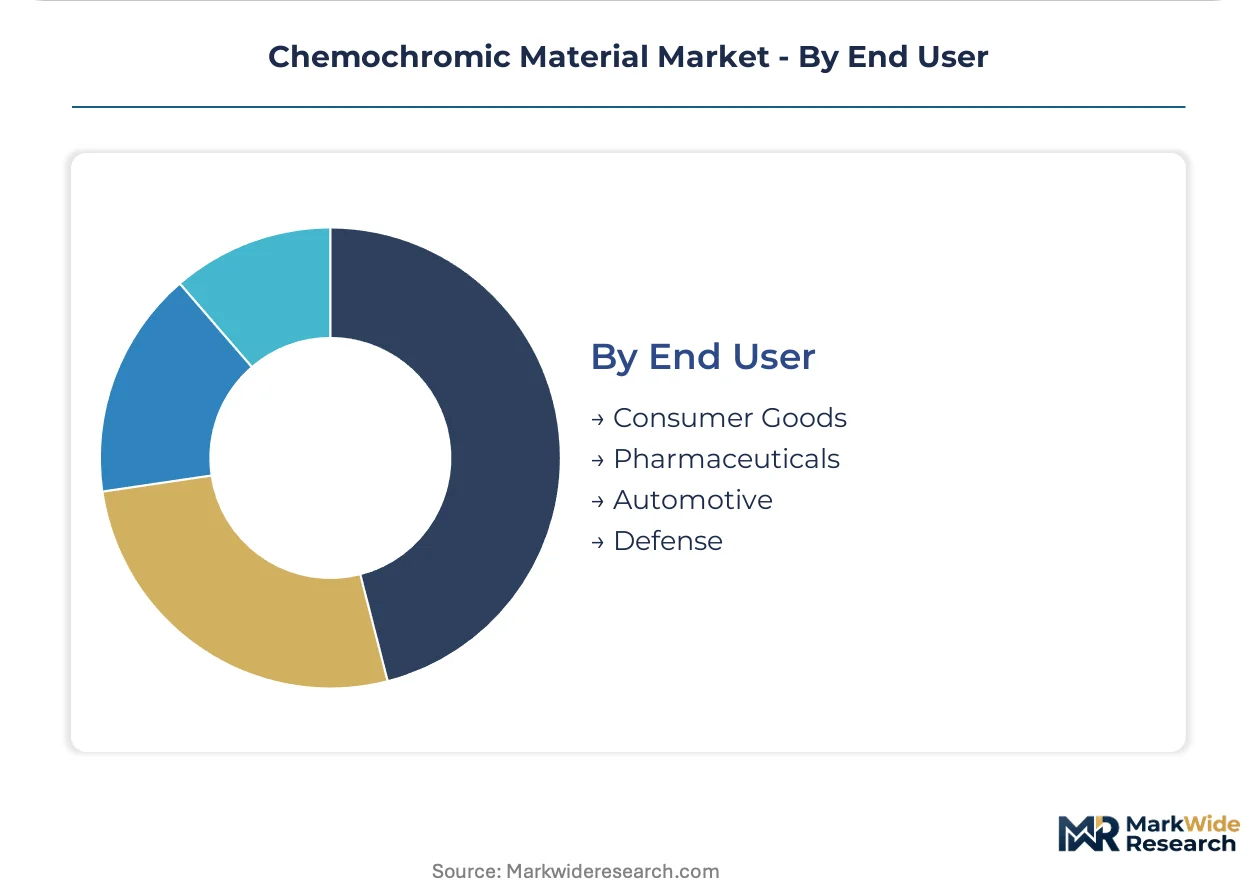
End User:
Customer sophistication determines specification stringency and qualification cycle duration.
- Consumer Goods:Consolidated multinational food retailers compress supplier qualification cycles from eighteen months to eight-to-ten months. European grocery procurement teams bundle freshness indicators with primary film contracts.
- Pharmaceuticals:FDA 21 CFR indirect food contact limits on migratable substances extend product qualification timelines by twelve-to-eighteen months for solvent-based security inks. Merck KGaA leverages pigment synthesis heritage for high-purity medical-grade production.
- Automotive:Interior temperature-indicating applications demand thermal cycle durability exceeding fifty thousand transitions.
- Defense:Moisture detection mandates for aerospace logistics integrate with supply chain visibility platforms.
Pharmaceutical applications generate the highest value per kilogram; defense procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as formulators migrate toward jurisdictions with streamlined chemical registration protocols. European REACH compliance costs are pushing intermediate synthesis toward Asian manufacturing bases, while end-market proximity requirements anchor final formulation in consuming regions.
United States
Pharmaceutical cold chain mandates from FDA are compressing qualification timelines for temperature-indicating labels. EPA volatile organic compound emission guidelines constrain solvent-based security ink production, accelerating waterborne polymer carrier adoption. Specialty chemical clusters in the Boston-Cambridge corridor support integrated medical-grade material development pipelines.
Germany
Automotive interior applications demand thermochromic systems exceeding fifty thousand thermal cycle durability thresholds. ECHA substance evaluation roadmaps for endocrine-disrupting substances force anticipatory reformulation of textile-grade color-change fibers. Ludwigshafen and Leverkusen chemical clusters reduce time-to-market through captive dye synthesis to coated film production integration.
Japan
Convenience store operators pilot direct dye house relationships to secure capacity for seasonal promotional packaging with compressed launch windows. METI standards for functional materials guide quality certification protocols for export-oriented production. Kansai and Chubu industrial corridors concentrate microencapsulation expertise for polymer-stabilized leuco dye systems.
China
Spirooxazine and fluoran leuco dye precursor manufacturing concentrates in coastal chemical provinces, exposing global formulators to input cost volatility. NMPA pharmaceutical packaging regulations align with international cold chain integrity standards for export-oriented production. Yangtze River Delta clusters integrate intermediate synthesis with downstream ink formulation for domestic security printing demand.
India
PLI scheme incentives for domestic pharmaceutical packaging create localized demand pull for temperature-indicating label materials. CDSCO streamlines medical device material approval pathways to accelerate supplier qualification cycles. Gujarat and Maharashtra chemical corridors attract backward integration investments from multinational formulators seeking regional supply security.
Chemochromic Material Market Competitive Landscape
Backward integration into captive dye synthesis dominates the current landscape as formulators seek insulation from Chinese intermediate price volatility. The vendor base stratifies across three tiers: integrated pigment manufacturers with synthesis heritage, specialized polymer compounders with microencapsulation expertise, and regional ink formulators serving security printing niches. Capacity expansion in aqueous polymer carriers and strategic partnerships for RFID-hydrochromic convergence represent the primary competitive vectors reshaping positioning.
Among European-integrated chemical conglomerates, Merck KGaA exemplifies the pigment synthesis archetype with captive high-purity production capabilities. Milliken & Company represents the polymer-focused compounder model with textile-centered thermochromic development heritage. OliKrom occupies the specialized coating specialist position with defense-aerospace moisture detection applications. These three anchors illustrate how competitive positioning stratifies by integration depth and end-market specialization rather than scale alone.
| Leading Market Players |
|---|
| Merck KGaA |
| Milliken & Company |
| Tokuyama Corporation |
| Flint Group |
| Chromatic Technologies Inc |
| OliKrom |
| QCR Solutions Corp |
| SpotSee |
| LCR Hallcrest LLC |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap German dye houses anchor supply discipline through captive synthesis of leuco dye precursors, translating upstream control into pricing power against Chinese intermediate volatility while pharmaceutical qualification timelines compress margin flexibility for non-integrated formulators.
Pricing Analysis
Distributor margins for medical-grade thermochromic inks absorb twelve-to-eighteen month FDA qualification delays, compressing net returns for solvent-based security ink specialists. Three-tier pricing structure across pharmaceutical-grade, industrial-grade, and commodity-grade certifications separates Merck KGaA's high-purity positioning from regional ink blenders. Cost compression in textile-grade masterbatches intensifies as ECHA phthalate restrictions force anticipatory reformulation investments. European grocery procurement teams exhibit highest price sensitivity through bundled primary film contracts, while defense aerospace buyers prioritize moisture-detection reliability over unit economics.
Supply Chain Analysis
REACH registration and FDA 21 CFR indirect food contact certification gate entry for pharmaceutical packaging applications, extending supplier qualification cycles beyond standard chemical procurement timelines. Spirooxazine and fluoran leuco dye precursor manufacturing concentrates in China's coastal chemical provinces, with downstream formulation anchored in Germany, Japan, and the United States. Microencapsulation polymer matrices and UV-curable inkjet carriers constitute critical input dependencies. Single-source vulnerability from Chinese intermediate concentration exposes formulators to raw material price swings. Distribution runs through specialty chemical distributors with technical application support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemochromic material market represents a late-cycle quality story where pharmaceutical cold chain integrity mandates and REACH compliance escalation concentrate procurement among qualified suppliers with captive synthesis heritage.
For Market Incumbents: Extend backward integration into spirooxazine precursor manufacturing to insulate margin structures from Chinese intermediate price volatility. Accelerate aqueous polymer carrier qualification ahead of EPA VOC enforcement timelines. Consolidate microencapsulation expertise through targeted capability acquisition in Kansai and Chubu industrial corridors. For New Entrants and Emerging Players: CDSCO streamlined medical device material approvals in India open a window for temperature-indicating label specialists to establish regional formulation presence. Target Gujarat and Maharashtra chemical corridors for backward integration investments under PLI scheme incentives. Pursue direct sourcing relationships with Japanese convenience store operators bypassing incumbent label converters. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale polymer compounders with microencapsulation expertise but without pharmaceutical qualification heritage. Five-to-ten year viability hinges on successful navigation of ECHA substance evaluation roadmaps and FDA migratable substance thresholds. Monitor REACH candidate list expansions for endocrine-disrupting substances as inflection indicator for reformulation-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Captive supply of spirooxazine intermediates insulates German formulators from Chinese price volatility. |
| Aqueous Polymer Carrier Qualification | EPA VOC compliance opens margin expansion for security printing ink developers in United States. |
| RFID-Hydrochromic Convergence | Dual-mode moisture detection systems penetrate defense aerospace supply chains through OliKrom specialization. |
| Regional Formulation Expansion | PLI scheme incentives in India attract multinational backward integration for pharmaceutical packaging security. |
| Digital Printing Platform Integration | UV-curable inkjet compatibility compresses minimum order quantities for SKU-diverse pharmaceutical contract packagers. |
Research Methodology
Direct dialogue with pigment synthesis directors, pharmaceutical packaging procurement leads, textile R&D managers, and specialty chemical distributors anchored qualitative assessment, cross-referenced with ECHA substance evaluation databases, FDA 21 CFR guidance documents, customs trade flows for leuco dye intermediates, and SEC filings from integrated chemical conglomerates. Bottom-up volume estimates from application-level consumption patterns triangulated against top-down market sizing from production capacity disclosures.
Top-down macroeconomic drivers and bottom-up segment-specific adoption curves converged across the projection horizon. Segmentation dimensions modeled include technology maturity tier, end-use industry vertical, certification grade level, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for qualification timeline compression and reformulation cycle acceleration. Industry-specific inputs incorporated pharmaceutical cold chain mandate expansion rates and ECHA authorization pathway probabilities.
Revisions become necessary when REACH candidate list expansions capture additional polymer plasticizers, EPA VOC thresholds tighten beyond current reformulation trajectories, or Chinese intermediate supply disruptions materialize. A model refresh is warranted upon material change in pharmaceutical regulator cold chain integrity mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Acid Orange Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Organic Pigment Dispersions Market
Dyes and Pigments
Synthetic Dyes Market
Dyes and Pigments
Global Thermochromic Paint Market
Dyes and Pigments
Quinacridone Pigments Market
Dyes and Pigments
Asia-Pacific Pigments Market
Dyes and Pigments
Zinc Oxide Pigments Market
Dyes and Pigments
Basic Violet 10 Market
Dyes and Pigments
Global Paint Pigments Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Indigo Carmine Market
Dyes and Pigments
Pigment Additive Film Market