
 Pearlescent Pigments Market | 2026-2036
Pearlescent Pigments Market Size, Share, and Industry Trends Forecast 2026-2036
Pearlescent Pigments Market Intelligence
The distinction between automotive-grade and cosmetic-grade pigment performance is collapsing as cross-industry technology transfer accelerates. This shift benefits manufacturers with deep research capabilities in synthetic mica substrates. BASF SE leverages its chemical expertise to develop weather-resistant pigments for exterior coatings. Merck KGaA sustains its market position through a portfolio of high-purity effect pigments for the cosmetics industry.
Pearlescent pigments are effect materials composed of platelet-like substrates, such as mica, coated with thin layers of metal oxides. The resulting structure creates color and visual effects through light interference, reflection, and absorption. Synthetic product types are gaining share over natural mica due to superior purity and color consistency. The cosmetics and coatings applications represent the largest demand segments, with the powder form dominating supply chains due to its stability and versatility in formulations.
Regulatory frameworks significantly influence material composition and market access. The EU's REACH regulation governs chemical safety, while the US FDA's rules for color additives and China's NMPA standards for cosmetic ingredients impose strict controls. These regulations shape product development and labeling requirements for manufacturers. The key strategic decision for formulators is balancing the ethical sourcing challenges of natural mica against the performance and cost profile of synthetic alternatives.
Market Dynamics
The central tension shaping the pearlescent pigments market is the regulatory and consumer-driven shift away from natural mica, with its associated ethical sourcing challenges, toward high-performance synthetic alternatives that offer superior purity and consistency for demanding applications.
Growth Catalysts
- Synthetic Mica Innovation:Advances in synthetic fluorphlogopite production yield pigments with exceptional clarity and color fidelity, meeting stringent performance criteria for high-end cosmetics and premium automotive coatings.
- Automotive Sector Demand:The automotive industry's adoption of multi-layer effect coatings for premium vehicle finishes, particularly in manufacturing centers in Germany and Japan, drives significant volume for weather-resistant pigments.
- Personal Care Expansion:Growth in the cosmetics sector across China and India, combined with consumer preference for special effects in makeup, boosts demand for pigments compliant with NMPA and BIS standards.
Market Restraints
- Raw Material Volatility:Price and supply fluctuations for key raw materials, such as high-purity titanium dioxide and iron oxides used for coatings, create cost instability and margin pressure for pigment manufacturers.
- Ethical Sourcing Scrutiny:The use of natural mica is constrained by strict supply chain audits and NGO oversight regarding labor practices in key mining regions like India, increasing compliance costs and reputational risk.
- Competition from Alternative Effects:The development of advanced aluminum, glass-flake, and chromatic pigments offers alternative visual effects, posing a substitution threat in certain automotive and industrial applications.
Strategic Opportunities
- Edible Pigments:Expanding into food and pharmaceutical applications with edible-grade pearlescent pigments that meet stringent FDA and EFSA color additive regulations presents a significant new revenue stream.
- Functional Coatings:Developing pigments with functional properties, such as IR-reflectivity for cool architectural coatings or conductivity for printed electronics, opens new industrial markets beyond purely aesthetic applications.
- Plastics Masterbatch Growth:Increased use of effect pigments in plastics for consumer electronics and packaging in Southeast Asian manufacturing hubs, including Vietnam and Thailand, represents an underpenetrated segment.
Industry Challenges
- Navigating Global Regulatory Divergence:Manufacturers face significant complexity and cost in aligning a single product formulation with divergent chemical registration requirements under EU REACH, US TSCA, and China's MEE regulations.
- Scaling Synthetic Mica Production:The high capital expenditure and deep technical expertise required to construct and operate synthetic mica substrate plants create high barriers to entry and potential production bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pearlescent Pigments Market |
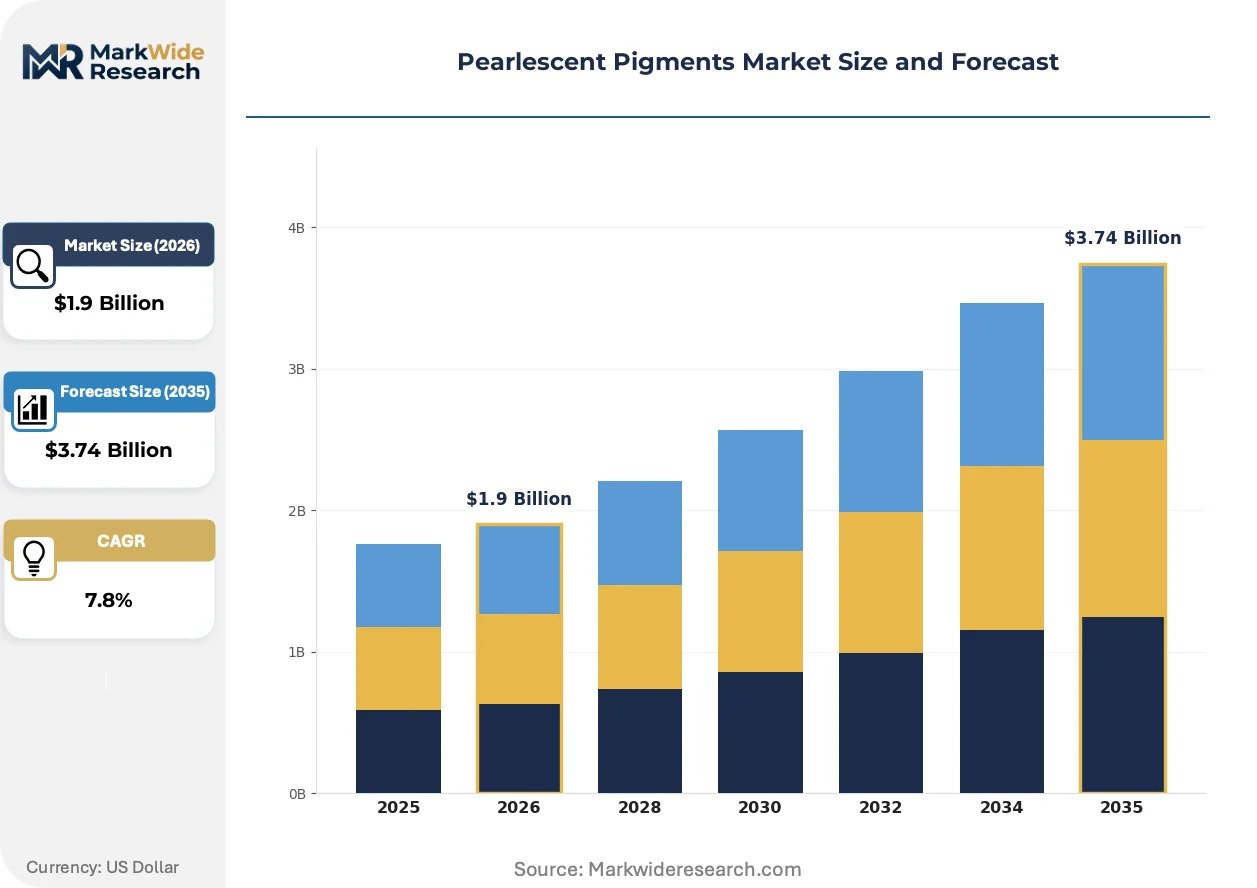
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.74 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Coated, Uncoated Application: Cosmetics, Coatings, Plastics, Printing Inks Form: Powder, Liquid, Paste, Granules End User: Personal Care, Automotive, Consumer Goods, Industrial |
| Companies Covered | BASF SE, Merck KGaA, Sun Chemical Performance Pigments, Fujian Kuncai Material Technology Co., Ltd., Huaian Concord Cosmetics Product Co., Ltd. (Kolortek), Eckart GmbH, Geotech International B.V., RIKA Technology Co., Ltd., Lansco Colors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pearlescent Pigments Market Strategic Shifts & Innovations
Material science advancements are converging with sustainability mandates to guide product development. Innovation is increasingly focused on creating pigments that not only deliver novel visual effects but also comply with a complex web of global chemical safety and ethical sourcing standards.
Synthetic fluorphlogopite, an engineered substrate, offers higher purity, enhanced brightness, and greater sparkle compared to natural mica. The cosmetics and automotive coatings industries are rapidly adopting these advanced substrates for their premium product lines. This technology is supplanting natural mica in high-value applications where color consistency, flawless finish, and transparent sourcing are paramount.
The European Union's REACH regulation imposes stringent data requirements for the registration and evaluation of chemical substances, including all pigment components. This framework drives manufacturers to invest heavily in toxicological testing and documentation, influencing material selection toward better-characterized substances. The coatings sector is most affected, as formulators must ensure every pigment in their portfolio complies with the European Chemicals Agency's registration mandates.
Brand owners in the personal care industry are increasingly prioritizing pigments with documented ethical sourcing and certifications such as vegan or cruelty-free. This consumer-driven preference shifts purchasing decisions away from pure cost considerations toward suppliers who can provide transparent supply chain documentation. This trend is most prominent among indie and premium cosmetic brands in North America and Europe, influencing procurement across the entire value chain.
Pearlescent Pigments Market Segmentation
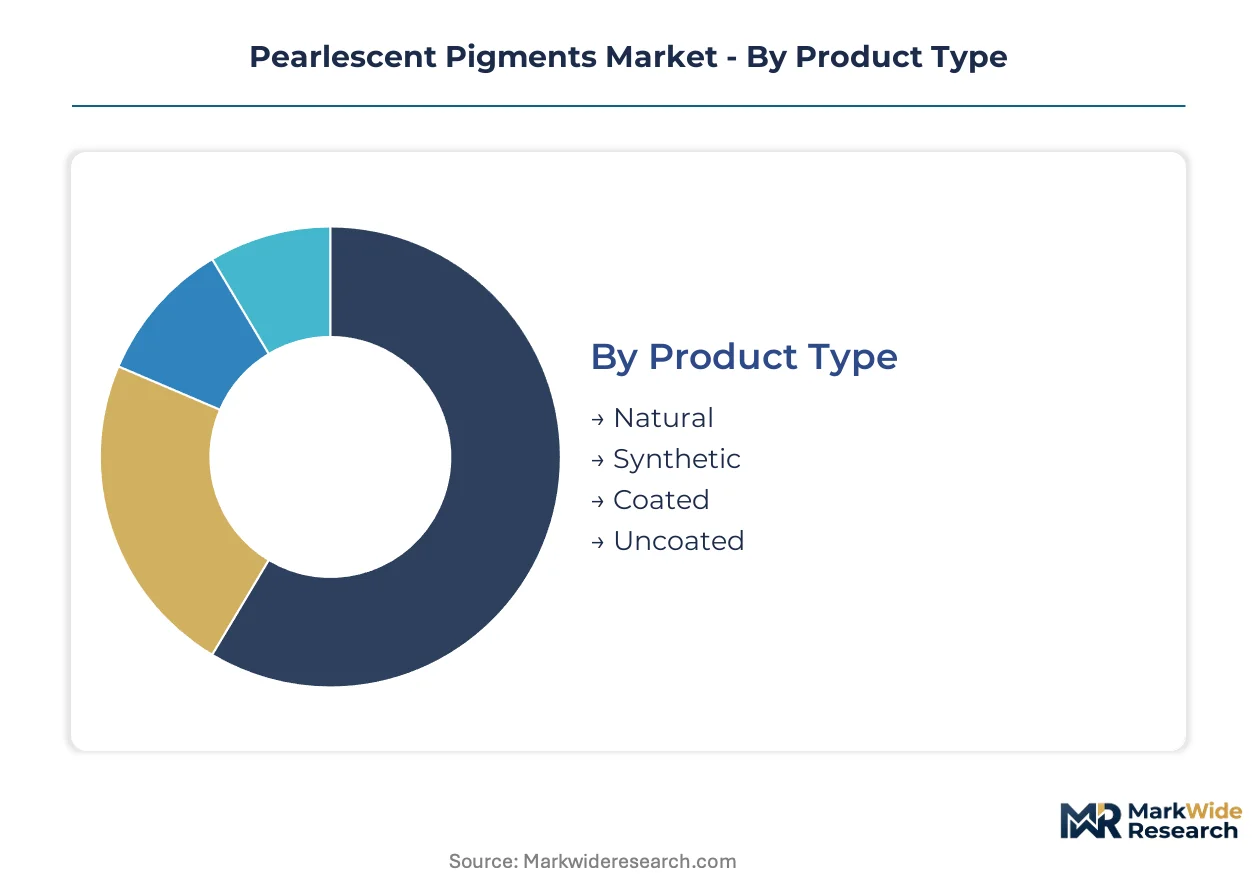
The pearlescent pigments market is delineated by diverse product types, applications, forms, and end-users. Understanding these segments clarifies the varying performance demands and regulatory landscapes influencing market participants. Strategic decisions for formulators often hinge on balancing cost, performance, and compliance within specific segment requirements.
Product Type:
The product type segment faces significant substitution pressure, particularly as advanced synthetic alternatives displace traditional natural mica in premium applications. This shift is driven by performance advantages and ethical sourcing concerns.
- Synthetic:Engineered substrates like synthetic fluorphlogopite offer superior purity, enhanced brightness, and greater color consistency. Demand concentrates in high-end cosmetics and automotive coatings, where flawless finish and consistent quality are critical performance criteria.
- Natural:Derived from muscovite mica, these pigments are valued for their cost-effectiveness but face scrutiny over ethical sourcing challenges. Applications remain strong in industrial coatings and lower-cost cosmetic formulations, particularly in regions with less stringent supply chain oversight.
- Coated:These pigments feature a metal oxide layer applied to a substrate, enhancing color and effect.
- Uncoated:Raw mica platelets without additional surface treatments provide a basic pearlescent effect.
Natural product types anchor the volume base while synthetic variants gain share at the steepest rate due to superior performance and ethical sourcing transparency.
Application:
Application segments exhibit varying cost sensitivities, with premium automotive and luxury cosmetic formulations demanding higher-purity, more expensive pigments. Industrial applications often prioritize cost-effectiveness and bulk availability.
- Cosmetics:These pigments provide visual effects in makeup, nail polish, and personal care products, requiring compliance with regulations like US FDA and China's NMPA. Demand is strong in China and India, driven by consumer preference for special effects.
- Coatings:Used extensively in automotive finishes and industrial paints, these pigments provide deep luster and weather resistance. The automotive sector, particularly in Germany and Japan, drives demand for multi-layer effect coatings.
- Plastics:Pigments integrate into plastic resins for consumer electronics, packaging, and household goods.
- Printing Inks:These specialty inks provide metallic or pearlescent effects for packaging, labels, and security printing.
Personal care consumers prioritize aesthetic appeal, while industrial customers focus on durability and cost efficiency in their pigment selections.
Form:
The form segment reflects the volume and ease of integration into various manufacturing processes. Powder forms dominate supply chains due to their stability and broad applicability across industries.
- Powder:This stable and versatile form is widely used across all applications due to its ease of dispersion and long shelf life. Its dominance in formulations makes it a staple for both cosmetic and industrial manufacturers globally.
- Liquid:Pre-dispersed pigments offer convenience and reduce processing time in specific applications like some printing inks and coatings. Formulators in Europe and North America increasingly adopt liquid dispersions for consistency.
- Paste:High-concentration pigment pastes are used in specialized coating systems requiring precise color matching.
- Granules:These forms are primarily for plastics masterbatch production, ensuring uniform dispersion in polymers.
Powder forms represent a mature segment, while liquid and paste forms demonstrate increasing sophistication in specialized manufacturing processes.
End User:
End-user segments are differentiated by specific customer requirements, from aesthetic appeal in personal care to durability in automotive applications. Each segment demands tailored pigment properties and regulatory compliance.
- Personal Care:This segment includes cosmetics, skincare, and hair care products, where pigments provide visual effects and brand differentiation. Consumer preference for special effects in China and India drives significant demand.
- Automotive:Pigments are crucial for vehicle finishes, offering deep luster, color travel effects, and weather resistance. Premium vehicle manufacturing centers in Germany and Japan are significant consumers of these advanced pigments.
- Consumer Goods:This segment incorporates pigments into packaging, toys, and household appliances for visual appeal.
- Industrial:Industrial applications include architectural coatings, textiles, and specialized printing, requiring functional and durable pigments.
Demand for pearlescent pigments in personal care and automotive applications concentrates in established manufacturing hubs, influencing supply chain dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pearlescent pigments market sees significant supply-side concentration in regions with advanced chemical manufacturing capabilities. These hubs leverage sophisticated processes for synthetic mica production and high-purity metal oxides. Demand centers often align with major automotive and personal care manufacturing ecosystems.
China
Demand for pearlescent pigments in China stems from its expansive personal care and consumer electronics manufacturing hubs. The NMPA standards for cosmetic ingredients impose strict controls on product development. Shanghai's cosmetic industry and Shenzhen's electronics cluster drive innovation in pigment applications.
Germany
Germany's automotive sector drives substantial demand for weather-resistant pearlescent pigments in multi-layer effect coatings. The EU's REACH regulation heavily influences material selection for these advanced products. Stuttgart's automotive manufacturing centers actively integrate premium finishes.
Japan
Japan's premium vehicle finishes and consumer electronics industries require high-performance pearlescent pigments. METI guidelines encourage innovation in advanced material science for industrial applications. Nagoya's automotive production facilities consistently adopt new effect pigments.
United States
The United States market for pearlescent pigments benefits from diverse applications in automotive, plastics, and personal care. The US FDA's rules for color additives mandate rigorous safety and labeling requirements. New York's cosmetic brands and Detroit's automotive sector fuel demand for specialized effects.
India
India's growing cosmetics sector and expanding automotive industry contribute to rising pearlescent pigment consumption. BIS standards for cosmetic ingredients and industrial products shape local market entry. Mumbai's personal care manufacturers and Chennai's automotive plants seek compliant pigment solutions.
Pearlescent Pigments Market Key Industry Players
Concentration sits with large chemical conglomerates and specialized pigment manufacturers possessing deep R&D capabilities. The market structure exhibits a tiered approach, with a few global leaders dominating premium segments. Strategic archetypes include diversified chemical giants, niche effect pigment specialists, and regional suppliers focusing on cost-effectiveness. Competitive moves often involve capacity expansion in synthetic mica production and strategic partnerships for application development.
On the premium-tier vector, BASF SE exemplifies a diversified chemical giant leveraging its extensive expertise for weather-resistant automotive coatings. Merck KGaA sustains its market position by offering a portfolio of high-purity effect pigments, particularly for the cosmetics industry. Germany-based Eckart GmbH also occupies a significant position among specialized pigment manufacturers, focusing on advanced metallic and pearlescent effects for various industrial applications. These companies anchor innovation in synthetic mica substrates and complex coating technologies.
| Leading Market Players |
|---|
| BASF SE |
| Merck KGaA |
| Sun Chemical Performance Pigments |
| Fujian Kuncai Material Technology Co., Ltd. |
| Huaian Concord Cosmetics Product Co., Ltd. (Kolortek) |
| Eckart GmbH |
| Geotech International B.V. |
| RIKA Technology Co., Ltd. |
| Lansco Colors |
| Others |
Cost & Logistics Intelligence
Economies of scale in synthetic mica production drive supply concentration among a few key manufacturers, influencing the global price floor for high-performance pearlescent pigments.
Pricing Analysis
EU REACH dictates the pricing tier structure for pearlescent pigments across European markets. The market operates on a contract-based long-term offtake model for large industrial buyers, while smaller cosmetic formulators often use per-unit transactional pricing. Price differentiation stems from the pigment's purity grade and specific regulatory certifications, such as US FDA approval for cosmetics or automotive weather resistance standards. Pricing pressure stems from raw material volatility for titanium dioxide and iron oxides. Cosmetics brands in China and India are generally more price-sensitive than premium automotive OEMs in Germany and Japan.
Supply Chain Analysis
Strategic control over high-purity titanium dioxide and iron oxide sources underwrites the pearlescent pigment supply chain. Geographic supply concentration sits with China, Germany, and Japan for advanced synthetic mica production. The industry relies heavily on a few specialized chemical companies for key raw material inputs. Single-source vulnerability for specialized fluorphlogopite substrates presents a structural risk. Distribution runs through a network of specialized chemical distributors and direct sales channels to large industrial and cosmetic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Renewed consumer spending on premium cosmetics and new vehicle purchases signals a cyclical recovery for the pearlescent pigments market.
For Market Incumbents: Consolidate market position through strategic acquisitions of niche technology firms specializing in advanced effect pigments. Invest heavily in synthetic mica capacity expansion in regions like Germany to counter emerging competition from alternative effect pigments. Deepen vertical integration into key raw material supply chains to mitigate price volatility for titanium dioxide. This strategy addresses the threat of margin erosion from raw material fluctuations and sustains a competitive edge in high-value automotive coatings.
For New Entrants and Emerging Players: Anchor in underpenetrated segments like edible pigments, leveraging stringent FDA and EFSA color additive regulations as a barrier to entry. Target Southeast Asian plastics masterbatch manufacturing hubs, including Vietnam and Thailand, with cost-effective, NMPA-compliant pigment solutions for consumer electronics. Focus on developing functional pigments with IR-reflectivity for cool architectural coatings. A direct-to-manufacturer sales model, emphasizing technical support and rapid prototyping, represents a viable go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized pigment manufacturers with strong intellectual property in synthetic fluorphlogopite. Long-term viability over the next decade depends on companies capable of navigating divergent global chemical safety regulations, particularly EU REACH. Acquisition targets should include firms with established ethical sourcing certifications for natural mica or proven expertise in high-purity synthetic alternatives. The signal to watch is the acceleration of synthetic mica adoption in premium cosmetics as a proxy for market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing synthetic mica production in Germany addresses growing demand from the automotive sector. |
| Backward Integration | Securing captive supply of high-purity titanium dioxide mitigates raw material price volatility. |
| Green Manufacturing Transition | Adopting sustainable production processes enhances brand reputation among European cosmetic consumers. |
| Long-term Supply Agreement | Ensuring consistent supply for major automotive OEMs in Japan stabilizes revenue streams. |
| Joint Venture | Partnering for edible pigment development accesses new food and pharmaceutical applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to gather qualitative and quantitative insights. Primary interviews included R&D directors, procurement managers at automotive OEMs, cosmetic formulators in China, and regulatory compliance specialists. Secondary validation drew from customs data, chemical industry reports, and company 10-K filings. This approach triangulated bottom-up market intelligence with top-down industry analysis to ensure data integrity.
The analysis window for market projections extends across a defined modeling period, capturing key industry shifts. Segmentation dimensions modeled include product type, application, form, and end-user, alongside regional regulatory compliance. Compound annual growth rates were derived from historical trends and forward-looking assessments of technological adoption. Forecast inputs considered the adoption rate of synthetic fluorphlogopite and the expansion of electric vehicle production.
Material uncertainties — geopolitical trade tensions and unforeseen raw material supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions concerning regulatory stability and technological innovation within the pearlescent pigments sector. Practitioners should keep alternative scenarios live as global economic conditions and consumer preferences evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Color Concentrates Market
Dyes and Pigments
Special Effect Pigments Market
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Asia Pacific Hair Colorants Market
Dyes and Pigments
Arylamide Pigments Market
Dyes and Pigments
Colorants Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
White Pigment Market
Dyes and Pigments
Photochromic Pigments Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Thermochromic Labels Market
Dyes and Pigments
Oil-Dispersible Colors Market
Dyes and Pigments
Titanium Dioxide Pigment Market