
 Oil-Dispersible Colors Market | 2026-2036
Oil-Dispersible Colors Market Size, Share, and Industry Trends Forecast 2026-2036
Oil-Dispersible Colors Market Analytics
Custom formulation services is fragmenting across specialized pigment houses and integrated ingredient distributors, eroding the margin pool once captured by broad-line chemical suppliers. Sensient Technologies Corporation leverages its technical service laboratories in North America and Europe to anchor long-term supply contracts with confectionery and nutraceutical manufacturers. Chr. Hansen Holding A/S specializes in carotenoid-derived oil-dispersible systems, competing on color stability under thermal stress and pH variation. DDW The Colour House controls heritage expertise in caramel and turmeric oil-dispersible formats, occupying a defensible niche in natural colorant portfolios.
Oil-dispersible colors comprise lipophilic pigment and dye systems engineered with surface-active coatings or carrier oils to achieve homogeneous dispersion in fat-based matrices at particle sizes typically below 10 microns; these systems serve as colorants in food, cosmetic, and industrial applications where aqueous solubility would compromise stability or visual uniformity. Pigments and masterbatches command the dominant share of value given their concentration efficiency and compatibility with high-temperature polymer processing, while dye-based liquid formats represent the fastest-growing structural pocket as cosmetics brands reformulate anhydrous color cosmetics. The coatings application segment sustains premium pricing through technical specification requirements for automotive and industrial finishes, whereas plastics integration demands granule and powder forms optimized for extrusion throughput.
FDA color additive regulations govern permissible lists and batch certification requirements for oil-dispersible colors entering food and cosmetic channels in the United States, while REACH and the EU Green Deal framework in Europe impose substance registration thresholds and restrict certain heavy metal contaminants across pigment chemistries. The EFSA evaluates novel color sources for oil-dispersible applications, creating a dual-track compliance burden for suppliers seeking transatlantic market access. Stakeholders must monitor divergence between FDA batch certification protocols and EU hazard classification updates to anticipate reformulation costs and qualification timelines.
Market Dynamics
Clean-label formulation mandates from cosmetics and food brands are compressing synthetic pigment demand while fragmenting procurement across specialized natural colorant suppliers with proven regulatory dossiers.
Growth Catalysts
- REACH substance registration thresholds:European formulators are accelerating qualification of oil-dispersible carotenoids and turmeric extracts to preempt 2025-2026 dossier deadlines.
- Thermal stability engineering:High-fat confectionery applications now require pigment systems surviving 85°C processing temperatures without hue shift.
- India:FSSAI's expanded natural colorant positive list is opening formulation pathways for anhydrous dairy and savory snack segments previously dependent on synthetic lakes.
Market Restraints
- Beta-carotene feedstock volatility:Fermentation-derived carotenoid costs swing with sugar and yeast extract pricing, squeezing margin predictability for mid-tier pigment houses.
- Heavy metal contaminant thresholds:EFSA and FDA divergence on lead and arsenic limits forces dual-track testing protocols, adding 12-18 months to new product qualification.
- Annatto extraction yield limits:Natural bixin concentration in seed sources caps output scalability, constraining supply response to surging clean-label demand.
Strategic Opportunities
- Brazil:ANVISA's pending natural colorant harmonization with Mercosur standards creates first-mover advantage for suppliers establishing local technical service labs.
- Precision fermentation:Microbial production of rare carotenoids (astaxanthin, canthaxanthin) converges with downstream lipid encapsulation to unlock pharmaceutical-grade purity at food-grade scale.
- Direct-to-formulator digital platforms:Specialty distributors bypass broad-line chemical houses, capturing margin through sample-to-scale technical support subscriptions.
Industry Challenges
- Spectrophotometric color matching expertise:Formulation chemists capable of predicting CIE L*a*b* values across variable fat matrices command 40% salary premiums, constraining R&D expansion.
- Legacy ERP-to-lab integration:Pigment houses struggle to connect batch certification workflows with customer quality portals, delaying order confirmation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil-Dispersible Colors Market |
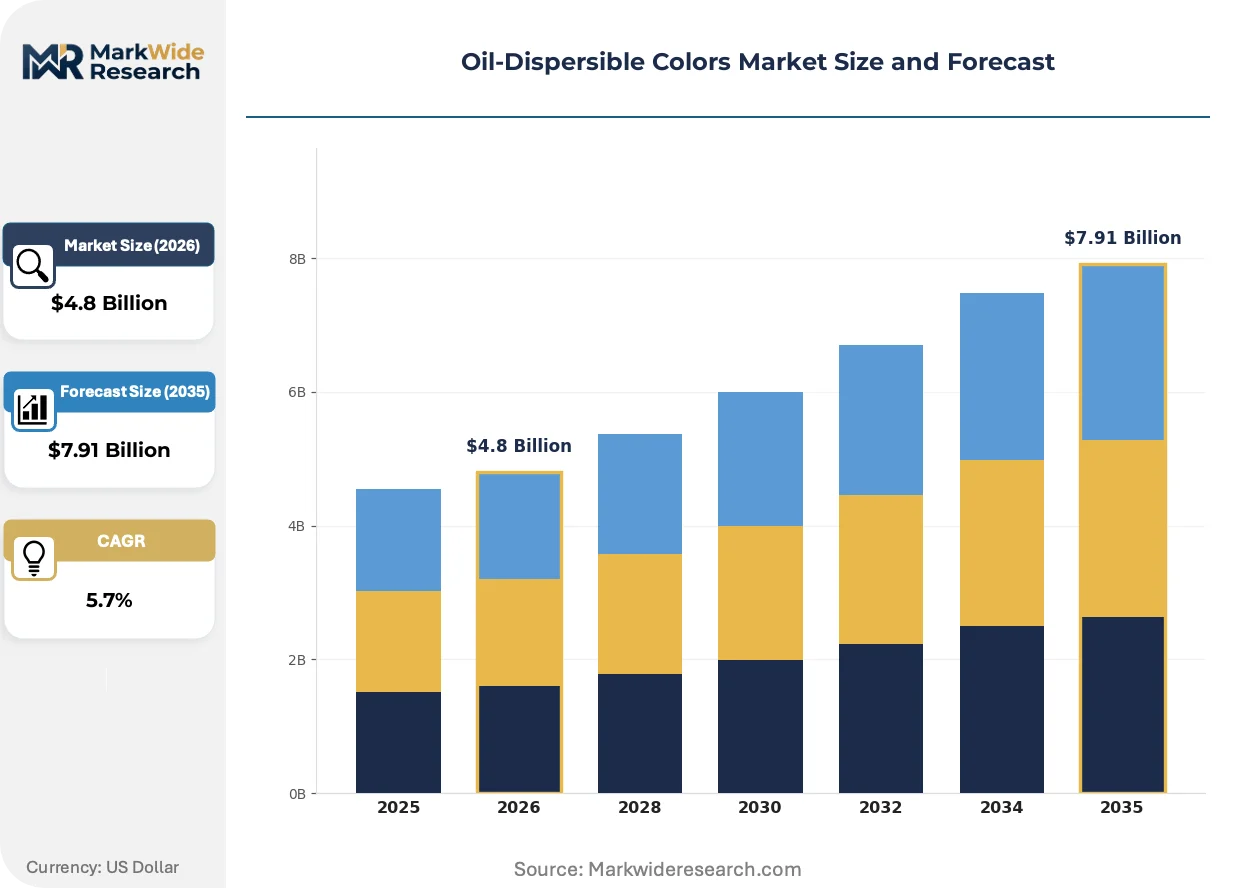
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pigments, Dyes, Colorants, Masterbatches Application: Coatings, Inks, Plastics, Cosmetics End User: Manufacturers, Artisans, Integrators, Retailers Form: Liquid, Powder, Granule, Paste |
| Companies Covered | Sensient Technologies Corporation, Chr. Hansen Holding A/S, DDW The Colour House, Archer Daniels Midland, Symrise, GNT International B.V., Naturex, Kalsec, Inc., Lycored, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil-Dispersible Colors Market Evolving Landscape
Surface-engineered lipid nanoparticles and bio-derived carrier systems are rewriting dispersion performance benchmarks, compressing the viable supplier set to those with in-house particle size control and regulatory dossier depth.
Microfluidic lipid encapsulation is rendering obsolete conventional high-shear homogenization for sub-micron pigment dispersion. Cosmetics formulators in France and Germany are adopting these systems at pilot scale within 18-month qualification windows. The technology is rendering obsolete legacy equipment investments and locking in multi-year supply contracts with integrated technology licensors.
EU Green Deal chemical sustainability requirements are forcing disclosure of pigment carbon intensity and renewable feedstock percentages across the supply chain. Industrial coatings manufacturers face reformulation costs to maintain CE marking eligibility for automotive finishes. German automotive OEMs are now requiring Tier 2 pigment suppliers to submit Product Carbon Footprint data via the Catena-X network.
Specification-driven procurement now separates premium pigment grades by thermal stability certification rather than origin claims alone. Confectionery manufacturers in Switzerland and Belgium are unbundling colorant purchasing from compound ingredient bundles, conducting direct qualification of oil-dispersible systems. This behavior concentrates volume with three to five qualified suppliers per manufacturing site, eroding spot-market liquidity.
Oil-Dispersible Colors Market Segmentation
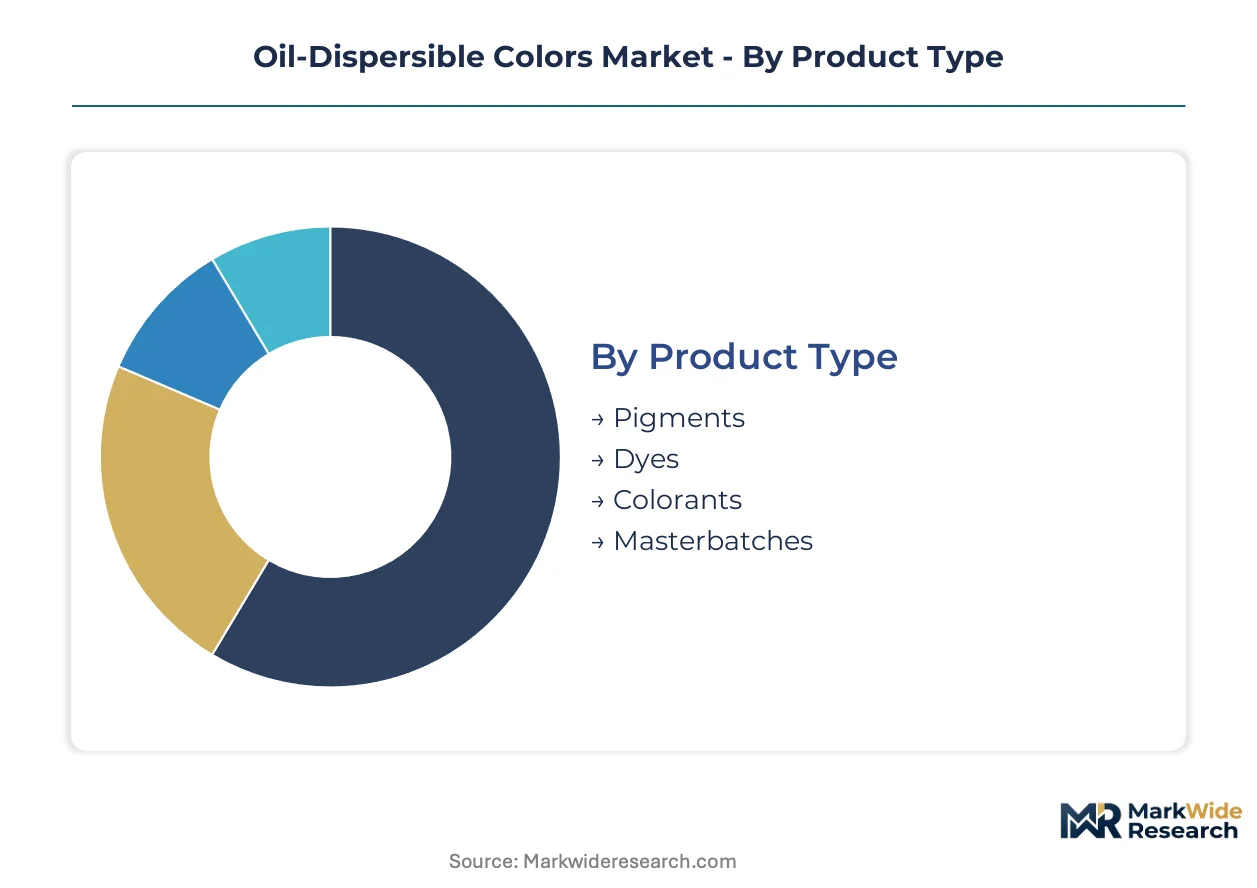
Oil-dispersible colors serve radically different performance requirements across fat-based matrices, from high-temperature polymer extrusion to delicate cosmetic emulsions. Segmentation reveals where formulation complexity concentrates procurement spend and where standardization enables scale.
Product Type:
Use cases span from concentrated pigment powders for industrial coatings to liquid dye systems for artisanal confectionery, with each format demanding distinct surface engineering and carrier chemistry.
- Pigments:Insoluble crystalline particles with lipophilic surface coatings deliver opacity and lightfastness in high-fat confectionery and automotive finishes. Swiss and Belgian chocolate manufacturers now require thermal stability certification above 85°C, compressing the qualified supplier base to pigment houses with in-house particle size control below 10 microns.
- Masterbatches:Concentrated pigment dispersions in polymer carriers enable precise dosing during extrusion of packaging films and industrial components. German automotive OEMs are mandating Product Carbon Footprint disclosure via Catena-X for all masterbatch inputs, favoring suppliers with renewable feedstock traceability.
- Dyes:Molecular colorants achieving transparency in anhydrous cosmetic formulations where particulate haze is unacceptable.
- Colorants:Blended systems combining pigment and dye fractions for intermediate opacity requirements in specialty inks.
The dominant share belongs to Pigments, while Masterbatches are closing the gap fastest as polymer processors consolidate supply relationships around carbon-accountable partners.
Application:
End-use specifications diverge sharply between segments requiring batch certification for food contact and those governed by industrial performance standards alone.
- Coatings:Automotive and industrial finishes demand oil-dispersible systems with weathering resistance and chemical stability. REACH substance registration thresholds are forcing reformulation of solvent-borne coatings across German and French manufacturing, with ECHA dossier deadlines accelerating qualification of low-hazard pigment alternatives.
- Cosmetics:Anhydrous color cosmetics, lipsticks, and oil-based serums require sub-micron dispersion without aqueous phase instability. French formulators are piloting microfluidic lipid encapsulation systems within 18-month qualification windows, locking in multi-year supply contracts with integrated technology licensors.
- Plastics:Extrusion and injection molding applications prioritize thermal stability during high-shear processing of polyolefins and engineering resins.
- Inks:Offset and flexographic printing on non-porous substrates depends on rapid solvent release and adhesion promotion in oil-based vehicles.
Coatings command premium pricing through technical specification depth, yet Cosmetics is expanding most quickly as clean-label mandates displace synthetic lakes.
End User:
Procurement sophistication varies from specification-driven direct purchasing by large manufacturers to price-sensitive spot buying by artisan formulators.
- Manufacturers:Industrial-scale compounders and converters with dedicated color matching laboratories and spectrophotometric quality protocols. These buyers are unbundling colorant purchasing from compound ingredient bundles, conducting direct qualification of three to five suppliers per manufacturing site.
- Integrators:Mid-tier formulators serving private-label cosmetics and regional food brands, balancing technical service needs against minimum order quantities.
- Artisans:Small-batch producers in specialty confectionery and handcrafted cosmetics, purchasing through distributor channels with sample-to-scale support subscriptions.
- Retailers:Private-label brands and direct-to-consumer colorant suppliers, increasingly sourcing through digital platforms that bypass broad-line chemical houses.
Manufacturers capture the volume concentration, though Retailers are gaining share fastest as direct-to-formulator digital platforms fragment traditional distribution.
Form:
Physical format determines handling economics, dispersion energy requirements, and compatibility with automated dosing systems across manufacturing scales.
- Liquid:Pre-dispersed pigment or dye suspensions in carrier oils eliminate dust exposure and reduce mixing time. Cosmetics brands reformulating anhydrous color cosmetics are driving demand for liquid formats with guaranteed sub-micron particle size distribution.
- Powder:Concentrated dry pigments requiring high-shear dispersion equipment but offering lowest cost-in-use for large-batch processing.
- Granule:Dust-free, free-flowing forms optimized for automated feeding in continuous extrusion operations.
- Paste:Semi-solid concentrates bridging handling convenience with high pigment loading for specialized ink and coating applications.
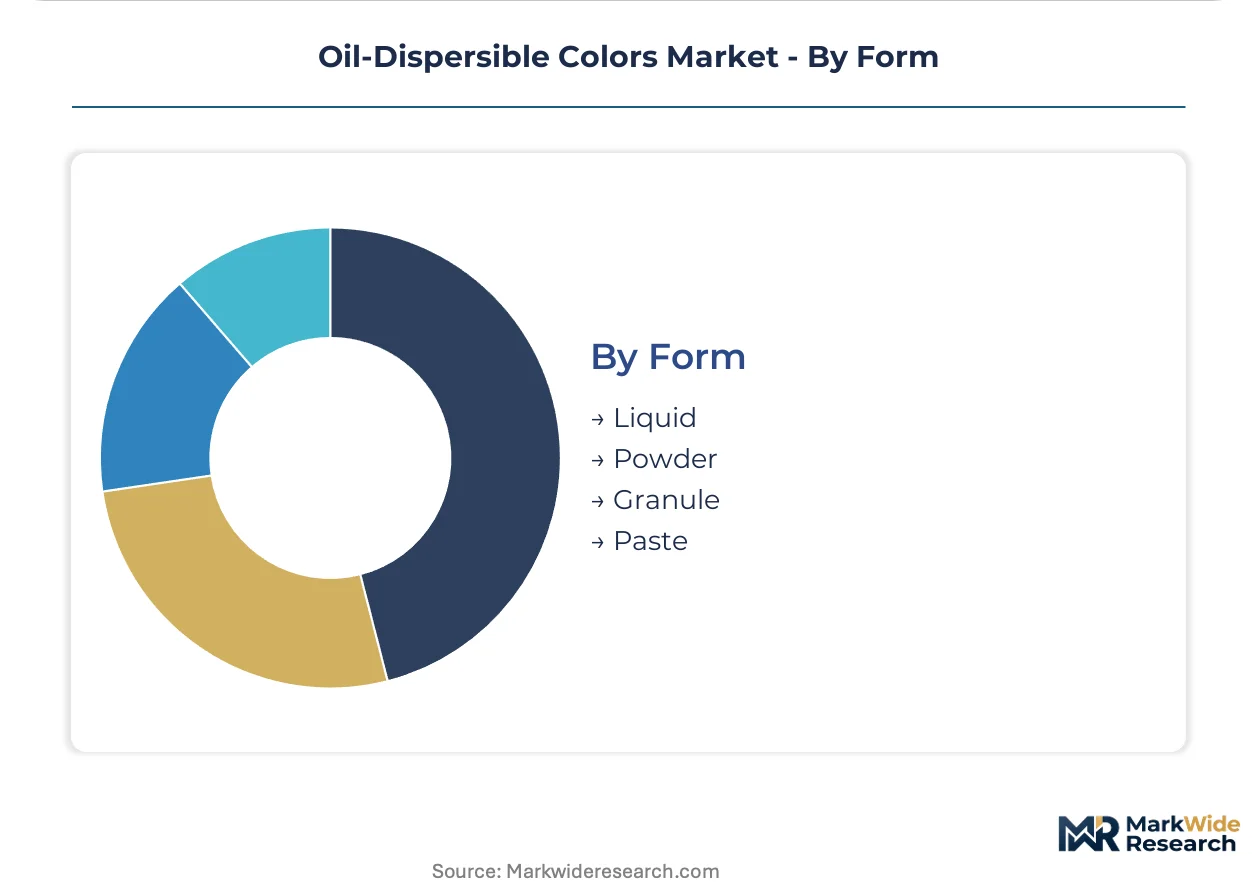
Powder retains the dominant position on cost efficiency, while Liquid is climbing the fastest as cosmetics formulators prioritize processing speed and dust-free handling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: European formulators prioritize REACH-compliant natural carotenoids for clean-label confectionery, while Asian processors emphasize cost-efficient synthetic lakes for high-volume savory applications. Regulatory stringency and end-use sophistication determine which pigment grades dominate regional procurement.
Germany
Automotive coatings manufacturers in Stuttgart and Munich drive demand for thermally stable oil-dispersible pigments surviving 180°C bake cycles. ECHA's REACH substance registration deadlines through 2026 are accelerating qualification of low-hazard alternatives among Tier 2 suppliers. The Catena-X automotive network now mandates Product Carbon Footprint disclosure from pigment houses serving Bavarian OEMs.
United States
Confectionery compounders in Chicago and Pennsylvania require FDA batch-certified oil-dispersible colors for chocolate and coating applications. The FDA's evolving color additive regulations are compressing timelines for novel natural colorant approvals. Sensient Technologies maintains technical service laboratories in North America to anchor long-term supply contracts with regional nutraceutical manufacturers.
India
Anhydrous dairy processors in Gujarat and Maharashtra are reformulating with FSSAI-approved natural colorants as the regulator expands its positive list. FSSAI's expanded natural colorant approvals are opening formulation pathways previously dependent on synthetic lakes. Mumbai-based formulators are unbundling colorant purchasing from compound ingredient bundles to conduct direct supplier qualification.
France
Cosmetics laboratories in Paris and Lyon pilot microfluidic lipid encapsulation systems for sub-micron pigment dispersion in anhydrous color cosmetics. EU Green Deal chemical sustainability requirements are forcing disclosure of carbon intensity across the supply chain. L'Oréal's procurement specifications now require renewable feedstock percentages from oil-dispersible color suppliers.
Brazil
Savory snack manufacturers in São Paulo state seek oil-dispersible turmeric and annatto systems as ANVISA prepares natural colorant harmonization with Mercosur standards. ANVISA's pending regulatory alignment is creating first-mover advantage for suppliers establishing local technical service infrastructure. Campinas-based ingredient distributors are fragmenting procurement away from broad-line chemical houses toward specialized pigment suppliers.
Oil-Dispersible Colors Market Competitive Landscape
Capability concentration sits with specialized pigment houses possessing in-house particle size control and regulatory dossier depth; scale advantage sits with integrated ingredient distributors with global logistics networks. The vendor base organizes into three tiers: multinational color specialists with technical service laboratories, regional natural extract houses with heritage expertise in carotenoid and turmeric systems, and broad-line chemical distributors ceding margin to specialized competitors. Dominant competitive moves include strategic partnerships for microfluidic encapsulation licensing and geographic expansion through local technical service lab establishment.
Among North American and European specialists, Sensient Technologies Corporation, Chr. Hansen Holding A/S, and DDW The Colour House exemplify contrasting archetypes. Sensient Technologies represents the technical-service-anchored model with laboratory infrastructure securing long-term manufacturing contracts. Chr. Hansen Holding A/S occupies a position within carotenoid-derived systems, competing on thermal stability performance. DDW The Colour House anchors heritage expertise in caramel and turmeric formats, sitting within the defensible natural colorant niche.
| Leading Market Players |
|---|
| Sensient Technologies Corporation |
| Chr. Hansen Holding A/S |
| DDW The Colour House |
| Archer Daniels Midland |
| Symrise |
| GNT International B.V. |
| Naturex |
| Kalsec, Inc. |
| Lycored |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese synthetic pigment intermediates is compressing spot-market liquidity and forcing European natural colorant suppliers toward long-term offtake structures. This utilization imbalance accelerates margin bifurcation between fermentation-derived carotenoid houses and legacy lake pigment distributors.
Pricing Analysis
Long-term offtake agreements dominate procurement for confectionery and automotive coatings manufacturers, insulating qualified suppliers from feedstock volatility. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade certifications captures 40-60% spreads. Cost compression in mid-tier synthetic lakes is intensifying because Indian and Chinese producers are expanding fermentation capacity. Artisan formulators and spot buyers in specialty cosmetics exhibit the highest price sensitivity, while Swiss chocolate manufacturers accept premiums for thermal stability guarantees.
Supply Chain Analysis
Contract-manufacturing concentration for carotenoid fermentation rests with Danish and Indian biotech facilities, while pigment dispersion and surface coating capacity clusters in Germany and the Netherlands. Feedstock dependencies include sugar cane and yeast extract for fermentation, plus annatto seeds and turmeric rhizomes for botanical extraction. Single-source vulnerability in annatto seed supply from Brazil and Peru threatens clean-label formulation continuity. Distribution runs through integrated ingredient distributors with technical service laboratories, bypassing broad-line chemical houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. EFSA and FDA dossier requirements create switching costs that lock in formulator relationships for 5-7 year qualification cycles.
For Market Incumbents: Insulate margin pools by deepening backward integration into fermentation feedstocks and captive annatto seed sourcing from Brazilian cooperatives. Accelerate REACH dossier submissions ahead of 2026 deadlines to preempt competitor qualification. Counter precision fermentation entrants by locking multi-year supply contracts with L'Oréal and Swiss confectionery manufacturers. For New Entrants and Emerging Players: Brazilian savory snack processors represent the most penetrable white-space target as ANVISA harmonizes with Mercosur standards. Direct-to-formulator digital platforms with sample-to-scale technical support subscriptions bypass entrenched distributor relationships. Target Campinas-based ingredient distributors for partnership rather than competing on specification depth. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across microfluidic lipid encapsulation equipment and precision fermentation infrastructure. Five-to-ten year viability favors specialists with in-house particle size control below 10 microns and existing regulatory dossiers. Watch for EFSA novel food approval velocity as an inflection indicator for natural colorant valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial astaxanthin production unlocks pharmaceutical-grade purity at food-grade cost structures. |
| Microfluidic Encapsulation Licensing | French cosmetics formulators pilot sub-micron dispersion systems within 18-month qualification windows. |
| Catena-X Carbon Disclosure Compliance | German automotive OEMs mandate Product Carbon Footprint data from Tier 2 pigment suppliers. |
| Direct Technical Service Lab Expansion | Local laboratories in São Paulo secure first-mover advantage ahead of ANVISA harmonization. |
| Heritage Botanical Extraction Acquisition |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across confectionery compounders, cosmetics formulators, pigment house technical directors, and automotive coatings procurement leads. Secondary validation drew from EFSA novel food opinions, FDA color additive petitions, ECHA REACH dossier databases, and FSSAI positive list notifications. Bottom-up volume triangulation from individual manufacturing sites converged with top-down value estimates from customs trade flows.
Calibration against historical thermal stability certification timelines and regulatory approval velocity anchored growth assumptions across the projection horizon. Segmentation dimensions modeled include pigment chemistry class, carrier oil formulation, thermal stability tier, and end-use regulatory pathway. CAGRs derived from diffusion curves of microfluidic adoption and precision fermentation capacity expansion, cross-checked against annatto seed harvest yield constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups or Chinese lake pigment exporters would shift outcomes. Quarterly review of EFSA novel food approval queues and FSSAI positive list expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Bio Based Pigments and Dyes Market
Dyes and Pigments
Light Interference Pigments Market
Dyes and Pigments
Material Color Matching Booth Market
Dyes and Pigments
Fluorescent Pigments Market
Dyes and Pigments
North America Hair Colorants Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Global Cosmetic Dyes Market
Dyes and Pigments
Pharmaceutical Dyes Market
Dyes and Pigments
Resin Pigments Market
Dyes and Pigments
Global Architectural Paint Oxide Market
Dyes and Pigments
Dyestuff (Black Color) Market
Dyes and Pigments
Carmine Market
Dyes and Pigments
Global Thermochromic Materials Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Polymer Colorant Market