
 Holographic Versatile Disc (HVD) Market | 2026-2036
Holographic Versatile Disc (HVD) Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic Versatile Disc (HVD) Market Foresight
ISO/IEC 29143 certification for holographic data interchange is rotating market access toward suppliers with verified optical recording compliance. Fuji Photo Film Co., Ltd. leverages its photopolymer chemistry heritage to anchor supply of holographic recording media. Sony Corporation dominates precision optical pickup development for parallel read-write architectures. Optware Corporation specializes in collinear holography systems that compress encoder complexity into single-lens assemblies.
Holographic Versatile Disc technology stores data through three-dimensional interference patterns in photopolymer layers, achieving theoretical capacities exceeding one terabyte per 120-millimeter disc by multiplexing angle, wavelength, and phase-encoded holograms. Its primary commercial purpose centers on cold archival where retrieval latency tolerance permits optical media's slower access speeds against magnetic alternatives. Rewritable media segments attract premium positioning due to phase-change material costs and limited supplier bases, while read-only formats occupy volume production for software distribution and entertainment mastering. Data center end users represent the fastest-growing demand pool as hyperscale operators seek air-gapped backup solutions immune to electromagnetic interference and ransomware penetration.
FCC equipment authorization governs laser emission thresholds for HVD drives marketed in the United States, while Japan's METI oversees domestic photonics manufacturing standards through JIS certification pathways. REACH chemical restrictions in Europe constrain photopolymer resin formulations, pushing reformulation investments toward halogen-free initiator compounds. Stakeholders must monitor which regulatory jurisdiction certifies first-mover archival standards, as that geography's technical specifications will likely propagate into procurement requirements across allied data center networks.
Market Dynamics
Data center operators are redirecting archival budgets toward air-gapped optical systems as ransomware attacks expose magnetic storage vulnerabilities. This demand rotation is compressing qualification timelines for holographic media suppliers.
Growth Catalysts
- Hyperscale archival demand:Cloud operators in Virginia and Frankfurt are provisioning petabyte-scale cold storage arrays that specify optical isolation from network-connected infrastructure.
- Japan's METI photonics roadmap:Domestic manufacturing subsidies for next-generation optical media are expanding foundry capacity in Yamanashi Prefecture.
- Photopolymer chemistry advances:Improved initiator stability at elevated temperatures is extending archival life ratings beyond fifty years for enterprise contracts.
Market Restraints
- Drive hardware cost concentration:Precision optical pickup assemblies require rare-earth magnet components subject to supply volatility from Chinese processing facilities.
- REACH formulation constraints:ECHA restrictions on halogenated photoinitiators are forcing European resin suppliers into eighteen-month reformulation cycles.
- Latency gap with tape systems:LTO-9 cartridges retrieve data blocks faster than holographic read heads for sequential workloads, limiting substitution in backup applications.
Strategic Opportunities
- India's data localization mandates:CERT-In requirements for domestic storage of financial records are creating first-mover advantage for archival media vendors establishing Mumbai assembly.
- Quantum encryption integration:Converging holographic write-once media with quantum key distribution protocols addresses sovereign cloud security specifications.
- Medical imaging archives:DICOM-compliant long-term storage for radiology departments represents an underpenetrated vertical with stringent immutability requirements.
Industry Challenges
- Optical engineering talent scarcity:Collinear holography system design requires expertise in Fourier optics that concentrates among Japanese and German research institutions.
- ISO/IEC 29143 certification timelines:Third-party verification of holographic interchange compatibility extends product launch schedules by fourteen to twenty months.
- Legacy jukebox integration:Robotic media handling systems from prior optical generations require mechanical retrofitting to accommodate HVD thickness tolerances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holographic Versatile Disc (HVD) Market |
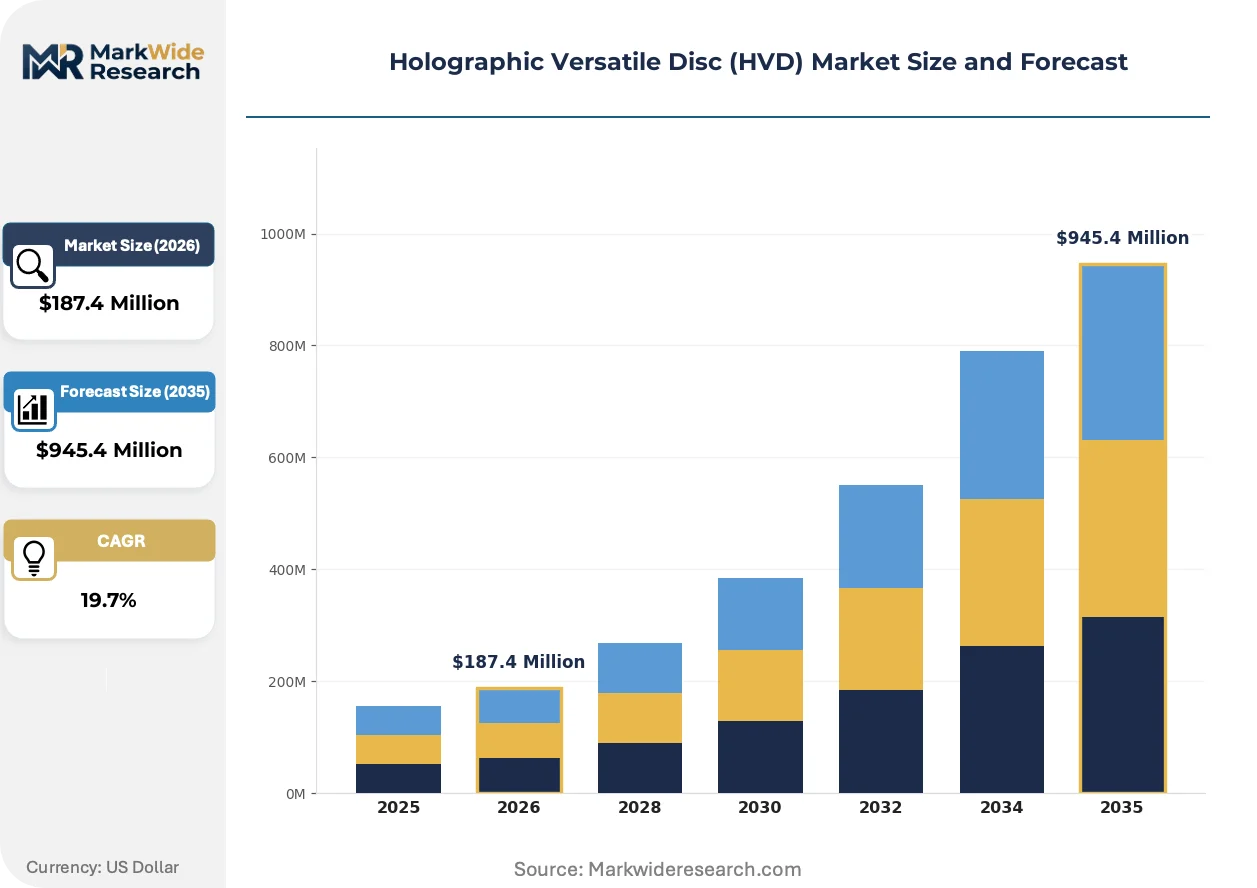
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $945.4 Million |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Read-Only, Rewritable, Writable, Hybrid Technology: Holographic Data Storage, Optical Recording, Data Retrieval, Signal Processing End User: Consumer Electronics, Data Centers, Film Industry, Research Institutions Application: Data Archiving, Multimedia Storage, Backup Solutions, Software Distribution |
| Companies Covered | Fuji Photo Film Co., Ltd., Pulstec Industrial Co., Ltd., Optware Corporation, Sony Corporation, TOAGOSEI Co., Ltd., InPhase Technologies, Nippon Paint Co., Ltd., Hitachi, CMC Magnetics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Versatile Disc (HVD) Market Shifts & Advancements
Parallel read-write architectures are compressing access latency gaps with magnetic alternatives. Three developments are restructuring supplier priorities and procurement specifications.
Collinear holography is supplanting traditional two-beam interference systems in next-generation drive designs. Data center operators in Singapore and Dublin are piloting single-lens encoder assemblies that halve optical path complexity. This convergence of recording geometry is enabling smaller form factors for rack-mounted archival units.
China's GB/T optical media standards are mandating domestic certification for government procurement contracts. MIIT testing protocols for holographic recording layers are diverging from ISO/IEC specifications on signal-to-noise thresholds. Suppliers targeting state-owned cloud infrastructure must maintain dual qualification tracks.
Enterprise buyers are unbundling media supply from drive hardware in multi-year contracts. Financial services firms in London and New York are negotiating direct sourcing agreements with photopolymer manufacturers. This disintermediation of original equipment manufacturers is compressing margin structures for integrated system vendors.
Holographic Versatile Disc (HVD) Market Segmentation
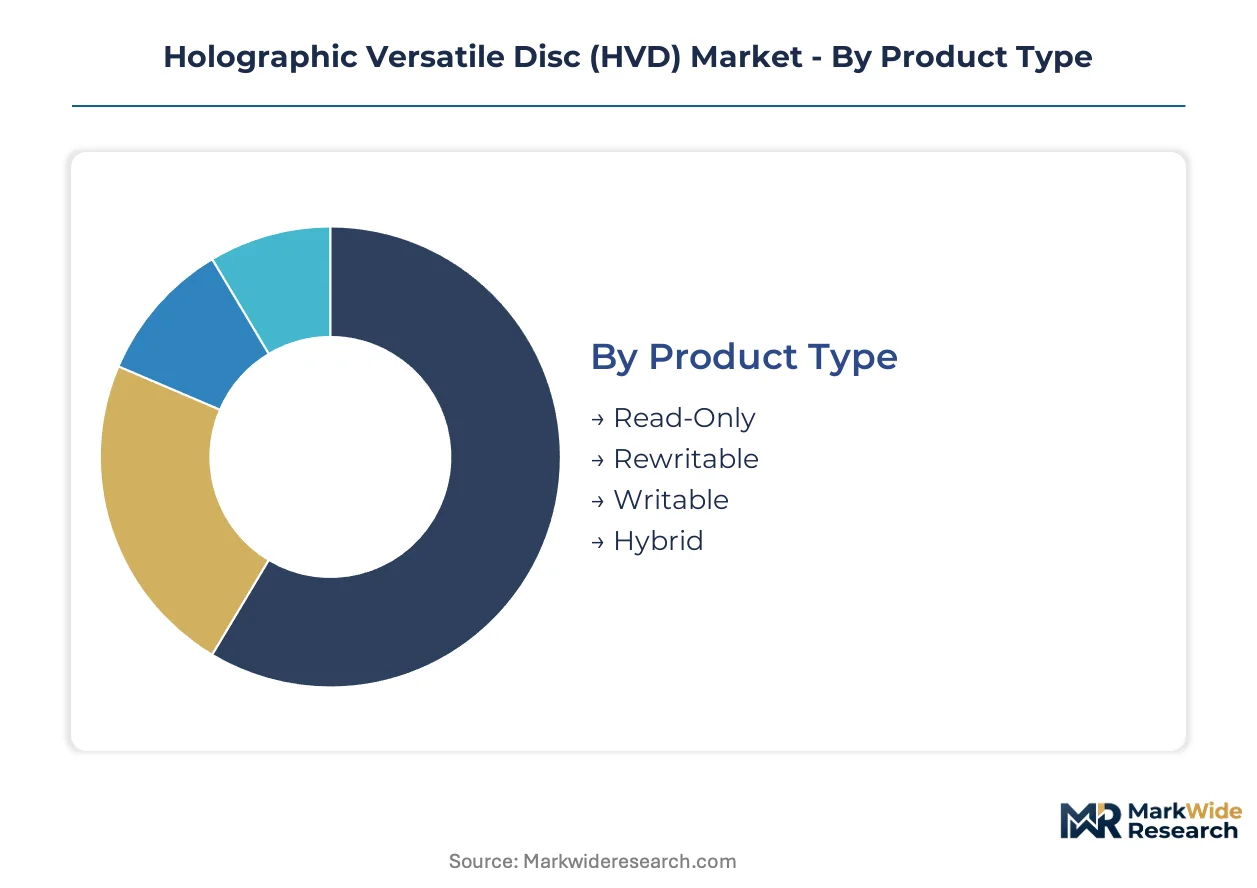
HVD market segmentation reveals how channel economics fragment procurement patterns. Product format determines whether sales flow through OEM system integrators or direct media supply contracts. Technology tier and end-user vertical further stratify pricing power and qualification timelines.
Product Type:
Channel economics diverge sharply across format types, with read-only media flowing through mastering houses and entertainment distributors while rewritable formats command direct enterprise procurement relationships.
- Read-Only:Permanent interference patterns are encoded during manufacturing, creating immutable data layers suited for software distribution and entertainment mastering. Data centers in Virginia and Frankfurt specify read-only formats for compliance archives where tamper-proof immutability satisfies regulatory retention mandates. This segment dominates installed base. Rewritable is where expansion concentrates.
- Rewritable:Phase-change photopolymer layers enable erasure and rewriting through controlled laser exposure, though material costs limit supplier bases and extend lead times. Financial services firms in London negotiate multi-year supply agreements directly with photopolymer manufacturers to secure allocation. Rewritable commands premium positioning against read-only alternatives.
- Writable:Single-write-once media serves backup applications requiring audit trails without rewritable complexity. Medical imaging archives in Japan's radiology departments favor writable formats for DICOM-compliant long-term storage.
- Hybrid:Dual-layer constructions combine read-only reference data with writable user sectors, enabling flexible deployment across mixed-use environments. Hybrid configurations attract pilot deployments in Singapore data centers testing rack-mounted archival units.
Read-Only dominates installed base. Rewritable is where expansion concentrates.
Technology:
Cost tier stratification separates mature optical recording from emerging holographic architectures, with signal processing layers capturing disproportionate R&D investment.
- Holographic Data Storage:Three-dimensional interference patterns multiplexed through angle, wavelength, and phase encoding achieve theoretical capacities exceeding one terabyte per 120-millimeter disc. Hyperscale operators provision petabyte-scale cold storage arrays specifying holographic isolation from network-connected infrastructure. This segment climbs the fastest as collinear holography compresses encoder complexity into single-lens assemblies.
- Optical Recording:Precision laser writing onto photopolymer substrates requires rare-earth magnet components in optical pickup assemblies, creating supply volatility from Chinese processing facilities. Optical recording remains the cost-accessible entry tier for qualification pilots.
- Data Retrieval:Parallel read-write architectures halve access latency gaps with magnetic alternatives through multi-channel hologram reconstruction. Data centers in Dublin pilot retrieval systems that displace sequential tape workloads.
- Signal Processing:Fourier optics expertise concentrates among Japanese and German research institutions, constraining engineering talent availability. Signal processing layers determine ISO/IEC 29143 certification timelines that extend product launches.
Optical Recording anchors volume shipments. Holographic Data Storage is gaining share fastest.
End User:
Customer type determines contract structure, with data centers unbundling media supply from drive hardware while consumer electronics maintains bundled system sales.
- Data Centers:Air-gapped backup solutions immune to electromagnetic interference and ransomware penetration redirect archival budgets toward optical isolation. Cloud operators specify optical media for cold storage tiers where retrieval latency tolerance permits slower access speeds. Data Centers represent the steepest expansion trajectory among end-user verticals.
- Consumer Electronics:Home archiving and personal media libraries drive unit volume through retail channels, though capacity requirements lag enterprise specifications. Consumer demand concentrates in Japan's optical technology corridor anchored by Tokyo and Osaka.
- Film Industry:Digital cinema mastering and distribution mastering requires read-only formats with fifty-year archival life ratings. Studios negotiate direct photopolymer supply to bypass OEM margin compression.
- Research Institutions:Scientific data preservation and experimental replication archives demand write-once immutability for peer review compliance. Research procurement flows through national laboratory frameworks in the United States and Europe.
Data Centers dominate new contract value. Film Industry maintains stable replacement demand.
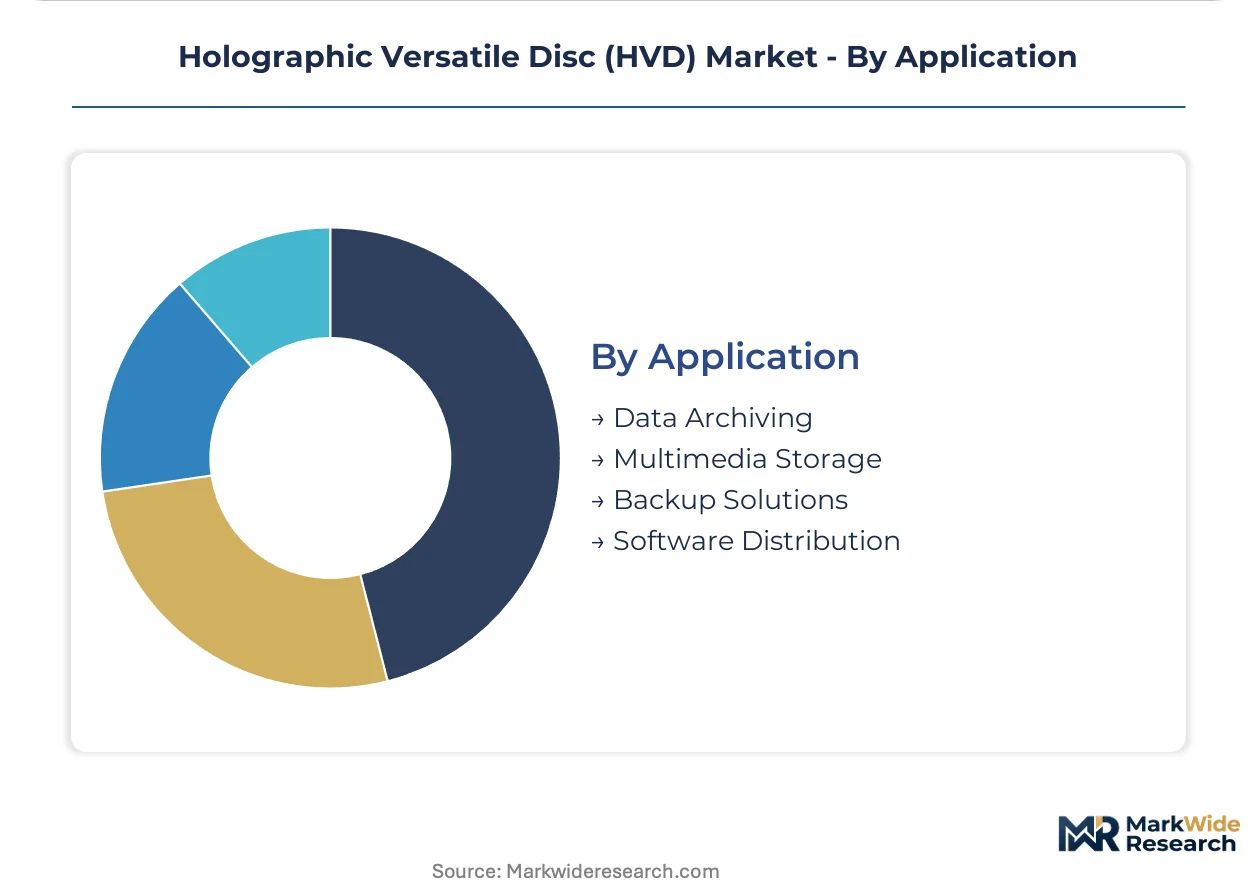
Application:
Maturity gradients separate established backup solutions from emerging multimedia storage, with software distribution occupying declining legacy share.
- Data Archiving:Long-term cold storage for compliance, legal hold, and regulatory retention specifies holographic media's immunity to bit rot and electromagnetic degradation. China's dual carbon goals and GB standards accelerate domestic manufacturing investment for state-owned cloud infrastructure. Data Archiving is expanding most quickly as hyperscale operators scale petabyte deployments.
- Backup Solutions:Secondary copy creation for disaster recovery competes against LTO-9 tape systems on retrieval latency for sequential workloads. Backup procurement favors hybrid optical-tape architectures.
- Multimedia Storage:High-resolution video archives and immersive content libraries exploit holographic capacity density for uncompressed source material. Multimedia demand concentrates in production clusters around Los Angeles and Mumbai.
- Software Distribution:Physical media mastering for enterprise software and gaming experiences declining share against digital delivery, though air-gapped environments sustain niche demand. Distribution channels consolidate through remaining optical mastering houses.
Data Archiving commands premium contract values. Backup Solutions maintains volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators in Virginia and hyperscale cloud providers in Frankfurt drive procurement volumes for holographic archival systems. Japan's optical technology corridor and China's state-owned cloud infrastructure anchor manufacturing investment. Regulatory divergence on certification standards is fragmenting supplier qualification tracks across major demand centers.
United States
Hyperscale operators in Northern Virginia provision petabyte-scale cold storage arrays specifying optical isolation from network-connected infrastructure. FCC equipment authorization governs laser emission thresholds for HVD drives marketed domestically. Cloud concentration in Loudoun County is compressing qualification timelines for holographic media suppliers seeking enterprise contracts.
Japan
Domestic manufacturing subsidies for next-generation optical media are expanding foundry capacity in Yamanashi Prefecture under METI photonics roadmap guidance. JIS certification pathways oversee domestic photonics manufacturing standards for holographic recording layers. Tokyo and Osaka anchor the optical technology corridor where Fourier optics expertise concentrates among research institutions.
Germany
Financial services firms in Frankfurt negotiate direct sourcing agreements with photopolymer manufacturers for rewritable media allocation. ECHA restrictions on halogenated photoinitiators force European resin suppliers into extended reformulation cycles. The Rhine-Main metropolitan region hosts pilot deployments of rack-mounted archival units testing collinear holography systems.
China
Dual carbon goals and GB/T optical media standards accelerate domestic manufacturing investment for state-owned cloud infrastructure. MIIT testing protocols for holographic recording layers diverge from ISO/IEC specifications on signal-to-noise thresholds. Suppliers targeting government procurement contracts must maintain dual qualification tracks for state-owned data centers.
India
CERT-In requirements for domestic storage of financial records create first-mover advantage for archival media vendors establishing Mumbai assembly operations. The country's national data protection framework mandates localization for critical sector records. Maharashtra's emerging data center cluster is attracting photopolymer chemistry investments from optical media specialists.
Holographic Versatile Disc (HVD) Market Competitive Landscape
Player mix skews toward integrated photonics conglomerates with heritage in optical media chemistry. Market structure concentrates around Japanese and German precision manufacturing ecosystems, with limited supplier bases for rare-earth magnet components in optical pickup assemblies. Three strategic archetypes dominate: photopolymer chemistry specialists, precision optical system integrators, and collinear holography technology developers. Competitive moves center on backward integration into photopolymer resin supply and geographic expansion into data center hubs seeking air-gapped archival solutions.
Among Japanese-based conglomerates, Fuji Photo Film Co., Ltd. and Sony Corporation exemplify the integrated photonics archetype, occupying positions that bridge chemical heritage with precision optical engineering. Optware Corporation represents the specialized collinear holography tier, anchoring technology development for single-lens encoder assemblies. These three entities collectively illustrate how competitive positioning stratifies across chemical supply, hardware integration, and proprietary recording geometries.
| Leading Market Players |
|---|
| Fuji Photo Film Co., Ltd. |
| Pulstec Industrial Co., Ltd. |
| Optware Corporation |
| Sony Corporation |
| TOAGOSEI Co., Ltd. |
| InPhase Technologies |
| Nippon Paint Co., Ltd. |
| Hitachi |
| CMC Magnetics Corporation |
| Others |
Supply & Pricing Matrix
ISO/IEC 29143 certification gates both supplier qualification and price differentiation simultaneously, extending product launch schedules by fourteen to twenty months while creating tiered access for verified optical recording compliance. Data center operators in Virginia and Frankfurt compress qualification timelines for holographic media suppliers, yet premium positioning concentrates among photopolymer chemistry specialists with verified archival life ratings.
Pricing Analysis
Cost-plus contracts with rare-earth magnet indexation dominate precision optical pickup assemblies, where photopolymer chemistry heritage commands premium positioning against commodity resin alternatives. Price differentiation separates ISO/IEC 29143-certified suppliers from qualification-pending entrants, while volume scale and archival life ratings further stratify contract values. Cost compression in rewritable media intensifies because phase-change material costs limit supplier bases. Financial services firms in London exhibit least price sensitivity due to regulatory retention mandates, whereas consumer electronics channels face greatest pressure from digital delivery alternatives.
Supply Chain Analysis
Eighteen-month lead times for halogen-free photoinitiator reformulation constrain European resin suppliers under ECHA restrictions. Manufacturing gravity centers on Japan's Yamanashi Prefecture and China's domestic foundry capacity, with rare-earth magnet processing tethered to Chinese facilities. Photopolymer chemistry, precision optical pickup assemblies, and collinear holography encoder components constitute critical input dependencies. Single-source vulnerability runs through rare-earth magnet supply chains. Distribution flows through OEM system integrators for bundled hardware-media sales and direct photopolymer contracts for enterprise disintermediation.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fourier optics expertise concentrates among Japanese and German research institutions, creating acute scarcity for collinear holography system design capabilities that extends certification timelines and inflates engineering premiums.
For Market Incumbents: Secure backward integration into photopolymer resin supply to defend margin structures against enterprise disintermediation. Add foundry capacity in Yamanashi Prefecture to capture METI subsidy flows and compress lead times for hyperscale contracts. Threat from LTO-9 tape latency advantages demands parallel read-write R&D investment to narrow access speed gaps. For New Entrants and Emerging Players: ISO/IEC 29143 fast-track certification in Mumbai assembly operations captures first-mover advantage under CERT-In data localization mandates. Medical imaging archives in Japan's radiology departments offer most penetrable vertical with DICOM-compliant immutability requirements underserved by incumbent focus on hyperscale operators. Go-to-market through direct photopolymer supply contracts bypasses OEM margin compression. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified photonics conglomerates with stranded optical media assets lacking holographic recording layer capabilities. Five-to-ten year viability hinges on air-gapped archival demand persistence against quantum storage emergence. Signal to monitor: hyperscale operator unbundling velocity in direct media sourcing agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photopolymer Chemistry | Captive resin supply insulates margin structures from ECHA reformulation cycles and rare-earth volatility. |
| Dual Certification Track Maintenance | Parallel ISO/IEC and GB/T qualification preserves access to Chinese state-owned cloud procurement. |
| Collinear Holography Encoder Development | Single-lens assemblies halve optical path complexity for Singapore and Dublin data center pilots. |
| Quantum Encryption Convergence | Write-once holographic media paired with quantum key distribution addresses sovereign cloud specifications. |
| Mumbai Assembly Establishment | CERT-In compliance for domestic financial record storage creates localized supply advantage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center procurement officers, photopolymer chemistry R&D directors, optical system integration engineers, and regulatory compliance leads at storage technology vendors. Secondary validation drew from FCC equipment authorization filings, METI photonics roadmap disclosures, ECHA restriction updates, and hyperscaler capex disclosures. Customs data on rare-earth magnet trade flows and ISO/IEC certification registries provided additional triangulation. Bottom-up segment builds and top-down macro anchoring were reconciled across approaches.
Across the projection horizon, the analytical framework modeled holographic data storage capacity by product format, technology tier, end-user vertical, and application maturity. Segmentation dimensions included read-only versus rewritable versus writable versus hybrid configurations, collinear versus traditional holography architectures, data center versus consumer electronics versus film industry versus research institution demand pools, and data archiving versus backup versus multimedia storage use cases. CAGRs were derived from installed base progression and replacement cycle analysis. Forecast inputs incorporated archival life rating improvements and air-gapped security premium persistence.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale cold storage expansion and stable rare-earth magnet supply chains; material deviation in quantum storage viability or Chinese export restrictions would warrant model refresh. Specific risk factors include REACH formulation constraint escalation, LTO tape latency gap narrowing failure, and holographic interchange standard fragmentation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Optical Disk Market
Data Storage
Hardware Storage Market
Data Storage
Germany Data Center Storage Market
Data Storage
Storage Virtualization Market
Data Storage
Data Storage Market
Data Storage
Transparent Cache Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
Channel Storage Systems Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Blu-Ray Drive Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Object-Based Storage Market
Data Storage
Storage Class Memory Market
Data Storage
Solid State Array Market