
 Blu-Ray Drive Market | 2026-2036
Blu-Ray Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Blu-Ray Drive Market Insights
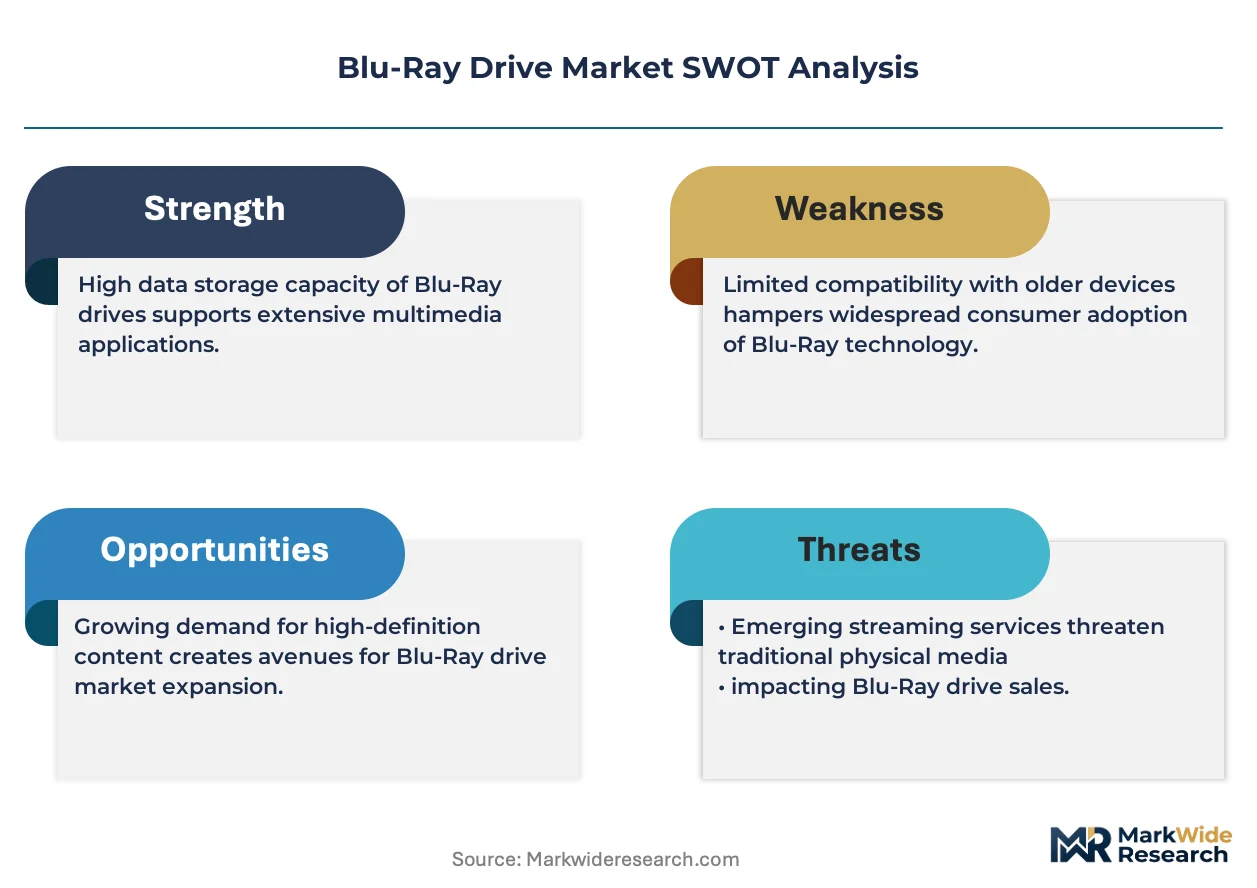
The Blu-Ray Drive Market is pivoting between premium UHD archival systems and commodity-grade internal drives for legacy PCs. Sony Corporation leverages its semiconductor expertise to sustain dominance in professional mastering equipment. Panasonic Corporation anchors its position through broadcast-grade drive reliability. LG Electronics competes in slim external drives for home theater enthusiasts.
A Blu-Ray drive is an optical disc drive employing a 405 nm blue-violet laser diode to read and write data on polycarbonate discs with 25 GB single-layer or 50 GB dual-layer capacity, primarily serving long-term data archiving and high-definition media distribution. External drives command durable margin pools among media production houses requiring field portability, while UHD drives lead technology migration as studios release 4K physical masters. BD-R write-once media sustains institutional archiving where rewrite cycles are unnecessary.
The US FCC governs electromagnetic emissions from drive electronics, while Japan's METI enforces standby power limits that raise design costs for domestic suppliers. The EU RoHS directive restricts hazardous substances in optical drive assemblies, compressing material sourcing flexibility. Stakeholders must weigh optical archival durability against solid-state cost curves when committing to long-format preservation infrastructure.
Market Dynamics
The Blu-Ray Drive Market faces structural compression from cloud storage cost curves, yet archival data centers sustain demand for optical durability where magnetic degradation poses unacceptable risk. Japan's METI standby power mandates raise design costs for domestic suppliers while preserving manufacturing capability.
Growth Catalysts
- Archival Data Center Demand:Cloud backup pricing volatility drives institutional buyers toward write-once optical media for immutable long-term retention. Facilities in Germany and Japan prioritize polycarbonate disc durability over tape degradation cycles.
- Broadcast Master Preservation:German public broadcasters mandate physical master archives alongside digital distribution, sustaining professional-grade drive procurement. This institutional requirement buffers against streaming-only infrastructure risks.
- REACH Compliance Differentiation:EU RoHS substance restrictions favor established suppliers with certified supply chains, creating regulatory moats against commodity competitors. Compliant assemblies command durable margin pools in European public sector tenders.
Market Restraints
- Semiconductor Input Volatility:Blue-violet laser diode fabrication depends on gallium nitride substrate availability concentrated in East Asian foundries. Price swings in III-V compound materials compress assembly margins unpredictably.
- Solid-State Substitution Threat:Enterprise-grade NVMe storage arrays now undercut optical cost-per-gigabyte at 5-year total cost of ownership horizons. Data center procurement committees increasingly disqualify optical for active-tier workloads.
- METI Standby Power Friction:Japan's energy-efficiency standards impose circuit redesign burdens that domestic manufacturers absorb while import competitors face certification delays. This regulatory asymmetry constrains price competition in the Japanese market.
Strategic Opportunities
- Media Production Field Portability:External UHD drives enable on-location 4K mastering for streaming content producers operating outside fixed facility infrastructure. Production houses in California and London deploy ruggedized units for dailies backup.
- Cultural Heritage Digitization Mandates:National film archives in France and Italy receive government funding for physical-to-digital preservation workflows. These programs specify archival-grade BD-R media with 50-year longevity ratings.
- Hybrid Cloud-Optical Architectures:Air-gapped optical storage satisfies ransomware recovery requirements that pure cloud configurations cannot guarantee. Financial institutions in Switzerland and Singapore specify optical WORM layers for compliance archives.
Industry Challenges
- Laser Optics Calibration Expertise:Precision alignment of 405 nm diodes requires specialized technicians whose training pipelines have narrowed as consumer DVD assembly migrated offshore. Remaining facilities compete for scarce metrology talent.
- Legacy Interface Integration:Modern production workstations increasingly omit SATA and USB-A ports, forcing adapter-dependent connectivity for archival drive deployment. Integration friction slows refresh cycles in institutional buyer segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blu-Ray Drive Market |
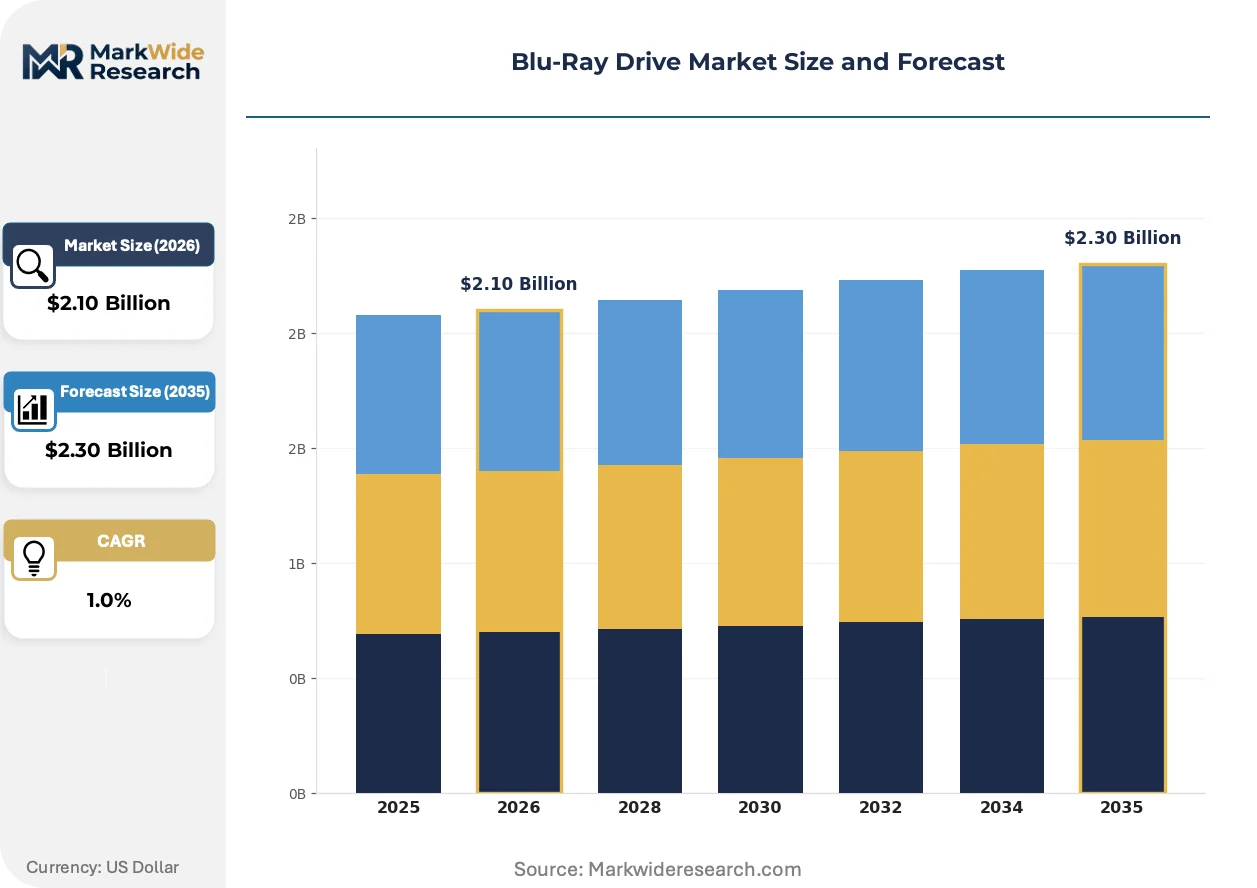
| Market Size in 2026 | $2.10 Billion |
| Market Size in 2035 | $2.30 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Drives, External Drives, UHD Drives, Portable Drives Technology: BD-ROM, BD-R, BD-RE, BD-RDL End User: Home Users, Businesses, Educational Institutions, Media Production Form Factor: Standard, Slim, Ultra Slim, Rack-Mount |
| Companies Covered | Sony Corporation, Panasonic Corporation, LG Electronics, Samsung Group, Pioneer Corporation, Cambridge Audio, Koninklijke Philips N.V., RITEK Corporation, Magnetar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blu-Ray Drive Market Trends and Innovations
Optical storage technology is bifurcating between premium archival systems and residual consumer hardware, with innovation concentrating on longevity validation and energy efficiency rather than capacity expansion.
Multi-layer BD-XL technology is converging with automated library robotics to enable petabyte-scale optical archives without manual disc handling. Japanese broadcast equipment integrators deploy these configurations for regulatory-mandated program retention. The convergence is compressing operational labor costs while extending optical relevance against tape-based alternatives.
EU RoHS substance restrictions are tightening exemptions for legacy optical drive components, forcing material substitutions in polycarbonate substrates and solder alloys. German drive assemblers face reformulation timelines that extend procurement cycles by 8-12 months. Professional mastering equipment suppliers absorb these compliance costs while commodity internal drive manufacturers exit the European market entirely.
Media preservation procurement is consolidating toward certified archival workflows with explicit chain-of-custody documentation. French national archives and US Library of Congress specifications now require vendor-provided longevity testing data rather than manufacturer claims alone. This documentation burden favors established Japanese and German suppliers with in-house accelerated aging laboratories over emerging competitors.
Blu-Ray Drive Market Segmentation
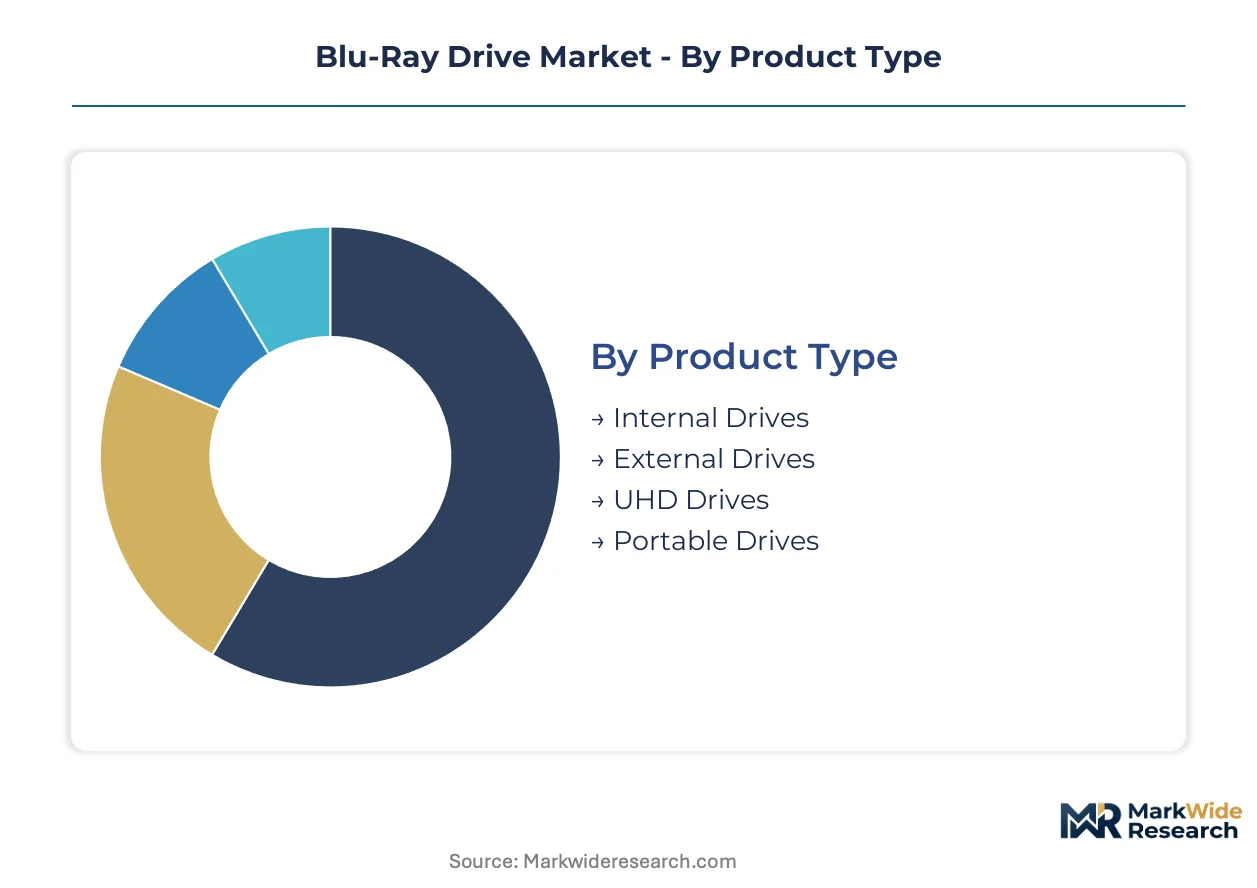
Blu-Ray drive segmentation reflects divergent technical requirements between archival durability and consumer convenience. Procurement patterns split between institutional buyers prioritizing media longevity and residual consumer demand for legacy playback compatibility.
Product Type:
Drive enclosure architecture determines thermal management capacity and field deployment flexibility across use cases.
- Internal Drives:5.25-inch SATA bay-mounted units integrate directly into workstation chassis for fixed facility archiving. German broadcast mastering suites specify these configurations for 24/7 write-cycle reliability in climate-controlled environments.
- External Drives:Self-cooled enclosures with USB-C or Thunderbolt connectivity enable mobile production workflows. California streaming content houses deploy ruggedized units for on-location 4K dailies backup where facility infrastructure is unavailable.
- UHD Drives:Support 4K Blu-ray playback with HDCP 2.2 compliance for premium home theater installations.
- Portable Drives:Bus-powered slim enclosures prioritize luggage-friendly dimensions for traveling media professionals.
Mature deployment sits with Internal Drives in fixed archival facilities. Newer deployment is concentrated in External Drives for distributed production workflows.
Technology:
Write-cycle specifications differentiate immutable archiving from rewritable production workflows.
- BD-ROM:Read-only factory-pressed discs deliver content distribution with zero write capability. Japanese anime distributors maintain pressing capacity for collector editions where streaming rights fragment territorially.
- BD-R:Write-once organic dye or inorganic phase-change recording layers suit regulatory-mandated WORM compliance. Swiss financial institutions specify these for ransomware-proof air-gapped recovery archives.
- BD-RE:Rewritable phase-change media enables iterative mastering revisions in post-production pipelines.
- BD-RDL:Dual-layer 50GB capacity addresses feature-length 4K mastering without disc spanning.
Procurement volume concentrates in BD-R for compliance archiving. Technology migration is accelerating toward BD-RDL as 4K mastering becomes standard.
End User:
Buyer sophistication spans consumer hobbyists to certified archival institutions with explicit chain-of-custody requirements.
- Home Users:Residual demand concentrates among physical media collectors and regions with unreliable broadband infrastructure. Japanese consumers sustain niche premium for anime collector editions with exclusive bonus content.
- Businesses:Enterprise procurement prioritizes total cost of ownership over unit price for 10-year retention mandates. Singapore data centers specify optical WORM layers for financial services compliance.
- Educational Institutions:University libraries balance preservation budgets against digitization backlogs for aging magnetic tape collections.
- Media Production:Post-production houses require broadcast-grade drive reliability for master delivery to streaming platforms.
Contracting demand sits with Home Users as streaming penetration deepens. Institutional procurement is expanding fastest in Media Production for 4K mastering workflows.
Form Factor:
Physical dimensions trade thermal headroom against spatial constraints in rack-dense facilities and mobile deployments.
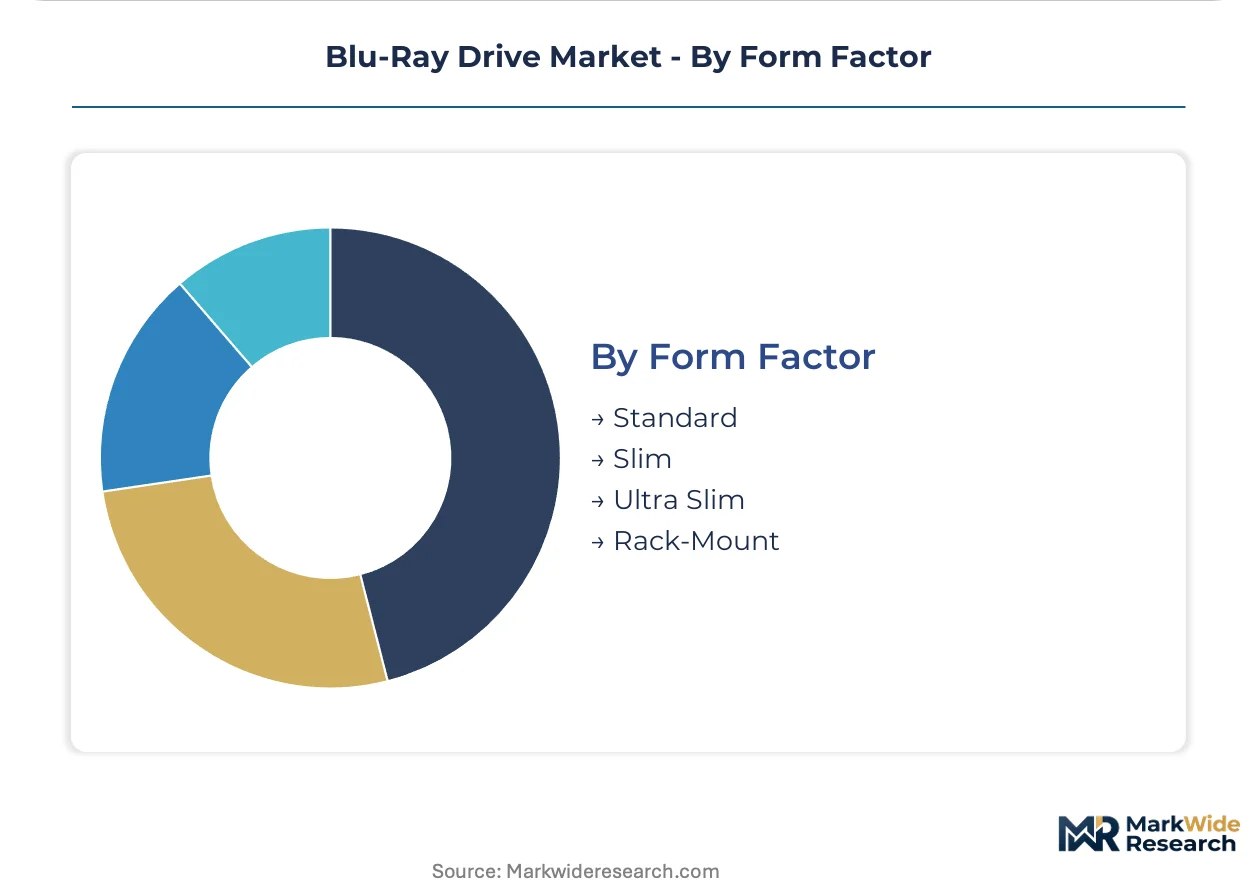
- Standard:Full-height 5.25-inch enclosures maximize heat dissipation for continuous write operations. German public broadcaster archives specify these for 18-hour daily ingest cycles.
- Slim:12.7mm height suits compact workstations where bay depth is limited. London post-production boutiques favor these for edit suite integration.
- Ultra Slim:9.5mm profile enables laptop optical bay retrofits for legacy compatibility workflows.
- Rack-Mount:19-inch chassis integration supports automated library robotics in petabyte-scale archives. Japanese broadcast equipment integrators deploy these for regulatory-mandated program retention.
Volume production concentrates in Slim form factors for workstation integration. Rack-Mount configurations are gaining share fastest in automated archival robotics deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's broadcast equipment corridor anchors professional mastering demand, with Japanese manufacturers supplying archival drives to domestic data centers and European preservation facilities. German public broadcasters in Cologne and Munich sustain procurement for physical master archives. California post-production houses deploy ruggedized external units for streaming content workflows.
Japan
Domestic data centers and broadcast archives sustain demand for high-reliability internal drives. METI standby power regulations impose circuit redesign costs that domestic manufacturers absorb while import competitors face certification delays. Tokyo and Osaka house the remaining precision optics calibration facilities serving professional mastering equipment.
Germany
Public broadcasters in Cologne and Munich mandate physical master archives alongside digital distribution, buffering procurement against streaming-only infrastructure risks. EU RoHS substance restrictions favor established suppliers with certified supply chains in European tenders. Baden-Württemberg assembles broadcast-grade drives for regional public sector contracts.
United States
California streaming content houses deploy ruggedized external UHD drives for on-location 4K dailies backup outside fixed facility infrastructure. FCC electromagnetic emissions standards govern drive electronics certification for domestic deployment. Los Angeles post-production boutiques integrate slim-form drives into edit suites for master delivery to platforms.
Switzerland
Financial institutions in Zurich and Geneva specify optical WORM layers for ransomware-proof air-gapped compliance archives. Swissmedic-equivalent financial regulators enforce immutable retention mandates that optical storage satisfies. Basel data centers procure BD-R media for hybrid cloud-optical architectures.
France
National film archives in Paris and Lyon receive government funding for physical-to-digital preservation workflows specifying archival-grade BD-R media. ANSM/CNIL-equivalent cultural heritage programs require vendor-provided longevity testing data. Île-de-France preservation laboratories validate 50-year media ratings for institutional tenders.
Blu-Ray Drive Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure separating professional mastering equipment from commodity external drives. The market concentrates around semiconductor-integrated manufacturers and specialized broadcast equipment suppliers. Strategic archetypes include precision optics specialists, consumer electronics conglomerates with optical legacy units, and regional assembly houses serving institutional tenders. Dominant competitive moves encompass vertical integration into laser diode supply and geographic expansion toward European public sector procurement.
Among Japanese conglomerates with optical heritage, Sony Corporation and Panasonic Corporation exemplify the precision-tier archetype, while LG Electronics represents the consumer electronics legacy positioning. Sony Corporation occupies a position within professional mastering equipment where semiconductor expertise sustains dominance. Panasonic Corporation anchors broadcast-grade reliability requirements through integrated manufacturing. LG Electronics sits within the slim external drive segment serving residual home theater demand.
| Leading Market Players |
|---|
| Sony Corporation |
| Panasonic Corporation |
| LG Electronics |
| Samsung Group |
| Pioneer Corporation |
| Cambridge Audio |
| Koninklijke Philips N.V. |
| RITEK Corporation |
| Magnetar |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap Japanese optics specialists anchor professional-grade drive manufacturing, translating concentrated precision-laser expertise into pricing discipline that resists commoditization pressures from Taiwanese contract assemblers. Their captive control over gallium nitride substrate sourcing tightens margin pools for archival-grade equipment while forcing import competitors into extended METI certification timelines that compress their pricing flexibility.
Pricing Analysis
Uptime-guaranteed service contracts anchor value-based pricing for broadcast-grade installations, separating premium-tier Japanese suppliers from economy-focused Taiwanese and Chinese producers. Three-tier pricing structure across archival certification, professional mastering, and residual consumer levels reflects differentiation by longevity testing documentation and METI compliance status. Cost compression in consumer internal drives is intensifying because solid-state substitution erodes PC OEM attachment rates. Educational institutions exhibit highest price sensitivity due to digitization budget constraints, while Swiss financial compliance buyers absorb premiums for WORM-certified configurations.
Supply Chain Analysis
Dual-sourcing requirements from German public broadcasters and Japanese data centers mandate multi-supplier qualification for gallium nitride substrates and precision optical pickups, preventing single-source concentration despite Taiwan's dominance in III-V compound foundries. Blue-violet laser diode fabrication rests on gallium nitride substrates, polycarbonate disc substrates, and phase-change recording alloys concentrated in Japan, Taiwan, and South Korea. Single-source vulnerability persists in specialized metrology equipment for 405 nm diode alignment. Distribution runs through broadcast equipment integrators in Tokyo and post-production supply houses in Los Angeles rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in precision optics calibration talent prop pricing power for incumbent Japanese manufacturers, insulating archival-grade segments from solid-state cost curves while compressing margins in commoditized consumer tiers.
For Market Incumbents: Deploy backward integration into gallium nitride substrate supply to defend against III-V compound price volatility from East Asian foundries. Lock in long-term service contracts with German public broadcasters and Swiss financial institutions before NVMe arrays erode 5-year TCO advantages for compliance archiving. Counter emerging Chinese contract assemblers by accelerating EU RoHS certification timelines that delay their European tender eligibility. For New Entrants and Emerging Players: The price-point gap between Japanese archival certification premiums and Taiwanese economy drives creates entry space for mid-tier suppliers offering documented longevity testing without broadcast-grade reliability margins. Target university digitization programs in France and Italy where government preservation funding sustains procurement despite budget constraints. Pursue white-label partnerships with California streaming content houses seeking ruggedized external units for field production workflows. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision optics specialists with in-house accelerated aging laboratories in Baden-Württemberg or Île-de-France as cloud cost compression forces commodity drive assemblers toward exit. Long-term viability hinges on hybrid cloud-optical architectures penetrating financial compliance verticals beyond current Swiss and Singapore adoption. Monitor ransomware incident frequency at financial institutions as the inflection signal for optical WORM layer procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Diode Supply | Captive gallium nitride sourcing insulates Japanese manufacturers from III-V compound price swings. |
| EU RoHS Certification Acceleration | Faster compliance timelines create regulatory moats against Taiwanese and Chinese commodity competitors. |
| Hybrid Cloud-Optical Architecture Partnerships | Swiss and Singapore financial institutions specify optical WORM layers for ransomware-proof compliance. |
| University Digitization Program Capture | French and Italian government-funded preservation workflows specify archival-grade BD-R media procurement. |
| Field Production Ruggedization | California streaming houses deploy external UHD drives for on-location 4K dailies backup outside facilities. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with broadcast equipment procurement managers, post-production technical directors, data center infrastructure leads, and archival preservation officers. METI standby power compliance databases, FCC electromagnetic emissions certifications, and EU RoHS substance restriction filings provided regulatory boundary conditions. Bottom-up shipment data from Japanese and German drive assemblers triangulated against top-down demand estimates from national film archive digitization program budgets.
Data-stream reconciliation across product type, technology write-cycle specifications, end-user sophistication tiers, and form factor thermal constraints shaped the analytical framework over the projection horizon. CAGRs derived from institutional procurement cycle analysis and consumer replacement rate modeling. Forecast inputs incorporated cloud storage pricing volatility indices and solid-state cost curve trajectories from hyperscaler capex disclosures.
Inputs from Japanese broadcast equipment trade associations and German public broadcaster procurement portals were available through the study window; gaps in Chinese contract assembler production data introduce uncertainty bands around economy-tier volume estimates. Forecasts reflect documented assumptions regarding METI regulatory stability and III-V compound supply continuity. A model refresh is warranted upon material change in enterprise NVMe TCO competitiveness against optical archival configurations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
USB 3.1 Flash Drive Market
Data Storage
Data Storage Devices Market
Data Storage
Enterprise Hard Drive Market
Data Storage
AI Powered Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Transparent Caching Market
Data Storage
Americas Flash Memory Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Multiprotocol Storage Market
Data Storage
Data Center Ssds Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Portable Storage Device Control Software Market