
 Heat-Assisted Magnetic Recording (HAMR) Device Market | 2026-2036
Heat-Assisted Magnetic Recording (HAMR) Device Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Assisted Magnetic Recording (HAMR) Device Market Foresight
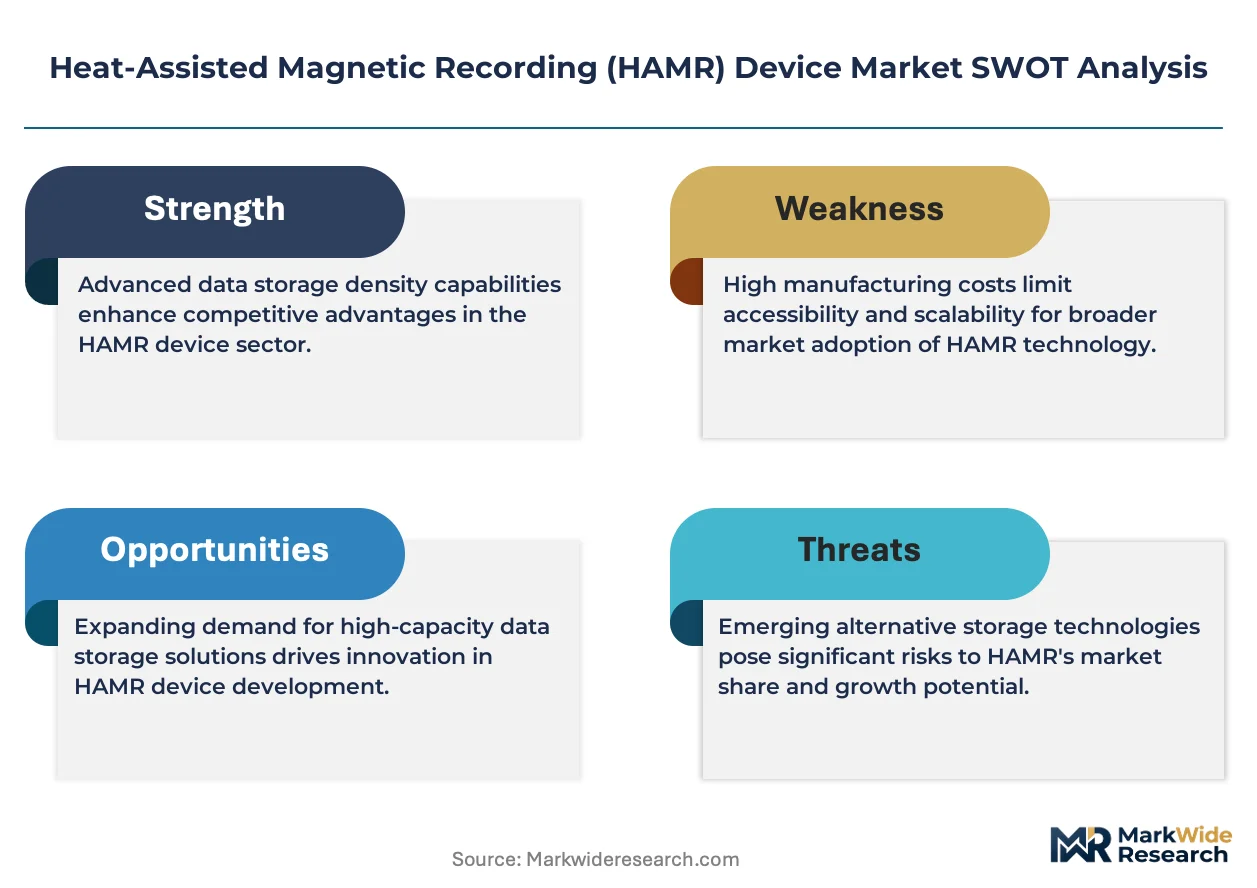
Platinum-alloy media specifications is unwinding the baseline cost structure for conventional perpendicular recording. Seagate Technology leverages in-house laser diode integration to control thermal spot precision. Western Digital Corporation anchors its roadmap on helium-sealed platforms paired with HAMR heads. Toshiba Corporation specializes in enterprise-grade firmware optimization for nearline workloads.
Heat-Assisted Magnetic Recording (HAMR) devices employ a near-field transducer to momentarily heat magnetic grains above their Curie temperature during write operations, enabling areal densities beyond 2 Tbit per square inch on cobalt-platinum granular media. The technology serves primary commercial purpose in high-capacity enterprise hard drives where bit-patterned media and thermally stable recording layers extend drive lifecycles under continuous operation. Internal drives command the dominant margin pool as hyperscale operators standardize on direct-attached storage architectures, while data center end users represent the fastest-expanding demand segment as rack-scale deployments displace tape for active archival tiers. Optical technology subsystems face supply constraints due to precision lenslet manufacturing, whereas magnetic layer deposition processes remain the most mature cost center.
The EPA Energy Star program and FCC electromagnetic emissions standards constrain thermal actuator power budgets and RF shielding designs for HAMR-enabled drives sold in the United States. Japan's METI circular economy directives and RoHS substance restrictions in Europe impose material substitution requirements on rare-earth dopants in recording media. Stakeholders must monitor thermal reliability certification timelines and wafer-level test capacity as production transitions from pilot lines to volume manufacturing.
Market Dynamics
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are consolidating procurement around direct-attached storage architectures, compressing vendor margins while driving volume commitments for heat-assisted magnetic recording platforms.
Growth Catalysts
- Cloud storage density mandates:Hyperscale operators require areal densities beyond 2 Tbit per square inch for active archival tiers, pulling HAMR deployment timelines forward.
- Japan's METI energy efficiency standards:Thermal management innovation in drive manufacturing accelerates as METI directives impose power-per-terabyte thresholds on data infrastructure.
- Helium-sealed platform maturation:Reduced aerodynamic drag in sealed enclosures enables thinner media stacks, extending drive capacity without proportional footprint expansion.
Market Restraints
- Precision lenslet supply concentration:Optical subsystem manufacturing depends on a limited supplier base in Japan and Germany, creating single-source vulnerability for near-field transducer optics.
- Cobalt-platinum media cost volatility:Platinum-alloy granular media specifications unwind conventional perpendicular recording cost structures, exposing margins to precious metal price swings.
- FCC electromagnetic emissions compliance:RF shielding designs for HAMR-enabled drives face stringent power budget constraints under United States electromagnetic compatibility standards.
Strategic Opportunities
- Nearline workload firmware optimization:Enterprise-grade firmware tuning for continuous read/write patterns creates differentiation in rack-scale deployments displacing tape systems.
- Wafer-level test capacity expansion:Pilot-to-volume manufacturing transitions unlock captive test infrastructure investments in Taiwan and South Korea.
- RoHS substance substitution incentives:European rare-earth dopant restrictions accelerate material science partnerships for compliant recording media formulations.
Industry Challenges
- Thermal reliability certification timelines:Extended validation cycles for laser diode integration delay product qualification with hyperscale procurement calendars.
- Near-field transducer integration complexity:Legacy drive controller architectures require substantial redesign to accommodate nanosecond-scale thermal spot timing precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat-Assisted Magnetic Recording (HAMR) Device Market |
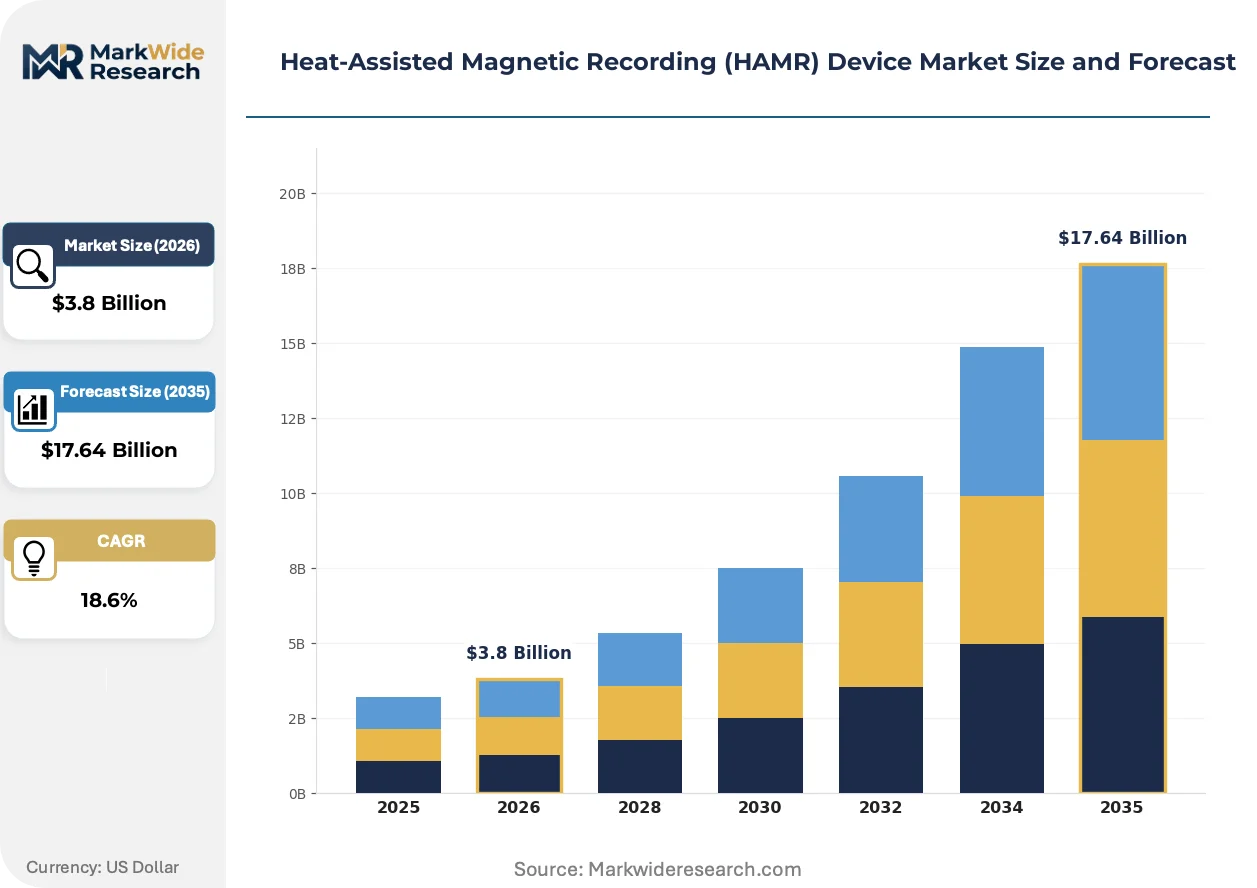
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Drives, External Drives, SSDs, Hybrid Drives End User: Enterprise, Consumer, Data Centers, Cloud Storage Technology: Optical, Electrical, Magnetic, Thermal Application: Backup Solutions, Data Recovery, Video Surveillance, Archival Storage |
| Companies Covered | Seagate Technology, Western Digital Corporation, Toshiba Corporation, TDK Corporation, Fujitsu, Showa Denko K.K., Samsung Electronics, Micron Technology, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Assisted Magnetic Recording (HAMR) Device Market Shifts & Advancements
Recording head architectures and thermal management subsystems are undergoing simultaneous redesign as areal density roadmaps collide with power consumption constraints in enterprise storage.
Near-field transducer designs are bifurcating between plasmonic antenna configurations and photonic wire alternatives. Hyperscale operators in the United States are piloting both approaches in limited deployments. The technology divergence is compressing supplier R&D budgets as dual-track development becomes necessary to secure design wins.
Japan's METI circular economy directives impose material substitution requirements on rare-earth dopants in recording media. Drive manufacturers must reformulate cobalt-platinum granular layers to maintain magnetic stability under reduced heavy-element content. Enterprise-grade product lines face the steepest compliance timelines as nearline workload certifications require extended validation.
Hyperscale procurement contracts now specify total-cost-of-ownership metrics rather than unit pricing. Direct-attached storage buyers in Northern Virginia and Dallas-Fort Worth negotiate power-per-terabyte and failure-rate guarantees over five-year operational horizons. This behavioral shift rewards vendors with integrated laser diode and thermal actuator control capabilities.
Heat-Assisted Magnetic Recording (HAMR) Device Market Segmentation
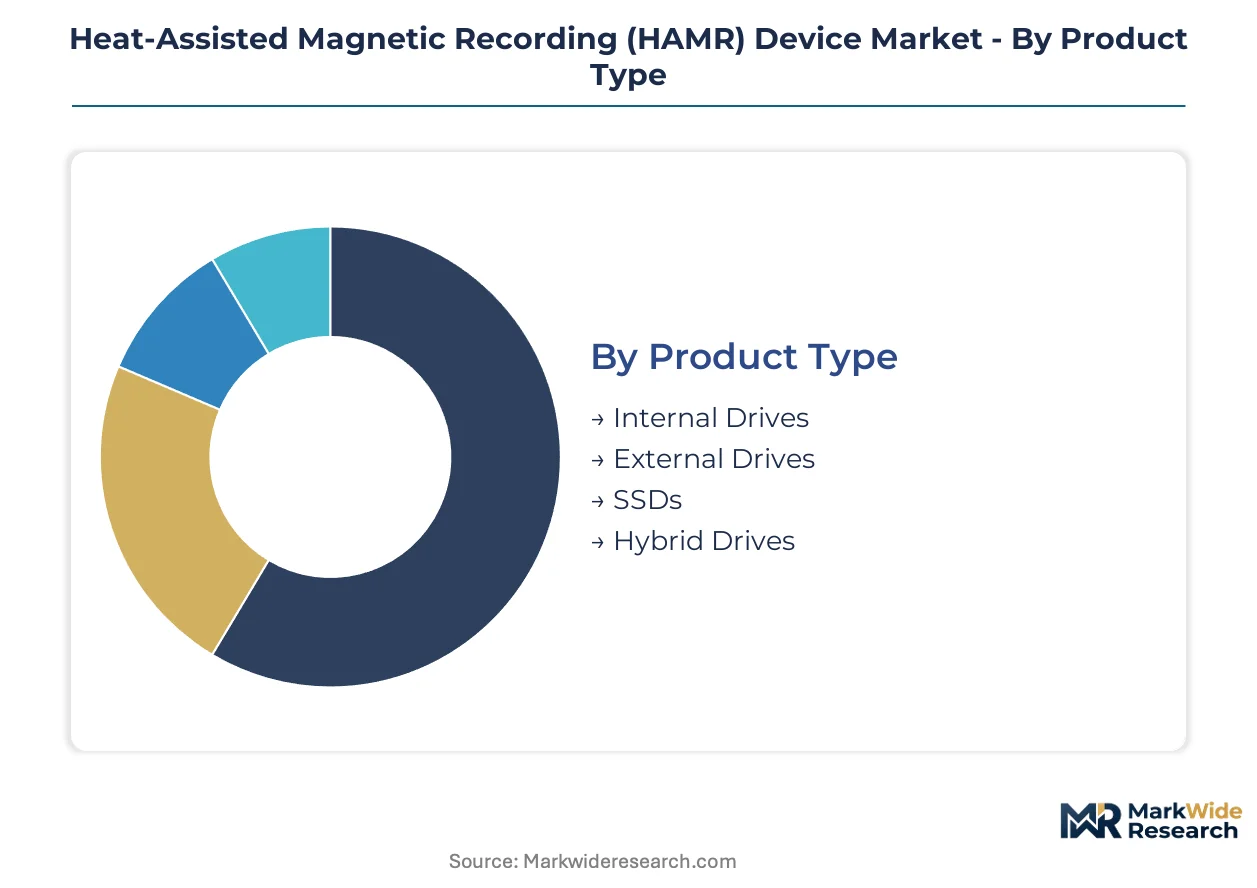
Segmentation in the Heat-Assisted Magnetic Recording (HAMR) Device Market reveals how procurement channels, technical specifications, and end-use requirements intersect. Understanding these divisions exposes where margin pools concentrate and which configurations align with hyperscale deployment timelines.
Product Type:
Channel flow diverges sharply between direct-attached storage procurement for hyperscale operators and retail distribution for smaller deployments.
- Internal Drives:Direct-mounted configurations in rack-scale servers employ helium-sealed enclosures with integrated laser diode subsystems. Hyperscale data centers in Northern Virginia and Dallas-Fort Worth standardize on these units for active archival tiers, compressing vendor margins through volume commitments while demanding five-year failure-rate guarantees.
- External Drives:Enclosed units with standalone power and cooling target enterprise backup workflows and media production houses. Japan's METI energy efficiency standards are accelerating thermal management innovation in this segment as power-per-terabyte thresholds tighten.
- SSDs:Solid-state alternatives compete for IOPS-intensive workloads but lack the areal density economics of HAMR platforms for petabyte-scale cold storage.
- Hybrid Drives:NAND cache layer paired with magnetic platters serves workstation markets where boot-time performance matters alongside bulk capacity.
Internal drives dominate installed base. External drives are where expansion concentrates for mid-market enterprise transitioning from tape systems.
End User:
Cost tier stratification separates capital-intensive hyperscale deployments from price-sensitive consumer procurement.
- Data Centers:Colocation and wholesale facilities deploy HAMR platforms for nearline storage tiers displacing LTO tape. Rack-scale buyers in the United States negotiate total-cost-of-ownership metrics including power-per-terabyte and thermal reliability certification timelines.
- Cloud Storage:Hyperscale operators require areal densities beyond 2 Tbit per square inch, pulling HAMR deployment timelines forward through direct vendor partnerships. These buyers command the steepest volume discounts while driving integrated laser diode and thermal actuator specifications.
- Enterprise:Corporate IT departments with on-premise infrastructure prioritize firmware optimization for continuous read/write patterns in nearline workloads.
- Consumer:Desktop and NAS applications represent residual demand as flash storage captures primary storage use cases.
Cloud storage commands the premium tier. Data centers are climbing the fastest as rack-scale deployments displace tape for active archival tiers.
Technology:
Supply concentration in optical subsystems creates single-source vulnerability while magnetic layer deposition remains the most mature cost center.
- Thermal:Near-field transducer and laser diode integration enables nanosecond-scale heating above Curie temperature during write operations. Precision lenslet manufacturing in Japan and Germany constrains supply availability for this critical subsystem.
- Optical:Plasmonic antenna and photonic wire configurations for near-field transducers are diverging in hyperscale pilot deployments, compressing supplier R&D budgets through dual-track development requirements.
- Magnetic:Cobalt-platinum granular media with rare-earth dopants provides thermally stable recording layers under continuous operation.
- Electrical:Redesigned drive controller architectures accommodate thermal spot timing precision and RF shielding for FCC electromagnetic emissions compliance.
Thermal subsystems anchor product differentiation. Optical technology is where supplier R&D investment concentrates most heavily.
Application:
Maturity gradient separates established backup workflows from emerging video surveillance storage requirements.
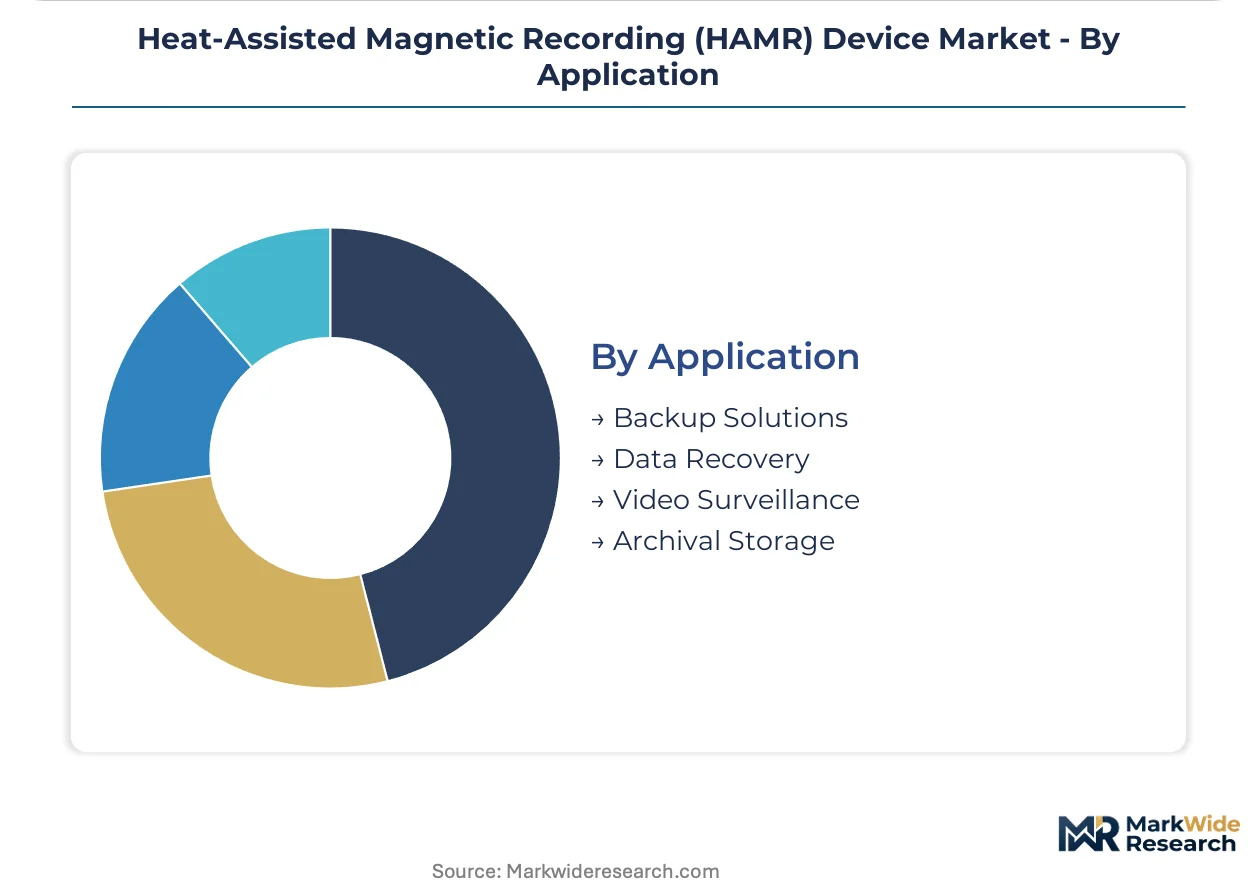
- Archival Storage:Long-retention data with infrequent access patterns leverages HAMR areal density for minimal footprint. Compliance-driven industries in the United States and Europe drive demand as retention periods extend under regulatory pressure.
- Backup Solutions:Enterprise disaster recovery infrastructure transitions from tape to disk-based systems, requiring enterprise-grade firmware optimization for continuous operation.
- Video Surveillance:Multi-petabyte retention requirements from municipal and commercial security networks are emerging as a volume segment as camera counts proliferate.
- Data Recovery:Specialized service providers maintain HAMR platforms for forensic extraction and damaged media reconstruction.
Archival storage dominates current revenue. Video surveillance is gaining share fastest as edge camera deployment accelerates storage buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision lenslet manufacturing concentrates in Japan and Germany, creating single-source vulnerability for near-field transducer optics. Hyperscale data center construction in the United States, Japan, and China pulls procurement volumes toward those markets. Regulatory pressure on power-per-terabyte metrics is accelerating thermal management innovation across all major demand centers.
United States
Northern Virginia and Dallas-Fort Worth hyperscale clusters drive concentrated procurement pull for direct-attached storage architectures. The EPA Energy Star program and FCC electromagnetic emissions standards constrain thermal actuator power budgets and RF shielding designs for HAMR-enabled drives. Rack-scale buyers in these metros negotiate total-cost-of-ownership metrics over five-year operational horizons.
Japan
METI energy efficiency standards for data infrastructure impose power-per-terabyte thresholds that accelerate thermal management innovation in drive manufacturing. METI circular economy directives also impose material substitution requirements on rare-earth dopants in recording media. Precision lenslet manufacturing clusters in Nagoya and Osaka supply critical optical subsystems to global drive assemblers.
Germany
RoHS substance restrictions in Europe impose material substitution requirements on rare-earth dopants in recording media, forcing reformulation of cobalt-platinum granular layers. German precision optics manufacturers in Jena and Munich supply near-field transducer components to drive makers. Enterprise IT departments prioritize firmware optimization for continuous read/write patterns in nearline workloads.
China
Hyperscale operators require areal densities beyond 2 Tbit per square inch for active archival tiers, pulling HAMR deployment timelines forward through direct vendor partnerships. GB standards and MIIT directives shape electromagnetic compatibility and energy efficiency certification requirements. Yangtze River Delta manufacturing clusters are expanding wafer-level test capacity as production transitions from pilot lines to volume manufacturing.
South Korea
Wafer-level test capacity expansion in Taiwan and South Korea unlocks captive test infrastructure investments as HAMR production scales. MFDS and related national regulators influence component import standards for optical subsystems. Seoul Capital Area data center operators are piloting both plasmonic antenna and photonic wire near-field transducer configurations in limited deployments.
Heat-Assisted Magnetic Recording (HAMR) Device Market Competitive Landscape
Concentration sits with integrated drive manufacturers controlling laser diode and thermal actuator supply chains. Three to four vertically integrated players dominate volume manufacturing, while specialized component suppliers occupy critical bottleneck positions in optical subsystems. Two strategic archetypes define competitive positioning: helium-sealed platform specialists and enterprise firmware optimizers. Capacity expansion in wafer-level testing and strategic partnerships for rare-earth material substitution represent the dominant competitive moves.
Among integrated drive manufacturers, Seagate Technology, Western Digital Corporation, and Toshiba Corporation anchor the competitive structure. Seagate exemplifies the laser diode integration archetype through in-house thermal spot precision control. Western Digital occupies a position within the helium-sealed platform tier, pairing sealed enclosures with HAMR head architectures. Toshiba represents the enterprise-grade firmware optimization specialist, targeting nearline workload certifications. Component suppliers including TDK Corporation and Showa Denko K.K. sit within the precision optics and magnetic media layers, respectively. Samsung Electronics and Micron Technology occupy positions in adjacent storage technologies that compete for IOPS-intensive workloads while lacking HAMR areal density economics.
| Leading Market Players |
|---|
| Seagate Technology |
| Western Digital Corporation |
| Toshiba Corporation |
| TDK Corporation |
| Fujitsu |
| Showa Denko K.K. |
| Samsung Electronics |
| Micron Technology |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Platinum-alloy media substitution for conventional perpendicular recording materials simultaneously relocates supply geography toward Japanese and German precision optics clusters while exposing drive manufacturers to precious metal price volatility that compresses margin structures across procurement tiers.
Pricing Analysis
FCC electromagnetic emissions standards dictate the pricing tier structure for HAMR-enabled drives sold in the United States, segmenting offerings across enterprise-certified, data center-qualified, and retail-configured levels. Price differentiation hinges on thermal reliability certification grade and helium-sealed enclosure specifications. Cost compression in the retail tier is intensifying because hyperscale volume commitments absorb premium component allocations. Cloud storage operators exhibit the lowest price sensitivity, while consumer desktop buyers face the steepest trade-offs between capacity and unit cost.
Supply Chain Analysis
Japan and Germany anchor precision lenslet manufacturing for near-field transducer optics, while Taiwan and South Korea expand wafer-level test capacity. The chain draws from cobalt-platinum granular media, rare-earth dopants, and laser diode subsystems. Single-source vulnerability in optical component fabrication creates structural risk for near-field transducer supply. Distribution runs through direct-attached storage procurement channels for hyperscale operators and distributor networks for enterprise IT departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HAMR device adoption sits in early-cycle expansion as hyperscale data center construction in Northern Virginia and Dallas-Fort Worth pulls deployment timelines forward through direct vendor partnerships.
For Market Incumbents: Compound laser diode integration capabilities through in-house thermal spot precision control to defend against plasmonic antenna alternative suppliers. Expand captive wafer-level test infrastructure in Taiwan and South Korea to secure qualification timelines against certification bottlenecks. Prioritize firmware optimization investments for nearline workload certifications that tape displacement demands. For New Entrants and Emerging Players: Anchor in video surveillance storage buildouts as municipal and commercial security networks multiply camera counts and petabyte retention requirements. Target mid-market enterprise transitioning from tape systems with external drive configurations emphasizing Japan's METI-compliant power-per-terabyte metrics. Pursue component supplier partnerships for precision optics rather than integrated drive manufacturing. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vertically integrated drive manufacturers with captive thermal actuator supply. Long-term viability across the analysis window depends on securing positions before wafer-level test capacity constraints harden. Acquisition candidates with rare-earth dopant substitution partnerships and METI circular economy compliance pathways warrant priority attention. Monitor hyperscale procurement contract structures shifting toward total-cost-of-ownership guarantees as the inflection signal for pricing power migration.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Diode Integration | In-house thermal spot precision control secures design wins with hyperscale operators in Northern Virginia. |
| Wafer-Level Test Capacity Expansion | Taiwan and South Korea investments unlock volume manufacturing transitions from pilot line constraints. |
| Rare-Earth Material Substitution Partnership | RoHS-compliant cobalt-platinum granular layer reformulation maintains magnetic stability under reduced heavy-element content. |
| Helium-Sealed Platform Maturation | Reduced aerodynamic drag enables thinner media stacks without proportional footprint expansion in rack-scale deployments. |
| Nearline Workload Firmware Certification | Enterprise-grade optimization for continuous read/write patterns differentiates offerings displacing LTO tape systems. |
Research Methodology
Operator-level perspectives from hyperscale data center procurement officers, drive manufacturing engineers, precision optics suppliers, and thermal subsystem specialists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through SEC filings from integrated drive manufacturers, EPA Energy Star certification databases, and METI circular economy directive documentation. Bottom-up unit economics triangulated against top-down hyperscale capex disclosure patterns across the analysis window.
Sensitivity analysis across deployment model, end-user scale tier, and regional regulatory cluster shaped the forecast framework. Segmentation dimensions modeled include product type, end-user category, technology subsystem, and application workload pattern. CAGRs derived from installed base replacement cycles and areal density roadmap milestones. Industry-specific inputs incorporated laser diode yield trajectories and precision lenslet manufacturing capacity constraints.
Decision-makers should treat outputs as directional under assumptions of sustained hyperscale data center construction and stable rare-earth supply availability; material deviation in platinum price volatility or thermal reliability certification timelines would warrant model refresh. Recalibration cycles align with shifts in FCC electromagnetic emissions enforcement and METI energy efficiency threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SAS Hard Disk Drives Market
Data Storage
Enterprise Hard Drive Market
Data Storage
Serial EEPROM Market
Data Storage
Flash Memory Market
Data Storage
Channel Storage Systems Market
Data Storage
Multiprotocol Storage Market
Data Storage
Data Center Ssds Market
Data Storage
NAND Flash Memory Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Flash-Based Array Market
Data Storage
External Storage Market
Data Storage
Next Generation Data Storage Market
Data Storage
Solid State Drive (SSD) Market
Data Storage
Holographic Versatile Disc (HVD) Market
Data Storage
Serial (SPI) NOR Flash Market