
 Indonesia Data Center Power Market | 2026-2036
Indonesia Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Power Market Insights
Software-defined power management is restructuring how Indonesian operators procure electrical infrastructure, shifting capital expenditure toward subscription-based energy optimization platforms. Schneider Electric SE leverages its integrated EcoStruxure architecture to anchor large-scale deployments across Cibitung and Bekasi. Vertiv Group Corp. competes through thermal-electrical co-design capabilities that reduce total facility energy overhead. Delta Electronics specializes in modular UPS systems suited to the fragmented, multi-phase buildouts common in secondary Indonesian cities.
Indonesia data center power encompasses the generation, conditioning, distribution, and backup electrical systems sustaining continuous server operations, typically operating at voltages from 380V to 480V with tiered redundancy from N+1 to 2N configurations. The primary purpose is eliminating downtime from grid instability that costs hyperscale operators millions in service-level agreement penalties. Diesel generators still dominate installed base capacity, though battery energy storage systems are capturing fastest growth as lithium-ion costs compress and BIS-equivalent safety certifications normalize. Liquid-cooling integration is reshaping power distribution design, as high-density racks above 30kW demand dedicated busway architectures rather than traditional panel distribution.
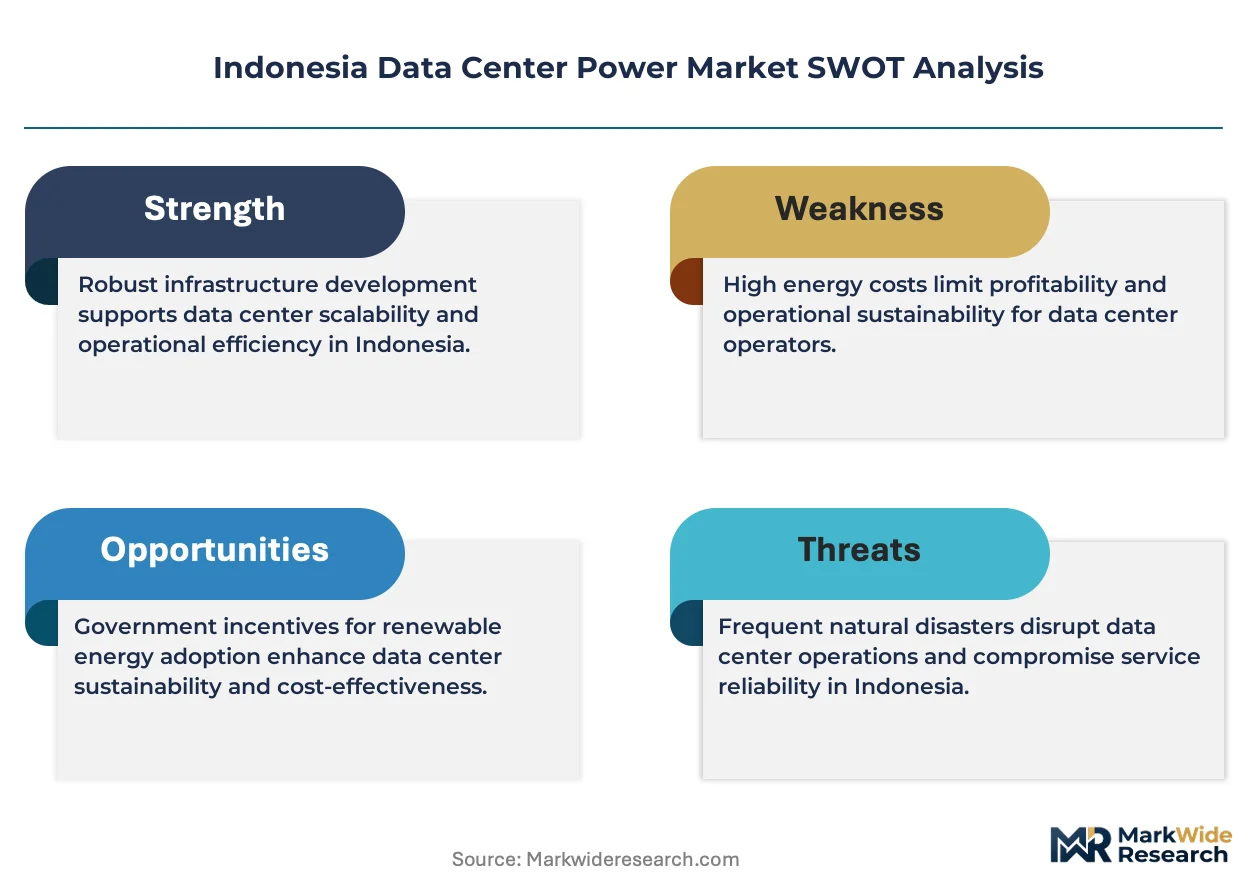
Indonesia's Ministry of Energy and Mineral Resources sets national electrical codes for data center construction, while the state utility PLN governs interconnection standards and backup generator emissions thresholds through regional operating permits. These frameworks push developers toward gas-turbine hybrids and solar-plus-storage configurations that satisfy both reliability mandates and Jakarta's air quality directives. Stakeholders must monitor how PLN's rural electrification priorities reshape grid availability timelines for Batam and Sulawesi greenfield projects.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles for redundant power architectures, forcing Indonesian developers to abandon phased buildouts in favor of simultaneous electrical and thermal infrastructure deployment across Java and Batam.
Growth Catalysts
- PLN Grid Modernization Mandates:State utility interconnection standards for data centers now prioritize facilities with on-site generation capacity, accelerating investment in gas-turbine hybrids and battery storage systems.
- BIS-Equivalent Safety Certification:Normalized lithium-ion battery standards are eliminating regulatory friction that previously delayed diesel-to-battery retrofits in existing Jakarta facilities.
- Hyperscale SLA Penalty Structures:Cloud operators' contractual downtime penalties measured in millions of dollars are compelling developers toward 2N redundant electrical architectures rather than N+1 minimums.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in Northeast Asian manufacturing hubs, exposing Indonesian operators to shipping cost volatility and extended lead times for BESS components.
- Land Scarcity in Greater Jakarta:Premium industrial zoned land costs in Cibitung and Bekasi are compressing facility footprints and forcing vertical construction that complicates generator fuel storage compliance.
- Diesel Generator Emissions Thresholds:Jakarta air quality directives are accelerating retirement timelines for existing genset fleets before battery storage alternatives achieve cost parity at scale.
Strategic Opportunities
- Batam Free Trade Zone Expansion:PLN's rural electrification timeline delays create first-mover advantage for developers establishing captive solar-plus-storage microgrids independent of mainland grid connections.
- Liquid-Cooling Busway Integration:Convergence of high-density rack architectures above 30kW with modular power distribution is opening specialized electrical infrastructure contracts for thermal-electrical co-design specialists.
- Sulawesi Greenfield Development:Underpenetrated secondary markets outside Java offer lower land acquisition costs and less stringent local emissions enforcement for initial deployment phases.
Industry Challenges
- Electrical-Thermal System Integration:Legacy facilities designed for 10-15kW rack densities face complex retrofit requirements when upgrading busway architectures to support liquid-cooled server deployments.
- Certification Timeline Compression:BIS-equivalent battery safety testing protocols require 12-18 month validation cycles that misalign with hyperscale operators' 6-9 month facility commissioning demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Power Market |
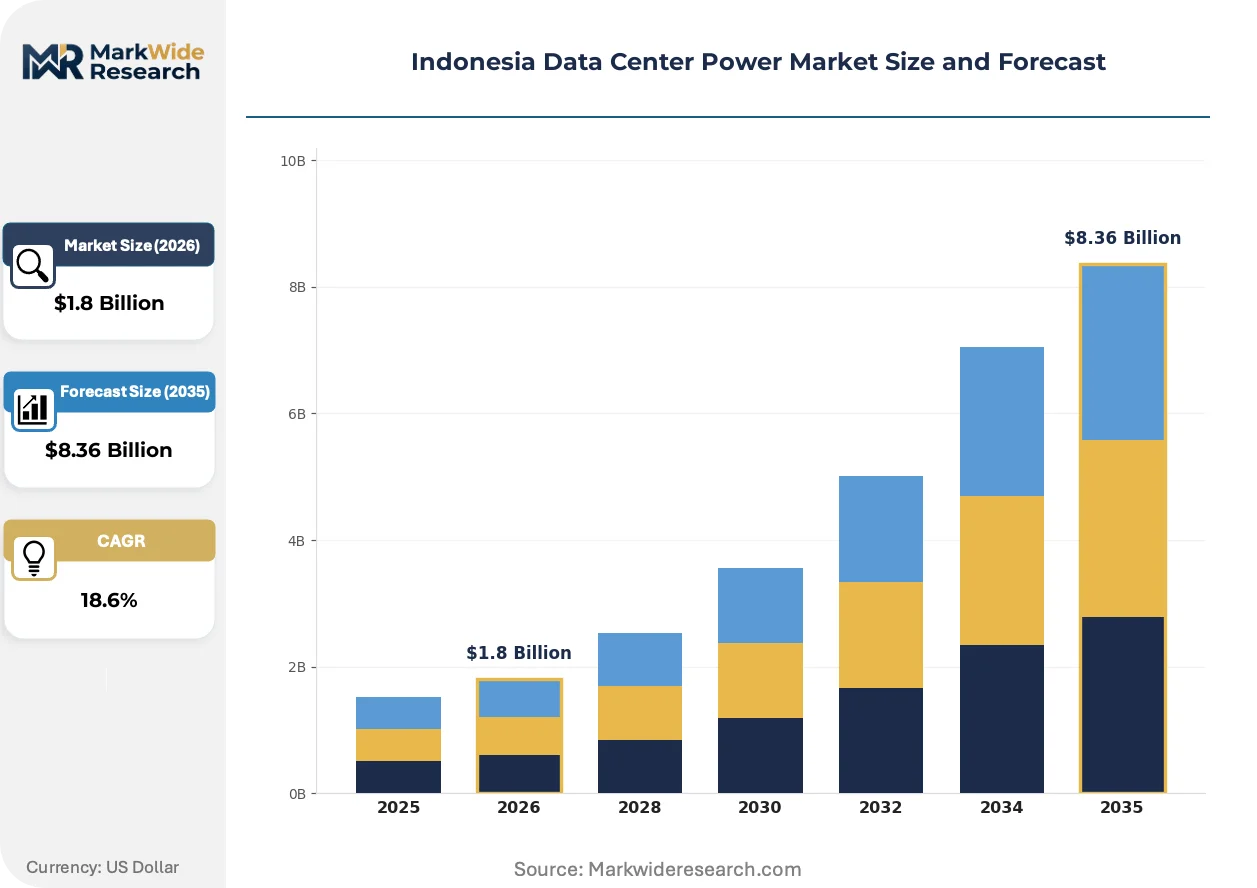
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Grid, Diesel Generator, Renewable, UPS Service Type: Colocation, Managed Services, Hybrid Cloud, Hosted Services Capacity: Small Scale, Medium Scale, Large Scale, Enterprise Scale Cooling Technology: Air-Cooling, Liquid-Cooling, Chilled Water, Free Cooling |
| Companies Covered | Schneider Electric SE, Vertiv Group Corp., ABB Ltd, Eaton Corporation plc, Cummins Inc., Delta Electronics, Rolls-Royce, Legrand, Hitachi Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Power Market Trends and Innovations
Software-defined control layers are displacing hardware-centric power management, enabling real-time load balancing across geographically distributed Indonesian facilities while compressing capital deployment timelines for multi-phase developments.
Modular uninterruptible power supply architectures are modularizing how Indonesian operators scale electrical capacity across fragmented buildouts. Secondary city developers in Surabaya and Medan are adopting containerized UPS systems to match capital expenditure with actual rack deployment rather than speculative overprovisioning. This approach is modularizing traditional procurement patterns and allowing phased commissioning without stranded asset risk.
Indonesia's Ministry of Energy and Mineral Resources is tightening emissions thresholds for backup generation through regional operating permits that govern diesel genset runtime hours. Industrial consequence includes accelerated depreciation schedules for existing generator fleets and mandatory fuel quality standards. Tier-III and Tier-IV facilities in Greater Jakarta are responding by procuring gas-turbine hybrids and solar-plus-storage configurations that satisfy both reliability mandates and local air quality directives.
Subscription-based energy optimization platforms are displacing capital-intensive hardware procurement for mid-tier colocation operators. Channel disruption concentrates among electrical infrastructure distributors as software vendors establish direct commercial relationships with facility managers. This pattern is most visible in Bekasi and Cibitung industrial corridors where land constraints force higher-density designs that benefit from predictive load management algorithms.
Indonesia Data Center Power Market Segmentation
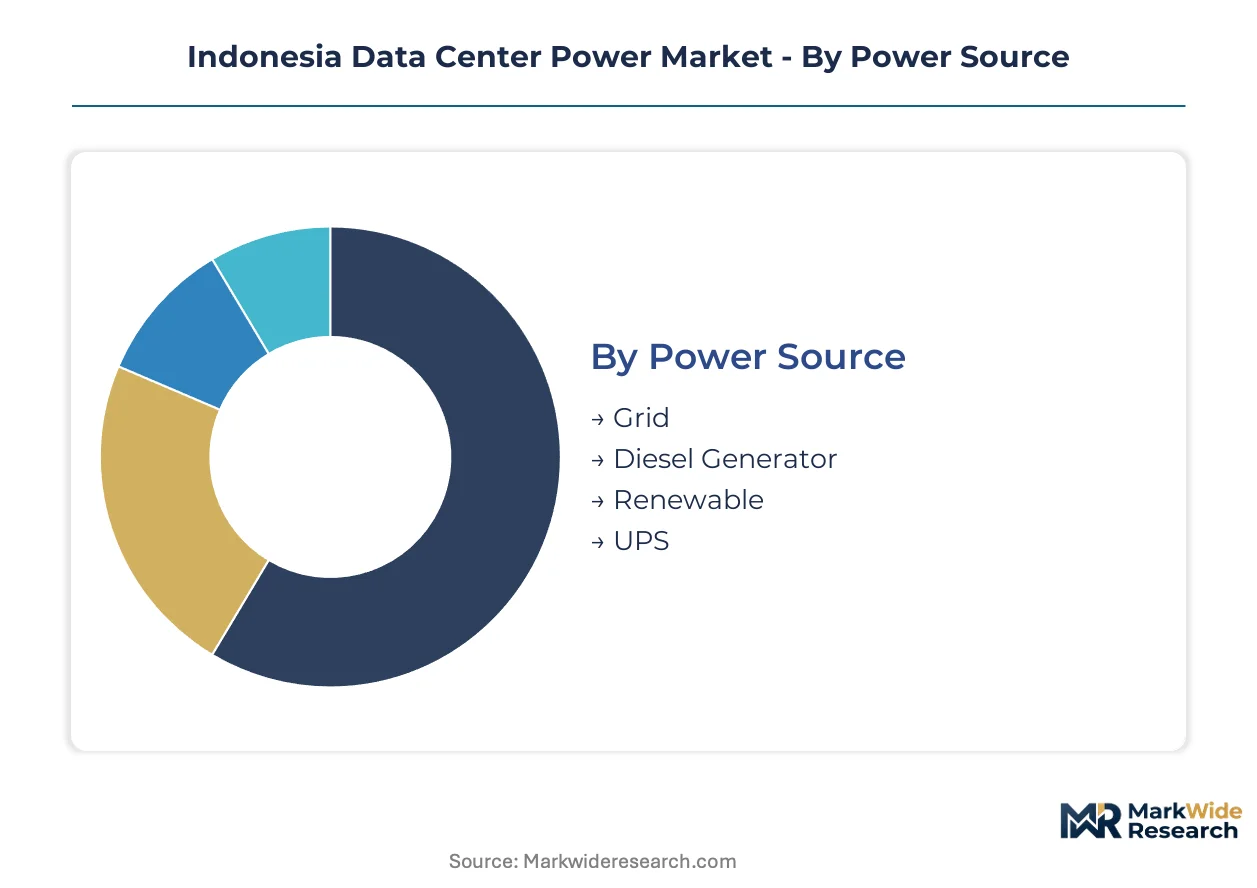
Indonesia data center power procurement fragments across four distinct dimensions that determine capital deployment patterns, operational cost structures, and regulatory compliance pathways. Each segmentation axis reveals divergent investment priorities between hyperscale cloud operators and domestic colocation providers. Understanding these splits enables equipment vendors to align product roadmaps with actual deployment trajectories rather than aggregate demand assumptions.
Power Source:
Volume deployments concentrate on legacy diesel backup systems, while premium procurement shifts toward battery hybrids and captive renewables as PLN interconnection standards tighten.
- Grid:Primary feedstock for facilities in Bekasi and Cibitung industrial corridors where PLN maintains dedicated substations for Tier-III certified operations. Grid instability in Greater Jakarta forces simultaneous investment in on-site generation capacity, inflating effective connection costs for developers.
- Diesel Generator:Dominates installed backup capacity across existing facilities, though Jakarta air quality directives are compressing permitted runtime hours and accelerating retirement timelines. Fuel storage compliance in vertical construction projects creates additional civil engineering overhead.
- Renewable:Capturing fastest growth in Batam Free Trade Zone where solar-plus-storage microgrids bypass mainland grid dependency. Captive generation configurations satisfy both BIS-equivalent safety mandates and national energy transition targets.
- UPS:Modular lithium-ion architectures are displacing traditional valve-regulated lead-acid systems in secondary city deployments across Surabaya and Medan. Containerized configurations match capital expenditure with actual rack commissioning rather than speculative overprovisioning.
Today's leader: Diesel Generator. Tomorrow's challenger: Renewable.
Service Type:
Customer control preferences split procurement between fully outsourced power management and retained operational responsibility.
- Colocation:Facilities in Greater Jakarta concentrate demand for redundant electrical architectures as multi-tenant operators absorb SLA penalty risk from hyperscale tenants. Power infrastructure becomes primary competitive differentiator in land-constrained Cibitung corridor.
- Managed Services:Subscription-based energy optimization platforms are restructuring how mid-tier operators procure electrical infrastructure, shifting capital expenditure toward software-defined load management. Channel disruption concentrates among electrical distributors as vendors establish direct facility manager relationships.
- Hybrid Cloud:Split workload architectures demand flexible power scaling across on-premise and off-premise capacity, favoring modular UPS and containerized generation that tracks actual compute deployment.
- Hosted Services:Legacy enterprise customers in secondary Indonesian cities retain traditional N+1 minimum configurations rather than hyperscale-grade 2N redundancy, preserving diesel generator dominance in Medan and Surabaya.
Colocation commands current procurement volume. Managed Services are climbing the fastest as operational outsourcing accelerates.
Capacity:
Facility scale determines redundancy architecture selection and generator fuel storage compliance complexity.
- Small Scale:Edge deployments in secondary cities favor containerized UPS and single-module generation to minimize stranded asset risk. Surabaya and Medan developers phase electrical infrastructure alongside actual rack occupancy.
- Medium Scale:Regional operators in Sulawesi exploit lower land acquisition costs and less stringent local emissions enforcement for initial deployment phases. N+1 configurations predominate as capital constraints limit 2N investment.
- Large Scale:Java-based facilities face compressed procurement cycles as hyperscale operators demand simultaneous electrical and thermal infrastructure deployment. Vertical construction in Bekasi complicates generator fuel storage compliance.
- Enterprise Scale:Hyperscale campuses in Batam and Greater Jakarta anchor procurement volumes for gas-turbine hybrids and battery storage systems. PLN interconnection standards prioritize these facilities for grid modernization mandates.
Enterprise Scale anchors supplier revenue. Medium Scale offers steepest expansion trajectory as secondary markets mature.
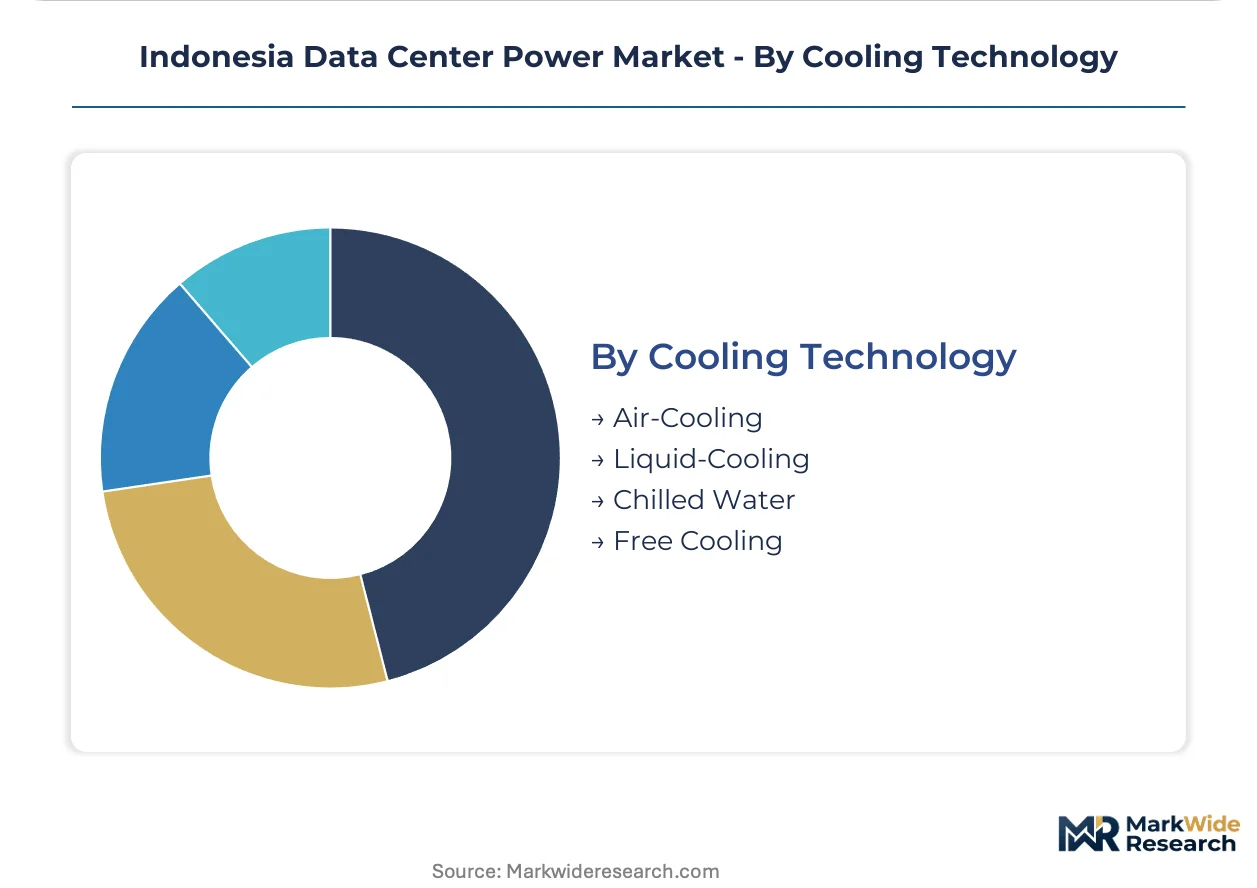
Cooling Technology:
Thermal-electrical system integration requirements reshape power distribution design as rack densities climb.
- Air-Cooling:Legacy standard for existing facilities designed around 10-15kW rack densities, now facing complex retrofit requirements when upgrading busway architectures. Continues to dominate secondary city deployments where land costs permit lower-density construction.
- Liquid-Cooling:High-density racks above 30kW demand dedicated busway architectures rather than traditional panel distribution, opening specialized electrical infrastructure contracts. Schneider Electric and Vertiv compete through thermal-electrical co-design capabilities.
- Chilled Water:Centralized mechanical systems in Greater Jakarta facilities integrate with PLN demand response programs to manage peak load charges. Chiller electrical demand shapes transformer sizing and switchgear configuration.
- Free Cooling:Limited applicability in tropical Indonesian climate except in elevated Batam locations where economizer hours extend operational windows. Supplementary mechanical cooling maintains electrical load profiles comparable to air-cooled alternatives.
Air-Cooling retains installed base dominance. Liquid-Cooling is gaining share fastest as AI training clusters drive density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's data center power infrastructure outpaces Philippine development timelines, while Vietnam accelerates renewable microgrid adoption faster than Malaysian grid-dependent operators.
Greater Jakarta
Hyperscale cloud operators compress procurement cycles for redundant power architectures across Cibitung and Bekasi corridors. PLN interconnection standards prioritize facilities with on-site generation capacity, accelerating gas-turbine hybrid investment. Vertical construction in land-scarce industrial zones complicates generator fuel storage compliance and forces higher-density electrical designs.
Java Island
Grid instability costs hyperscale operators millions in service-level agreement penalties, compelling 2N redundant electrical architectures over N+1 minimums. BIS-equivalent lithium-ion battery standards eliminate regulatory friction for diesel-to-battery retrofits. Tier-III and Tier-IV facilities in Surabaya anchor procurement volumes for modular UPS systems suited to fragmented, multi-phase buildouts.
Batam Free Trade Zone
PLN's rural electrification timeline delays create first-mover advantage for developers establishing captive solar-plus-storage microgrids independent of mainland grid connections. Captive generation configurations satisfy both reliability mandates and national energy transition targets. Elevated locations permit limited free cooling economizer hours that extend operational windows for supplementary mechanical systems.
Sulawesi
Underpenetrated secondary markets offer lower land acquisition costs and less stringent local emissions enforcement for initial deployment phases. Regional operators exploit capital constraints to deploy N+1 configurations rather than hyperscale-grade 2N redundancy. Medium-scale facilities phase electrical infrastructure alongside actual rack occupancy to minimize stranded asset risk.
Medan and Sumatra
Secondary city developers adopt containerized UPS systems to match capital expenditure with actual rack deployment rather than speculative overprovisioning. Legacy enterprise customers retain traditional N+1 minimum configurations, preserving diesel generator dominance. Subscription-based energy optimization platforms restructure procurement patterns for mid-tier colocation operators through direct vendor-facility manager relationships.
Indonesia Data Center Power Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrical-thermal solution providers commanding premium positioning in hyperscale deployments while modular component suppliers capture fragmented secondary market demand. The vendor base organizes around three strategic archetypes: full-stack infrastructure integrators, thermal-electrical co-design specialists, and modular power component fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as participants race to anchor multi-year hyperscale supply agreements before PLN grid modernization timelines crystallize.
Within the full-stack infrastructure tier, Schneider Electric SE and Vertiv Group Corp. occupy positions defined by integrated platform architectures and thermal-electrical co-design capabilities respectively. Delta Electronics exemplifies the modular component archetype through specialized UPS systems. These three anchors represent divergent strategic bets on whether Indonesian data center power procurement consolidates around integrated solution procurement or fragments into best-of-breed component sourcing.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Vertiv Group Corp. |
| ABB Ltd |
| Eaton Corporation plc |
| Cummins Inc. |
| Delta Electronics |
| Rolls-Royce |
| Legrand |
| Hitachi Energy |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators concentrated in Greater Jakarta and Batam anchor procurement volumes for redundant power architectures, locking in contract-based long-term offtake agreements that compress price discovery for modular UPS and gas-turbine hybrid systems. Their SLA penalty exposure measured in millions creates inelastic demand for Tier-III certified configurations, insulating premium-tier suppliers from cost compression while forcing mid-market colocation providers toward subscription-based energy optimization platforms.
Pricing Analysis
Capacity additions in Bekasi and Cibitung industrial corridors are reshaping price floors for containerized UPS systems as local assembly reduces import duty exposure. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in standard-tier lithium-ion battery systems is intensifying because BIS-equivalent safety testing protocols compress supplier margins without commensurate price recovery. Mid-tier colocation operators in Surabaya and Medan exhibit highest price sensitivity, while hyperscale campuses in Batam prioritize reliability premiums over unit economics.
Supply Chain Analysis
Freight cost volatility from Northeast Asian manufacturing hubs to Indonesian ports is amplifying total landed cost exposure for battery cell and power electronics shipments. Supply concentrates in China, South Korea, and Japan for lithium-ion cells, IGBT modules, and precision switchgear components. Raw material dependencies span copper busbars, rare earth magnets, and semiconductor-grade silicon. Single-source vulnerability around battery management system firmware creates regulatory compliance risk. Distribution runs through electrical infrastructure distributors in Jakarta, with direct vendor-facility manager relationships displacing traditional channel intermediaries in subscription-based service segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia data center power infrastructure offers margin expansion potential as lithium-ion cost compression and software-defined load management shift value capture toward operational technology layers. Premium-tier gas-turbine hybrid and solar-plus-storage configurations command pricing power from hyperscale operators facing Jakarta air quality directive compliance deadlines.
For Market Incumbents: To counter hyperscale procurement cycle compression, anchor multi-year supply agreements before PLN grid modernization timelines crystallize. Prioritize backward integration into battery energy storage system assembly to capture margin otherwise lost to Northeast Asian cell suppliers. Defend channel position by establishing direct commercial relationships with facility managers in Bekasi and Cibitung corridors, bypassing electrical distributors threatened by software vendor disintermediation. For New Entrants and Emerging Players: Digital-channel direct sales models offer lowest customer acquisition cost for subscription-based energy optimization platforms targeting mid-tier colocation operators. Sulawesi greenfield developments present the most penetrable geography, with lower land acquisition costs and less stringent emissions enforcement enabling N+1 configuration entry before hyperscale-grade 2N redundancy becomes mandatory. Target containerized UPS deployment in Surabaya and Medan edge facilities, matching capital expenditure with phased rack occupancy to minimize stranded asset risk. For Investors and Strategic Acquirers: Integrated electrical-thermal solution providers are the most active acquirer category in this space, consolidating thermal-electrical co-design capabilities to capture hyperscale campus contracts. Long-term viability centers on vendors with captive solar-plus-storage microgrid expertise for Batam Free Trade Zone expansion. Acquisition target archetype: modular power component fabricators with BIS-equivalent certification pipelines and established PLN interconnection relationships. Monitor PLN rural electrification timeline delays as inflection indicator for captive generation investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Captures margin from lithium-ion cell supply concentration in Northeast Asia. |
| Direct-to-Facility-Manager Channel Expansion | Bypasses electrical distributors threatened by software vendor disintermediation in Bekasi corridor. |
| Solar-Plus-Storage Microgrid Deployment | Satisfies PLN interconnection standards and Jakarta air quality directives for Batam campuses. |
| Thermal-Electrical Co-Design Certification | Opens specialized contracts for liquid-cooled rack architectures above 30kW in Cibitung. |
| Subscription Platform Launch | Restructures mid-tier colocation procurement from capital-intensive hardware to operational expenditure models. |
Research Methodology
Bottom-up data center operator modeling reconciled against top-down electrical infrastructure supplier tracking forms the analytical core of this study. Primary interviews with hyperscale procurement officers, colocation facility managers, PLN interconnection planners, EPC contractors, and BIS-equivalent certification auditors combine with secondary validation from PLN regional operating permits, Ministry of Energy and Mineral Resources emissions filings, customs import records for power electronics, and SEC disclosures from publicly traded infrastructure vendors. Triangulation between demand-side deployment schedules and supply-side manufacturing capacity confirms volume and value estimates.
Historical trendline analysis of diesel-to-battery retrofit timelines and solar-plus-storage adoption curves informs projection parameters across the analysis window. Segmentation dimensions span power source architecture, service type, facility capacity tier, and cooling technology integration. CAGRs derive from fitted growth curves applied to disclosed hyperscale capex commitments and PLN grid availability forecasts. Industry-specific inputs include lithium-ion cost compression trajectories and BIS-equivalent certification timeline validation.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization or green hydrogen backup generation would alter the outlook. Forecasts reflect documented assumptions about PLN rural electrification priorities and Jakarta emissions enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
France Data Center Server Market
Data Center Infrastructure
New York Data Center Market
Data Center Infrastructure
Denmark Data Center Rack Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Chile Data Center Rack Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
New Jersey Data Center Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Europe Data Center Construction Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Vietnam Data Center Power Market