
 Life Insurance Policy Administration System Market | 2026-2036
Life Insurance Policy Administration System Market Size, Share, and Industry Trends Forecast 2026-2036
Life Insurance Policy Administration System Market Analytics
Policy servicing revenue is fragmenting between legacy maintenance contracts and cloud-native subscription platforms. DXC Technology anchors substantial mainframe modernization portfolios across North American mutual insurers. Oracle Corporation extends its database-centric policy admin stack through vertical integration into claims and billing modules. Majesco specializes in cloud-first deployments for mid-tier carriers seeking to bypass on-premise infrastructure cycles.
A life insurance policy administration system constitutes a software platform that automates policy issuance, premium collection, beneficiary management, and claims adjudication through configurable rules engines and workflow orchestration. These systems integrate actuarial calculation engines capable of processing mortality tables, lapse assumptions, and reserve valuations in real time to ensure statutory compliance and accurate liability reporting. Cloud-based deployments now lead new vendor selections as carriers prioritize elastic scalability and API interoperability with distribution management layers. On-premise installations retain dominance among large mutual insurers with decades of customized COBOL logic, though maintenance margins compress as technical debt accumulates. Implementation and consulting services capture disproportionate value during platform transitions, particularly for universal life and variable life products requiring complex fund administration linkages.
FDA guidelines on algorithmic decision-making in insurance, HIPAA privacy safeguards for health-linked life products, and state-level NAIC model regulations on data governance collectively elevate compliance architecture to a core procurement criterion. The EU AI Act and GDPR impose additional algorithmic transparency obligations on carriers deploying automated underwriting within European operations. Stakeholders must evaluate whether vendor roadmaps accommodate emerging explainability standards without sacrificing policy processing throughput.
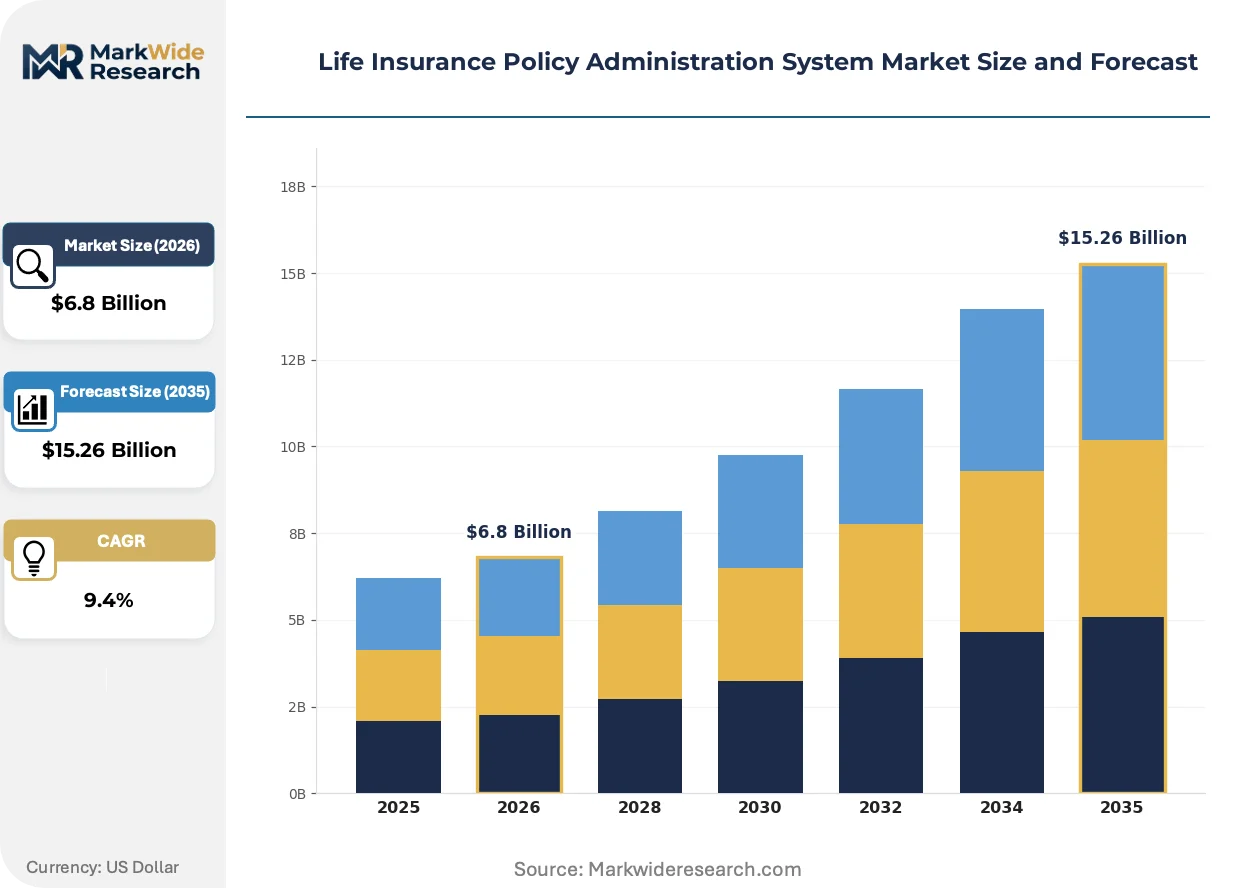
Market Dynamics
Cloud migration mandates from German, Indian, and Brazilian data localization authorities are forcing carriers to reevaluate vendor roadmaps and deployment architectures. This regulatory pressure compounds with actuarial system modernization cycles to reshape procurement priorities.
Growth Catalysts
- Data Localization Mandates:Germany's Federal Data Protection Act, India's Digital Personal Data Protection Act, and Brazil's LGPD compel carriers to select vendors with in-country infrastructure. These frameworks accelerate replacement of cross-border hosted legacy systems.
- Term Life Platform Modernization:Direct-to-consumer term insurers are retiring COBOL mainframes for API-first architectures. Elastic scalability requirements from volatile premium volumes favor cloud-native policy engines.
- Bancassurance Network Expansion:Asia-Pacific banking channels demand real-time policy issuance integrated with core banking systems. This distribution pressure pulls carriers toward microservices-based administration platforms.
Market Restraints
- Legacy Technical Debt:Decades of customized COBOL logic in large mutual insurers create path dependency. Migration costs often exceed replacement system license fees by multiples.
- Actuarial Talent Scarcity:Specialized skills bridging mortality modeling and modern software architecture concentrate in North American and Western European labor markets. Carrier IT departments face recruitment bottlenecks.
- Regulatory Fragmentation:HIPAA privacy safeguards for health-linked life products, state-level NAIC model regulations, and EU AI Act algorithmic transparency obligations create overlapping compliance architectures. Vendors must maintain multiple certification tracks.
Strategic Opportunities
- Embedded Insurance Integration:E-commerce platforms and fintech wallets represent underpenetrated distribution. API-first policy administration systems enable point-of-sale life coverage without traditional agent networks.
- Parametric Product Expansion:Simplified issue products with automated underwriting rules reduce acquisition costs. This product category demands configurable rules engines that legacy platforms cannot support.
- EU AI Act Explainability Requirements:Automated underwriting transparency mandates create demand for interpretable machine learning pipelines. Vendors with built-in model documentation tools capture competitive differentiation.
Industry Challenges
- Mainframe Knowledge Attrition:Retirement waves among COBOL programmers threaten operational continuity. Carriers face knowledge transfer crises during platform transitions.
- Universal Life Fund Administration Complexity:Variable life products require real-time investment subaccount reconciliation. Integration between policy administration and fund accounting systems demands specialized implementation expertise.
- Cross-Border Data Architecture Conflicts:Multi-national carriers must reconcile GDPR data portability requirements with country-specific localization mandates. Cloud vendor selection becomes a geopolitical risk management exercise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Life Insurance Policy Administration System Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Universal Life, Variable Life End User: Insurers, Brokers, Agents, Policyholders Technology: Cloud-Based, On-Premise, Hybrid, Mobile Solutions Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Sapiens International Corporation, DXC Technology, Oracle Corporation, Pegasystems Inc., FIS, Accenture Plc, Majesco, EIS Group, Cognizant Technology Solutions Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Life Insurance Policy Administration System Market Evolving Landscape
Carrier technology strategy is pivoting from monolithic replacement toward modular augmentation. This shift reflects compressed implementation timelines and elevated risk tolerance for phased modernization.
Microservices-based policy engines are hybridizing core administration functions with specialized satellite modules. Tier-two carriers adopting this architecture report 40% faster product launches than mainframe-dependent peers. The approach compresses vendor lock-in by enabling component-level substitution.
GDPR and EU AI Act transparency obligations are reshaping automated underwriting system design. Carriers deploying algorithmic decision-making in European operations must implement interpretable model pipelines and audit trails. This regulatory pressure elevates explainability features to core procurement criteria alongside processing throughput.
Direct-to-consumer channels are displacing traditional agency distribution for term life products. North American insurtech platforms and Asia-Pacific bancassurance networks now capture policy volumes that previously flowed through captive agent forces. This channel rotation demands administration systems with sub-second quote-to-bind latency and mobile-optimized interfaces.
Life Insurance Policy Administration System Market Segmentation
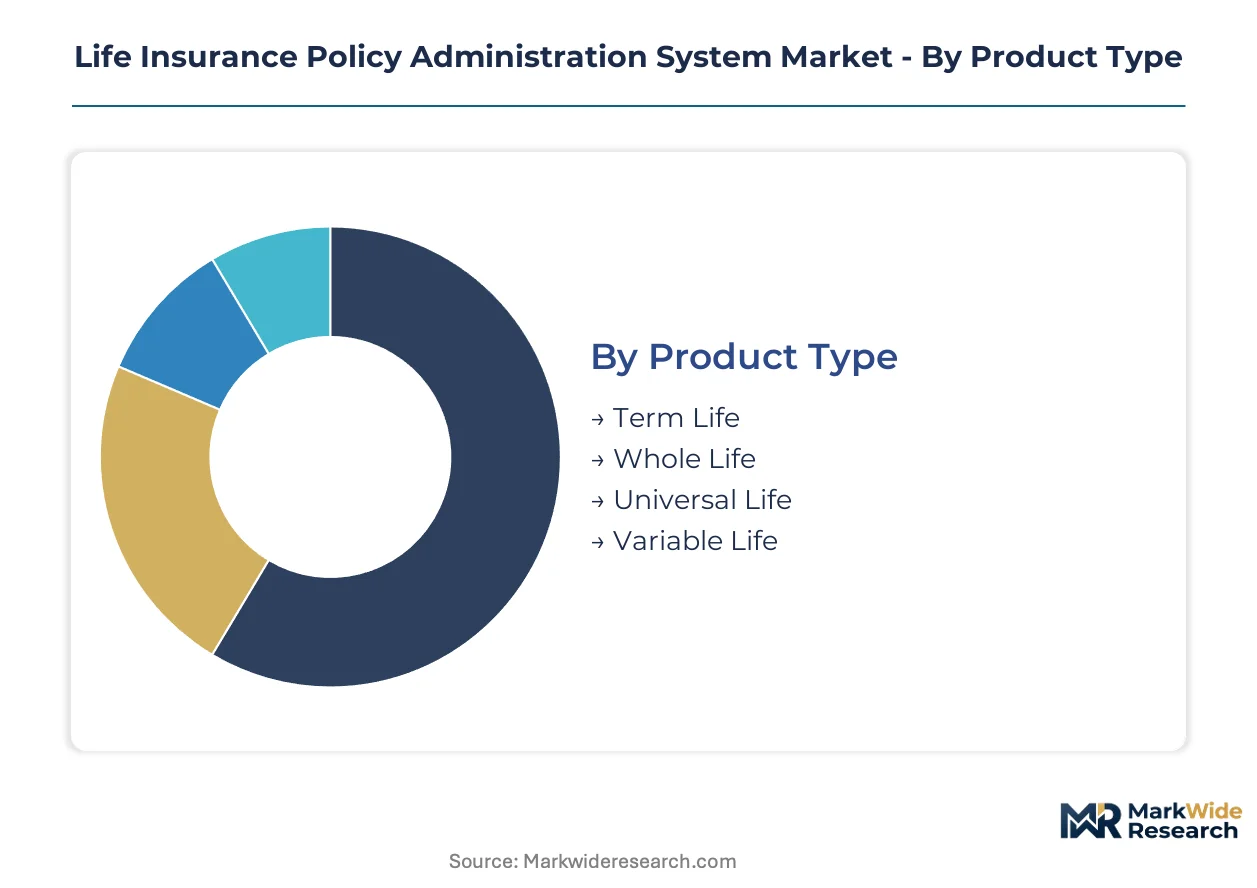
Life insurance policy administration systems fragment across product complexity, distribution channels, deployment architectures, and service delivery models. Each segmentation axis carries distinct procurement criteria, implementation timelines, and vendor specialization patterns that reshape competitive positioning.
Product Type:
Mature whole life and term life segments coexist with emerging universal and variable life configurations that demand more sophisticated fund administration capabilities.
- Term Life:Simplified underwriting rules and fixed premium structures reduce system configuration complexity. North American direct-to-consumer channels concentrate demand here as digital-native carriers seek sub-second quote-to-bind latency for pure protection products.
- Whole Life:Guaranteed cash value accumulation and fixed mortality charges require stable actuarial calculation engines. Large mutual insurers in the United States and Japan maintain decades of customized COBOL logic for these products, creating substantial technical debt during modernization cycles.
- Universal Life:Flexible premium schedules and adjustable death benefits demand configurable policy administration rules.
- Variable Life:Investment subaccount linkages require real-time reconciliation with fund accounting systems.
Term life retains volume leadership; variable life holds the steepest expansion curve.
End User:
Customer type segmentation reveals a cost tier structure spanning enterprise carriers with complex customization needs down to individual policyholders accessing self-service portals.
- Insurers:Full-stack policy administration platforms with actuarial calculation engines, regulatory reporting modules, and reinsurance interfaces. Carriers in Germany and India prioritize vendors with localized data residency capabilities to satisfy federal data protection mandates.
- Brokers:Multi-carrier quoting and policy comparison tools with aggregated commission tracking. Asia-Pacific bancassurance networks concentrate demand here as banking subsidiaries seek seamless core banking integration.
- Agents:Mobile-optimized policy illustration and application submission systems.
- Policyholders:Self-service beneficiary updates, premium payment portals, and claims status tracking.
Insurers command the highest per-seat licensing values; policyholder-facing solutions are climbing fastest as carriers deflect servicing costs to digital channels.
Technology:
Deployment architecture choices increasingly hinge on jurisdictional data localization requirements rather than purely technical considerations.
- Cloud-Based:Elastic scalability and API-first architectures enable rapid product launches and distribution partnerships. Brazil's LGPD and India's Digital Personal Data Protection Act compel carriers to verify in-country infrastructure presence before vendor selection.
- On-Premise:Customized COBOL environments with decades of policy-specific logic retain dominance among large mutual insurers. Migration cost overruns and retired programmer knowledge gaps constrain transition timelines.
- Hybrid:Core administration on legacy systems with customer-facing layers in cloud environments.
- Mobile Solutions:Native applications for agent field underwriting and policyholder self-service.
On-premise installations retain installed base dominance; cloud-based deployments are gaining share fastest among mid-tier carriers bypassing mainframe generations entirely.
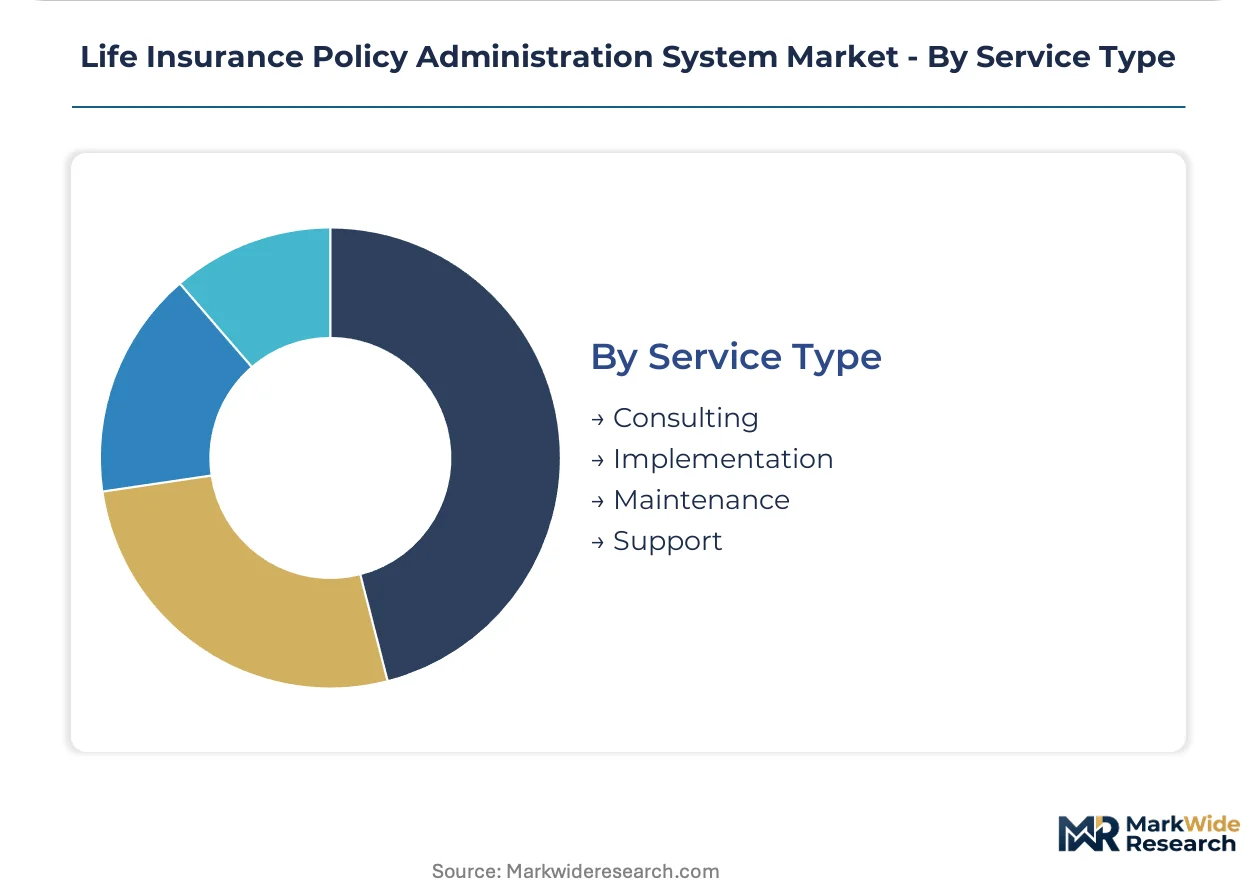
Service Type:
Service delivery segmentation tracks margin concentration away from perpetual licenses toward recurring revenue streams and value-added implementation expertise.
- Consulting:Business process reengineering, data migration planning, and regulatory compliance architecture. Universal life and variable life product conversions demand specialized actuarial-IT bridge expertise that concentrates in North American and Western European labor markets.
- Implementation:System configuration, integration with existing core systems, and user acceptance testing. Complex fund administration linkages for investment-linked products extend project durations and capture disproportionate value.
- Maintenance:Ongoing platform updates, security patching, and regulatory compliance monitoring.
- Support:Help desk services, troubleshooting, and end-user training programs.
Implementation services capture the highest project-based margins; consulting revenue is expanding most quickly as carriers seek external guidance for modernization roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for policy administration systems varies sharply by geography. German and Indian carriers face strict data localization mandates that compress vendor choice and elevate compliance premiums. United States term life insurers enjoy broader vendor pools but bear higher customization costs for legacy mainframe migration.
United States
Direct-to-consumer term life channels drive demand for sub-second quote-to-bind latency. HIPAA privacy safeguards govern health-linked life products, forcing vendors to maintain specialized compliance architectures. Hartford and Boston insurance technology clusters concentrate mutual insurer modernization projects.
Germany
Large mutual insurers prioritize on-premise retention due to decades of customized actuarial logic. The Federal Data Protection Act mandates in-country data residency, disqualifying cross-border cloud deployments. Munich and Frankfurt host dense concentrations of carrier IT procurement decision-making.
India
Bancassurance networks require real-time policy issuance integrated with core banking systems. The Digital Personal Data Protection Act compels verification of local infrastructure presence before vendor selection. Mumbai and Bangalore financial districts anchor Asia-Pacific policy administration demand.
Brazil
LGPD data localization requirements accelerate replacement of legacy hosted systems. Mid-tier carriers bypass mainframe generations entirely, favoring cloud-native deployments. São Paulo's insurance corridor concentrates vendor sales and implementation resources.
Japan
Whole life product dominance preserves demand for stable actuarial calculation engines with fixed mortality charge processing. METI guidelines shape technology procurement standards for financial institutions. Tokyo and Osaka mutual insurers maintain substantial COBOL-dependent policy portfolios.
Life Insurance Policy Administration System Market Competitive Landscape
Legacy systems integrators and cloud-native specialists split the market along modernization trajectory lines. The vendor base concentrates around three strategic archetypes: mainframe modernization contractors, API-first platform builders, and vertical integration specialists. Consolidation pressure intensifies as carriers demand end-to-end policy-to-claims stacks rather than point solutions. Dominant competitive moves include geographic expansion to satisfy data localization mandates and technology licensing to accelerate product roadmap delivery.
Within the legacy modernization tier, DXC Technology and Oracle Corporation occupy positions anchored by substantial mainframe transformation portfolios. Majesco exemplifies the cloud-first archetype targeting mid-tier carriers seeking to bypass on-premise infrastructure cycles entirely. Cognizant Technology Solutions Corporation sits within the systems integration tier, bridging actuarial expertise with modern software architecture delivery.
| Leading Market Players |
|---|
| Sapiens International Corporation |
| DXC Technology |
| Oracle Corporation |
| Pegasystems Inc. |
| FIS |
| Accenture Plc |
| Majesco |
| EIS Group |
| Cognizant Technology Solutions Corporation |
| Others |
Value Network & Pricing Analysis
India's cloud infrastructure labor pools anchor implementation cost structures for policy administration deployments across Asia-Pacific bancassurance networks. Margin concentration sits with consulting and implementation services rather than software licenses, as carriers pay premiums for actuarial-IT bridge expertise during modernization cycles.
Pricing Analysis
Maintenance and support contracts drive lifetime value beyond initial SaaS subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates enterprise carriers with complex customization from mid-tier carriers seeking rapid deployment. Cost compression in implementation services is intensifying because offshore delivery centers are expanding actuarial talent pipelines. Mid-tier carriers exhibit highest price sensitivity; large mutual insurers prioritize vendor stability over license cost.
Supply Chain Analysis
Accenture, Cognizant, and TCS hold dominant capacity for policy administration implementation and consulting. Delivery draws from India, Poland, and the Philippines for actuarial-IT integration work. Specialized inputs include mortality table databases, regulatory compliance engines, and API middleware. Single-source vulnerability concentrates in COBOL programmer knowledge pools nearing retirement. Distribution runs through direct vendor-carrier relationships with systems integrators as intermediaries for complex deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The life insurance policy administration market sits at a high-growth inflection as EU AI Act explainability mandates force algorithmic transparency investments across automated underwriting stacks.
For Market Incumbents: Harden compliance architecture investments to preempt EU AI Act certification requirements before automated underwriting deployments expand. Deepen backward integration into actuarial calculation engines to capture margin pools fleeing generic SaaS tiers. Consolidate around data localization capabilities in Germany, India, and Brazil as vendor selection criteria tighten. For New Entrants and Emerging Players: Mid-tier term life carriers in North America represent the most penetrable entry point for API-first policy engines bypassing mainframe migration complexity. Asia-Pacific bancassurance networks seeking real-time core banking integration offer second-mover advantages for microservices-native platforms. Lead with sub-second quote-to-bind latency demonstrations against incumbent batch-processing limitations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment segments as containerization reduces infrastructure overhead. Target vendors with established data localization footprints in regulated European and Asian markets. Watch automated underwriting transparency mandate enforcement timelines as the signal for explainability feature demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Localization | In-country data residency capabilities satisfy Germany's Federal Data Protection Act and India's Digital Personal Data Protection Act mandates. |
| API-First Platform Architecture | Microservices-based policy engines enable 40% faster product launches than mainframe-dependent peers. |
| Actuarial Talent Acquisition | Specialized mortality modeling and software architecture skills concentrate in North American and Western European labor markets. |
| Explainability Tool Development | Interpretable machine learning pipelines address EU AI Act algorithmic transparency obligations for automated underwriting. |
| Legacy Mainframe Modernization | COBOL knowledge transfer programs mitigate operational continuity risks from retiring programmer waves. |
Research Methodology
The analysis maps cloud-native deployments, on-premise installations, hybrid architectures, and mobile solutions, each validated through carrier CIOs, actuarial system architects, regulatory compliance officers, and implementation project managers. Primary intelligence combines structured interviews with secondary triangulation across NAIC model regulation filings, EIOPA supervisory reports, vendor SEC disclosures, and carrier technology procurement databases. Bottom-up segment sizing reconciles with top-down market boundary analysis.
Forecast assumptions hold data localization mandate enforcement timelines and cloud migration capex cycles as fixed parameters while varying term life direct-to-consumer penetration rates and bancassurance network expansion trajectories. Segmentation dimensions span product complexity tiers, deployment architectures, end-user categories, and regional regulatory clusters. CAGRs derive from fitted growth curves applied to validated base-year estimates, with actuarial system replacement cycles and embedded insurance integration timelines as key model inputs across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting universal life product profitability or carrier IT budget expansion would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement consistency and talent market equilibrium. Quarterly review of carrier modernization announcement velocity and data localization law implementation progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Life Reinsurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life and Annuity Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market
Life and Non Life Insurance
Russia Life and Non-Life Insurance Market