
 Global Life and Non-Life Insurance Market | 2026-2036
Global Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Life and Non-Life Insurance Market Foresight
European insurer balance sheets are consolidating as reinsurance capacity tightens and capital rules harden. Ping An Insurance Company of China Ltd. leverages its healthcare ecosystem to cross-sell life products through digital channels. Allianz SE anchors its position through bancassurance dominance across Southern Europe. Axa SA competes on property and casualty lines with modular coverage for climate-exposed assets.
Life and non-life insurance encompasses risk pooling instruments where policyholders transfer financial exposure to underwriters in exchange for premium payments, with reserves held against stochastic claims liabilities and investment income smoothing long-duration obligations. The primary purpose spans individual income replacement, enterprise liability containment, and institutional wealth preservation. Term life and whole life products capture the bulk of premium flow in emerging economies where mortality protection remains underpenetrated. Bancassurance and online platforms represent the fastest-growing distribution channels, displacing traditional agent networks in urban centers. Corporate client demand for business continuity coverage is deepening as supply chain interruption risks multiply.
Solvency II in Europe, state-level insurance commissioners in the United States, and China's National Financial Regulatory Administration collectively shape capital adequacy thresholds, product approval timelines, and cross-border market access conditions. GDPR and emerging AI governance frameworks in the European Union are constraining how insurers deploy algorithmic underwriting and claims automation. Stakeholders must monitor regulatory divergence between jurisdictions as data localization mandates and climate stress-testing requirements proliferate.
Market Dynamics
Solvency II reforms are compressing capital efficiency across European underwriters while embedded wealth products in Southeast Asia pull premium flow toward hybrid savings instruments. Reinsurance capacity tightening and bancassurance channel expansion now define competitive positioning in life and non-life lines.
Growth Catalysts
- Embedded Wealth Instruments:Southeast Asian retail savers are migrating from traditional deposits toward unit-linked life products bundled with digital banking platforms.
- Bancassurance Velocity:India's regulatory sandbox approvals for insurer-bank partnerships are compressing policy issuance timelines and expanding distribution reach into tier-2 urban centers.
- Climate Risk Coverage:Commercial property owners in climate-exposed coastal zones are accelerating demand for parametric catastrophe bonds and modular P&C extensions.
Market Restraints
- Capital Reserve Compression:Solvency II's tightened matching adjustment rules are immobilizing long-duration assets on European balance sheets and constraining dividend capacity.
- Reinsurance Supply Concentration:Bermuda and London market capacity constraints following natural catastrophe losses are hardening rates for property treaty renewals.
- Legacy System Technical Debt:Core policy administration platforms built on COBOL architectures are blocking real-time data integration with telematics and IoT sensor feeds.
Strategic Opportunities
- Microinsurance Penetration:India's rural agricultural workforce remains underpenetrated for weather-indexed crop and livestock coverage, with mobile distribution enabling premium collection at sub-dollar thresholds.
- Health Ecosystem Convergence:Wearable biometric data streams and predictive analytics are enabling dynamic underwriting models that adjust premiums based on real-time mortality risk indicators.
- EU AI Act Tailwinds:The European Union's risk-based framework for algorithmic decision-making is creating first-mover advantages for insurers with documented model governance and human-in-the-loop claims protocols.
Industry Challenges
- Actuarial-Data Science Talent Gap:Underwriters struggle to recruit professionals fluent in both stochastic reserving methods and machine learning pipeline deployment.
- Cross-Border Data Localization:China's National Financial Regulatory Administration and India's RBI are imposing conflicting data residency mandates that fragment cloud infrastructure strategies for multinational carriers.
- IFRS 17 Implementation Complexity:The new accounting standard's contractual service margin calculations are forcing reconciliation between actuarial systems and general ledgers that were never architected for unified reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Life and Non-Life Insurance Market |
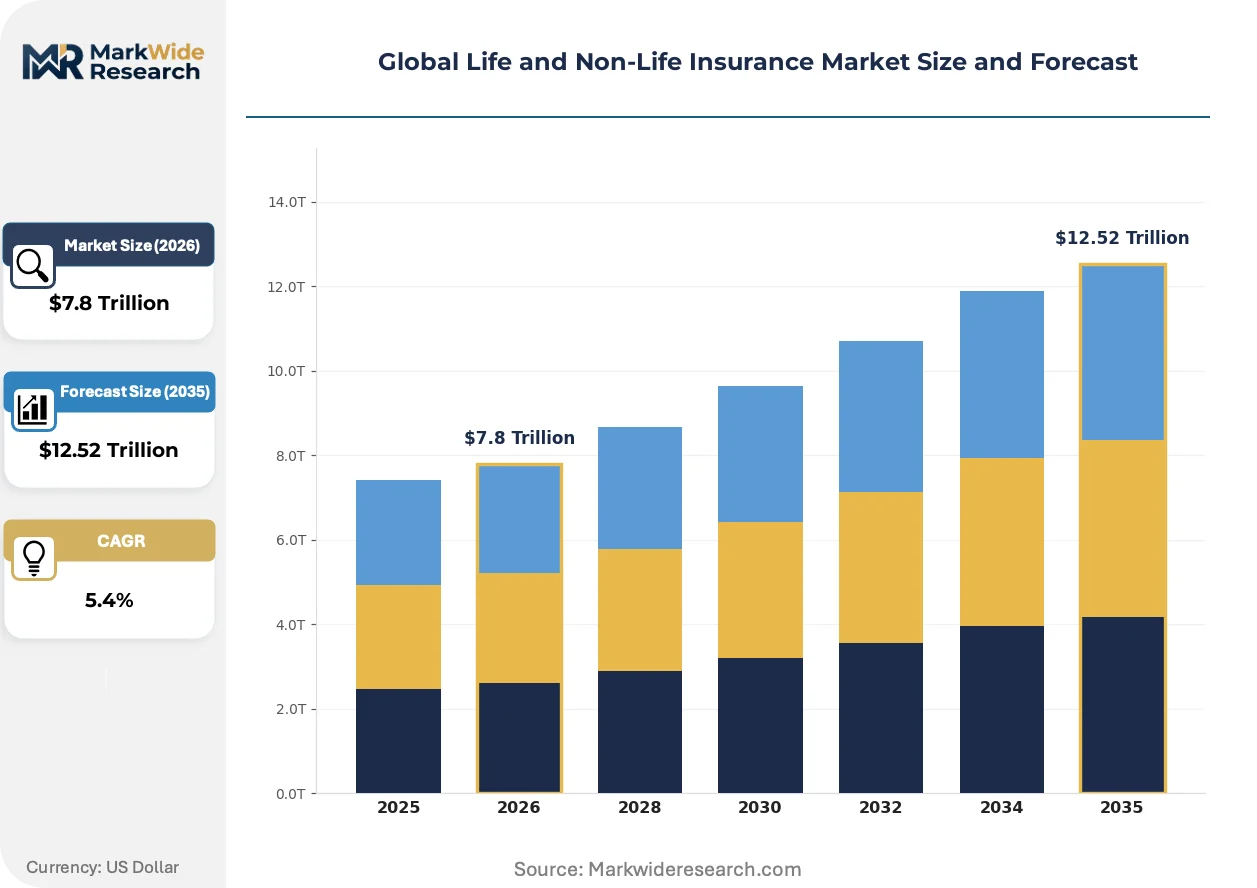
| Market Size in 2026 | $7.8 Trillion |
| Market Size in 2035 | $12.52 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Term Life, Whole Life, Disability Insurance, Property Insurance, Liability Insurance, Travel Insurance Application: Risk Management, Wealth Accumulation, Asset Protection, Retirement Planning, Income Replacement, Business Continuity Customer Type: Individual Policyholders, Small Enterprises, Corporate Clients, Self-Employed Professionals, Non-Governmental Organizations, Freelancers Distribution Channel: Brokers, Bancassurance, Direct Sales, Agents, Online Platforms, Independent Financial Advisors |
| Companies Covered | Ping An Insurance Company of China Ltd., China Life Insurance Company Limited, Allianz SE, Axa SA, MetLife Inc., Prudential plc, UnitedHealth Group Incorporated, Zurich Insurance Group Ltd., AIA Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Life and Non-Life Insurance Market Shifts & Advancements
Distributed ledger infrastructure and biometric sensor networks are rewiring how risk is priced, reserved, and settled across life and non-life lines. Regulatory technology mandates and shifting distribution economics are accelerating the displacement of traditional agent networks.
Blockchain-based smart contracts for parametric insurance are absorbing claims settlement friction by automating payout triggers when predefined index thresholds breach. Agricultural cooperatives in Kenya and flood-exposed municipalities in Germany are piloting these instruments. The technology is absorbing intermediary layers that historically verified loss adjusters' manual assessments.
The EU AI Act's high-risk system classification is forcing European underwriters to rearchitect algorithmic underwriting engines with mandatory human oversight checkpoints and bias audit trails. Property and casualty lines deploying computer vision for damage assessment face the steepest compliance retrofit costs. German and French regulators are demanding model cards documenting training data provenance and performance drift monitoring.
Telematics-enabled usage-based auto insurance is compressing the traditional annual policy cycle into monthly or per-mile billing structures. Younger driver cohorts in South Korea and the United Kingdom are switching from bundled agent-sold packages to smartphone-activated coverage that activates only during vehicle operation. This behavioral pivot is eroding commission-based distribution economics that sustained captive agent networks for decades.
Global Life and Non-Life Insurance Market Segmentation
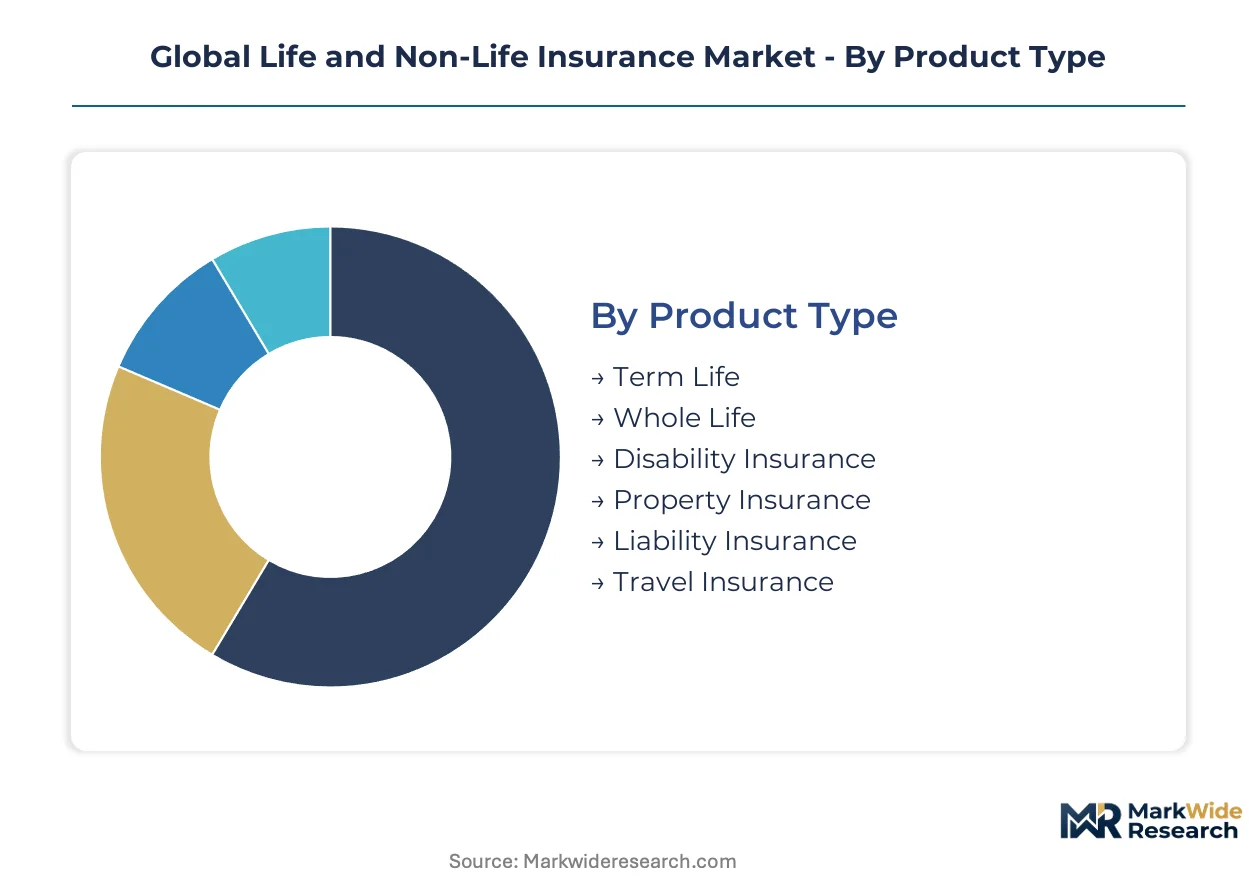
Insurance market segmentation reveals how capital deployment, risk pooling mechanics, and distribution economics vary across product architectures and customer archetypes. Each dimension carries distinct reserve requirements, regulatory treatment, and margin profiles that shape competitive strategy.
Product Type:
Capital intensity peaks in long-duration life products where statutory reserves must cover mortality risk across multi-decade horizons, while short-tail property lines release capital faster.
- Term Life:Pure mortality protection with no cash value accumulation requires lower capital reserves than permanent products. Demand concentrates among younger households in India and Southeast Asia where income protection gaps remain acute; bancassurance partnerships accelerate policy issuance velocity.
- Whole Life:Bundled mortality protection with guaranteed cash value accumulation demands substantial long-duration asset portfolios. European insurers face Solvency II matching adjustment constraints that immobilize capital; Asian markets favor these products for tax-advantaged wealth accumulation.
- Disability Insurance:Short-term and long-term income replacement coverage with complex morbidity underwriting.
- Property Insurance:Physical asset protection against fire, theft, and natural perils with annual policy cycles.
- Liability Insurance:Third-party bodily injury and property damage coverage for individuals and enterprises.
- Travel Insurance:Short-duration coverage for trip cancellation, medical emergencies, and baggage loss.
Whole Life absorbs the bulk of installed capacity; Term Life is expanding most quickly.
Application:
Application segments diverge by policy duration, with retirement and wealth products locking in capital for decades while business continuity coverage operates on annual renewals.
- Risk Management:Enterprise-focused transfer of operational, financial, and strategic exposure through tailored policy structures. Corporate clients in climate-exposed coastal zones accelerate demand for parametric catastrophe coverage; reinsurance capacity tightening hardens treaty renewal rates.
- Wealth Accumulation:Unit-linked and participating life products combining mortality protection with investment returns. Southeast Asian retail savers migrate from traditional deposits toward these instruments; embedded digital banking distribution reduces acquisition costs.
- Asset Protection:Physical property and valuable item coverage against damage or loss.
- Retirement Planning:Annuity products converting accumulated savings into guaranteed income streams.
- Income Replacement:Life and disability coverage maintaining household cash flow after earnings disruption.
- Business Continuity:Interruption coverage for revenue loss following insured physical damage.
Risk Management commands the deepest capital commitments; Wealth Accumulation climbs the fastest.
Customer Type:
Customer archetypes span vastly different premium scales, with corporate programs generating six-figure annual revenues versus microinsurance policies collected at sub-dollar thresholds.
- Individual Policyholders:Retail consumers purchasing personal life, health, and property coverage. Younger cohorts in South Korea and the United Kingdom switch from bundled agent-sold packages to smartphone-activated telematics coverage; this behavioral pivot erodes commission-based distribution economics.
- Corporate Clients:Large enterprises procuring comprehensive risk transfer programs across multiple lines. Multinational carriers face conflicting data residency mandates from China's National Financial Regulatory Administration and India's RBI that fragment cloud infrastructure strategies.
- Small Enterprises:Mid-market businesses with simplified coverage needs and price-sensitive procurement.
- Self-Employed Professionals:Doctors, lawyers, and consultants requiring professional liability and income protection.
- Non-Governmental Organizations:Mission-driven entities with specialized coverage for field operations and volunteer liability.
- Freelancers:Gig economy workers with irregular income streams and portable coverage requirements.
Corporate Clients anchor premium volume; Individual Policyholders gain share fastest.
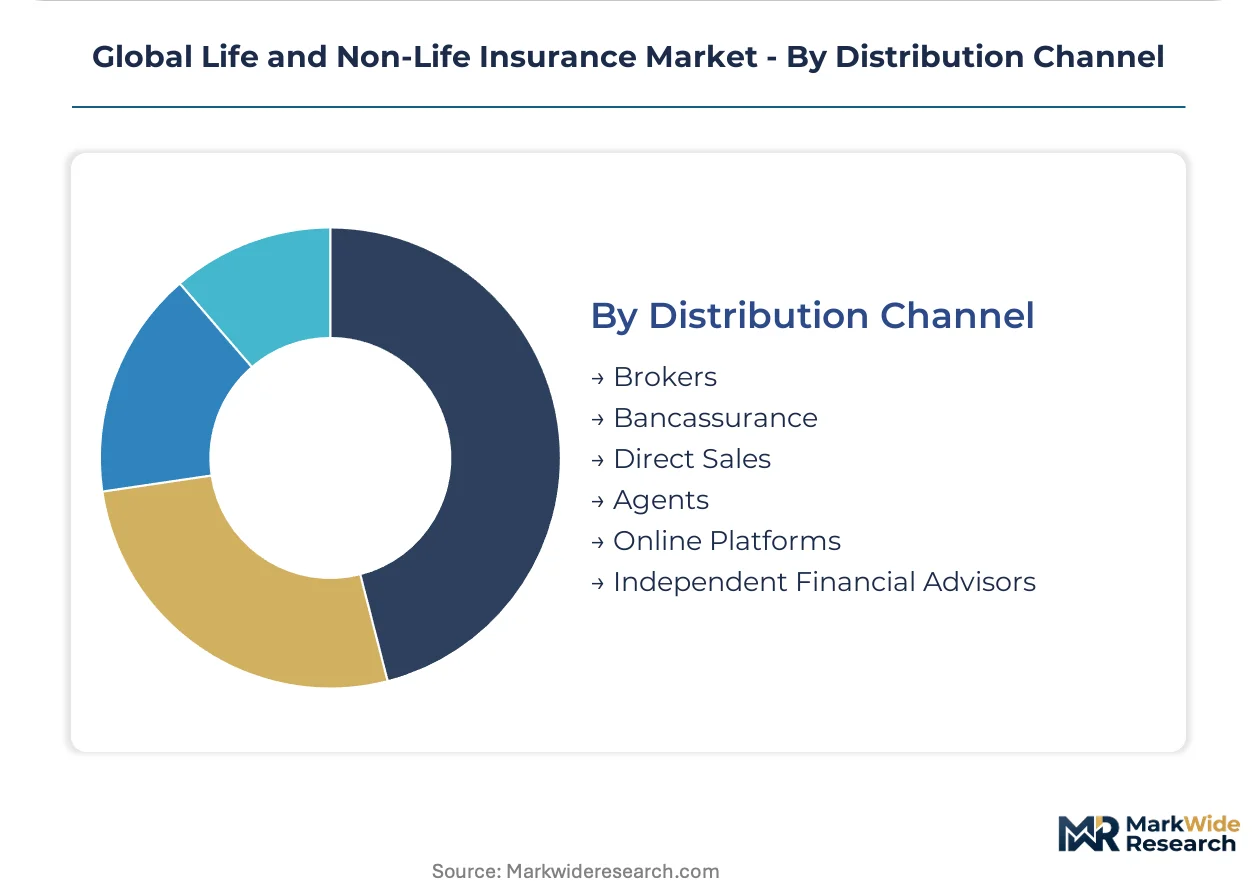
Distribution Channel:
Channel economics determine customer acquisition costs and persistency rates, with digital platforms achieving lower expense ratios than traditional agent networks.
- Bancassurance:Insurance products distributed through banking networks leveraging existing customer relationships. India's regulatory sandbox approvals for insurer-bank partnerships compress policy issuance timelines; tier-2 urban centers expand distribution reach beyond traditional agency strongholds.
- Online Platforms:Direct-to-consumer digital sales with algorithmic underwriting and instant policy issuance. Telematics-enabled usage-based auto insurance compresses annual policy cycles into monthly or per-mile billing; smartphone-activated coverage activates only during vehicle operation.
- Brokers:Independent intermediaries advising clients across multiple carrier options.
- Direct Sales:Carrier-employed representatives selling proprietary product portfolios.
- Agents:Commission-based producers with exclusive or independent carrier appointments.
- Independent Financial Advisors:Fee-based planners integrating insurance into holistic wealth management.
Agents retain the bulk of legacy policy flow; Online Platforms scale fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment across insurance markets tracks demographic density and regulatory sophistication, with premium flow concentrating where household savings rates intersect with digital distribution infrastructure.
United States
Employer-sponsored group life coverage and Medicare Advantage expansion drive institutional premium volumes. State-level insurance commissioners enforce capital adequacy thresholds through risk-based capital frameworks. The Hartford and Boston clusters anchor property-casualty underwriting concentration for commercial lines.
China
Healthcare ecosystem convergence and aging demographics accelerate demand for critical illness riders and long-term care products. The National Financial Regulatory Administration imposes data localization mandates on multinational carriers. Shenzhen and Shanghai host the densest fintech-insurer partnership networks for digital policy issuance.
Germany
Industrial Mittelstand demand for business interruption coverage and cyber liability protection deepens corporate premium pools. BaFin enforces Solvency II matching adjustment rules that immobilize long-duration assets. Munich and Frankfurt concentrate reinsurance treaty structuring and alternative risk transfer expertise.
India
Bancassurance partnerships and regulatory sandbox approvals compress policy issuance timelines for term life penetration. The Reserve Bank of India and Insurance Regulatory and Development Authority coordinate on foreign ownership caps and distribution licensing. Mumbai and Bangalore lead insurtech platform development for tier-2 urban center expansion.
United Kingdom
Pension risk transfer transactions and bulk annuity de-risking reshape liability-driven investment strategies. The Prudential Regulation Authority and Financial Conduct Authority enforce Solvency II compliance and consumer duty standards. London's Lloyd's market and Edinburgh's fund administration clusters dominate specialty lines and unit-linked product structuring.
Global Life and Non-Life Insurance Market Competitive Landscape
Global majors compete with regional champions across capital efficiency and distribution reach, producing a tiered structure where scale-driven conglomerates sit alongside ecosystem-integrated specialists and bancassurance-dominant regional players. Strategic archetypes include healthcare-ecosystem underwriters, bancassurance-anchored European groups, and Asia-Pacific digital platform insurers. Competitive moves center on reinsurance capacity consolidation and embedded wealth product partnerships with retail banking networks.
Among Asia-Pacific-based conglomerates, Ping An Insurance Company of China Ltd. and AIA Group Limited exemplify the healthcare-ecosystem archetype, integrating biometric data streams with mortality protection products. European-listed groups including Allianz SE and Axa SA occupy positions defined by bancassurance channel dominance and modular climate-risk coverage specialization. Zurich Insurance Group Ltd. represents the commercial-lines-focused tier with industrial property and liability concentration.
| Leading Market Players |
|---|
| Ping An Insurance Company of China Ltd. |
| China Life Insurance Company Limited |
| Allianz SE |
| Axa SA |
| MetLife Inc. |
| Prudential plc |
| UnitedHealth Group Incorporated |
| Zurich Insurance Group Ltd. |
| AIA Group Limited |
| Others |
Supply & Pricing Matrix
Corporate risk managers at multinational enterprises in Germany and the United States anchor premium pricing power through multi-year master policy contracts that bundle property, liability, and business interruption coverage with embedded claims servicing guarantees.
Pricing Analysis
Warranty-style bundling of loss adjustment services with core coverage separates premium tiers in commercial property and casualty lines. Three-tier pricing structure across premium, standard, and economy levels tracks claims settlement speed and dedicated adjuster assignment. Cost compression in standard-tier commercial auto coverage intensifies as telematics-enabled usage-based models erode traditional annual policy economics. Individual policyholders in South Korea and the United Kingdom exhibit the sharpest price sensitivity, while corporate captive programs show the least.
Supply Chain Analysis
Actuarial talent shortages in Mumbai and Bangalore constrain back-office underwriting capacity for digital-first insurers expanding into tier-2 Indian urban centers. Capital reserves draw from long-duration sovereign bond portfolios in Germany, Japanese yen-denominated assets, and U.S. Treasury inflation-protected securities. Single-source vulnerability concentrates in Bermuda-based reinsurance treaty capacity following natural catastrophe losses. Distribution runs through bancassurance partnerships, direct-to-consumer platforms, and independent broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reinsurance capacity tightening and Solvency II capital reserve compression are forcing sub-scale European underwriters into distressed consolidation, creating acquisition opportunities for well-capitalized competitors.
For Market Incumbents: Deepen bancassurance channel control across Southern Europe and Southeast Asia to lock in premium flow before digital-native entrants capture younger cohorts. Acquire distressed mid-tier insurers in Germany and France facing Solvency II matching adjustment constraints to consolidate balance sheet capacity and eliminate overlapping distribution costs.
For New Entrants and Emerging Players: The gap between premium-tier whole life products and economy-tier term coverage in rural India offers white-space entry through mobile-enabled microinsurance distribution. Target weather-indexed agricultural coverage for underpenetrated farming cooperatives; partner with regional banks for premium collection at sub-dollar thresholds rather than building captive agent networks.
For Investors and Strategic Acquirers: The window for entry favors healthcare-ecosystem-integrated insurers with documented AI governance frameworks ahead of EU AI Act enforcement. Monitor regulatory sandbox approvals from India's Insurance Regulatory and Development Authority as inflection indicators for distribution velocity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reinsurance Capacity Consolidation | Bermuda and London market treaty restructuring absorbs post-catastrophe rate hardening. |
| Bancassurance Partnership Expansion | India's regulatory sandbox approvals compress policy issuance timelines into tier-2 urban centers. |
| Health Ecosystem Convergence | Ping An's biometric data integration with mortality products creates cross-selling density in China. |
| AI Governance Infrastructure Investment | EU AI Act compliance creates first-mover advantages for documented model governance protocols. |
| Parametric Product Development | Blockchain-based smart contracts automate payout triggers for climate-exposed commercial property. |
Research Methodology
Document review covered regulatory filings from the National Financial Regulatory Administration, BaFin, and the Insurance Regulatory and Development Authority, complemented by interviews with chief underwriting officers, actuarial directors, bancassurance partnership leads, and insurtech platform engineers. Secondary validation drew from Solvency II disclosure templates, Lloyd's market reports, and Reserve Bank of India sandbox approval records. Bottom-up premium flow modeling triangulated against top-down demographic savings rate projections.
Segment-level value outputs trace product architecture, application purpose, customer archetype, and distribution channel across the projection horizon. CAGRs derived from stochastic reserving models incorporating mortality improvement factors, interest rate path simulations, and catastrophe loss distributions. Forecast inputs included regulatory capital requirement trajectories and telematics adoption curves in personal auto lines.
Inputs from primary stakeholder interviews were available through the study window; gaps in proprietary reinsurance treaty pricing introduce uncertainty bands around property-casualty premium forecasts. Material deviation in Solvency II matching adjustment rules or Bermuda market capacity availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Israel Life and Non-Life Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Pacific Life & Non-Life Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Poland Life and Non-Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market