
 Colombia Life and Non-Life Insurance Market | 2026-2036
Colombia Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Life and Non-Life Insurance Market Outlook
SOAT certification compliance is collapsing the field of authorized auto underwriters, forcing smaller carriers to exit mandatory liability coverage. Grupo Sura leverages its bancassurance network to dominate individual life sales through Davivienda's branch footprint. Seguros Bolivar anchors the property segment with specialized catastrophe reinsurance treaties covering seismic zones. Mapfre competes through direct digital platforms targeting urban millennials with modular health riders.
Colombia life and non-life insurance constitutes risk-pooling contracts where carriers collect premiums to indemnify policyholders against mortality, morbidity, property damage, or liability events, with reserves held against future claims per technical provisions calculated via mortality tables and loss ratio projections. Health insurance leads premium volume due to employer-mandated EPS complementary coverage, while auto insurance remains structurally constrained by SOAT price caps that compress margins on mandatory lines. Brokers control the corporate segment, capturing mid-market enterprises through bundled property-casualty programs, whereas online platforms are gaining fastest among individual purchasers seeking term-life comparison tools.
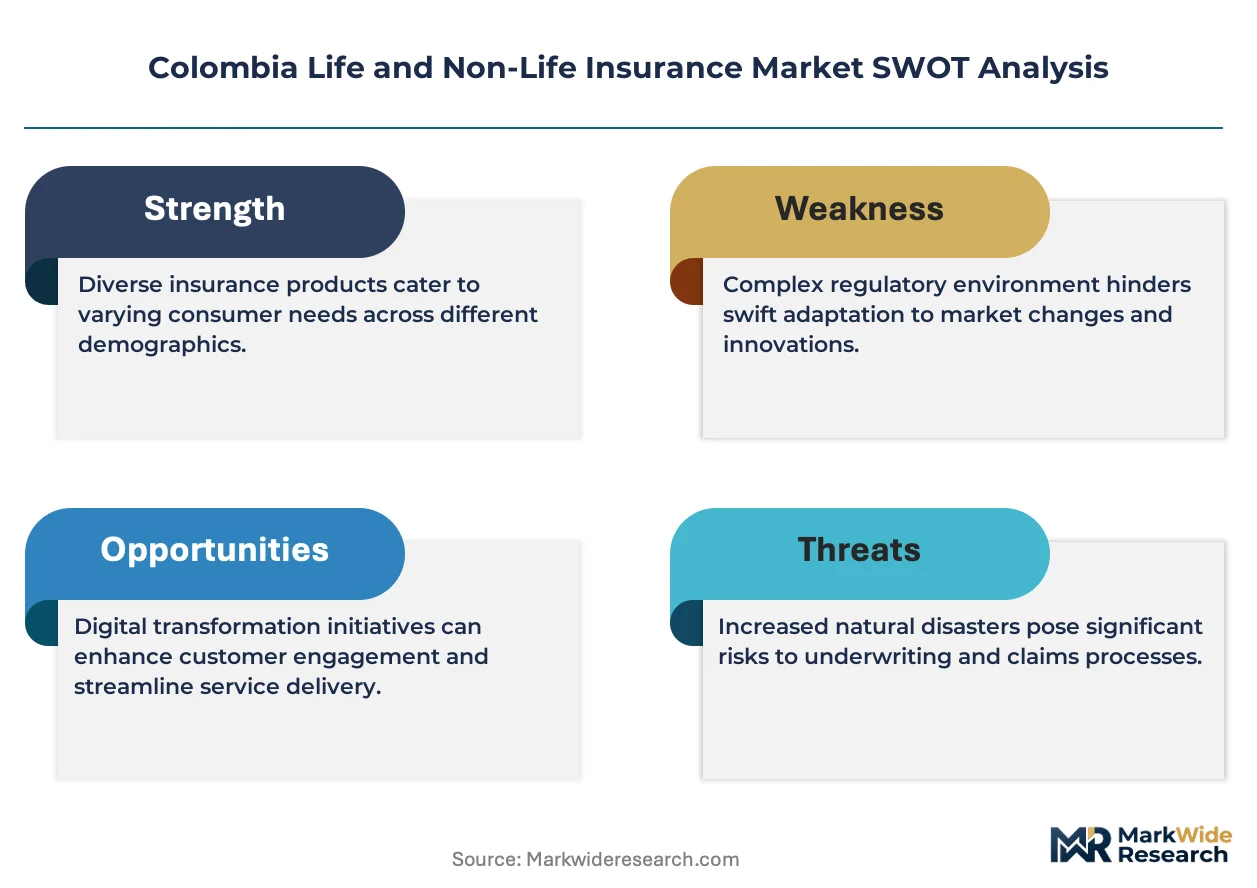
Colombia's Financial Superintendence enforces Circular Externa 029 solvency standards and anti-money laundering protocols under UIAF oversight, raising compliance costs but strengthening policyholder protection frameworks. The Ministry of Finance periodically adjusts SOAT premium bands, directly constraining auto underwriter pricing flexibility. Stakeholders must monitor whether regulator-mandated reserve adequacy tests will trigger further market consolidation among mid-tier carriers lacking reinsurance backing.
Market Dynamics
Colombia's Financial Superintendence tightened Circular Externa 029 solvency rules, compelling carriers to raise capital reserves and triggering consolidation among mid-tier underwriters lacking reinsurance backing. This regulatory pressure is reshaping competitive positioning across both life and non-life lines.
Growth Catalysts
- EPS Complementary Mandate:Employer-mandated health coverage expansion drives premium volume in Bogotá's corporate corridor, where payroll-linked policies dominate new business acquisition.
- Small Enterprise Coverage Expansion:Health and property line purchases accelerate among Colombia's growing SME sector, particularly in Medellín's manufacturing belt where commercial auto and asset protection needs concentrate.
- Catastrophe Reinsurance Access:Specialized seismic treaties enable property underwriters to cover high-risk zones previously deemed uninsurable, unlocking premium growth in Pacific and Andean regions.
Market Restraints
- SOAT Price Caps:Ministry of Finance premium bands compress margins on mandatory auto liability lines, constraining underwriting flexibility and deterring new market entrants.
- Reinsurance Concentration:Limited domestic reinsurance capacity forces Colombian carriers to cede risk to international markets, exposing balance sheets to currency volatility and foreign counterparty dependence.
- Claims Inflation in Health:Medical cost escalation outpaces premium adjustment cycles, eroding technical margins on employer-sponsored complementary coverage.
Strategic Opportunities
- Pacific Coast Underpenetration:Buenaventura and Cali corridor present whitespace for microinsurance distribution targeting informal port workers and logistics subcontractors excluded from formal EPS networks.
- Bancassurance Channel Deepening:Davivienda's branch footprint and digital banking integration create captive distribution for modular life products targeting underbanked segments in secondary cities.
- Parametric Agriculture Coverage:Drought and flood index-based policies align with Ministry of Agriculture rural development priorities, opening subsidized premium pools for climate-vulnerable coffee and cocoa cooperatives.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals skilled in stochastic modeling for catastrophe risk and IFRS 17 technical provision calculations delays product development cycles.
- Legacy Core System Migration:Decades-old policy administration platforms impede real-time data integration with UIAF anti-money laundering monitoring systems, elevating compliance breach risk.
- Broker Channel Disintermediation Resistance:Corporate segment intermediaries defend commission structures against direct digital platforms, complicating cost-to-serve optimization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Life and Non-Life Insurance Market |
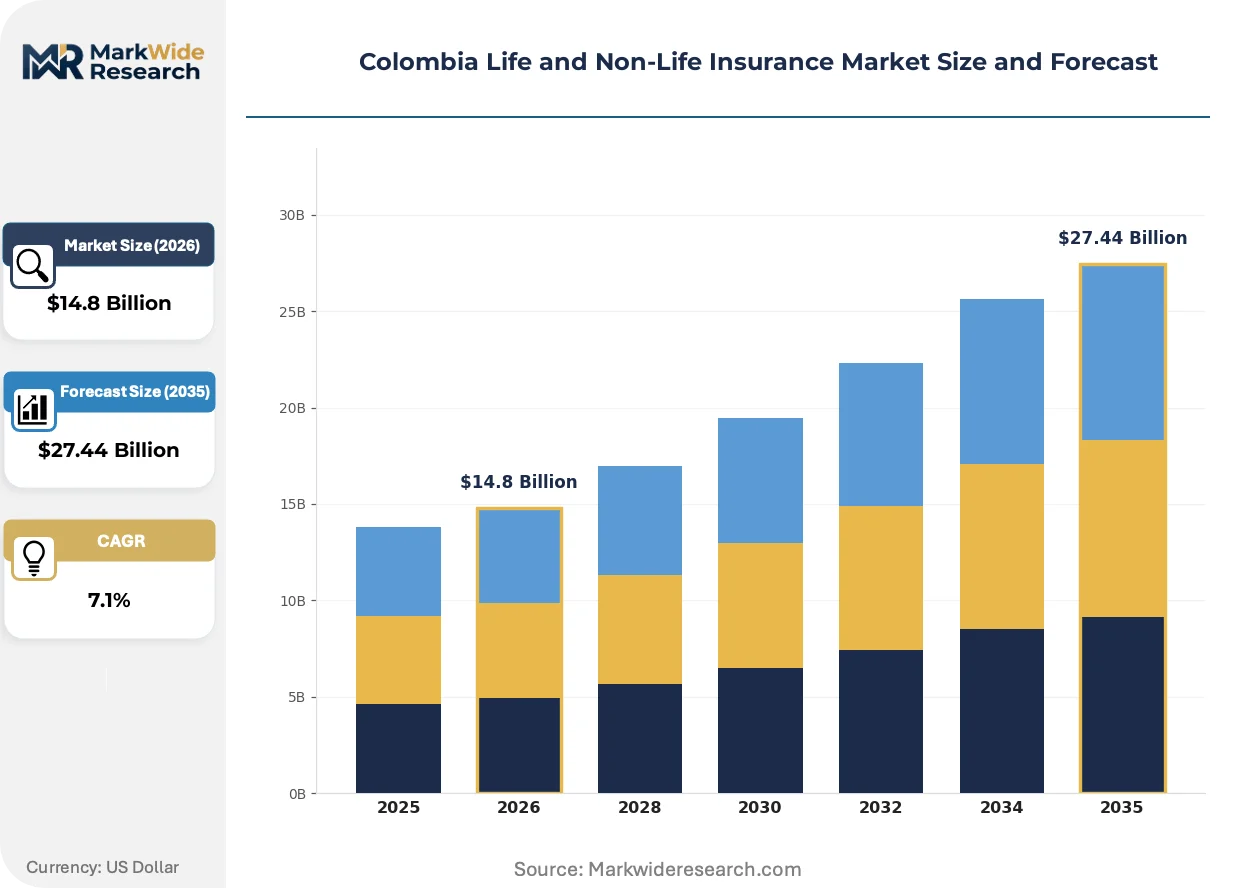
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $27.44 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Health Insurance, Auto Insurance, Property Insurance, Life Insurance End User: Individuals, Small Enterprises, Corporates, Non-Profit Organizations Distribution Channel: Direct Sales, Brokers, Online Platforms, Agents Premium Type: Regular Premium, Single Premium, Group Premium, Variable Premium |
| Companies Covered | Grupo Sura, Suramericana, Seguros Bolivar, Seguros Alfa, Axa, Allianz, Mapfre, Alfa Vida, Bolivar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Life and Non-Life Insurance Market Strategic Shifts
Digital distribution architectures and regulatory data mandates are compressing traditional intermediation layers while forcing carriers to rebuild core systems around real-time compliance reporting. These shifts favor technology-forward underwriters with modular product engines.
Telematics-enabled usage-based auto insurance is miniaturizing risk assessment from annual policy periods to real-time driving behavior monitoring. Fleet operators in Bogotá's logistics corridor adopt these platforms fastest, lured by premium discounts tied to actual mileage and braking patterns. This granularity is compressing traditional actuarial pooling models and enabling dynamic pricing that displaces static SOAT rate bands for voluntary complementary coverage.
Colombia's Financial Superintendence Circular Externa 029 mandates risk-based capital adequacy testing aligned with Solvency II principles. Mid-tier carriers face elevated compliance costs as they implement internal models for technical provision calculations and catastrophe reserve stress testing. The property-casualty segment bears the heaviest implementation burden, with seismic zone underwriters accelerating reinsurance treaty renegotiations to meet December compliance deadlines.
Urban millennials in Medellín and Bogotá bypass traditional broker channels for direct digital comparison platforms when purchasing term life and modular health riders. Insurtech aggregators capture this demand by unbundling product components and enabling self-service policy customization. This channel migration is most pronounced among individual purchasers earning above minimum wage thresholds, where digital literacy and price transparency expectations outpace carrier legacy distribution investments.
Colombia Life and Non-Life Insurance Market Segmentation
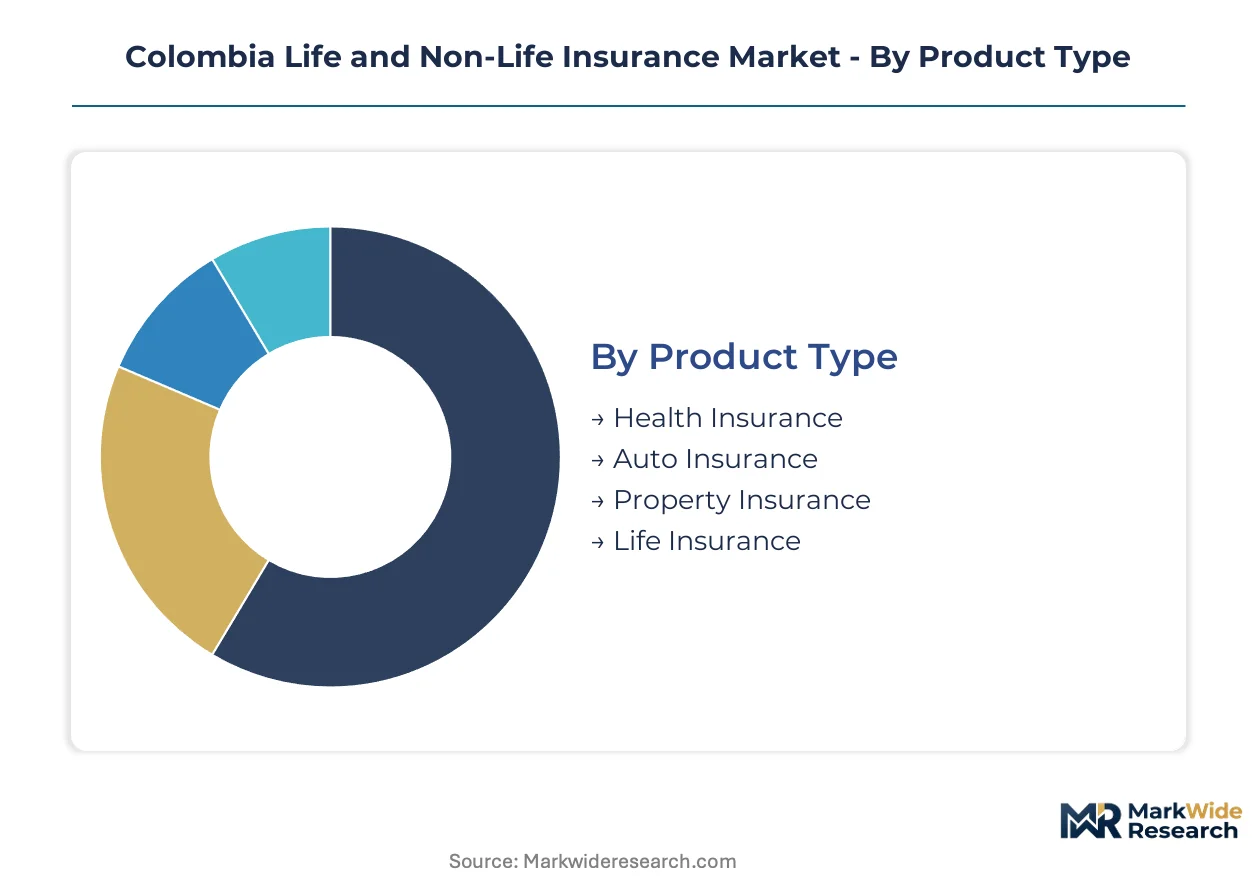
Insurance carriers in Colombia optimize product mix and channel economics through granular segmentation. Distinct margin profiles across life and non-life lines demand tailored capital allocation and distribution strategies.
Product Type:
Health insurance commands the widest margin pools due to employer-mandated EPS complementary coverage and recurring premium structures.
- Health Insurance:Employer-mandated complementary coverage layered atop EPS public plans. Demand concentrates in Bogotá's corporate corridor where payroll-linked policies dominate new premium acquisition and technical margins benefit from group rating efficiencies.
- Life Insurance:Term and whole-life contracts indemnifying mortality risk with reserves held against future claims. Individual purchasers in Medellín's urban core drive fastest growth through bancassurance channels linked to Davivienda's banking footprint.
- Auto Insurance:SOAT mandatory liability and voluntary comprehensive coverage. Ministry of Finance price caps compress margins on compulsory lines while telematics-enabled usage-based products unlock pricing flexibility for fleet operators.
- Property Insurance:Commercial and residential asset protection with catastrophe reinsurance backing. Seismic zone underwriters in Pacific and Andean regions leverage specialized treaties to cover previously uninsurable risks.
The dominant share belongs to Health Insurance, while Life Insurance is gaining share fastest through bancassurance penetration.
End User:
Volume concentration varies sharply by user type, with corporate purchasers driving premium scale and SMEs expanding coverage breadth fastest.
- Corporates:Large enterprises procuring bundled property-casualty and group life programs. Procurement concentrates in Bogotá's financial district where brokers control placement through multi-year master policies.
- Small Enterprises:Growing manufacturing and logistics firms in Medellín's industrial belt purchasing commercial auto and asset protection. Regulatory solvency requirements under Circular Externa 029 have tightened credit standards for this segment.
- Individuals:Urban millennials and salaried workers seeking term life and modular health riders. Digital comparison platforms capture this demand fastest among minimum-wage-plus earners with smartphone banking access.
- Non-Profit Organizations:Foundations and cooperatives requiring specialized liability and director coverage. Parametric agriculture policies align with Ministry of Agriculture rural development priorities for climate-vulnerable coffee cooperatives.
Corporates retain the largest premium base, though Small Enterprises are expanding coverage purchases most rapidly.
Distribution Channel:
Channel economics diverge sharply, with digital platforms compressing acquisition costs while broker networks defend corporate relationships.
- Brokers:Independent intermediaries controlling mid-market and corporate placements through bundled program design. Commission structures resist disintermediation despite carrier pressure on cost-to-serve ratios.
- Online Platforms:Insurtech aggregators and direct carrier portals enabling self-service policy comparison. Urban millennials in Bogotá and Medellín bypass traditional channels for term-life and health rider purchases.
- Agents:Tied representatives pushing proprietary products through face-to-face sales. Secondary city penetration relies on agent networks where digital literacy lags banking corridor levels.
- Direct Sales:Carrier-owned channels including call centers and branch offices. Bancassurance integration through Davivienda creates captive distribution for modular life products targeting underbanked segments.
Brokers maintain the deepest corporate penetration, yet Online Platforms are climbing the fastest among individual purchasers.
Premium Type:
Payment structure preferences reflect employer sponsorship levels and policyholder liquidity constraints across income tiers.
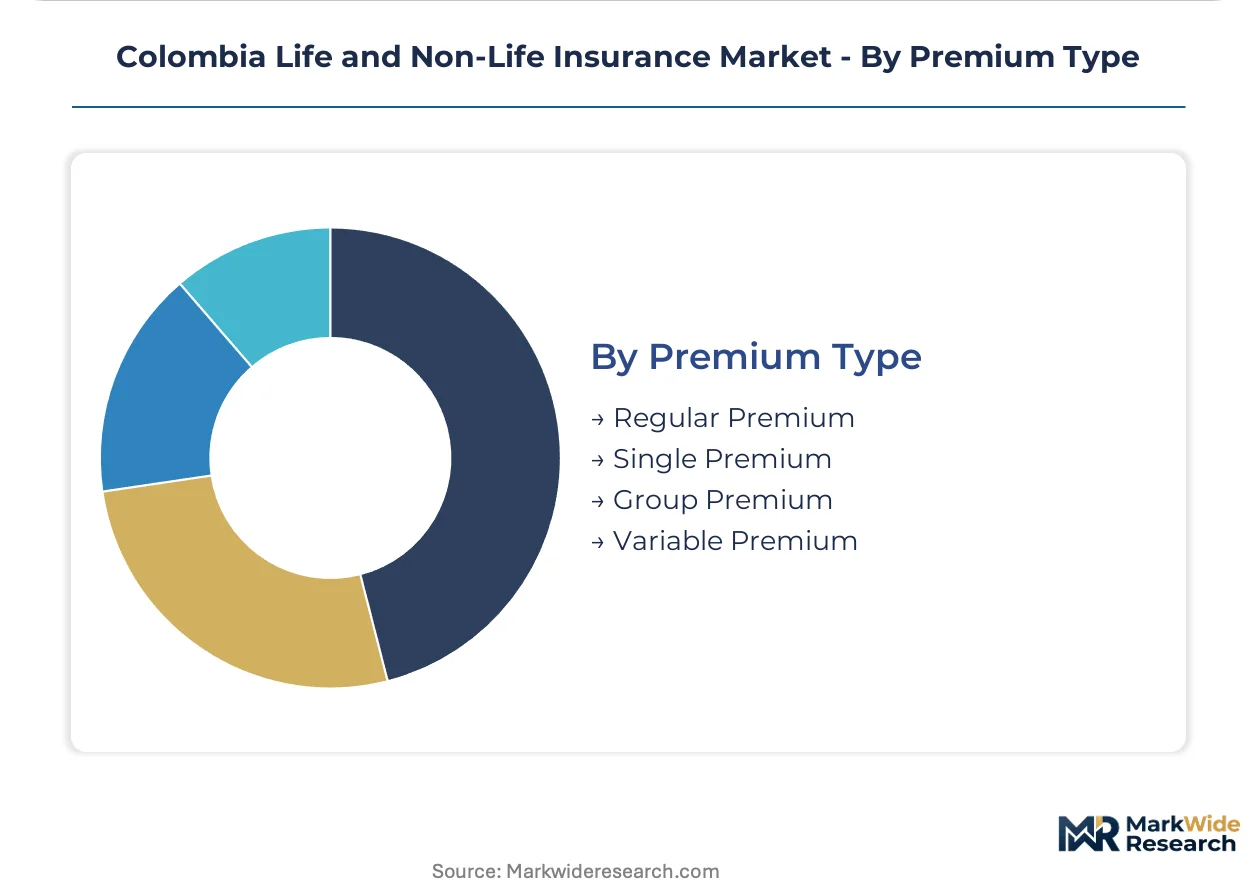
- Regular Premium:Monthly or annual payments standard for employer-sponsored group coverage. Payroll deduction mechanisms dominate in formal sector employment linked to EPS complementary mandates.
- Group Premium:Collective billing for corporate and association-sponsored policies. Risk pooling efficiencies lower per-capita costs for Bogotá-based enterprises with stable workforce retention.
- Single Premium:Lump-sum payment for annuities and investment-linked life contracts. High-net-worth individuals in Medellín's professional services sector favor these for tax-advantaged wealth transfer.
- Variable Premium:Adjustable payments tied to unit-linked investment performance. Limited penetration reflects regulatory reserve complexity under Circular Externa 029 technical provision requirements.
Regular Premium structures dominate volume, while Group Premium formats are scaling fastest through SME sector expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colombia's Financial Superintendence mandates Circular Externa 029 solvency standards nationwide, driving capital reserve increases that reshape competitive positioning across Bogotá's financial corridor, Medellín's manufacturing belt, and Pacific port zones.
Bogotá Capital District
Employer-mandated EPS complementary coverage concentrates premium volume in Bogotá's corporate corridor, where payroll-linked life policies dominate new business acquisition. The Financial Superintendence enforces anti-money laundering protocols under UIAF oversight, elevating compliance costs for carriers serving the financial district. Insurance brokers control mid-market and corporate placements through bundled property-casualty programs targeting enterprises along Carrera Séptima.
Antioquia and Medellín Metro
Small enterprises in Medellín's manufacturing belt accelerate health and property line purchases, with commercial auto coverage expanding fastest among logistics subcontractors. Bancassurance integration through Davivienda's branch footprint creates captive distribution for modular life products. Urban millennials in El Poblado and Laureles bypass traditional broker channels for direct digital comparison platforms when purchasing term-life riders.
Valle del Cauca and Cali Corridor
Property underwriters leverage specialized catastrophe reinsurance treaties to cover seismic risks in Pacific and Andean regions previously deemed uninsurable. The Ministry of Agriculture's rural development priorities align with parametric agriculture coverage opportunities for climate-vulnerable coffee cooperatives in the Cauca River valley. Claims inflation in health lines erodes technical margins as medical cost escalation outpaces premium adjustment cycles.
Pacific Coast and Buenaventura
Microinsurance distribution presents whitespace targeting informal port workers and logistics subcontractors excluded from formal EPS networks. SOAT price caps imposed by the Ministry of Finance compress margins on mandatory auto liability lines, constraining underwriting flexibility for carriers serving the maritime logistics corridor. Telematics-enabled usage-based insurance gains traction among fleet operators seeking premium discounts tied to actual mileage and braking patterns.
Santander and Bucaramanga Industrial Zone
Mid-tier carriers lacking reinsurance backing face consolidation pressure as Circular Externa 029 reserve adequacy tests trigger market exits. Legacy core system migration challenges impede real-time data integration with UIAF monitoring systems, elevating compliance breach risk for regional underwriters. Actuarial talent scarcity delays product development cycles for stochastic modeling of catastrophe risk and IFRS 17 technical provision calculations.
Colombia Life and Non-Life Insurance Market Competitive Environment
Player mix skews toward diversified financial conglomerates with bancassurance networks and specialized property-casualty underwriters with catastrophe reinsurance access. Market structure concentrates around carriers with sufficient capital reserves to meet Circular Externa 029 solvency thresholds, forcing smaller authorized auto underwriters to exit SOAT mandatory liability coverage. Strategic archetypes include integrated financial services groups leveraging banking distribution, regional property specialists with seismic zone expertise, and digital-first platforms targeting urban millennials. Competitive moves center on reinsurance treaty renegotiations to meet compliance deadlines and direct digital channel investments to bypass broker commission structures.
Within the integrated financial services tier, Grupo Sura and Suramericana exemplify conglomerate-scale carriers with captive banking distribution networks. Seguros Bolivar occupies a position among property-casualty specialists with catastrophe reinsurance backing for high-risk seismic zones. Mapfre represents the multinational platform archetype competing through direct digital channels and modular health rider products. These carriers anchor the competitive landscape as regulatory reserve requirements reshape market access for mid-tier underwriters lacking international reinsurance relationships.
| Leading Market Players |
|---|
| Grupo Sura |
| Suramericana |
| Seguros Bolivar |
| Seguros Alfa |
| Axa |
| Allianz |
| Mapfre |
| Alfa Vida |
| Bolivar |
| Others |
Value Chain & Pricing Dynamics
Scale economies in reinsurance treaty placement concentrate pricing power among carriers with international counterparty relationships, compressing margin floors for mid-tier underwriters lacking capital reserves under Circular Externa 029. This concentration shapes both supply-side carrier consolidation and demand-side broker channel economics across Bogotá's corporate corridor and Medellín's manufacturing belt.
Pricing Analysis
Certification level under Financial Superintendence solvency standards creates the primary spread between premium tiers, with Circular Externa 029-compliant carriers commanding rate advantages over undercapitalized competitors. Three-tier pricing structure across premium, standard, and economy levels reflects reserve adequacy, reinsurance backing depth, and distribution channel cost. Pricing pressure stems from SOAT price caps imposed by the Ministry of Finance, which compress margins on mandatory auto liability lines. Small enterprises in Medellín's industrial belt exhibit highest price sensitivity, while large corporates in Bogotá's financial district prioritize coverage breadth over rate competition.
Supply Chain Analysis
Colombia and international reinsurance markets in Bermuda and London anchor risk capacity for seismic zone property coverage and catastrophe treaty backing. Domestic carriers draw from global reinsurance capacity for technical provisions, specialized catastrophe modeling, and claims reserve instruments. Single-source vulnerability concentrates in international reinsurer dependence, exposing balance sheets to currency volatility and foreign counterparty credit risk. Distribution runs through broker-controlled corporate placements in Bogotá, bancassurance integration via Davivienda's banking network, and direct digital platforms targeting urban millennials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against fintech-enabled insurtech aggregators unbundling traditional product components and capturing price-sensitive individual purchasers through self-service comparison platforms.
For Market Incumbents: Compound bancassurance channel depth through Davivienda's digital banking integration to lock in sticky premium flows from payroll-linked life policies. Accelerate reinsurance treaty renegotiations with Bermuda and London markets to secure Circular Externa 029 compliance before reserve adequacy tests trigger forced exits. Vertical integration into captive distribution displaces broker commission structures eroding cost-to-serve ratios in the corporate segment.
For New Entrants and Emerging Players: Fast-track Financial Superintendence authorization for microinsurance products targeting informal port workers in Buenaventura excluded from formal EPS networks. White-space concentration in parametric agriculture coverage for climate-vulnerable coffee cooperatives in Valle del Cauca aligns with Ministry of Agriculture rural development priorities. Go-to-market through mobile-first distribution partnerships with logistics subcontractors bypasses legacy broker channel saturation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carriers with modular product engines and real-time compliance reporting capabilities integrated with UIAF anti-money laundering systems. Long-term viability across the analysis window rests on reinsurance relationship depth and core system modernization progress rather than premium volume scale. Acquisition target archetype: regional property specialists with seismic zone expertise and existing catastrophe treaty access. Signal to watch: Circular Externa 029 reserve adequacy test failures triggering forced divestiture of mid-tier carrier portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Reinsurance Treaty Renegotiation | Secures Circular Externa 029 compliance through Bermuda and London counterparty relationships. |
| Bancassurance Channel Deepening | Captures payroll-linked premium flows via Davivienda's digital banking integration. |
| Telematics Platform Deployment | Enables usage-based auto pricing for Bogotá fleet operators beyond SOAT rate caps. |
| Parametric Product Development | Aligns with Ministry of Agriculture priorities for climate-vulnerable coffee cooperatives. |
| Core System Modernization | Integrates real-time UIAF compliance reporting to reduce regulatory breach risk. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interviews with insurance carrier executives, reinsurance placement specialists, broker network heads, and Financial Superintendence regulatory affairs officers. Secondary validation drew from UIAF anti-money laundering filings, Financial Superintendence circulars, reinsurance treaty disclosure databases, and Ministry of Finance SOAT premium band adjustments. Bottom-up premium volume estimates triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, analytical frameworks modeled product type segmentation, end user archetypes, distribution channel economics, and premium payment structures alongside regional regulatory cluster variations. CAGRs were derived from historical premium trajectory analysis and forward-looking reserve adequacy stress testing. Forecast inputs incorporated Circular Externa 029 solvency threshold evolution and reinsurance capacity availability from international markets.
Underlying assumptions cover stable Financial Superintendence regulatory enforcement, sustained reinsurance market access, and consistent EPS complementary mandate employer compliance, with deviation risk concentrated in Ministry of Finance SOAT price cap adjustments and international reinsurer credit availability. Recalibration cycles align with material shifts in solvency regulation, reinsurance treaty renewal patterns, and digital distribution adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
UAE Life & Non-Life Insurance Market
Life and Non Life Insurance
Canada Life and Non-Life Insurance Market
Life and Non Life Insurance
Greece Life and Non-Life Insurance Market
Life and Non Life Insurance
USA Life and Non-Life Insurance Market
Life and Non Life Insurance
Israel Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Children Life Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Sweden Life and Non-Life Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market