
 Germany Life and Non-Life Insurance Market | 2026-2036
Germany Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Life and Non-Life Insurance Market Foresight
Buyer concentration among Germany's corporate policyholders is broadening as mid-sized enterprises diversify risk coverage beyond traditional bundles. Allianz Group leverages its bancassurance network to sustain dominant placement across retail channels. Münchener Rück Gruppe anchors global reinsurance capacity that feeds directly into German primary carrier pricing. Talanx Konzern differentiates through industrial specialty lines targeting manufacturing exporters.
Germany life and non-life insurance encompasses risk-transfer contracts where insurers pool policyholder premiums to cover mortality, morbidity, property damage, and liability exposures against defined capital reserves. Products incorporate biometric risk tables, catastrophe loss models, and risk-adjusted capital charges to match long-duration liabilities with asset portfolios. Term life and motor insurance command the largest premium volumes, while online platforms represent the fastest-growing distribution channel as digital onboarding reduces acquisition costs. Property and liability lines retain the deepest margin pools due to complex risk assessment barriers that limit price competition.
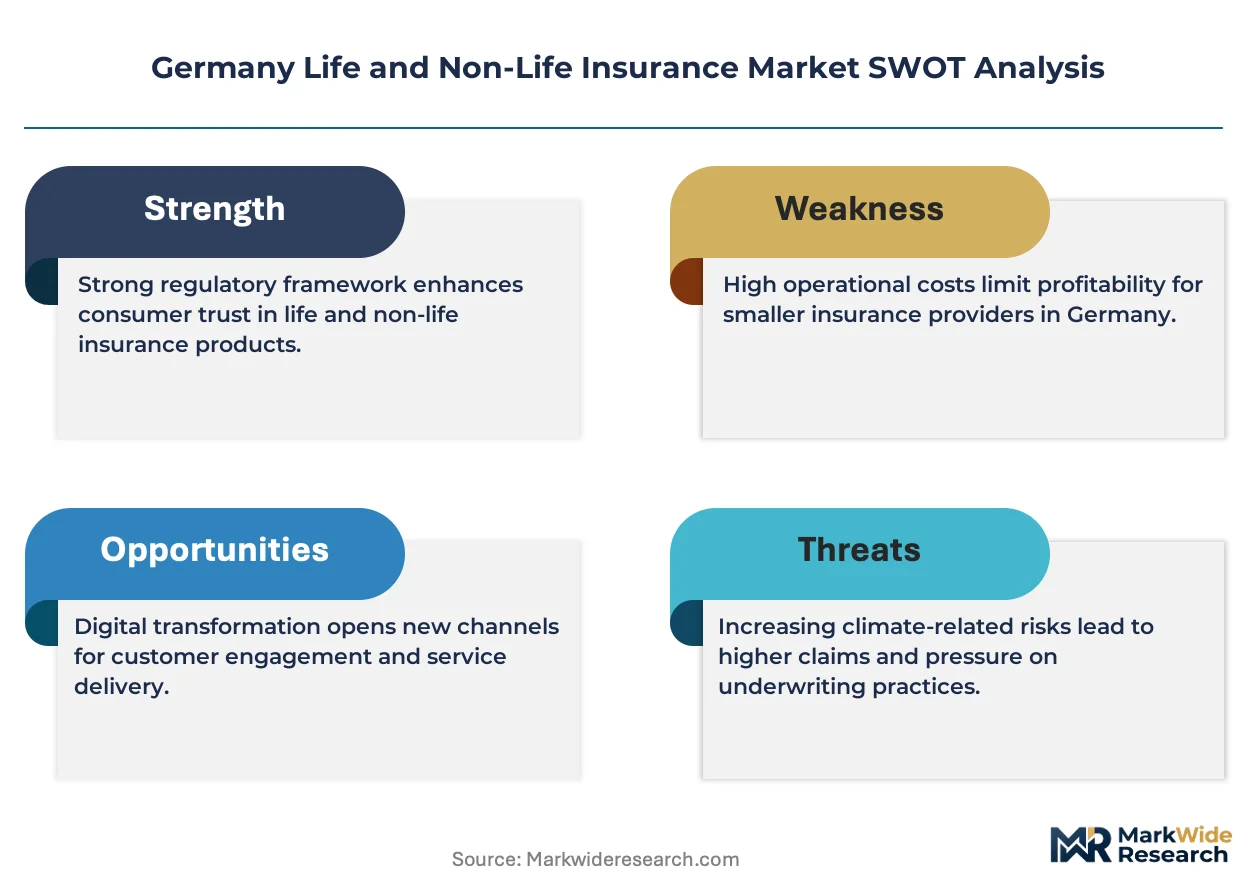
BaFin enforces Solvency II capital requirements that force insurers to hold risk-sensitive reserves, directly elevating pricing for long-duration life products. The EU Green Deal and national climate disclosure rules pressure property underwriters to integrate flood and storm risk models into premium calculations. Stakeholders must monitor how digital distribution platforms reshape customer acquisition economics against traditional agent networks.
Market Dynamics
BaFin's Solvency II capital adequacy framework is compressing risk-adjusted returns across German life portfolios while simultaneously accelerating digital distribution investments to offset elevated acquisition costs.
Growth Catalysts
- EU Green Deal climate disclosure mandates:Property underwriters in Bavaria and North Rhine-Westphalia now embed flood and storm risk models into premium calculations, expanding addressable coverage for climate-exposed assets.
- Small business coverage diversification:Mid-sized enterprises across Baden-Württemberg are unbundling traditional insurance bundles to purchase standalone cyber and D&O policies.
- Bancassurance channel penetration:Sparkassen and cooperative banking networks deepen insurance product placement through embedded finance integrations at branch level.
Market Restraints
- Low interest rate environment:German Bund yields below 2.5% compress guaranteed return provisions in traditional life products, forcing insurers to shift toward unit-linked structures.
- Reinsurance capacity concentration:Primary carriers remain dependent on Münchener Rück Gruppe and Hannover Rück for catastrophe coverage, creating pricing power asymmetry in hard markets.
- Legacy IT architecture:Core policy administration systems at established carriers require multi-year migration timelines to support real-time data exchange with BaFin's supervisory reporting portal.
Strategic Opportunities
- Embedded insurance in mobility services:Usage-based motor coverage integrated with connected vehicle platforms offers granular risk pricing for fleet operators in Saxony.
- Industrial specialty expansion:Manufacturing exporters in Hesse seek customized cargo and product liability programs aligned with Incoterms 2020 trade frameworks.
- Digital onboarding platforms:Direct-to-consumer term life sales through smartphone-enabled biometric verification reduce acquisition costs versus traditional agent networks.
Industry Challenges
- Actuarial talent scarcity:German insurers compete with fintechs and consulting firms for data science professionals capable of integrating machine learning into Solvency II internal models.
- Interoperability with legacy systems:API connectivity between new digital distribution layers and decades-old policy administration databases creates integration bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Life and Non-Life Insurance Market |
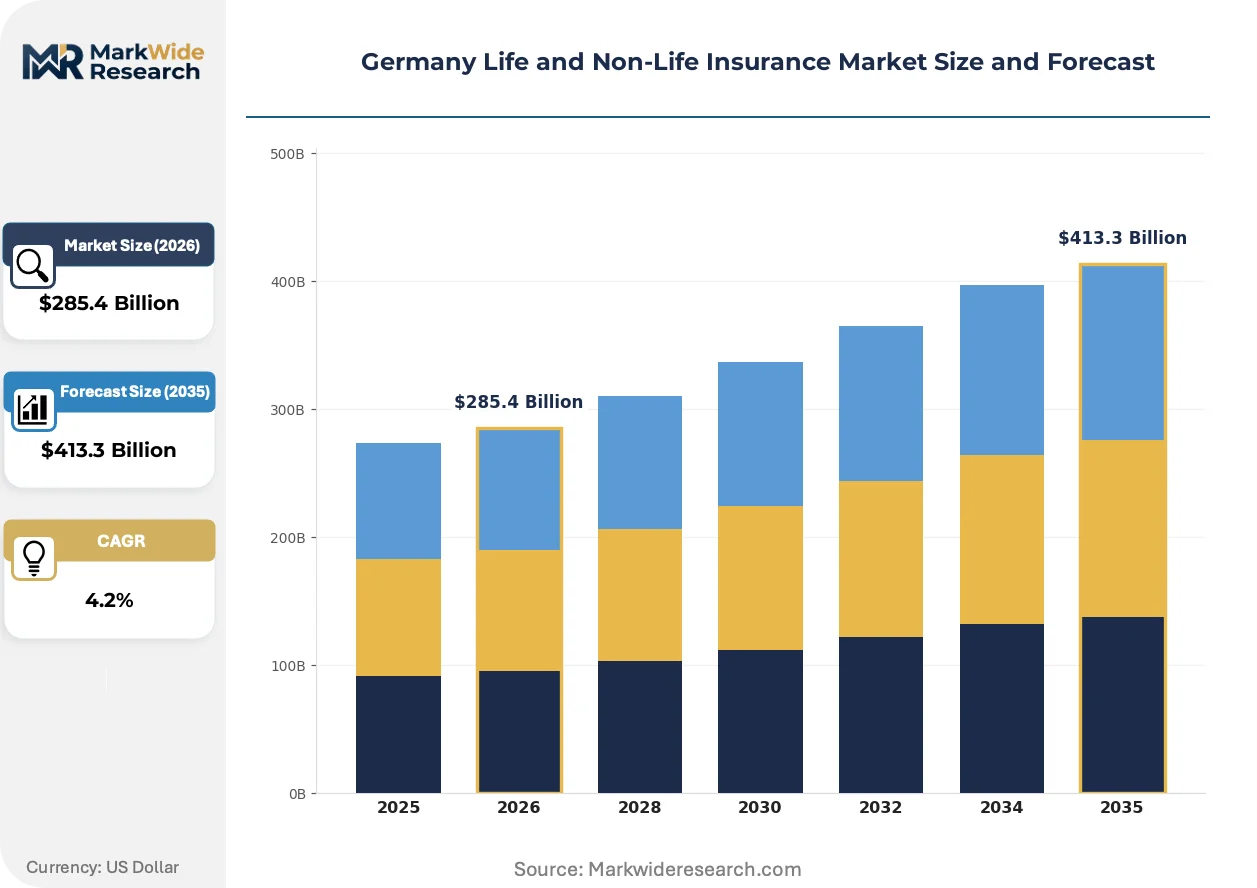
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $413.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Term Life, Whole Life, Property, Liability, Motor, Travel Distribution Channel: Bancassurance, Direct Sales, Brokers, Online Platforms, Agents Customer Category: Individual Policyholders, Small Businesses, Corporates, Non-Profit Organizations Policy Features: Premium Payment Frequency, Sum Assured, Riders, Policy Tenure, Claims Settlement Time |
| Companies Covered | Allianz Group, Münchener Rück Gruppe, Talanx Konzern, R+V Konzern, Generali Deutschland AG, Debeka Versicherungen, AXA Konzern AG, Versicherungskammer Bayern, HUK-Coburg Versicherungsgruppe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Life and Non-Life Insurance Market Shifts & Advancements
Telematics and parametric triggers are reshaping risk transfer mechanics across German insurance lines, compressing traditional indemnity structures while expanding preventive service integration.
Usage-based motor insurance is electrifying competitive positioning in the German auto coverage segment. Fleets and private policyholders in urban centers adopt smartphone-integrated driving behavior monitoring that adjusts premiums monthly based on actual mileage and braking patterns. This data granularity is compressing cross-subsidies between low-risk and high-risk driver pools, forcing traditional annual-contract underwriters to accelerate platform investments.
Solvency II's risk-sensitive capital charges under BaFin supervision are elevating pricing transparency requirements for long-duration life products. German carriers must now hold additional reserves against guaranteed interest rate risks, compressing product margins. The annuity and endowment segments respond by accelerating unit-linked product development to transfer investment risk to policyholders.
Mid-sized corporate buyers in Rhineland manufacturing clusters now unbundle insurance procurement from banking relationships, establishing standalone risk management functions with direct carrier negotiations. Digital broker platforms displace traditional Versicherungsmakler for standard property and liability placements. This channel rotation is most visible in Baden-Württemberg's automotive supplier ecosystem, where risk managers prioritize API-enabled quote comparison over personal advisory relationships.
Germany Life and Non-Life Insurance Market Segmentation
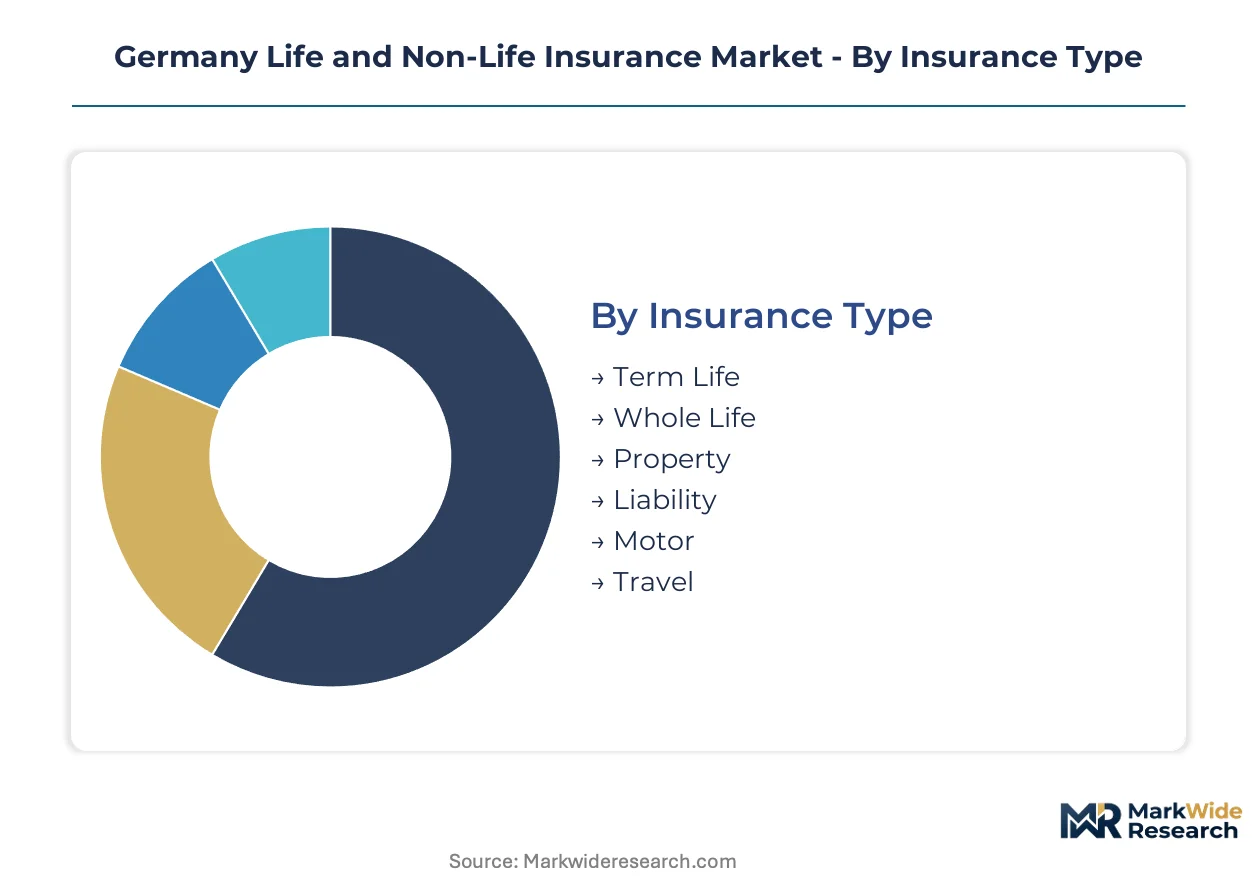
German insurers structure product portfolios around capital intensity variations across life and non-life lines. Solvency II reserve requirements differ sharply between long-duration biometric liabilities and short-tailed property risks. Distribution economics and customer acquisition costs further differentiate segment profitability.
Insurance Type:
Capital intensity peaks in life segments requiring decades-long reserve maintenance against guaranteed returns. Non-life lines demand less balance sheet commitment but face catastrophe exposure concentration.
- Term Life:Pure mortality coverage with fixed premiums over contract duration. Corporate group policies in Baden-Württemberg's automotive sector drive volume as employers expand employee benefit packages amid talent competition.
- Whole Life:Permanent coverage bundling mortality protection with cash value accumulation. Bavarian retail demand concentrates in unit-linked variants as Bund yield compression erodes guaranteed return product viability.
- Property:Physical asset protection against fire, flood, and storm perils. North Rhine-Westphalia industrial zones absorb capacity as climate disclosure rules force flood risk model integration.
- Liability:Third-party obligation coverage spanning professional and product exposures. Mid-sized manufacturers in Hesse seek customized programs aligned with export trade frameworks.
- Motor:Vehicle damage and third-party bodily injury protection. Telematics-enabled usage-based contracts in Saxony urban centers are compressing traditional annual policy pricing.
- Travel:Short-duration trip cancellation and medical emergency coverage. Online direct sales channels capture leisure demand from price-sensitive individual policyholders.
Whole Life absorbs the bulk of installed capacity; Motor is expanding most quickly.
Distribution Channel:
Cost tier differentiation separates high-touch advisory models from automated platform economics. Commission structures and customer lifetime value calculations vary dramatically across channel mix.
- Bancassurance:Embedded product placement through Sparkassen and cooperative banking networks. Branch-level integration in rural Bavaria sustains dominant retail penetration for standardized life products.
- Direct Sales:Carrier-owned channels bypassing intermediary commissions. Allianz leverages proprietary salesforce for complex whole life consultations in affluent suburban markets.
- Brokers:Independent advisory intermediaries serving commercial accounts. Industrial specialty placements in Rhineland manufacturing clusters rotate toward digital broker platforms.
- Online Platforms:Smartphone-enabled quote comparison and policy issuance. Term life and motor segments in Berlin-Brandenburg metropolitan areas show steepest adoption curves.
- Agents:Tied representatives with exclusive carrier appointments. Legacy Versicherungsmakler relationships persist in aging policyholder demographics resistant to digital migration.
Bancassurance retains the deepest premium pool; Online Platforms are gaining share fastest.
Customer Category:
Application complexity escalates from standardized individual products to bespoke corporate risk programs. Underwriting resource allocation and pricing sophistication scale with account size.
- Individual Policyholders:Mass-market retail buyers purchasing standardized term life and motor coverage. Direct-to-consumer digital onboarding in Hamburg reduces acquisition costs versus traditional agent networks.
- Small Businesses:Mid-sized enterprises unbundling traditional insurance bundles. Baden-Württemberg automotive suppliers purchase standalone cyber and D&O policies through specialized broker channels.
- Corporates:Large industrial accounts with captive risk management functions. Manufacturing exporters negotiate customized cargo and product liability programs aligned with Incoterms frameworks.
- Non-Profit Organizations:Social sector entities with constrained risk budgets. Municipal insurers in North Rhine-Westphalia offer subsidized coverage for volunteer liability and property exposures.
Individual Policyholders generate the highest transaction volume; Small Businesses show the steepest expansion trajectory.
Policy Features:
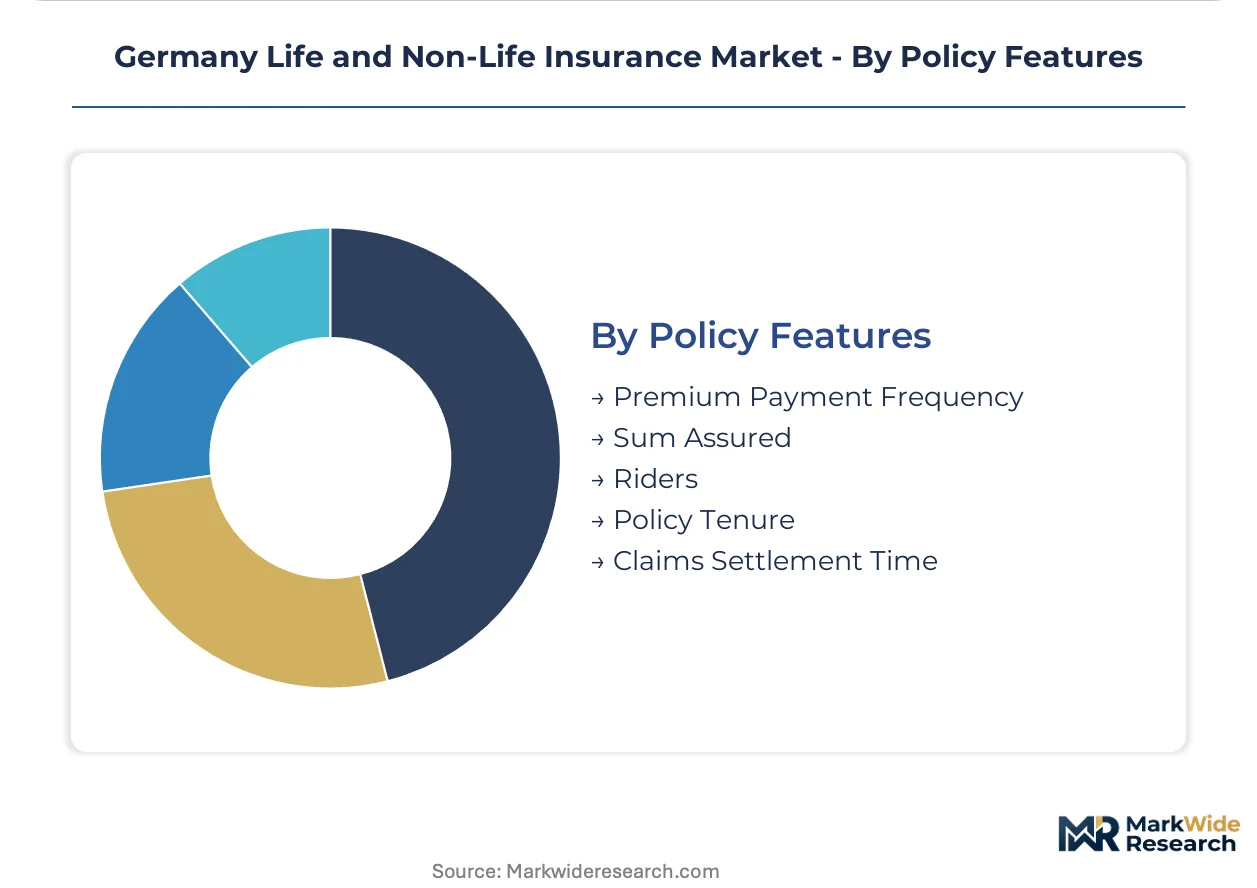
Margin structure varies across contractual terms and service-level commitments. Feature customization drives pricing differentiation and retention economics.
- Premium Payment Frequency:Monthly, quarterly, or annual contribution schedules. Annual prepayment discounts attract liquidity-rich policyholders in Hesse's financial services corridor.
- Sum Assured:Maximum benefit payable under contract terms. High-net-worth whole life applications in Munich metropolitan area trigger enhanced medical underwriting protocols.
- Riders:Supplementary coverage attachments for critical illness or disability. Term life base policies in Stuttgart industrial zones bundle occupational accident riders for manufacturing workers.
- Policy Tenure:Contract duration ranging from annual renewable to lifetime guarantees. Long-duration life reserves face Solvency II capital charges that compress guaranteed return product margins.
- Claims Settlement Time:Service-level commitment for benefit disbursement. Digital claims platforms in Frankfurt reduce motor property damage settlement cycles below traditional paper-based timelines.
Sum Assured configurations absorb the bulk of actuarial capacity; Claims Settlement Time optimization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's concentrated reinsurance capital anchors German risk-transfer capacity, while regional demand patterns fragment across industrial clusters and demographic centers.
Bavaria
Munich-based manufacturing exporters drive demand for customized cargo and product liability coverage. BaFin's Solvency II reporting requirements elevate reserve standards for life insurers headquartered in the region. Industrial zones around Augsburg absorb expanding property capacity as climate disclosure rules integrate flood risk models.
North Rhine-Westphalia
Rhineland chemical and steel clusters generate concentrated industrial specialty premium pools. The EU Green Deal mandates pressure property underwriters in Cologne-Düsseldorf corridor to embed storm exposure calculations. Mid-sized enterprises in Dortmund-Essen unbundle traditional insurance bundles for standalone cyber policies.
Baden-Württemberg
Automotive supplier ecosystems in Stuttgart industrial zone expand employee benefit term life packages amid talent competition. Sparkassen bancassurance networks sustain dominant retail penetration for standardized whole life products. Risk managers prioritize API-enabled broker platforms over traditional Versicherungsmakler relationships.
Hesse
Frankfurt's financial services corridor concentrates liquidity-rich policyholders seeking annual prepayment discounts. Deutsche Bundesbank proximity elevates actuarial talent competition with fintechs and consulting firms. Manufacturing exporters negotiate Incoterms-aligned cargo programs through captive risk management functions.
Berlin-Brandenburg
Metropolitan digital adoption curves steepen for online platform distribution of term life and motor coverage. Smartphone-enabled biometric verification reduces acquisition costs versus traditional agent networks. Telemedicine-integrated health riders gain traction among tech-sector employees in Potsdam corridor.
Germany Life and Non-Life Insurance Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded insurance and telematics-enabled niches. Allianz Group, Münchener Rück Gruppe, and Talanx Konzern anchor a consolidated structure where bancassurance networks and global reinsurance capacity create defensive moats. Three archetypes dominate: integrated financial conglomerates with proprietary distribution, specialty reinsurers feeding primary carrier pricing, and mutual insurers leveraging cooperative banking ties. Competitive moves concentrate on digital platform investments and industrial specialty line diversification.
Among integrated financial conglomerates, Allianz Group exemplifies the bancassurance-anchored archetype through embedded placement at branch level. Münchener Rück Gruppe occupies the global reinsurance tier, feeding capacity directly into German primary market pricing. Talanx Konzern represents the industrial specialty vector, targeting manufacturing exporters with customized risk programs. These three entities collectively illustrate how scale, distribution control, and segment focus stratify competitive positioning.
| Leading Market Players |
|---|
| Allianz Group |
| Münchener Rück Gruppe |
| Talanx Konzern |
| R+V Konzern |
| Generali Deutschland AG |
| Debeka Versicherungen |
| AXA Konzern AG |
| Versicherungskammer Bayern |
| HUK-Coburg Versicherungsgruppe |
| Others |
Supply & Pricing Matrix
Mid-sized enterprises unbundling traditional insurance bundles in Baden-Württemberg and North Rhine-Westphalia are forcing primary carriers to restructure product packaging and pricing architectures. This procurement shift pressures insurers to unbundle service components and expose underlying cost structures, compressing margin pools previously protected by opaque bundled pricing.
Pricing Analysis
Warranty and claims service bundling separates premium-tier offerings from stripped-down economy products across German insurance lines. Three-tier pricing structure across premium, standard, and economy levels reflects Solvency II capital charge differentials and digital distribution cost savings. Pricing pressure stems from telematics-enabled usage-based motor contracts compressing traditional annual policy premiums. Small businesses exhibit highest price sensitivity as they migrate to API-enabled broker platforms for transparent quote comparison.
Supply Chain Analysis
Single-source vulnerability sits with Münchener Rück Gruppe and Hannover Rück for catastrophe reinsurance capacity feeding German primary carrier pricing. Risk modeling software and actuarial talent concentrate in Frankfurt, Munich, and London financial centers. Supply chain risk centers on regulatory restriction as BaFin tightens Solvency II reporting requirements and climate disclosure mandates. Distribution runs through bancassurance networks, independent brokers, and direct digital platforms in parallel channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Life and Non-Life Insurance Market is executing a technology transition where telematics platforms and AI-enabled risk scoring displace legacy actuarial tables and manual underwriting workflows.
For Market Incumbents: Lock in bancassurance channel control through deeper Sparkassen and cooperative banking integrations before digital brokers capture mid-sized commercial accounts. Invest in API-enabled policy administration systems to resolve legacy IT bottlenecks threatening BaFin reporting compliance. Threat vector: fintechs and insurtechs with machine learning capabilities poaching data science talent for Solvency II internal model development. For New Entrants and Emerging Players: EU Green Deal climate disclosure mandates in Germany open a window for parametric property products targeting flood-exposed industrial zones in North Rhine-Westphalia. White-space targets include embedded insurance in connected vehicle platforms for Saxony fleet operators and smartphone-enabled biometric verification for direct term life sales in Berlin-Brandenburg. Go-to-market angle: partnership with automotive OEMs for usage-based motor coverage integration. For Investors and Strategic Acquirers: The window for entry favors digital distribution platforms with Solvency II-compliant data infrastructure and established API connectivity to legacy carrier systems. Long-term viability hinges on capturing mid-sized enterprise accounts rotating away from traditional Versicherungsmakler relationships toward automated procurement. Signal to watch: BaFin regulatory technology sandbox approvals accelerating insurtech market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Enables granular risk pricing for motor fleets in Saxony urban centers through connected vehicle data feeds. |
| Solvency II Internal Model Investment | Reduces risk-adjusted capital charges for long-duration life portfolios under BaFin supervision. |
| Climate Risk Model Deployment | Integrates flood and storm exposure calculations into North Rhine-Westphalia property underwriting. |
| API-Enabled Broker Platform | Captures mid-sized Baden-Württemberg automotive suppliers migrating from traditional advisory relationships. |
| Embedded Bancassurance Expansion | Deepens Sparkassen branch-level product placement for standardized whole life coverage in rural Bavaria. |
Research Methodology
Document review covered BaFin regulatory filings, Solvency II reporting disclosures, and EU Green Deal implementation guidelines, complemented by interviews with chief risk officers at primary carriers, actuarial directors at reinsurance groups, and digital distribution heads at broker platforms. Secondary validation drew from insurance association statistical yearbooks, trade register data, and premium volume reports. Bottom-up policy-level modeling triangulated against top-down market sizing from regulatory capital disclosures.
Cross-referencing historical premium trends against panel input from underwriting executives informed the analytical framework across the analysis window. Segmentation dimensions modeled include insurance type, distribution channel, customer category, and policy feature configurations. CAGRs were derived from risk-adjusted growth assumptions incorporating biometric liability duration, catastrophe exposure concentration, and digital channel penetration rates. Industry-specific forecast inputs encompassed Solvency II capital charge evolution and climate model integration timelines.
The model assumes a particular technology adoption path for telematics and AI-enabled underwriting; alternative pathways for legacy actuarial system retention would alter the outlook. Forecasts reflect assumptions regarding regulatory implementation pace, reinsurance capacity availability, and interest rate trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Norway Life and Non-Life Insurance Market
Life and Non Life Insurance
Asia-Pacific Life and Annuity Insurance Market
Life and Non Life Insurance
Teenager Life Insurance Market
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Denmark Life and Non-Life Insurance Market
Life and Non Life Insurance
Brazil Life and Non-Life Insurance Market
Life and Non Life Insurance
Malaysia Life Insurance Market
Life and Non Life Insurance
Uruguay Life and Non-Life Insurance Market
Life and Non Life Insurance
US Burial Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
Iran Property and Casualty Insurance Market