
 IoT Testing Equipment Market | 2026-2036
IoT Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Testing Equipment Market Outlook
Silicon carbide is recalibrating thermal test parameters for power electronics in connected automotive and industrial nodes. Keysight Technologies leverages protocol emulation depth to anchor North American and European certification workflows. ROHDE&SCHWARZ dominates millimeter-wave test benches for 5G-integrated IoT modules. Anritsu specializes in compact field-test sets that service providers deploy for live network diagnostics.
IoT testing equipment comprises signal generators, spectrum analyzers, protocol conformance systems, and environmental stress chambers designed to verify connectivity reliability, power integrity, and electromagnetic compatibility across wireless sensor networks. These instruments subject devices to temperature cycling, fading simulation, and interoperability suites to certify operational readiness before commercial deployment. Network analyzers command the largest product-type revenue pool due to 5G NR and Wi-Fi 7 complexity, while protocol analyzers represent the fastest-expanding category as Matter and Thread standards proliferate across smart home ecosystems. Among applications, automotive systems absorb the steepest test-equipment investment as OEMs validate vehicle-to-everything links against SAE and UNECE frameworks.
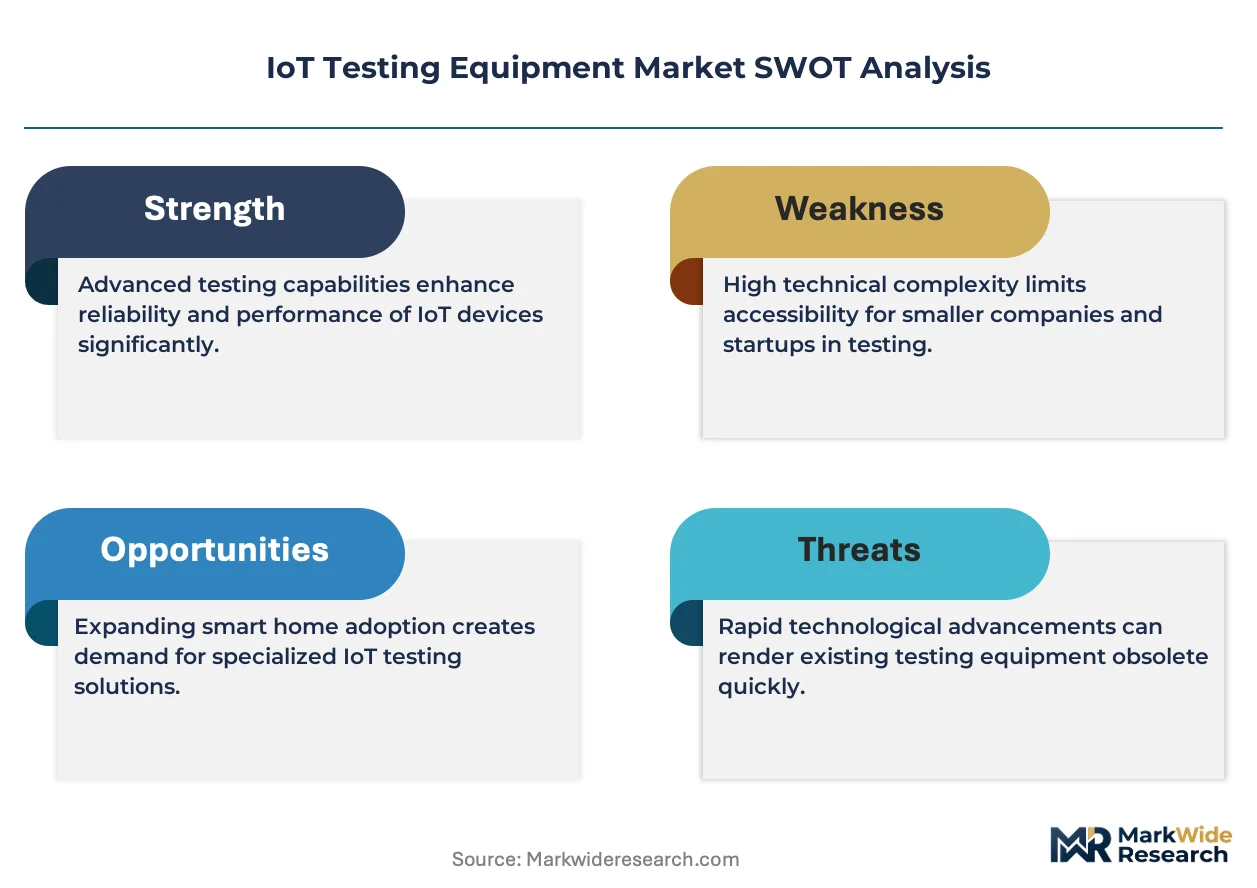
FCC Part 15 emissions rules, the EU Cyber Resilience Act, and FDA software-as-a-medical-device guidance collectively mandate pre-market electromagnetic and cybersecurity validation for IoT endpoints sold in the United States and Europe. This regulatory stack forces manufacturers to maintain captive test labs or outsource to accredited third-party facilities, embedding equipment demand into product release cycles. Stakeholders must weigh capital deployment against subscription-based test-service models as certification velocity becomes a bottleneck to revenue recognition.
Market Dynamics
Silicon carbide power semiconductors are forcing recalibration of thermal cycling protocols across automotive and industrial IoT certification labs, as device junction temperatures push past legacy test limits.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory pre-market cybersecurity validation for all network-connected hardware sold in Europe is expanding third-party test lab throughput requirements.
- Vehicle-to-everything protocols:SAE J2945 and UNECE WP.29 mandates for connected vehicles are embedding RF conformance testing into every automotive release cycle.
- 5G-Advanced deployment:Millimeter-wave spectrum activation for industrial IoT backhaul is creating demand for over-the-air test chambers in Germany, Japan, and the United States.
Market Restraints
- RF component concentration:Gallium nitride amplifier supply tightness from a handful of foundries is extending lead times for high-frequency signal generators.
- Capital intensity:Full 5G NR protocol conformance systems require seven-figure capital commitments that mid-size device makers cannot absorb.
- Regulatory fragmentation:Divergent electromagnetic emission limits between FCC Part 15 and Japan's Radio Law force redundant test campaigns for multi-region product launches.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for electronics assembly are attracting test equipment providers to establish calibration facilities near Chennai and Noida clusters.
- Digital twin integration:Virtual pre-certification environments are compressing physical chamber time for thermal and mechanical stress validation.
- Matter protocol proliferation:Thread-based smart home interoperability mandates are creating new protocol analyzer demand across residential IoT device categories.
Industry Challenges
- Millimeter-wave engineering scarcity:RF design expertise for 28 GHz and 39 GHz test fixture development remains concentrated among a narrow specialist labor pool.
- Multi-standard firmware complexity:Simultaneous Wi-Fi 7, Bluetooth 5.4, and Zigbee validation requires test automation software that few captive labs have deployed.
- Third-party accreditation backlog:ISO/IEC 17025 certification delays at testing facilities are extending product release timelines by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Testing Equipment Market |
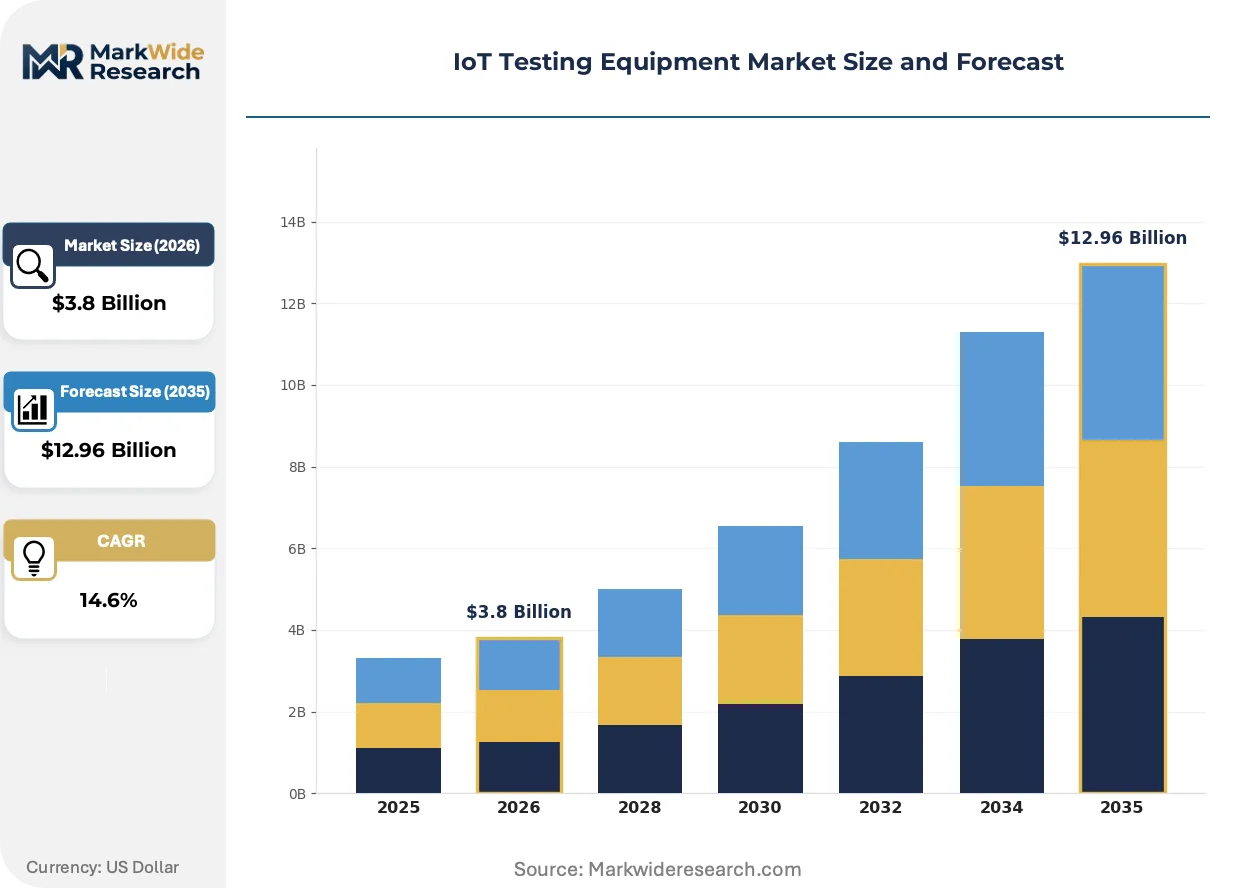
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Device Simulators, Protocol Analyzers, Network Analyzers Application: Smart Home, Industrial Automation, Healthcare Devices, Automotive Systems End User: Manufacturers, Service Providers, System Integrators, Research Institutions Technology: Cloud Computing, Edge Computing, AI-driven Solutions, Connectivity Standards |
| Companies Covered | Keysight Technologies, Anritsu, ROHDE&SCHWARZ, HCL Technologies, Capgemini SE, Infosys Limited, Tektronix, RIGOL Technologies, Ixia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Testing Equipment Market Strategic Shifts
Edge-native test architectures are displacing centralized lab workflows, while regulatory pressure on cybersecurity and emissions compliance is accelerating automation investment across certification chains.
Distributed test nodes with embedded spectrum monitoring are decentralizing RF validation from fixed facilities to production floors and field deployment sites. Automotive tier-1 suppliers are piloting these systems at scale to catch radiated emissions defects before vehicles reach homologation. This shift is decentralizing capital deployment patterns and compressing the feedback loop between design iteration and compliance sign-off.
The EU Cyber Resilience Act's vulnerability disclosure and automatic update mandates are forcing test houses to integrate penetration testing and firmware lifecycle validation into hardware certification workflows. Medical device OEMs face the steepest compliance burden as FDA software-as-a-medical-device guidance converges with European cybersecurity requirements. European notified bodies are expanding headcount to prevent bottlenecks in CE marking timelines.
Equipment-as-a-service contracting is displacing outright purchase for mid-volume IoT device manufacturers facing uncertain certification cadences. Test service providers in Germany and the United States are bundling chamber time with engineering support to capture recurring revenue from hardware startups. This model is most visible among Matter-certified smart home device makers who lack capital for captive lab investment.
IoT Testing Equipment Market Segmentation
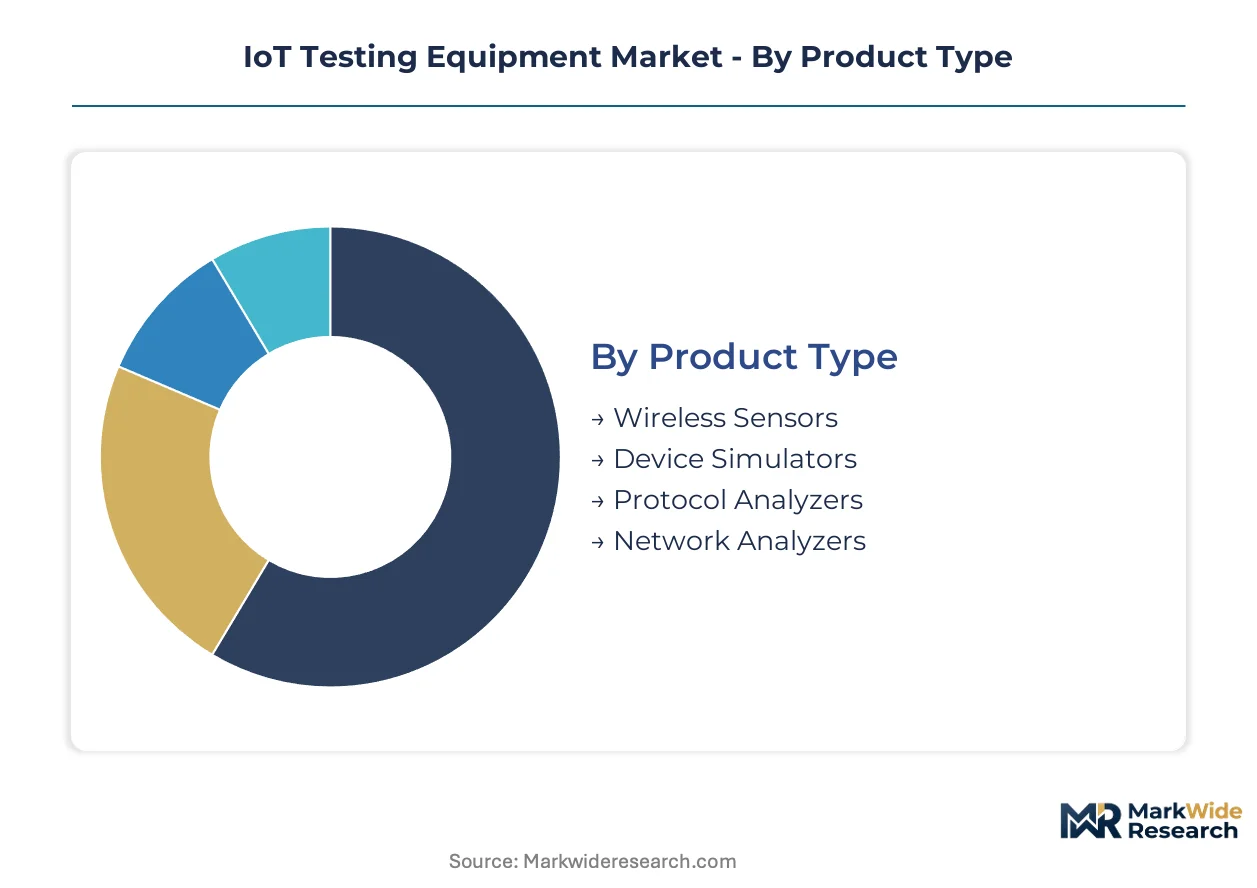
Certification complexity varies sharply across IoT testing equipment segments, with automotive and medical device categories bearing the heaviest regulatory loads. Equipment buyers align procurement strategies to the specific approval pathways their end products must traverse.
Product Type:
Network analyzers and protocol analyzers absorb disproportionate certification burden due to 5G NR and Matter standard validation requirements, while wireless sensors face lighter electromagnetic compliance overhead.
- Network Analyzers:Vector and scalar instruments measure S-parameters, impedance, and transmission characteristics across RF and microwave frequencies. Demand concentrates in Germany and the United States where automotive OEMs validate vehicle-to-everything modules against UNECE WP.29 mandates. These systems command premium pricing due to millimeter-wave capability requirements.
- Protocol Analyzers:Decoding and conformance verification tools for Bluetooth, Zigbee, Thread, and Matter stacks. Smart home device manufacturers in Shenzhen and Amsterdam drive procurement as Matter certification becomes mandatory for ecosystem compatibility. Firmware complexity is accelerating replacement cycles.
- Wireless Sensors:Environmental and motion sensing endpoints with embedded RF validation. Industrial automation deployments in Japan and South Korea favor compact, battery-operated units with pre-certified radio modules.
- Device Simulators:Emulation platforms that replicate IoT node behavior under network stress. Telecom service providers deploy these for live network diagnostics prior to commercial 5G-Advanced rollout.
Network analyzers sit at the top of the volume ranking, with protocol analyzers climbing the fastest.
Application:
Cost tier stratification separates capital-intensive automotive validation from lighter smart home certification, with industrial automation occupying the mid-tier.
- Automotive Systems:Vehicle-to-everything, autonomous driving, and infotainment testing against SAE J2945 and UNECE frameworks. OEM captive labs in Stuttgart, Detroit, and Nagoya absorb the steepest equipment investment. Silicon carbide power electronics are forcing thermal cycling protocol recalibration.
- Healthcare Devices:FDA software-as-a-medical-device and EU MDR cybersecurity validation for connected monitors and wearables. Minneapolis and Dublin medical device clusters drive demand for penetration testing integration.
- Industrial Automation:Predictive maintenance sensors and robotic control systems. German Ruhr Valley manufacturing hubs prioritize electromagnetic compatibility for harsh factory floor environments.
- Smart Home:Thread and Matter interoperability certification for lighting, security, and climate control devices. Equipment-as-a-service models dominate here due to startup capital constraints.
Automotive systems command the highest capital deployment per test station, while healthcare devices show the steepest expansion trajectory on cybersecurity compliance.
End User:
Volume concentration follows manufacturing scale, with tier-1 automotive suppliers and contract electronics manufacturers driving the largest procurement batches.
- Manufacturers:OEM captive labs and EMS providers with continuous certification pipelines. Foxconn and Jabil-scale operations in India and Mexico favor multi-site equipment standardization.
- Service Providers:Telecom operators and managed test houses offering outsourced validation. German and US providers bundle chamber time with engineering support for recurring revenue capture.
- System Integrators:Industrial automation and smart building specialists assembling multi-vendor IoT stacks. These buyers prioritize protocol interoperability over deep RF characterization.
- Research Institutions:University and government labs advancing 6G and AI-native testing methodologies. Funding cycles create lumpy procurement patterns distinct from commercial buyers.
Manufacturers occupy the top volume tier, with service providers gaining share fastest on equipment-as-a-service adoption.
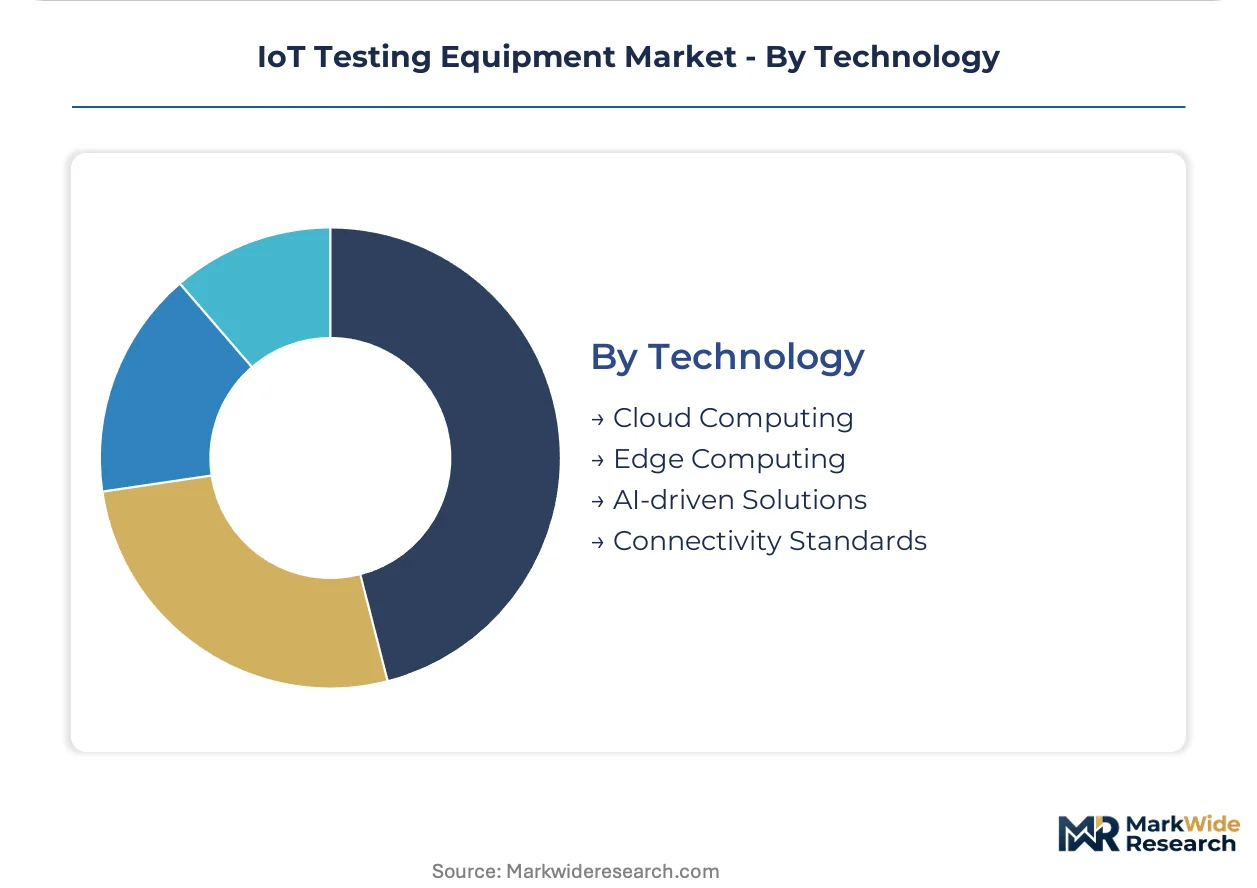
Technology:
Deployment architecture determines capital efficiency, with edge-native solutions compressing physical chamber time versus centralized cloud approaches.
- Connectivity Standards:5G NR, Wi-Fi 7, Bluetooth 5.4, Zigbee, and Thread protocol test suites. Multi-standard firmware complexity is forcing automation software upgrades across certification labs.
- AI-driven Solutions:Machine learning for test pattern optimization and anomaly detection. Automotive tier-1 suppliers pilot these for radiated emissions defect prediction before homologation.
- Edge Computing:Distributed test nodes with embedded spectrum monitoring decentralizing RF validation to production floors. This architecture reduces feedback loops between design iteration and compliance sign-off.
- Cloud Computing:Centralized data aggregation and remote access for global lab networks. Mid-size device makers leverage this for access to high-end equipment without seven-figure capital commitments.
Connectivity standards anchor current volume, with AI-driven solutions expanding most quickly on automation imperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart's automotive certification corridor anchors the highest concentration of millimeter-wave test chambers for vehicle-to-everything validation. Equipment procurement patterns track regulatory mandates across Germany, Japan, the United States, India, and South Korea where automotive OEMs and medical device manufacturers maintain captive labs.
United States
FCC Part 15 emissions enforcement and FDA software-as-a-medical-device guidance drive test-equipment procurement for connected healthcare monitors and automotive modules. Minneapolis medical device clusters absorb specialized penetration-testing integration for FDA submissions. Detroit automotive OEMs validate SAE J2945 vehicle-to-everything links in captive facilities.
Germany
UNECE WP.29 mandates and EU Cyber Resilience Act pre-market requirements expand third-party test lab throughput across automotive and industrial IoT categories. Ruhr Valley manufacturing hubs prioritize electromagnetic compatibility chambers for harsh factory floor environments. Stuttgart certification corridors concentrate millimeter-wave infrastructure for 5G-integrated automotive modules.
Japan
METI industrial IoT promotion and Radio Law electromagnetic limits create dual compliance obligations for multi-region product launches. Nagoya automotive supplier clusters deploy compact field-test sets for live network diagnostics. Tokyo Bay electronics corridors concentrate protocol analyzer demand for Thread and Matter smart home certification.
India
PLI scheme electronics assembly incentives attract test equipment providers to establish calibration facilities near manufacturing clusters. BIS certification requirements for wireless devices expand domestic chamber capacity. Chennai and Noida electronics corridors absorb equipment-as-a-service contracting from capital-constrained hardware startups.
South Korea
5G-Advanced millimeter-wave spectrum activation for industrial backhaul creates demand for over-the-air test chambers. MFDS medical device software guidance converges with cybersecurity validation requirements. Seoul Capital Area electronics clusters deploy AI-driven test pattern optimization for radiated emissions defect prediction.
IoT Testing Equipment Market Competitive Environment
Global majors compete with regional champions across certification workflow depth and protocol specialization breadth. The vendor base stratifies between full-stack instrumentation houses and focused RF specialists. Three archetypes dominate: protocol emulation depth providers, millimeter-wave test bench specialists, and compact field-test set manufacturers. Competitive moves center on equipment-as-a-service contracting and digital twin integration partnerships.
Within the instrumentation tier, Keysight Technologies, ROHDE&SCHWARZ, and Anritsu occupy distinct positioning vectors. Keysight Technologies exemplifies the protocol emulation archetype anchoring North American and European certification workflows. ROHDE&SCHWARZ represents the millimeter-wave specialization pattern for 5G-integrated module validation. Anritsu sits within the field-deployable diagnostic tier servicing provider live network testing requirements.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu |
| ROHDE&SCHWARZ |
| HCL Technologies |
| Capgemini SE |
| Infosys Limited |
| Tektronix |
| RIGOL Technologies |
| Ixia |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between automotive-millimeter-wave systems and smart-home protocol analyzers manifests in divergent pricing architectures and supply chain footprints. Premium-tier equipment serving UNECE WP.29 automotive validation commands captive foundry allocation and extended engineering support contracts, while economy-tier protocol conformance systems draw from standardized component pools with compressed margin structures.
Pricing Analysis
Gallium nitride amplifier cost pass-through from concentrated foundry sources is elevating base unit economics for high-frequency signal generators. Three-tier pricing structure across premium, standard, and economy levels segments by certification complexity, with automotive OEMs absorbing the least price sensitivity and hardware startups in India exhibiting acute cost consciousness. Pricing pressure stems from equipment-as-a-service contracting penetration among capital-constrained Matter-certified device makers. FDA-tier medical device validation systems sustain premium positioning through bundled penetration-testing integration.
Supply Chain Analysis
Millimeter-wave engineering scarcity in Germany, Japan, and the United States concentrates precision RF assembly capacity near Stuttgart, Nagoya, and Minneapolis medical-automotive clusters. Supply chains draw from gallium nitride foundries in Taiwan, precision machining in Switzerland, and FPGA logic from Xilinx-scale suppliers. Single-source vulnerability in 28 GHz test fixture components exposes lead time volatility. Distribution runs through direct OEM captive lab channels and accredited third-party test house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Cyber Resilience Act compounds equipment demand through mandatory pre-market cybersecurity validation, embedding test infrastructure into every hardware release cycle across European markets.
For Market Incumbents: Deepen protocol emulation software moats through Matter and Thread stack specialization to defend against modular test-service entrants. Anchor capacity expansion in Stuttgart and Detroit automotive corridors where UNECE WP.29 mandates concentrate procurement volume. Vertical integration into digital twin pre-certification platforms compresses physical chamber utilization rates for tier-1 automotive suppliers. For New Entrants and Emerging Players: Contract electronics manufacturers in Chennai and Noida represent the most penetrable channel partner type for equipment-as-a-service market entry. Target BIS certification workflow gaps in Indian hardware startup clusters where capital constraints exclude captive lab investment. Bundle calibration services with Thread protocol analyzer deployment to capture recurring revenue from PLI-scheme electronics assembly expansion. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO/IEC 17025 accreditation backlogs extend product release timelines and fragment third-party test house capacity. Five-to-ten-year viability favors millimeter-wave specialization over commoditized protocol conformance. Acquire field-deployable diagnostic specialists with live network testing relationships to telecom service providers. Watch EU notified body headcount expansion as inflection signal for CE marking velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration Partnership | Virtual pre-certification compresses physical chamber time for thermal validation cycles. |
| Equipment-as-a-Service Launch | Subscription contracting captures recurring revenue from capital-constrained hardware startups. |
| Millimeter-Wave Test Bench Expansion | 5G-Advanced spectrum activation drives over-the-air chamber demand in Germany and Japan. |
| Accreditation Facility Acquisition | ISO/IEC 17025 certification capacity alleviates third-party lab throughput bottlenecks. |
| Protocol Analyzer Automation Upgrade | Multi-standard firmware complexity forces Wi-Fi 7, Bluetooth 5.4, Zigbee simultaneous validation. |
Study Parameters
Direct dialogue with test equipment procurement directors at automotive OEMs, certification lab operations managers, RF engineering leads at semiconductor foundries, and smart home device manufacturing executives grounded qualitative assessment. Secondary validation drew from FCC equipment authorization databases, EU notified body registers, FDA software-as-a-medical-device guidance documents, and BIS wireless certification filings. Bottom-up and top-down triangulation cross-referenced equipment shipment data against end-use application demand modeling.
Bottom-up segmentation analysis modeled vector network analyzer, protocol analyzer, wireless sensor, and device simulator revenue pools across automotive systems, healthcare devices, industrial automation, and smart home applications. Top-down macroeconomic anchoring incorporated 5G-Advanced deployment trajectories, EU Cyber Resilience Act implementation timelines, and PLI scheme electronics assembly incentives across the analysis window. CAGR derivation weighted historical certification velocity against regulatory mandate expansion curves and silicon carbide thermal protocol recalibration requirements.
Revisions become necessary when EU notified body capacity expansion stalls, gallium nitride foundry allocation tightens beyond current projections, or equipment-as-a-service contracting penetration accelerates faster than captive lab depreciation cycles anticipate. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Solid-State Battery Fast-Charge Degradation Test Systems Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Battery Resistance Tester Market
Test and Measurement
Electronic Measuring Device Market
Test and Measurement
Global Electromagnetic Flow Meter Market
Test and Measurement
Structure Tester Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
United States Borescope Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market