
 Thermal Energy Flow Metering Solutions Market | 2026-2036
Thermal Energy Flow Metering Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Energy Flow Metering Solutions Market Outlook
Copper sensor housings is consolidating around polymer-composite alternatives that cut raw material costs by half while preserving thermal conductivity. Emerson Electric Co. leverages captive semiconductor fabrication to control digital sensor supply chains. Endress+Hauser Group anchors European district heating retrofit programs with calibrated thermal mass meters. Siemens AG competes on cloud-integrated analytics platforms that layer energy optimization software above hardware sales.
Thermal energy flow metering solutions measure heat transfer in liquid and steam circuits using temperature differential, mass flow rate, and specific heat capacity calculations, typically achieving accuracy within one percent of reading through paired platinum resistance thermometers and precision flow elements. Ultrasonic flow meters dominate district heating applications where non-intrusive installation preserves pipe integrity, while thermal mass flow meters capture industrial process segments requiring direct gas measurement. Smart meters represent the fastest-expanding technology category as utilities mandate remote readability and real-time leakage detection.
The EU F-Gas Regulation and REACH framework restrict refrigerant-based metering technologies, redirecting procurement toward thermal mass and ultrasonic alternatives that eliminate greenhouse gas containment risks. Germany's national metrology institute enforces calibration protocols that create compliance barriers for uncertified imports. Stakeholders must monitor evolving carbon border adjustment mechanisms that will penalize non-EU manufacturers lacking embedded emissions documentation.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-dependent metering architectures while accelerating thermal mass and ultrasonic alternatives across European district heating networks.
Growth Catalysts
- EU F-Gas Regulation:Mandatory phase-down of hydrofluorocarbon refrigerants redirects utility procurement toward thermal mass flow meters that eliminate greenhouse gas containment risks entirely.
- District heating densification:Northern European utilities in Germany, Denmark, and Sweden modernize thermal allocation infrastructure to support building-level heat accounting and demand-response programs.
- Platinum resistance thermometers:Advances in paired temperature sensor precision enable sub-one-percent measurement accuracy that satisfies national metrology institute calibration protocols.
Market Restraints
- Copper price volatility:Traditional sensor housings depend on copper alloys whose raw material costs fluctuate with commodity markets, squeezing margins for standard-grade meter manufacturers.
- Calibration infrastructure concentration:Germany's national metrology institute and a handful of accredited European laboratories control certification capacity, creating bottlenecks for new market entrants.
- Ultrasonic transit-time limitations:Non-intrusive flow measurement struggles with heavily aerated or particulate-laden thermal fluids, restricting deployment in certain industrial steam applications.
Strategic Opportunities
- Smart meter mandates:Utility directives requiring remote readability and real-time leakage detection create replacement demand across legacy mechanical meter installed bases.
- Polymer-composite housings:Material substitution cutting raw material costs while preserving thermal conductivity opens margin expansion for mid-tier suppliers.
- Cloud-integrated analytics:Energy optimization software layered above hardware sales transforms transactional meter procurement into recurring service relationships.
Industry Challenges
- Embedded emissions documentation:Carbon border adjustment mechanisms require supply chain traceability that many non-EU manufacturers lack, threatening market access.
- REACH compliance complexity:Chemical substance registration and restriction protocols create extended certification timelines for new sensor materials and coatings.
- Legacy system integration:Retrofitting thermal mass meters into existing district heating networks demands specialized protocol translation and mechanical adaptation expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Energy Flow Metering Solutions Market |
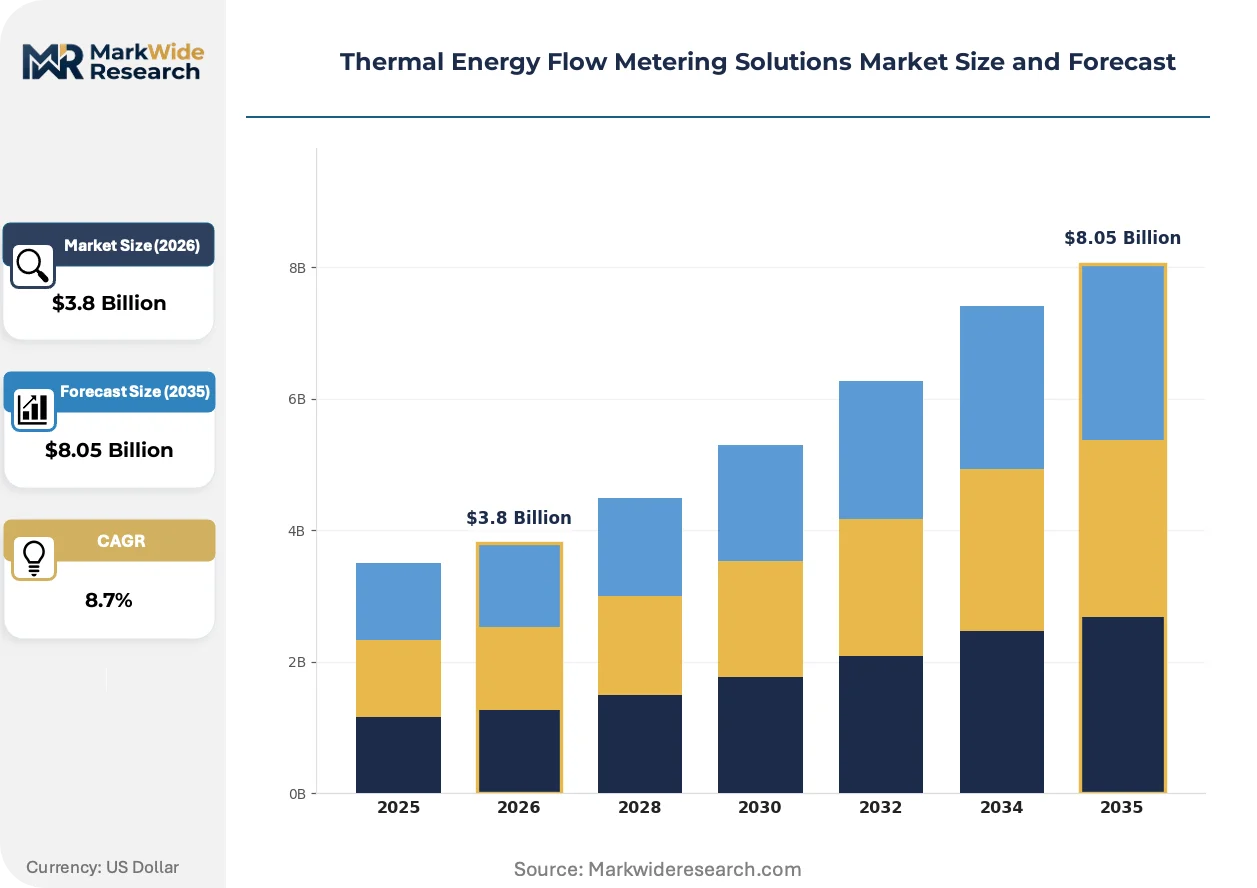
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Flow Meters, Electromagnetic Flow Meters, Vortex Flow Meters, Thermal Mass Flow Meters Application: District Heating, Industrial Processes, HVAC Systems, Renewable Energy Technology: Wireless Monitoring, Smart Meters, Digital Sensors, Cloud Integration End User: Manufacturing, Utilities, Commercial Buildings, Power Generation |
| Companies Covered | Emerson Electric Co., ABB Ltd., Siemens AG, Yokogawa Electric Corporation, Sierra Instruments Inc., Kamstrup Group, Endress+Hauser Group, Landis+Gyr AG, Fluid Components International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Energy Flow Metering Solutions Market Strategic Shifts
Digital sensor architectures and cloud-native analytics platforms are redefining how thermal energy data is captured, transmitted, and monetized across heating networks.
Copper sensor housings is consolidating around polymer-composite alternatives that halve raw material costs while maintaining thermal conductivity specifications. District heating utilities in Scandinavia and Germany are adopting these housings fastest, driven by total-cost-of-ownership procurement criteria. This material transition is compressing price premiums between mid-tier and premium meter tiers.
REACH and the EU F-Gas Regulation jointly restrict refrigerant-based metering technologies across European thermal networks. Industrial consequence includes mandatory replacement schedules and procurement bans on systems containing hydrofluorocarbons. District heating operators respond by accelerating thermal mass and ultrasonic meter deployments ahead of regulatory deadlines.
Buyers are unbundling after-sales service contracts from hardware procurement, treating calibration and maintenance as separately sourced operational expenditures. This pattern disrupts traditional bundled pricing models and favors vendors with certified service networks. Germany and Denmark exhibit this behavior most prominently where utility procurement departments enforce category management disciplines.
Thermal Energy Flow Metering Solutions Market Segmentation
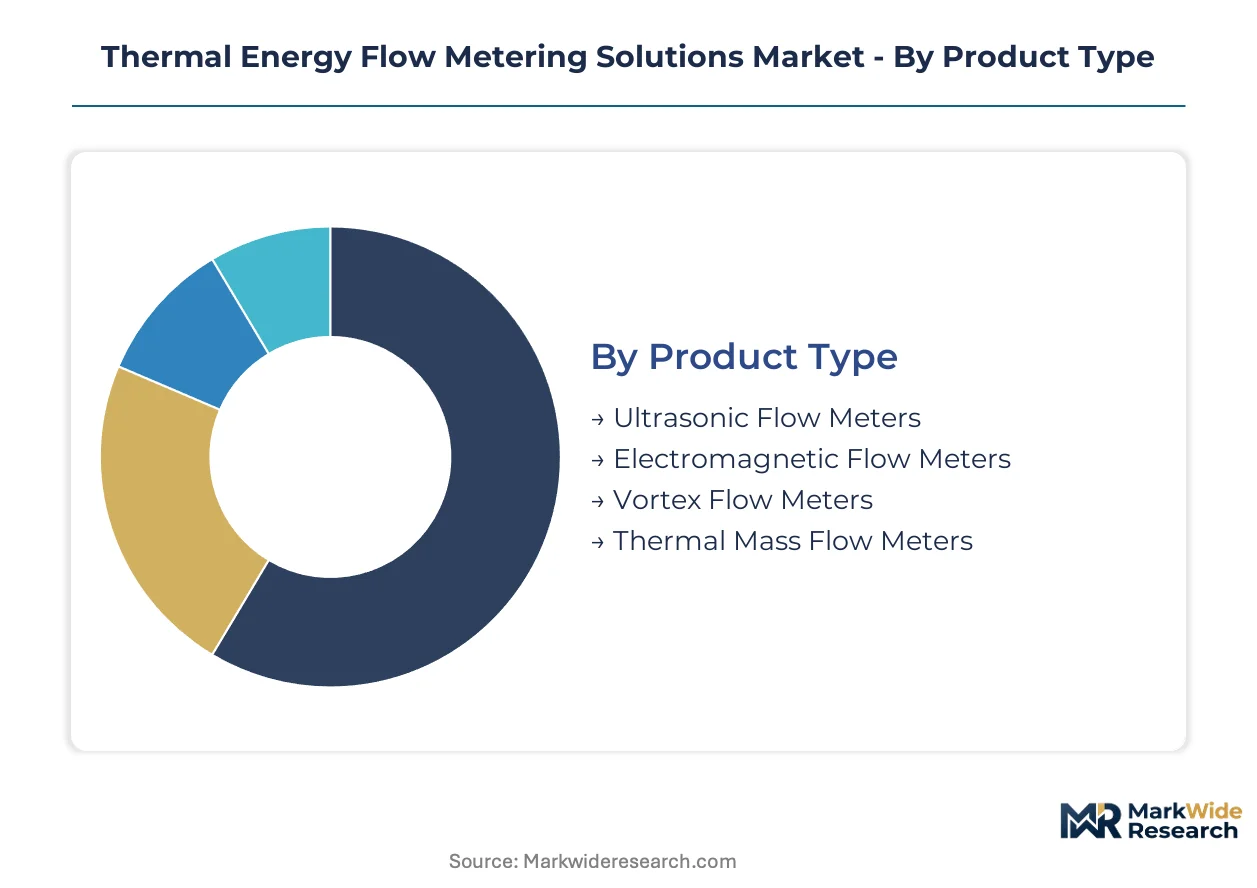
Thermal energy flow metering solutions fragment across four critical dimensions that determine procurement workflows and compliance burdens. Product type dictates metrological certification requirements under national standards. Application context shapes accuracy specifications and installation protocols. Technology tier separates legacy mechanical systems from digitally native architectures. End user category determines volume purchasing power and service contract structures.
Product Type:
Certification intensity varies sharply across meter architectures, with district heating networks demanding MID approval and industrial applications requiring explosion-proof ratings.
- Ultrasonic Flow Meters:Transit-time and Doppler variants measure fluid velocity through acoustic signal propagation without pipe penetration. Demand concentrates in German and Danish district heating retrofits where pipe integrity preservation outweighs higher unit costs. The EU F-Gas Regulation accelerates displacement of refrigerant-dependent alternatives in these networks.
- Thermal Mass Flow Meters:Direct gas measurement through heated element thermal dissipation eliminates moving parts and achieves wide turndown ratios. Industrial process segments in Sweden and Germany adopt these for compressed air and natural gas monitoring where contamination tolerance matters. REACH compliance for sensor coatings extends certification timelines.
- Electromagnetic Flow Meters:Faraday's law induction suits conductive liquid measurement in HVAC and secondary heating circuits.
- Vortex Flow Meters:Von Kármán shedding principles serve steam and high-temperature liquid applications with moderate accuracy requirements.
Leading the category by volume: Ultrasonic Flow Meters. Growing fastest: Thermal Mass Flow Meters.
Application:
End-use context determines whether meters face building-level allocation precision or process-control reliability demands.
- District Heating:Building-level thermal energy accounting requires paired temperature sensors and flow elements achieving sub-one-percent accuracy for billing fairness. Northern European utilities in Germany, Denmark, and Sweden modernize infrastructure to support demand-response programs and leakage detection. Smart meter mandates drive replacement cycles.
- Industrial Processes:Steam, compressed air, and thermal fluid monitoring in manufacturing plants prioritizes uptime reliability over metrological precision. German chemical and automotive sectors deploy redundant meter configurations where process interruption costs exceed hardware premiums.
- HVAC Systems:Commercial building energy management meters balance cost sensitivity against basic accuracy for tenant billing.
- Renewable Energy:Geothermal and solar thermal installations require corrosion-resistant materials for aggressive heat transfer fluids.
Dominant by installed base: District Heating. Expanding most quickly: Industrial Processes.
Technology:
Digital maturity tiers separate procurement into mechanical replacement and connected system investments.
- Smart Meters:Integrated communication modules enable remote readability, tamper detection, and real-time leakage alerts that utility directives increasingly mandate. German and Danish regulators accelerate deployment timelines through technical specifications. Cloud-integrated analytics transform hardware sales into recurring service relationships.
- Digital Sensors:Platinum resistance thermometer pairs with microcontroller-based signal processing achieve calibration stability exceeding analog alternatives. Emerson Electric Co. leverages captive semiconductor fabrication to control supply chains.
- Wireless Monitoring:Battery-powered LoRaWAN and cellular connectivity eliminates wiring costs in retrofit installations.
- Cloud Integration:API-connected meter data platforms layer energy optimization software above measurement hardware.
Highest shipment volume: Smart Meters. Steepest expansion trajectory: Cloud Integration.
End User:
Purchasing power and service expectations diverge across organizational scale and technical sophistication.
- Utilities:District heating operators in Scandinavia and Germany procure through framework agreements specifying decade-long calibration service commitments. Category management disciplines unbundle hardware from maintenance contracts. Total-cost-of-ownership criteria favor polymer-composite housings that halve raw material expenses.
- Manufacturing:Process industries prioritize meter redundancy and protocol compatibility with existing distributed control systems. Endress+Hauser Group anchors retrofit programs with calibrated thermal mass meter portfolios.
- Commercial Buildings:Facility managers seek plug-and-play installations with minimal commissioning overhead.
- Power Generation:Cogeneration and waste-heat recovery plants require high-temperature ratings and ASME compliance documentation.
Largest procurement volume: Utilities. Gaining share fastest: Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Northern Europe concentrate thermal energy flow metering demand through district heating infrastructure modernization. Germany's regulatory framework and Denmark's district heating penetration above sixty percent anchor procurement volumes. Sweden's national metrology protocols create certification gateways that filter market access.
Germany
District heating network densification in Hamburg and Berlin drives building-level thermal allocation upgrades. The EU F-Gas Regulation mandates hydrofluorocarbon phase-downs that redirect utility procurement toward thermal mass alternatives. Bavaria's industrial corridor around Munich deploys calibrated meters for process steam monitoring in automotive manufacturing clusters.
Denmark
Utility directives requiring remote readability and real-time leakage detection accelerate smart meter replacement cycles. The national energy agency enforces technical specifications that compress deployment timelines for connected metering architectures. Copenhagen's district heating operator unbundles after-sales service contracts from hardware procurement, favoring vendors with certified calibration networks.
Sweden
Platinum resistance thermometer precision advances enable sub-one-percent measurement accuracy for billing fairness in Stockholm's thermal networks. REACH compliance protocols for sensor coatings extend certification timelines for new market entrants. Gothenburg's process industries adopt redundant meter configurations where uptime reliability outweighs hardware premiums.
United States
Commercial building energy management retrofits in Chicago and New York Metro balance cost sensitivity against tenant billing accuracy requirements. EPA efficiency standards indirectly shape HVAC system meter specifications through building code adoption. Texas petrochemical corridors deploy thermal mass meters for compressed air monitoring where contamination tolerance matters.
China
Dual carbon goals accelerate district heating infrastructure investments in Beijing-Tianjin-Hebei and Yangtze River Delta urban clusters. MIIT standards for smart city deployments mandate communication-enabled metering for thermal network optimization. Shandong Peninsula manufacturing bases source polymer-composite housings that halve raw material costs while preserving thermal conductivity.
Thermal Energy Flow Metering Solutions Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with district heating utilities favoring established calibration service networks while industrial buyers prioritize protocol compatibility. The vendor base concentrates around three strategic archetypes: semiconductor-integrated sensor fabricators, cloud-analytics platform operators, and polymer-composite housing specialists. Consolidation pressures emerge as utilities unbundle service contracts and enforce total-cost-of-ownership procurement criteria. Geographic expansion through certified calibration partnerships and backward integration into captive sensor supply chains represent dominant competitive vectors.
Among diversified industrial technology conglomerates, Emerson Electric Co., Siemens AG, and Endress+Hauser Group occupy positions that exemplify contrasting strategic postures. Emerson leverages semiconductor fabrication capabilities to control digital sensor supply chains. Siemens competes through cloud-integrated analytics platforms that layer energy optimization software above hardware transactions. Endress+Hauser anchors European district heating retrofit programs with calibrated thermal mass meter portfolios. These three represent archetypes spanning captive component production, software-service hybridization, and precision calibration specialization.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| ABB Ltd. |
| Siemens AG |
| Yokogawa Electric Corporation |
| Sierra Instruments Inc. |
| Kamstrup Group |
| Endress+Hauser Group |
| Landis+Gyr AG |
| Fluid Components International LLC |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between MID-approved meters and uncertified alternatives manifests in pricing spreads exceeding threefold while anchoring supply chain configurations around German and Danish calibration laboratories. Polymer-composite housing adoption compresses these spreads by halving raw material costs for mid-tier suppliers, redirecting procurement toward total-cost-of-ownership criteria that reward embedded service networks over hardware premiums.
Pricing Analysis
Volume shipments concentrate in standard-grade ultrasonic meters where margins compress under polymer-composite substitution, while premium-tier thermal mass meters retain pricing power through captive semiconductor fabrication and calibration exclusivity. Price differentiation hinges on MID certification status and after-sales service bundling, with German utilities unbundling maintenance contracts to intensify hardware price sensitivity. Cost compression in standard tiers accelerates as Chinese polymer-composite suppliers enter European supply chains. Manufacturing segments prioritize uptime reliability over metrological precision, exhibiting lowest price sensitivity; commercial building managers face tenant billing accuracy mandates with constrained capital budgets, driving highest sensitivity to unit cost.
Supply Chain Analysis
Platinum resistance thermometer supply rests on Japanese and German precision component specialists, while polymer-composite housing production concentrates in China and South Korea. Raw material dependencies span copper alloys for legacy sensor housings, semiconductor-grade silicon for digital temperature sensors, and fluoropolymer coatings for REACH-compliant surface treatments. Single-source vulnerability in platinum thin-film deposition equipment creates bottlenecks for new sensor qualification. Distribution runs through authorized calibration service networks that utility procurement frameworks mandate, privileging incumbents with decade-long German and Danish laboratory partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation constructs a cost-of-compliance moat that filters market access toward players with REACH documentation and embedded emissions traceability, elevating certified European incumbents while threatening non-EU manufacturers lacking supply chain transparency infrastructure.
For Market Incumbents: To counter polymer-composite price erosion from Asian suppliers, deepen backward integration into captive semiconductor fabrication for platinum resistance thermometer pairs and expand certified calibration capacity in Scandinavia beyond German laboratory concentration. Cloud-integrated analytics platform development transforms transactional hardware sales into recurring service relationships that resist commodity pricing pressure. For New Entrants and Emerging Players: Launch via wireless monitoring retrofit solutions targeting Denmark's unbundled service procurement frameworks, where battery-powered LoRaWAN connectivity eliminates wiring infrastructure barriers. Industrial process segments in Sweden offer penetrable white-space for thermal mass meters with contamination tolerance specifications that ultrasonic alternatives fail to satisfy. Position through polymer-composite housing cost advantages under total-cost-of-ownership procurement criteria. For Investors and Strategic Acquirers: Re-rating potential sits with calibration-specialist mid-caps given EU carbon border adjustment mechanism implementation accelerating demand for embedded emissions documentation capabilities. Five-to-ten-year viability favors vendors with semiconductor-integrated sensor supply chains and certified European service networks. Monitor German national metrology institute accreditation queue lengths as inflection indicator for certification capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Captive platinum resistance thermometer production insulates Emerson Electric from semiconductor supply volatility. |
| Cloud-Integrated Analytics Platform Launch | Siemens AG layers energy optimization software above hardware to transform transactional meter sales into recurring SaaS relationships. |
| Polymer-Composite Housing Scale-Up | Material substitution halves raw material costs while preserving thermal conductivity for mid-tier suppliers competing on total-cost-of-ownership. |
| Certified Calibration Network Expansion | Endress+Hauser Group anchors European district heating retrofits through decade-long service commitments that procurement frameworks mandate. |
| REACH Compliance Documentation Investment | Embedded emissions traceability systems secure market access under EU carbon border adjustment mechanisms threatening non-EU manufacturers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across district heating utility procurement directors, industrial plant engineers, and national metrology institute calibration specialists. Bottom-up shipment data triangulated against top-down utility capital expenditure disclosures from German, Danish, and Swedish network operators. Secondary validation drew from EU F-Gas Regulation implementation reports, REACH substance registration databases, and MID certification registries.
Granularity-level modeling disaggregated volume and value across product type, application context, technology tier, and end-user category throughout the forecast period. Analytical framework derived CAGRs from utility replacement cycle analysis, regulatory deadline acceleration effects, and smart meter mandate deployment schedules. Industry-specific inputs incorporated platinum price volatility indices, polymer-composite raw material cost curves, and calibration laboratory capacity utilization rates.
The model assumes a particular technology adoption path; alternative pathways for wireless monitoring and cloud-native analytics deployment would alter the outlook if utility technical specifications accelerate faster than projected. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement intensity, REACH compliance timeline extensions, and carbon border adjustment mechanism implementation scope. A small set of triggers—German calibration accreditation queue lengths, Chinese polymer-composite export capacity expansion, and district heating network densification funding allocations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Pickup Truck Market
Others
Europe Military 4D Printing Market
Others
Global on-Demand Laundry Service Market
Others
Saudi Arabia Cat Food Market
Others
IoT Testing Market
Others
Global Application Testing Services Market
Others
Asia-Pacific B2B Legal Services Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
Europe Video Encoder Market
Others
Asia-Pacific Medical Simulation Market
Others
Aircraft Exterior Lighting Market
Others
Toy Packaging Market
Others
Connected Living Room Market
Others
Augmented Reality in BFSI Market
Others
Prunes Market
Others
Asia-Pacific Battery E-Commerce Market