
 Shear Testing Equipment Market | 2026-2036
Shear Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Shear Testing Equipment Market Analytics
Materials testing laboratories are rotating toward automated shear testing systems as construction firms defer capital spending. AMETEK Inc. leverages its electromechanical platform breadth to serve aerospace qualification workflows. Shimadzu Corporation anchors its position in Asia through localized calibration services and university research partnerships. Controls S.p.A. competes on European construction compliance testing with heavy-duty hydraulic frames.
Shear testing equipment measures the shear strength, modulus, and deformation behavior of materials under parallel opposing forces, typically operating at force capacities from kilonewtons to meganewtons depending on specimen geometry and industry standard. These systems serve critical quality assurance functions where bond integrity, composite lamination, or soil stability determines structural safety. Digital shear testers command premium positioning due to integrated data acquisition and compliance traceability, while portable units address field-based construction inspection needs where laboratory access remains impractical. Electromechanical technology leads installed base volume, though hydraulic systems retain dominance in high-force civil engineering applications where pneumatic actuation lacks sufficient load capacity.
FAA airworthiness standards and EASA certification requirements mandate documented shear characterization for adhesive joints in primary aircraft structures, directly shaping equipment specifications and calibration protocols. ISO 14130 and ASTM D732 establish baseline test methods that manufacturers must support for cross-border laboratory accreditation. Stakeholders should monitor evolving battery enclosure bonding standards as electric vehicle platforms expand adhesive-intensive lightweighting strategies beyond traditional mechanical fastening.
Market Dynamics
Automotive electrification is compressing validation cycles for adhesive-intensive battery enclosures, forcing shear testing equipment suppliers to align calibration protocols with evolving OEM bonding specifications.
Growth Catalysts
- FAA Airworthiness Directives:North American aerospace manufacturers must document shear characterization for primary structural adhesives, expanding materials testing laboratory capacity requirements.
- ISO 14130 Harmonization:Cross-border laboratory accreditation standards are driving replacement of legacy mechanical testers with digital systems featuring integrated compliance traceability.
- Electric Vehicle Platform Expansion:German automotive suppliers are validating aluminum-intensive bonding systems for battery enclosures, creating sustained equipment demand from Tier-1 component manufacturers.
Market Restraints
- High-Force Hydraulic Component Concentration:Specialized servo-valve suppliers in Japan control critical subsystems for meganewton-capacity civil engineering frames, creating single-source vulnerability.
- Calibration Service Fragmentation:Regional metrology providers lack ISO 17025 accreditation breadth, forcing buyers to maintain redundant equipment inventories across multiple facilities.
- Electromechanical Force Limitations:Pneumatic actuation systems face technical ceilings around 500 kN, excluding them from geotechnical applications requiring sustained compressive-shear cycling.
Strategic Opportunities
- Battery Enclosure Bonding Standards:Emerging UN ECE regulations for electric vehicle crashworthiness will mandate documented shear performance for thermal runaway containment systems.
- Field-Portable Digital Systems:Construction inspection workflows in remote infrastructure projects are creating demand for battery-powered units with cloud-connected data logging.
- University Research Partnerships:Materials science departments in South Korea and Taiwan are expanding composite characterization programs, opening calibration service and equipment placement channels.
Industry Challenges
- Multiphysics Simulation Integration:Equipment vendors must embed finite element correlation tools that align physical test outputs with digital twin platforms used by aerospace prime contractors.
- Cross-Standard Certification Timelines:Simultaneous FAA, EASA, and CAAC qualification requirements for adhesive testing protocols extend product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shear Testing Equipment Market |
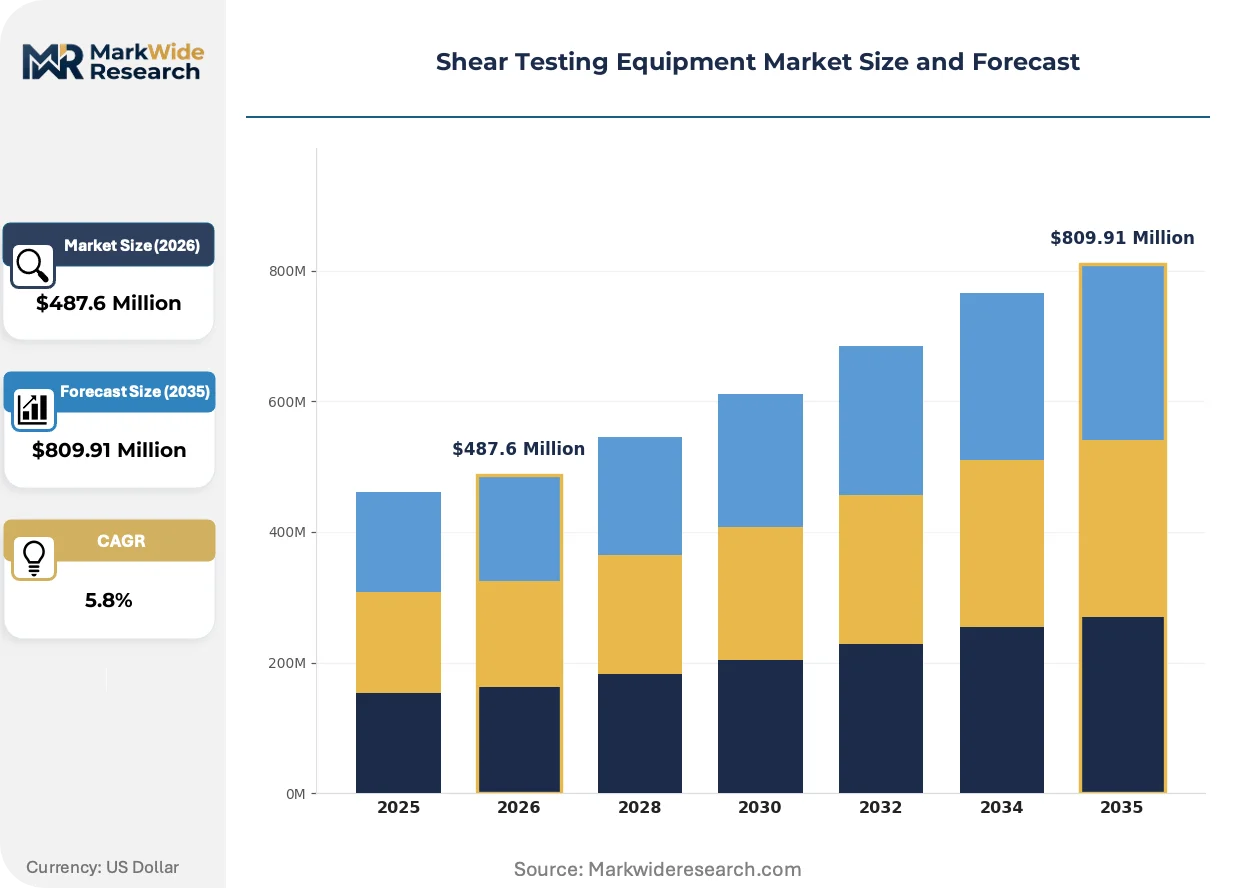
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Shear Testers, Digital Shear Testers, Portable Shear Testers, Automated Shear Testers Technology: Electromechanical, Hydraulic, Pneumatic, Manual End User: Construction, Aerospace, Automotive Components, Materials Testing Labs Application: Material Characterization, Quality Control, Research & Development, Product Development |
| Companies Covered | AMETEK Inc., Controls S.p.A., Shimadzu Corporation, Humboldt Mfg. Co., Prolific Engineers, HOVERLABS, EIE Instruments Pvt. Ltd., Nordson Corporation, Tinius Olsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shear Testing Equipment Market Evolving Landscape
Digital shear testing architectures are compressing the gap between laboratory characterization and production-line quality assurance, enabling real-time bond integrity verification.
Electromechanical test frames with integrated load cell digitization are displacing hydraulic systems in sub-meganewton aerospace applications. Boeing and Airbus tier suppliers are adopting these platforms for adhesive joint qualification workflows. The shift is compressing facility footprint requirements while improving force control resolution for thin-film composite laminates.
EU F-Gas Regulation restrictions on hydraulic fluid formulations are forcing equipment redesigns for European construction compliance testing. Manufacturers must now certify seal compatibility with biodegradable synthetic alternatives. German civil engineering laboratories are responding by accelerating electromechanical platform adoption for soil shear box applications previously dominated by hydraulic actuation.
Construction firms are unbundling after-sales service contracts from equipment purchases, preferring third-party metrology providers for calibration and maintenance. This shift is disrupting traditional vendor revenue models in North American infrastructure markets. Equipment suppliers in the United States are responding with subscription-based software tiers that remote-monitor machine health and predict component replacement intervals.
Shear Testing Equipment Market Segmentation
Shear testing equipment segmentation reflects divergent compliance burdens across regulatory regimes. FAA airworthiness directives in the United States and EASA certification standards in Europe impose distinct calibration protocols that shape equipment specifications and buyer procurement criteria.
Product Type:
FAA documentation requirements for adhesive joint characterization favor systems with integrated data traceability and audit-ready output formats.
- Mechanical Shear Testers:Legacy dial-indicator systems with manual force application and visual readout. Construction firms in Germany retain these units for soil shear box testing where digital compliance documentation remains secondary to field durability.
- Digital Shear Testers:Microprocessor-controlled platforms with automated data acquisition, ISO 17025-compliant calibration certificates, and direct LIMS integration. Aerospace manufacturers in France and the United States specify these systems for adhesive qualification workflows under EASA and FAA protocols.
- Portable Shear Testers:Battery-powered field units for remote infrastructure inspection. Bridge maintenance crews in Italy deploy these where laboratory access is impractical.
- Automated Shear Testers:Robotic specimen handling with unattended batch processing. Automotive Tier-1 suppliers in Germany adopt these for electric vehicle battery enclosure validation cycles.
Digital shear testers handle the majority of throughput; automated shear testers are the fastest mover on share.
Technology:
Cost tier differentiation separates premium electromechanical platforms from economy manual alternatives.
- Electromechanical:Servomotor-driven force application with closed-loop displacement control and sub-micron resolution. Boeing and Airbus tier suppliers in the United States specify these for thin-film composite laminate testing where force precision exceeds hydraulic capability.
- Hydraulic:High-pressure fluid actuation delivering meganewton-range sustained loading. Geotechnical laboratories in Germany rely on these for soil shear box applications requiring compressive-shear cycling beyond electromechanical limits.
- Pneumatic:Compressed air actuation capped near 500 kN force capacity. Small-batch metal fabricators in Italy use these for routine quality control where capital constraints preclude hydraulic investment.
- Manual:Hand-cranked screw mechanisms with mechanical force multiplication. Educational institutions in South Korea maintain these for undergraduate materials science instruction.
Electromechanical systems command the dominant installed base; hydraulic configurations retain irreplaceable positioning in high-force civil engineering.
End User:
Application urgency varies sharply across customer type, with automotive electrification compressing validation timelines fastest.
- Construction:Geotechnical and structural bonding verification for infrastructure projects. German civil engineering laboratories drive demand for heavy-duty hydraulic frames under EU F-Gas Regulation compliance timelines.
- Aerospace:Primary structure adhesive qualification and composite lamination testing. FAA airworthiness directives and EASA certification standards mandate documented shear characterization, expanding materials testing capacity requirements in the United States and France.
- Automotive Components:Battery enclosure bonding validation for electric vehicle platforms. Tier-1 suppliers in Germany validate aluminum-intensive adhesive systems under emerging UN ECE crashworthiness regulations.
- Materials Testing Labs:Third-party certification and cross-industry contract testing. ISO 14130 harmonization drives replacement of legacy mechanical testers with digital systems featuring integrated compliance traceability.
Materials testing labs process the highest equipment volume; automotive components end users are expanding most quickly as electric vehicle platforms proliferate.
Application:
Margin structure concentrates in research and development segments where customization commands premium pricing.
- Material Characterization:Determination of shear strength, modulus, and deformation behavior per standardized test methods. University research partnerships in Taiwan and South Korea expand composite characterization programs, opening equipment placement channels.
- Quality Control:Production-line bond integrity verification with pass-fail automation. Aerospace manufacturers in the United States deploy these systems for adhesive joint qualification workflows.
- Research & Development:Novel material formulation and bonding process development. Battery enclosure bonding standards under UN ECE regulations mandate documented shear performance for thermal runaway containment systems.
- Product Development:Prototype validation and design iteration support. Automotive OEMs in Germany use these capabilities for electric vehicle platform lightweighting strategies.
Quality control absorbs the largest equipment deployment; research and development applications show the steepest expansion trajectory as multiphysics simulation integration requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers supply shear testing systems to aerospace qualification centers in France and the United States, establishing a transatlantic trade corridor anchored by automotive and aviation demand clusters.
United States
FAA airworthiness directives mandate documented shear characterization for primary aircraft structural adhesives, expanding materials testing laboratory capacity in Wichita and Seattle aerospace corridors. Boeing tier suppliers in Everett adopt electromechanical platforms for composite laminate qualification workflows. The Department of Transportation infrastructure bill sustains geotechnical testing demand for bridge and highway projects.
Germany
Automotive electrification compresses validation cycles for aluminum-intensive battery enclosure bonding systems at Tier-1 suppliers. KBA vehicle type approval requirements shape equipment specifications for crashworthiness documentation. Stuttgart and Munich engineering clusters host concentrated materials characterization programs serving BMW and Mercedes-Benz electric platform development.
France
EASA certification standards drive replacement of legacy mechanical testers with digital systems featuring integrated compliance traceability. Airbus supply chain qualification requirements in Toulouse expand adhesive joint testing capacity. The country's national aerospace regulator maintains stringent calibration protocols for primary structure bonding verification.
China
Domestic electric vehicle manufacturers accelerate battery enclosure bonding validation under evolving GB standards for thermal runaway containment. MIIT industrial policy supports localization of materials testing equipment production. Shanghai and Shenzhen automotive clusters import European calibration protocols while building indigenous certification capabilities.
Japan
METI industrial standards harmonization enables Japanese shear testing equipment exports to Southeast Asian automotive assembly operations. Specialized servo-valve suppliers in Nagoya control critical subsystems for meganewton-capacity hydraulic frames. Composite characterization programs at Tokyo and Osaka universities sustain research equipment demand.
Shear Testing Equipment Market Competitive Landscape
Listed leaders compete with private specialists across calibration service breadth and electromechanical platform integration. The vendor base organizes around three tiers: diversified instrumentation conglomerates with aerospace qualification workflows, construction-focused hydraulic frame specialists, and regional calibration service providers. Consolidation pressure concentrates in the mid-market as digital compliance requirements displace legacy mechanical testers. Strategic moves center on university research partnerships for equipment placement channels and cloud-connected service tier subscriptions.
Within the diversified instrumentation tier, AMETEK Inc. and Shimadzu Corporation exemplify scale-driven platform breadth spanning electromechanical and digital architectures. Controls S.p.A. occupies a position among European construction compliance specialists with heavy-duty hydraulic frame capabilities. These three entities anchor competitive positioning across distinct regulatory regime requirements.
| Leading Market Players |
|---|
| AMETEK Inc. |
| Controls S.p.A. |
| Shimadzu Corporation |
| Humboldt Mfg. Co. |
| Prolific Engineers |
| HOVERLABS |
| EIE Instruments Pvt. Ltd. |
| Nordson Corporation |
| Tinius Olsen |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for Japanese servo-valve subsystems concentrate pricing power among Nagoya-based suppliers of meganewton-capacity hydraulic frames, while German automotive OEMs compress procurement cycles for battery enclosure validation equipment. This inventory tension forces buyers to absorb premium positioning for ISO 17025-compliant digital architectures or accept extended fulfillment horizons for heavy-duty civil engineering platforms.
Pricing Analysis
Next-generation electromechanical platforms command 40-60% premiums over legacy hydraulic configurations, while prior-generation manual testers face accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels stratifies by calibration certification grade and after-sales bundling intensity. Cost compression in mid-range digital systems is intensifying because construction firms unbundle service contracts and source third-party metrology independently. Materials testing laboratories exhibit highest price sensitivity due to redundant equipment inventory requirements across fragmented regional calibration providers, whereas aerospace manufacturers demonstrate lowest sensitivity given FAA airworthiness directive compliance mandates.
Supply Chain Analysis
Strategic stockpiling of servo-valve inventories dominates Japanese and German supply strategies, while just-in-time preferences prevail among North American electromechanical platform assemblers. Component manufacturing concentrates in Japan, Germany, and the United States for precision load cells and servo-hydraulic subsystems. Critical inputs include specialized servo-valves, high-resolution load cells, and aerospace-grade calibration standards. Single-source vulnerability runs through Nagoya-based servo-valve suppliers controlling meganewton-range hydraulic actuation. Distribution runs through authorized dealer networks serving materials testing laboratories, with direct OEM relationships dominating aerospace qualification workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FAA airworthiness directives and EASA certification standards creates durable defensive moats for incumbent calibration service providers and equipment manufacturers with established accreditation breadth.
For Market Incumbents: Secure ISO 17025 accreditation expansion across emerging battery enclosure bonding standards before UN ECE regulations crystallize, insulating against specialized European calibration entrants. Deepen backward integration into servo-valve subsystem production to mitigate Nagoya supplier concentration risk. Prioritize cloud-connected service tier subscriptions that remote-monitor machine health, countering construction firm preferences for third-party metrology unbundling. For New Entrants and Emerging Players: Accelerated FAA-EASA dual certification pathways offer fastest market access for electromechanical platform specialists targeting sub-meganewton aerospace applications. White-space concentrates in field-portable digital systems for remote infrastructure inspection, where Italian bridge maintenance crews and North American DOT field offices lack battery-powered cloud-connected alternatives. Target university research partnerships in South Korea and Taiwan as equipment placement channels, leveraging government-funded composite characterization program expansion. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because evolving airworthiness and crashworthiness standards continuously refresh equipment replacement cycles and calibration service demand. Acquisition targets should emphasize calibration service providers with ISO 17025 breadth across multiple regulatory jurisdictions, not pure equipment manufacturers facing hardware commoditization. Watch for UN ECE battery enclosure bonding standard finalization as inflection signal for accelerated automotive validation equipment procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | ISO 17025 accreditation breadth across FAA, EASA, and CAAC protocols locks in aerospace qualification workflows. |
| Cloud-Connected Service Tier Launch | Remote machine health monitoring counters construction firm unbundling of traditional after-sales contracts. |
| University Research Partnership Program | Equipment placement channels in South Korea and Taiwan composite characterization programs build future installed base. |
| Servo-Valve Subsystem Integration | In-house production of critical hydraulic components mitigates Nagoya supplier concentration vulnerability. |
| Field-Portable Product Line Development | Battery-powered units with cloud logging address Italian infrastructure inspection and remote DOT project demand. |
Research Methodology
Desk research of SEC equipment manufacturer filings, FAA airworthiness directive documentation, and EASA certification standards preceded structured interviews with materials testing laboratory directors, aerospace Tier-1 supplier quality engineers, automotive OEM bonding validation specialists, and regional calibration service providers. Secondary validation drew from ISO 14130 and ASTM D732 standard documentation, customs trade data for shear testing equipment imports, and university research partnership announcements. Bottom-up equipment shipment estimates triangulated against top-down aerospace and automotive capital expenditure disclosures.
Variance decomposition across product type, technology architecture, end-user industry, and application urgency shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include force capacity tier, automation level, compliance certification grade, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, electric vehicle platform proliferation timelines, and infrastructure spending authorization trajectories. Industry-specific forecast inputs encompass FAA airworthiness directive implementation schedules and UN ECE battery enclosure bonding standard development status.
Decision-makers should treat outputs as directional under assumptions of continued FAA-EASA regulatory harmonization and sustained automotive electrification capital allocation; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding calibration service accreditation expansion and electromechanical platform displacement rates. Revision becomes warranted when UN ECE battery enclosure standard finalization timelines or Japanese servo-valve supply disruptions cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Astrology Market
Others
Education and Learning Analytics Market
Others
Over the Top Devices and Services Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Cryogenic Storage Tanks Market
Others
Automatic Barriers and Bollards Market
Others
Durian Fruit Market
Others
Global Military Apparel Market
Others
APAC Machine Vision Systems Market
Others
Global Virtual Keyboard Market
Others
Gesture Recognition for Smart TV Market
Others
Sound Reinforcement Market
Others
Europe Indoor LBS Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Global Solder Balls Market
Others
Synthetic Leather Market