
 Global IoT Managed Services Market | 2026-2036
Global IoT Managed Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Managed Services Market Outlook
The EU AI Act is consolidating the cost-of-entry calculus for IoT managed services vendors serving European industrial clients. IBM sustains deep vertical expertise in predictive maintenance platforms for asset-intensive sectors. Tata Consultancy Services anchors its competitive stance through captive delivery centers and long-term manufacturing client relationships. Wipro differentiates via integrated OT-IT security operations tailored to hybrid cloud IoT deployments.
IoT managed services encompass the remote monitoring, administration, and optimization of connected device fleets, sensor networks, and edge infrastructure through subscription-based operational contracts typically governed by SLAs covering latency thresholds, uptime guarantees, and incident response windows. The primary commercial purpose is to transfer operational complexity and cybersecurity liability from capital-constrained enterprises to specialized service providers. Security Management commands premium pricing due to escalating firmware vulnerability exposure and ransomware targeting of edge devices. Hybrid Cloud deployment models are expanding fastest as manufacturers retain sensitive process data on-premises while bursting analytics workloads to public infrastructure. Data Analytics represents an emerging margin pool where real-time stream processing and predictive model deployment create recurring revenue stickiness.
FDA oversight of connected medical devices, FCC spectrum allocation rules for unlicensed IoT bands, and ETSI cybersecurity standards for consumer IoT collectively shape product certification requirements and cross-border service eligibility. Japan's METI has introduced operational technology security guidelines that mandate third-party audits for critical infrastructure IoT, directly stimulating managed security service procurement. Stakeholders must evaluate whether their service architectures can absorb divergent regional compliance layers without fragmenting operational scale.
Market Dynamics
The EU AI Act is compressing vendor economics by forcing compliance infrastructure investments that only scaled providers can amortize across multi-tenant platforms, while manufacturing buyers simultaneously demand edge-native security stacks.
Growth Catalysts
- Industrie 4.0 mandates:German automotive suppliers are outsourcing entire connected-factory operations to managed service providers capable of integrating OT-IT security operations under unified SLAs.
- ETSI cybersecurity standards:Certification requirements for consumer IoT devices in European markets are pushing OEMs toward third-party firmware lifecycle management rather than in-house security teams.
- Edge AI inference:Real-time predictive maintenance models deployed at manufacturing sites require specialized providers to manage heterogeneous silicon environments spanning NVIDIA Jetson to ARM Cortex clusters.
Market Restraints
- Semiconductor supply concentration:Edge gateway SoC availability remains constrained by Taiwan-based foundry capacity allocation, creating deployment backlogs for managed service rollouts.
- GDPR data residency friction:Cross-border telemetry streaming from German industrial sites to Indian delivery centers requires architecturally complex sovereign cloud partitioning that elevates operational overhead.
- Cellular module cost volatility:NB-IoT and Cat-M1 radio component pricing fluctuates with lithium and rare earth processing constraints, compressing hardware-inclusive contract margins.
Strategic Opportunities
- Japan METI security guidelines:Mandatory third-party audits for critical infrastructure IoT are creating immediate procurement windows for managed security service providers with OT-specific certifications.
- Digital twin convergence:Physics-based simulation platforms merged with live sensor streams enable new outcome-based pricing models for asset uptime guarantees in process manufacturing.
- Healthcare IoT expansion:FDA pre-certification pathways for connected medical devices allow managed service providers to assume post-market surveillance liability from device manufacturers.
Industry Challenges
- OT security talent scarcity:Industrial control system expertise combined with cloud-native DevSecOps skills commands compensation premiums that strain service provider margin structures.
- Multi-standard certification timelines:Simultaneous compliance with IEC 62443, ISO 27001, and sector-specific frameworks extends sales-to-revenue cycles by 6-12 months in regulated verticals.
- Legacy protocol integration:Brownfield manufacturing environments running Modbus and PROFIBUS require custom gateway development that resists standardization and economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Managed Services Market |
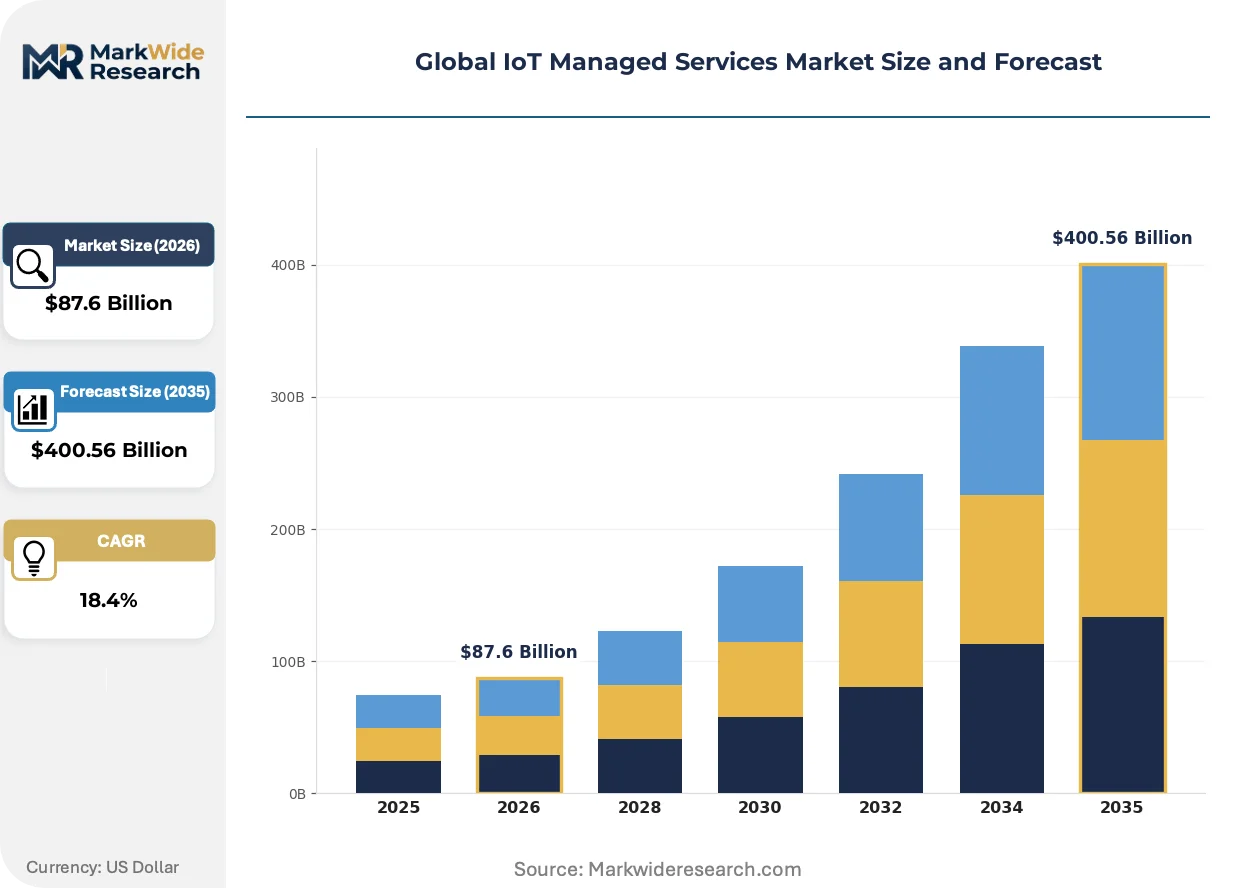
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, Device Management, Security Management, Data Analytics Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Manufacturing, Healthcare, Retail, Transportation Application: Smart Homes, Industrial Automation, Asset Tracking, Wearable Technology |
| Companies Covered | Cognizant, EPAM Systems, IBM, HCLTech, Tata Consultancy Services, Accenture, Wipro, Capgemini Engineering, Infosys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Managed Services Market Strategic Shifts
Managed IoT platforms are pivoting from device connectivity toward data monetization infrastructure, with security operations and edge analytics emerging as the primary vectors of competitive differentiation.
Confidential computing architectures using hardware-based trusted execution environments are consolidating security postures for multi-tenant industrial IoT deployments. German automotive manufacturers are mandating these capabilities for supplier-facing data exchanges. The technology is consolidating previously fragmented encryption key management into unified hardware roots of trust administered by managed service providers.
The EU AI Act's risk classification framework for AI-enabled IoT systems is forcing operational restructuring across European industrial deployments. High-risk applications now require documented human oversight mechanisms and algorithmic audit trails that managed service providers must embed in their delivery stacks. Medical device and critical infrastructure segments are absorbing the steepest compliance cost increases.
Consumption-based pricing models tied to actual data throughput and compute utilization are displacing per-device subscription structures in hybrid cloud IoT deployments. Manufacturing buyers in Germany and Japan are negotiating outcome-based contracts linking fees to measurable productivity gains rather than connected asset counts. This shift compresses provider working capital cycles while demanding more sophisticated customer success functions.
Global IoT Managed Services Market Segmentation
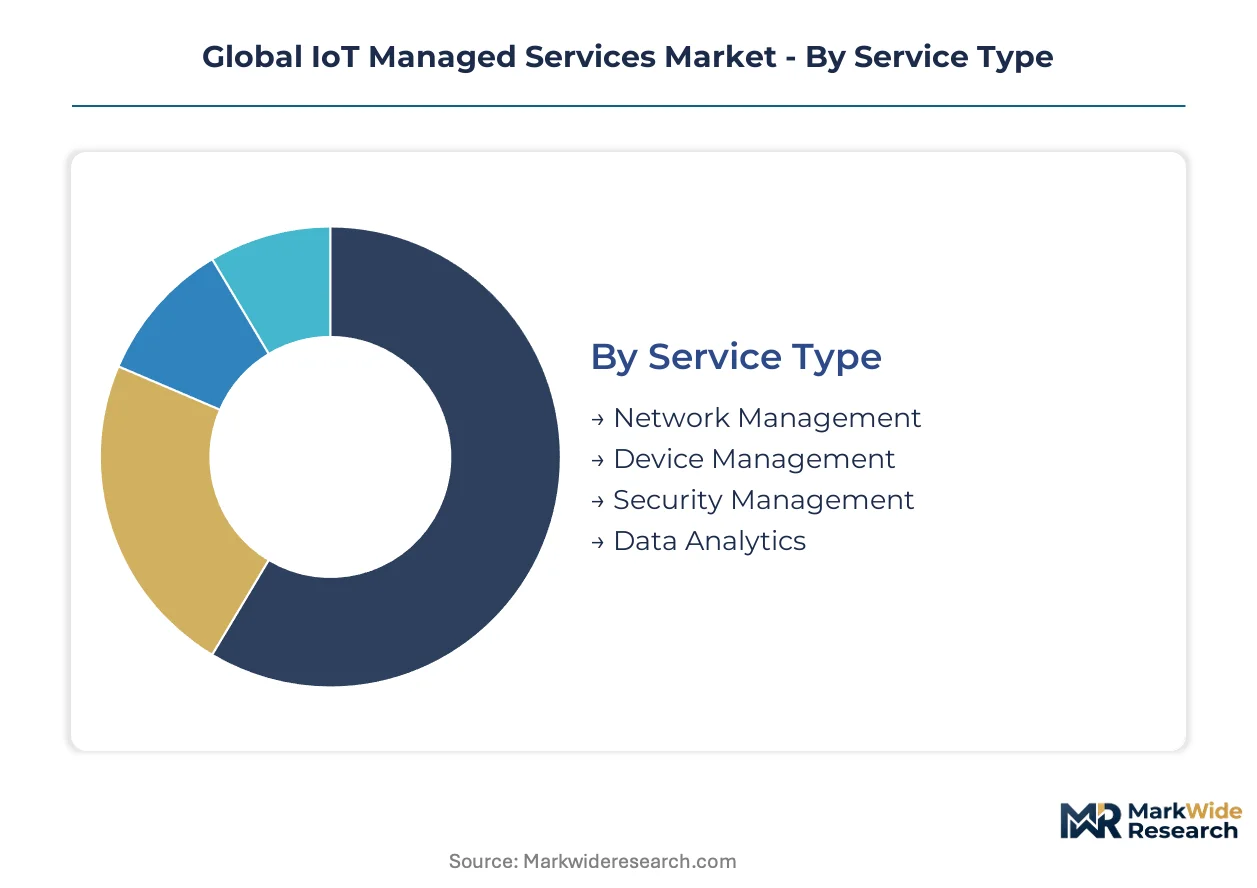
Segmentation in IoT managed services reveals divergent margin structures and capability requirements across service layers and deployment contexts. Buyers prioritize different combinations of latency guarantees, security postures, and data sovereignty controls depending on operational criticality.
Service Type:
Volume-driven segments compete on scale economies while premium tiers extract value from specialized expertise and liability transfer.
- Security Management:Firmware vulnerability monitoring, edge device hardening, and ransomware response protocols delivered through 24/7 SOC operations. German automotive suppliers and Japanese critical infrastructure operators now mandate third-party security administration under METI guidelines and EU AI Act risk classifications. Premium pricing reflects scarce OT-security talent and escalating liability exposure.
- Data Analytics:Real-time stream processing, predictive model deployment, and physics-based digital twin convergence enabling outcome-based uptime guarantees. Manufacturing enterprises in Germany negotiate contracts tied to measurable productivity gains rather than connected asset counts. This segment commands recurring revenue stickiness through embedded algorithmic IP.
- Network Management:Connectivity orchestration across cellular, LPWAN, and private 5G infrastructures with SLA-backed latency thresholds.
- Device Management:Remote provisioning, firmware lifecycle administration, and fleet health monitoring at scale.
Mature deployment sits with Network Management. Newer deployment is concentrated in Data Analytics.
Deployment Model:
Customer risk tolerance for data residency and control determines architecture selection, with hybrid configurations capturing manufacturing complexity.
- Hybrid Cloud:Sensitive process data retained on-premises while analytics workloads burst to public infrastructure. German Industrie 4.0 implementations require this architecture to satisfy GDPR data residency friction without sacrificing compute elasticity. The model demands sophisticated sovereign cloud partitioning that elevates provider operational overhead.
- Private Cloud:Dedicated tenant environments delivering isolation for regulated verticals including FDA-scrutinized connected medical devices and FCC-governed critical infrastructure.
- Public Cloud:Multi-tenant platforms amortizing infrastructure costs across customer bases for non-sensitive IoT deployments.
- On-Premises:Fully air-gapped installations serving defense, nuclear, and classified industrial applications with zero external connectivity.
Volume concentration favors Public Cloud. Margin expansion is steepest in Hybrid Cloud.
End User:
Vertical specialization requirements separate commodity connectivity providers from embedded operational partners.
- Manufacturing:Connected-factory operations integrating OT-IT security under unified SLAs, predictive maintenance platforms, and heterogeneous silicon environment management spanning NVIDIA Jetson to ARM Cortex clusters. German automotive supplier digitization and Industrie 4.0 mandates are pulling managed service contracts at scale.
- Healthcare:FDA pre-certification pathways for connected medical devices allow providers to assume post-market surveillance liability. Real-time patient monitoring and asset location tracking demand sub-second latency guarantees and HIPAA-aligned data governance.
- Retail:Inventory visibility, cold chain monitoring, and customer experience optimization through connected store infrastructure.
- Transportation:Fleet telematics, predictive maintenance for commercial vehicles, and autonomous system support services.
Procurement sophistication is highest in Manufacturing. Regulatory complexity peaks in Healthcare.
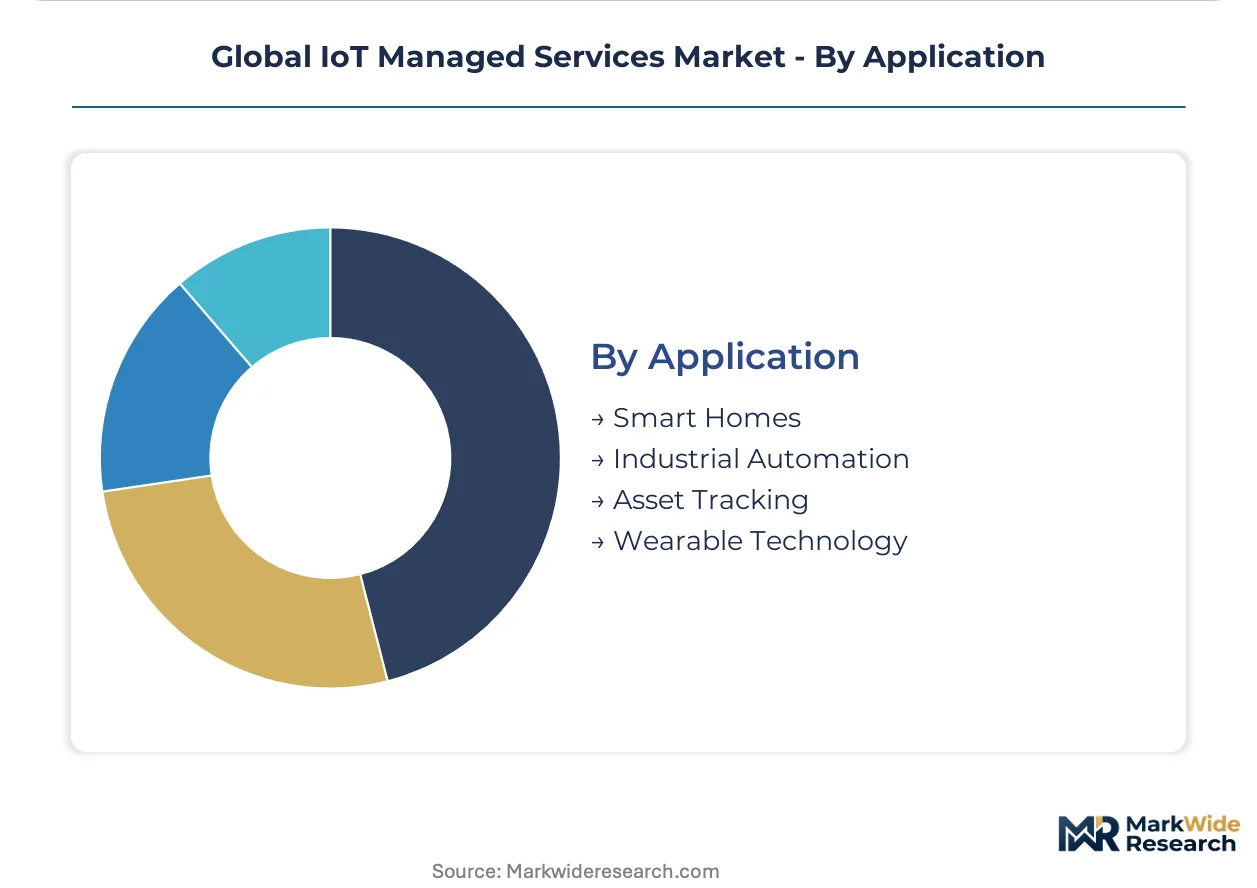
Application:
Use case maturity correlates with data monetization potential and integration depth into customer revenue operations.
- Industrial Automation:Connected production lines, robotic system orchestration, and quality inference at the edge. Brownfield environments running Modbus and PROFIBUS require custom gateway development that resists standardization. Physics-based simulation merged with live sensor streams enables new outcome-based pricing models.
- Asset Tracking:Real-time location systems for high-value equipment, supply chain visibility, and geofenced operational compliance.
- Smart Homes:Consumer IoT device administration, ETSI cybersecurity standard compliance, and OEM firmware lifecycle management.
- Wearable Technology:Health monitoring device connectivity, biometric data pipeline management, and wellness platform integration.
Revenue per connected unit is highest in Industrial Automation. Device count scale favors Smart Homes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing enterprises in Germany currently generate the steepest demand acceleration for outsourced connected-factory operations. Industrial digitization mandates across multiple jurisdictions are redistributing procurement volumes toward specialized managed service providers.
Germany
Industrie 4.0 adoption and automotive supplier digitization are pulling managed service contracts at scale. The EU AI Act imposes risk classification frameworks requiring documented human oversight mechanisms for high-risk AI-enabled IoT systems. Stuttgart and Munich industrial clusters host extensive predictive maintenance platform deployments under unified OT-IT security SLAs.
United States
Asset-intensive sectors including oil & gas and utilities are outsourcing edge infrastructure administration to reduce cybersecurity liability exposure. FDA oversight of connected medical devices shapes certification requirements for healthcare IoT managed services. Houston energy corridor and Gulf Coast manufacturing hubs are negotiating outcome-based contracts tied to measurable uptime guarantees.
Japan
Critical infrastructure operators face mandatory third-party audits under METI operational technology security guidelines. These mandates directly stimulate managed security service procurement for industrial control system environments. Nagoya manufacturing belt and Osaka industrial zones are integrating heterogeneous silicon environments spanning NVIDIA Jetson to ARM Cortex clusters.
India
Global systems integrators operate captive delivery centers serving European and North American manufacturing clients. GDPR data residency friction requires architecturally complex sovereign cloud partitioning for German industrial telemetry streaming. Bangalore and Hyderabad technology corridors host specialized OT-security talent pools commanding compensation premiums.
United Kingdom
Financial services and insurance sectors are adopting managed IoT platforms for asset tracking and operational risk monitoring. ETSI cybersecurity standards for consumer IoT devices push OEMs toward third-party firmware lifecycle management. London fintech cluster and Manchester industrial technology hubs are deploying hybrid cloud architectures retaining sensitive process data on-premises.
Global IoT Managed Services Market Competitive Environment
United States-based technology conglomerates anchor one tier; Indian systems integrators hold substantial scale positions through captive delivery infrastructure. The vendor base concentrates around diversified IT services firms with vertical-specific IoT practices rather than pure-play connectivity providers. Three archetypes dominate: full-stack integrators with OT-security certifications, cloud-native platforms with edge analytics specialization, and manufacturing-focused consultancies with physics-based digital twin capabilities. Competitive moves center on strategic partnerships with semiconductor vendors and portfolio diversification into outcome-based pricing models.
Within the full-stack integrator tier, IBM and Accenture exemplify archetypes combining predictive maintenance platforms with unified OT-IT security operations. Tata Consultancy Services anchors the scale-driven segment through long-term manufacturing client relationships and extensive captive delivery center networks. These three entities represent positioning patterns visible across the competitive set: deep vertical expertise in asset-intensive sectors, integrated security operations tailored to hybrid cloud deployments, and sustained investment in sovereign cloud partitioning capabilities for GDPR-compliant European service delivery.
| Leading Market Players |
|---|
| Cognizant |
| EPAM Systems |
| IBM |
| HCLTech |
| Tata Consultancy Services |
| Accenture |
| Wipro |
| Capgemini Engineering |
| Infosys |
| Others |
Value Chain & Pricing Dynamics
Edge-native security stack standardization across German automotive supplier networks simultaneously compresses deployment cost curves and consolidates procurement power among scaled managed service providers capable of amortizing compliance infrastructure across multi-tenant platforms.
Pricing Analysis
Volume concentration in public cloud device management sits at the economy tier while margin expansion runs through hybrid cloud deployments with sovereign partitioning. Price differentiation hinges on OT-security certification grade and GDPR-compliant data residency architecture. Pricing pressure stems from cellular module cost volatility tied to lithium and rare earth processing constraints. Small and mid-sized manufacturers exhibit acute price sensitivity; German automotive OEMs prioritize liability transfer over unit economics.
Supply Chain Analysis
Reverse-logistics flows for edge gateway refurbishment and firmware lifecycle management create secondary value capture opportunities in extended hardware service contracts. Component manufacturing concentrates in Taiwan for edge SoCs, South Korea for memory modules, and China for cellular radio assemblies. Supply chains draw from constrained foundry capacity allocation, NAND flash memory, and NB-IoT/Cat-M1 modules. Single-source vulnerability around Taiwan-based semiconductor fabrication poses structural risk. Distribution runs through systems integrator captive centers in India and direct enterprise sales forces in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compliance-scale advantages as the EU AI Act forces compliance infrastructure investments that fragment operational economics for sub-scale competitors.
For Market Incumbents: Deploy sovereign cloud partitioning capabilities as the primary defensive lever to capture GDPR-bound German manufacturing demand. Acquire OT-security certification specialists to address talent scarcity compressing margin structures. Counter emerging cloud-native platform entrants by bundling predictive maintenance IP with unified OT-IT security SLAs.
For New Entrants and Emerging Players: Direct-to-enterprise digital sales channels targeting mid-sized Japanese manufacturers offer the most penetrable entry vector. Japan METI security guideline mandates create immediate procurement windows for providers with industrial control system certifications. White-space exists in outcome-based pricing models for asset uptime guarantees in process manufacturing verticals.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by full-stack integrators seeking OT-security talent and vertical-specific digital twin capabilities. Five-to-ten year viability favors providers with embedded algorithmic IP and long-term manufacturing client relationships. Monitor EU AI Act enforcement intensity and German Industrie 4.0 procurement acceleration as inflection indicators for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| OT-Security Certification Investment | ISO 27001 and IEC 62443 credentials unlock regulated vertical procurement in German automotive and Japanese critical infrastructure. |
| Sovereign Cloud Partitioning Deployment | GDPR-compliant data residency architecture captures hybrid cloud demand from Industrie 4.0 implementations. |
| Edge AI Inference Platform Integration | NVIDIA Jetson and ARM Cortex cluster management capabilities enable real-time predictive maintenance service tiers. |
| Outcome-Based Pricing Model Development | Contracts tied to measurable productivity gains displace per-device subscriptions in German manufacturing procurement. |
| Confidential Computing Architecture Adoption | Hardware-based trusted execution environments satisfy German automotive supplier mandates for supplier-facing data exchanges. |
Study Parameters
Independent corroboration across managed service provider delivery heads, manufacturing CIOs, and semiconductor supply chain managers underwrites the qualitative findings. Primary interviews with OT-security operations directors, predictive maintenance platform engineers, and German automotive supplier procurement leads combined with secondary validation from SEC filings of listed systems integrators, hyperscaler IoT platform capex disclosures, and ETSI cybersecurity standard documentation. Bottom-up service revenue modeling and top-down market sizing triangulate volume estimates.
Rate-of-change decomposition across deployment model adoption curves, vertical penetration patterns, and compliance cost absorption timelines structures the analytical framework. Segmentation dimensions span service type, deployment architecture, end-user vertical, and application use case with regional regulatory cluster overlays. CAGRs derive from fitted growth curves calibrated to disclosed contract values and procurement pipeline indicators. Forecast inputs incorporate EU AI Act implementation pace and Industrie 4.0 mandate execution timelines.
The model holds under stable regulatory enforcement intensity and sustained German manufacturing digitization investment; deviation in semiconductor supply availability or METI guideline expansion scope would shift trajectory. Practitioners should monitor Taiwan foundry capacity allocation announcements and EU AI Act high-risk system designation updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Non-Terrestrial IoT Gateway Hardware and Software Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Marine Internet of Things Market
Internet of Things (IoT)
Global IoT in Aerospace and Defense Market
Internet of Things (IoT)
Smart Pool Systems Market
Internet of Things (IoT)
Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
Qatar Internet of Things (IoT) Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
IoT Technology Market
Internet of Things (IoT)
IoT Microcontroller Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Healthcare M2M Market
Internet of Things (IoT)
Global Internet of Things (IoT) Defence Market
Internet of Things (IoT)
IoT Services Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market