
 Internet of Things in Energy Market | 2026-2036
Internet of Things in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things in Energy Market Foresight
Utility end-user demand is shifting toward distributed intelligence architectures as power providers replace centralized SCADA with edge-enabled monitoring. Siemens leverages deep automation heritage to anchor European grid modernization contracts. Schneider Electric sustains integrated hardware-software positioning across predictive maintenance deployments. Cisco competes through secure networking layers that bridge operational technology and enterprise IT environments.
Internet of Things in Energy encompasses networked sensor arrays, communication modules, and analytics platforms that collect, transmit, and process operational data from generation through consumption. These systems typically operate across sub-GHz to cellular spectrum bands with latency requirements under 100 milliseconds for grid stabilization commands, enabling real-time load balancing and asset health assessment. IoT Platforms capture disproportionate margin pools as recurring software revenue outpaces hardware commoditization in Smart Meters. Demand Response applications exhibit the fastest structural expansion as intermittent renewable penetration forces dynamic pricing mechanisms. Sensors remain the volume anchor across Grid Monitoring installations where thermal, vibration, and current transducers proliferate on transformers and switchgear.
FERC Order 2222 in the United States enables distributed energy resource aggregation, directly expanding addressable demand for behind-the-meter IoT endpoints. The EU Green Deal and F-Gas Regulation jointly mandate refrigerant leak detection and thermal efficiency monitoring, tightening product standards for industrial sensor deployments. China's GB standards and dual carbon goals impose data interoperability requirements on state grid procurement. Stakeholders must monitor which regulatory frameworks standardize data protocols versus those that prescribe hardware specifications, as this divergence determines platform scalability and vendor lock-in risk.
Market Dynamics
Utility-scale grid modernization is forcing a wholesale migration from centralized SCADA architectures toward distributed intelligence, with edge-enabled monitoring nodes now proliferating across transmission and distribution networks. This structural shift compresses latency requirements below 100 milliseconds while expanding the addressable hardware base for sensor OEMs and platform vendors.
Growth Catalysts
- FERC Order 2222:The United States mandate enables distributed energy resource aggregation, directly expanding deployment of behind-the-meter IoT endpoints for demand response and grid balancing services.
- EU Green Deal mandates:European transmission operators face accelerated sensor deployment requirements for thermal efficiency monitoring and refrigerant leak detection across high-voltage infrastructure.
- Sub-GHz spectrum utilization:Low-power wide-area networks operating in unlicensed bands reduce connectivity costs for rural grid monitoring applications, unlocking previously uneconomic deployment zones.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for power-efficient communication modules remains concentrated in East Asian foundries, exposing sensor OEMs to geopolitical supply disruption.
- Cybersecurity certification timelines:IEC 62443 compliance requirements for critical infrastructure IoT extend product development cycles by 12-18 months, compressing vendor margins.
- Legacy protocol fragmentation:Persistent coexistence of DNP3, Modbus, and IEC 61850 standards forces multi-protocol gateway investments that inflate deployment costs for utilities.
Strategic Opportunities
- India smart metering:The country's national power regulator mandates 250 million smart meter installations by 2025, creating concentrated demand for communication modules and analytics platforms.
- Digital twin convergence:Integration of physics-based simulation with real-time sensor streams enables predictive asset management for transformer fleets, opening premium service revenue pools.
- Behind-the-meter storage:Residential battery aggregation creates new endpoint categories for power quality monitoring and islanding detection in distributed microgrids.
Industry Challenges
- OT-IT integration expertise:Utilities face acute shortages of engineers capable of bridging operational technology environments with enterprise cybersecurity architectures.
- Multi-vendor interoperability:Proprietary data formats from incumbent automation suppliers create vendor lock-in that complicates platform consolidation initiatives.
- Field deployment scale:Physical installation of ruggedized sensors on energized switchgear requires certified lineworker capacity that utilities struggle to staff at required velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things in Energy Market |
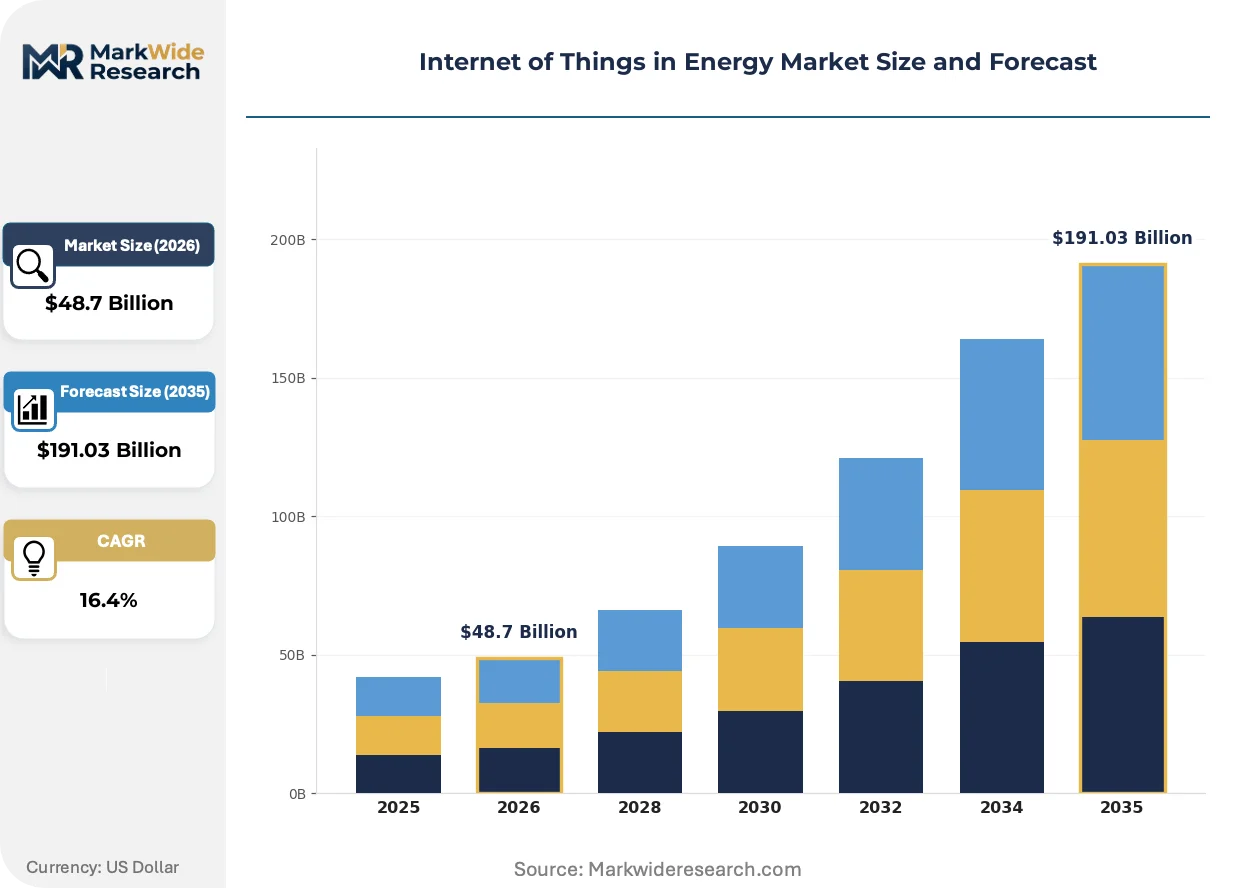
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $191.03 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Sensors, Communication Modules, IoT Platforms Application: Energy Management, Predictive Maintenance, Grid Monitoring, Demand Response End User: Utilities, Industrial, Commercial, Residential Installation: Onshore, Offshore, Smart Grid, Home Automation |
| Companies Covered | IBM, Verizon, Siemens, AT&T, Ericsson, Schneider Electric, Cisco, Accenture, GE Vernova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things in Energy Market Shifts & Advancements
Edge-native processing architectures are actively displacing cloud-dependent analytics in grid monitoring, with latency-sensitive applications now mandating local inference. This technological pivot reconfigures hardware specifications, software licensing models, and vendor competitive positioning simultaneously.
Time-synchronized phasor measurement units enhanced with embedded machine learning inference engines are rewriting protection and control strategies for transmission networks. European transmission system operators in Germany and France are deploying these intelligent PMUs at substation scale during the current retrofit cycle. The technology is compressing the traditional separation between measurement instrumentation and protective relay functions into unified edge devices.
China's GB standards for smart grid data interoperability impose mandatory open-protocol requirements on state grid procurement specifications. Domestic and foreign equipment suppliers must re-engineer communication stacks to satisfy these interoperability mandates. Industrial sensor vendors targeting the Chinese market are responding by modularizing protocol layers to accelerate certification cycles.
Utility procurement committees now prioritize outcome-based service contracts over capital equipment purchases, unbundling hardware ownership from analytics performance guarantees. European power distributors are leading this contractual evolution, with German municipal utilities restructuring vendor relationships around availability-based payments. This shift is most visible in predictive maintenance deployments for transformer and switchgear fleets.
Internet of Things in Energy Market Segmentation
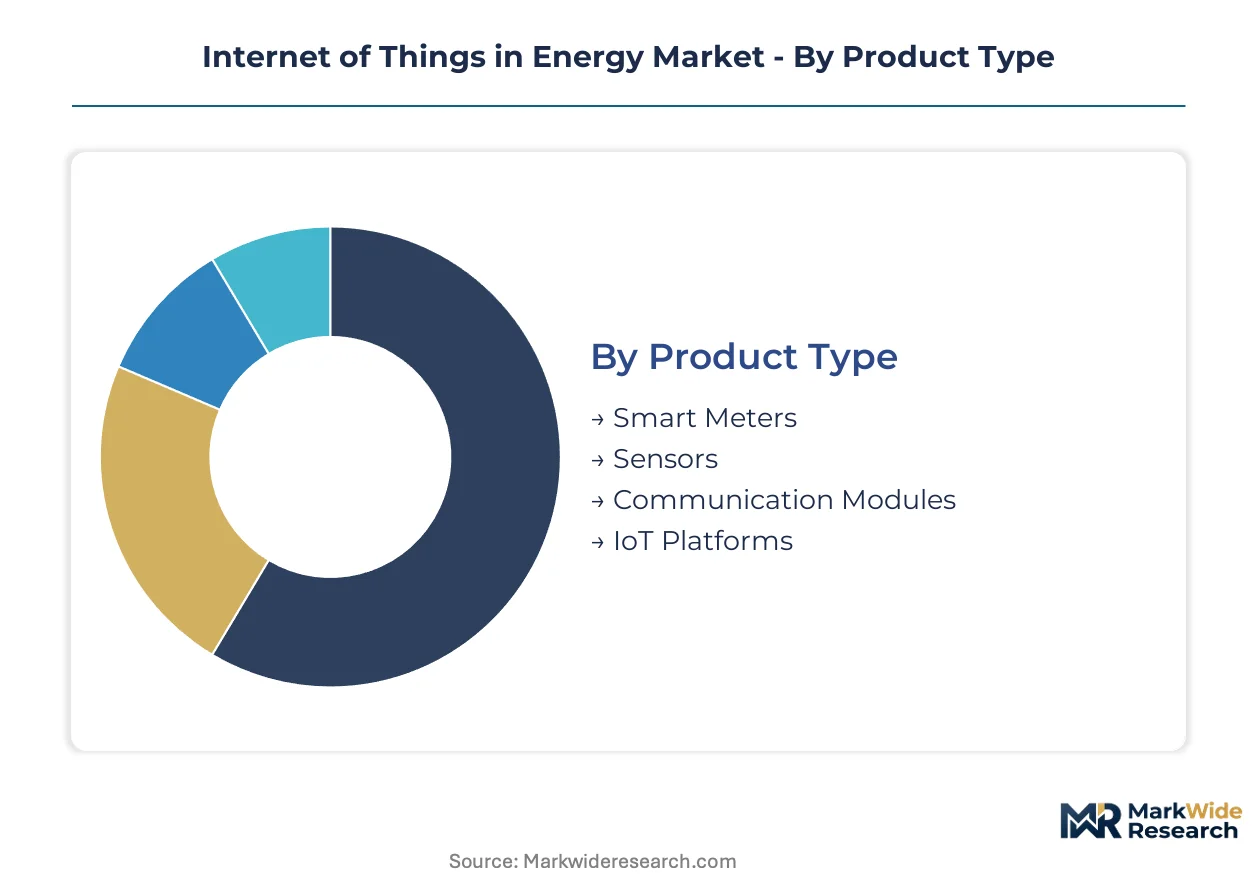
IoT deployments in energy require precise alignment between hardware specifications, application latency demands, and end-user procurement capabilities. Segmentation reveals where capital concentrates versus where volume scales fastest.
Product Type:
Capital intensity varies sharply across hardware categories, with platform and module investments front-loaded while sensor deployments spread across extended replacement cycles.
- Smart Meters:Solid-state measurement devices with integrated cellular or RF communication stacks for automated billing and load profiling. German municipal utilities and India's state discoms are driving concentrated procurement for advanced metering infrastructure, though certification timelines for IEC 62056 compliance extend vendor cash conversion cycles.
- Sensors:Thermal, vibration, and current transducers deployed on transformers and switchgear for condition monitoring. Demand clusters around EU transmission networks where F-Gas Regulation mandates refrigerant leak detection, creating specification premiums for industrial-grade enclosures.
- Communication Modules:Sub-GHz and cellular radio units enabling last-mile connectivity for distributed endpoints.
- IoT Platforms:Cloud and edge-native software stacks for data ingestion, analytics, and device management.
Smart meters absorb the bulk of installed capacity; IoT platforms are expanding most quickly.
Application:
Latency requirements and data sovereignty rules fragment the application landscape, with grid-stabilization use cases demanding fundamentally different architectures than back-office optimization.
- Energy Management:Real-time consumption analytics and automated load scheduling for commercial and industrial facilities. Large manufacturing clusters in China and Germany are retrofitting building management systems with open-protocol gateways to satisfy interoperability mandates.
- Predictive Maintenance:Physics-informed machine learning models applied to transformer and switchgear degradation signals. European utilities are restructuring vendor contracts around availability-based payments rather than capital equipment purchases, unbundling hardware ownership from performance guarantees.
- Grid Monitoring:Wide-area situational awareness through phasor measurement and fault detection.
- Demand Response:Automated load curtailment and distributed resource aggregation for frequency regulation.
Grid monitoring commands the deepest retrofit budgets; demand response is climbing the fastest as intermittent renewable penetration forces dynamic pricing mechanisms.
End User:
Procurement sophistication and cybersecurity compliance burdens create tiered market access, with utility buyers imposing IEC 62443 certification requirements that filter out smaller platform vendors.
- Utilities:Transmission and distribution operators with centralized procurement functions and multi-year capital planning horizons. State grid corporations in China and investor-owned utilities in the United States are migrating from centralized SCADA toward distributed intelligence architectures with edge-enabled monitoring nodes.
- Industrial:Heavy manufacturing, data centers, and process industries with behind-the-meter generation and storage assets. FERC Order 2222 enables distributed energy resource aggregation, expanding addressable demand for industrial IoT endpoints participating in wholesale markets.
- Commercial:Office buildings, retail chains, and institutional facilities with sustainability disclosure obligations.
- Residential:Single-family and multi-unit dwellings with smart home integration requirements.
Utilities anchor procurement volume; industrial end users are gaining share fastest through behind-the-meter aggregation plays.
Installation:
Physical deployment constraints and environmental hardening specifications segment the hardware supply base, with offshore and energized switchgear installations requiring certified lineworker capacity that limits deployment velocity.
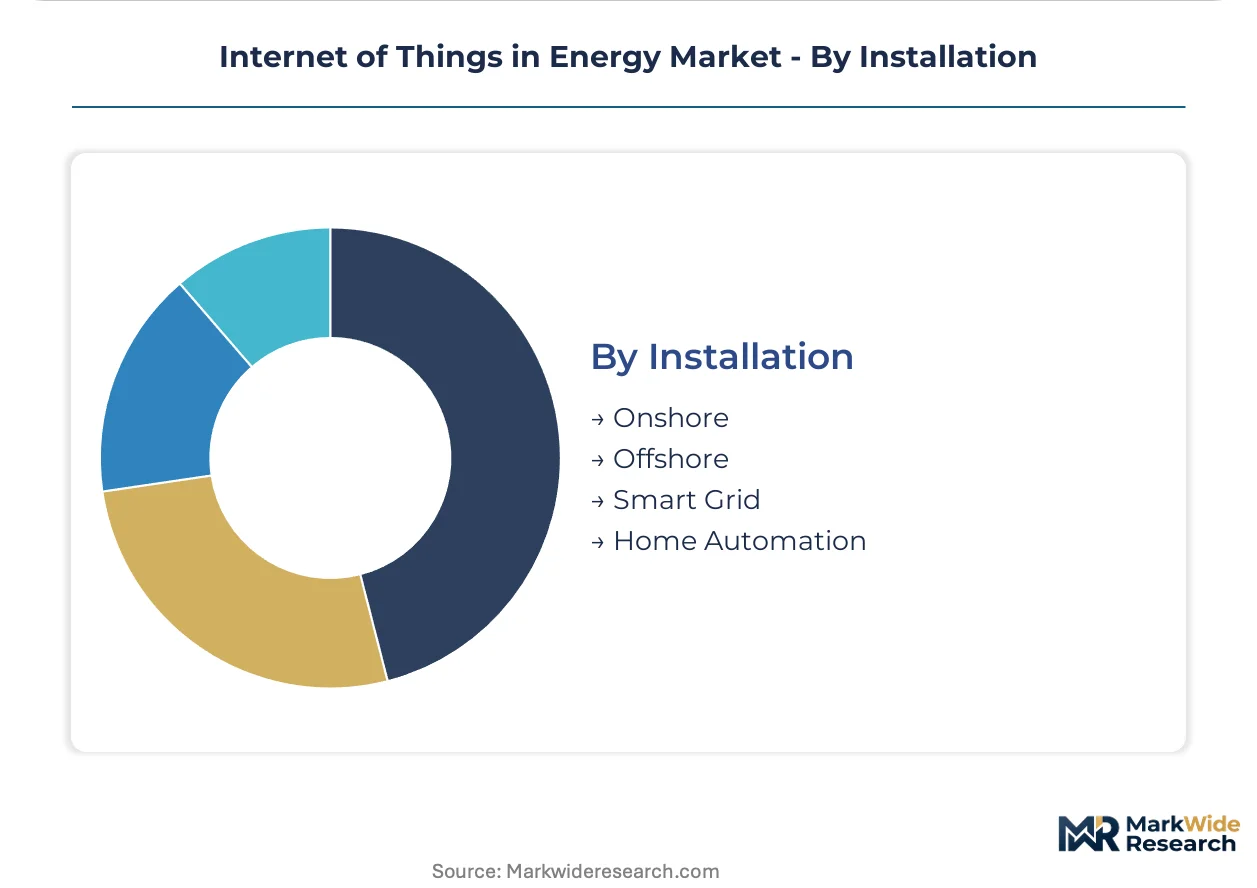
- Onshore:Terrestrial grid infrastructure including substations, transmission towers, and distribution feeders. Deployment concentrates in Germany, the United States, and China where smart grid investment pipelines remain deepest and regulatory mandates accelerate retrofit timelines.
- Offshore:Subsea cable monitoring and offshore wind farm connectivity with marine-grade enclosures. European North Sea developments and China's coastal wind installations drive specification requirements for salt-fog corrosion resistance and submersible sealing.
- Smart Grid:Integrated transmission-distribution automation with two-way communication and self-healing capabilities.
- Home Automation:Residential energy management with consumer-facing interfaces and third-party device integration.
Onshore installations absorb the bulk of deployed units; offshore is expanding most quickly as floating wind platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate sensor module fabrication, while India's designated smart city corridors concentrate demand for grid-connected endpoints. These incentive structures pull capital toward specific metropolitan clusters rather than dispersing deployment evenly across national territories.
United States
FERC Order 2222 drives distributed energy resource aggregation demand across Texas and California independent system operators. The Federal Energy Regulatory Commission's mandate enables behind-the-meter IoT endpoints to participate in wholesale capacity markets. ERCOT's Houston-Gulf Coast corridor hosts concentrated deployments of industrial demand response systems.
Germany
Municipal utilities in Bavaria and North Rhine-Westphalia retrofit transformer fleets with predictive maintenance sensors. The EU Green Deal and F-Gas Regulation mandate thermal efficiency monitoring across transmission networks. Siemens anchors European grid modernization contracts from its Munich-Nuremberg industrial corridor.
China
State Grid Corporation procurement enforces GB standards for data interoperability across Yangtze River Delta and Pearl River Delta zones. The dual carbon goals impose open-protocol requirements on equipment suppliers. Shanghai's smart grid pilot zone demonstrates edge-native processing architectures at substation scale.
India
The Central Electricity Authority mandates 250 million smart meter installations by 2025, concentrating demand in Maharashtra and Gujarat. State distribution companies in Delhi-NCR and Karnataka accelerate advanced metering infrastructure tenders. Bangalore's technology corridor hosts communication module assembly for rural grid monitoring.
Internet of Things in Energy Market Competitive Landscape
Top-tier vendors anchor utility-scale platform contracts, while mid-tier specialists capture niche sensor deployments. The market exhibits tiered concentration with automation heritage determining access to transmission operator procurement committees. Strategic archetypes include integrated hardware-software conglomerates, secure networking specialists, and edge analytics pure-plays. Dominant competitive moves involve portfolio diversification into predictive maintenance services and geographic expansion through outcome-based contracting.
Within the integrated systems tier, Siemens and Schneider Electric represent European automation heritage positioning, while Cisco exemplifies secure networking layer specialization bridging operational technology and enterprise IT environments. These three anchors demonstrate how vendor origin and legacy capability shape competitive access to grid modernization budgets across German, United States, and Chinese transmission networks.
| Leading Market Players |
|---|
| IBM |
| Verizon |
| Siemens |
| AT&T |
| Ericsson |
| Schneider Electric |
| Cisco |
| Accenture |
| GE Vernova |
| Others |
Supply & Pricing Matrix
IEC 62443 certification tiers bifurcate hardware procurement into premium-qualified and commodity-uncertified pools, with German transmission operators and Texas ISOs paying 40-60% spreads for identical sensor specifications. This tier divergence concentrates margin capture among automation heritage vendors while forcing price-sensitive Indian discoms toward multi-protocol gateway bundles that inflate total deployment costs.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with European utilities paying substantial markups for IEC 62056-certified smart meters against 26-week certification timelines. Subscription-based SaaS tiers for IoT platforms separate predictive maintenance analytics from basic device management, with Siemens and Schneider Electric anchoring premium positioning through integrated hardware-software bundles. Price erosion runs through cellular communication modules as sub-GHz LPWAN alternatives commoditize rural connectivity. Indian state discoms exhibit highest price sensitivity, while German municipal utilities prioritize availability guarantees over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from State Grid Corporation and ERCOT procurement committees require qualified secondary suppliers for power-efficient communication modules, fragmenting order books across Taiwan, South Korea, and domestic Chinese foundries. Semiconductor fabrication for RF front-ends and edge processors draws from concentrated East Asian capacity, with silicon wafer and rare-earth magnet dependencies exposing sensor OEMs to tariff volatility. Distribution runs through authorized automation distributors in Germany, direct utility procurement in the United States, and state tender aggregators in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around platform vendors with automation heritage, as IEC 62443 certification burdens and multi-protocol engineering requirements force sub-scale sensor OEMs toward acquisition or exit.
For Market Incumbents: Deepen edge-native analytics capabilities through targeted R&D in physics-informed machine learning for transformer degradation modeling, defending against pure-play software entrants. Secure exclusive channel relationships with German municipal utilities and Texas ISOs to lock out Schneider Electric and Cisco from critical substation retrofit cycles. Prioritize backward integration into sub-GHz radio module production to capture margin pools currently flowing to cellular chipset suppliers. For New Entrants and Emerging Players: Embedded machine learning inference engines for time-synchronized phasor measurement units offer the most penetrable wedge, with European TSOs in France and Germany actively unbundling measurement and protection functions. Target India's 250 million smart meter installation mandate through communication module assembly partnerships with Bangalore technology corridor firms. Pursue outcome-based contracting with availability-based payment structures to bypass incumbent equipment ownership models. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by automation conglomerates seeking predictive maintenance service capabilities, with industrial sensor vendors commanding premium multiples due to F-Gas Regulation-mandated deployment schedules. Mid-cap specialists with IEC 62443 certification and State Grid GB standard compliance represent the most defensible acquisition targets across the medium-term horizon. Monitor FERC Order 2222 implementation velocity in Texas and California ISOs as the critical inflection signal for behind-the-meter aggregation platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies edge analytics with SCADA legacy systems for German transmission operators. |
| Acquisition of Specialist Firm | Captures IEC 62443-certified sensor engineering teams from fragmented European OEMs. |
| Strategic Partnership | Links Cisco secure networking layers with Schneider Electric predictive maintenance deployments. |
| Geographic Expansion | Establishes outcome-based contracting presence in India's Maharashtra and Gujarat discoms. |
| Product Launch | Introduces GB standards-compliant communication modules for Yangtze River Delta procurement. |
Research Methodology
Independent corroboration across utility planning officers, IPP project developers, EPC contractors, and grid operators underwrites the qualitative findings, validated against FERC filings, EIA deployment data, IEA grid investment reports, and State Grid procurement disclosures. Primary interviews with transmission system operators in Germany, Texas ISO administrators, and Indian Central Electricity Authority officials combined with secondary triangulation across bottom-up project pipelines and top-down regulatory mandate quantification.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by hardware category, application latency tier, end-user procurement sophistication, and regional regulatory framework intensity. CAGRs derive from weighted capacity addition schedules, smart meter installation mandates, and edge computing deployment curves, with sensor OEM shipment data and platform vendor recurring revenue disclosures informing cross-segment calibration.
Several conditions sit outside the modeled scope, including unforeseen IEC 62443 standard revisions, geopolitical disruption of Taiwan semiconductor fabrication, and accelerated F-Gas Regulation enforcement timelines. Deviation in China dual carbon goal implementation velocity or FERC Order 2222 state-level adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Industrial IoT Platform Market
Internet of Things (IoT)
Consumer IoT Market
Internet of Things (IoT)
North America and Europe IoT Gateway Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Massive Machine Type Communication Market
Internet of Things (IoT)
Smart Tracker Market
Internet of Things (IoT)
IoT Application Development Services Market
Internet of Things (IoT)
North America IoT Device Market
Internet of Things (IoT)
Telecom Internet of Things (IoT) Market
Internet of Things (IoT)
IoT Software Market
Internet of Things (IoT)
Internet of Things (IoT) in Healthcare Market
Internet of Things (IoT)
GCC Indoor LBS Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Asia-Pacific Massive IoT Market
Internet of Things (IoT)
Europe IoT Device Market
Internet of Things (IoT)
Smart Sprinkler Controller Market