
 Internet of Things in BFSI Market | 2026-2036
Internet of Things in BFSI Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things in BFSI Market Analysis
Buyer concentration in banking institutions is consolidating as tier-one banks merge branch networks and centralize technology procurement across national footprints. Microsoft Corporation leverages its Azure IoT platform to anchor cloud-to-edge data pipelines for financial services workloads. Cisco Systems dominates industrial-grade networking infrastructure, while IBM Corporation sustains mainframe-integrated IoT analytics for legacy core banking systems.
The Internet of Things in BFSI encompasses sensor networks, connected terminals, and edge intelligence platforms that capture real-time operational data across financial service delivery points, transmitting via encrypted protocols to cloud analytics engines for automated decisioning. Its primary commercial purpose is to reduce fraud latency, optimize physical asset utilization, and personalize customer interactions at banking touchpoints. Fraud detection applications lead solution deployment as regulatory scrutiny intensifies, while edge computing architectures represent the fastest-expanding technology layer due to sub-millisecond response requirements for transactional security. Connected ATMs and wearable devices concentrate margin pools where hardware-software integration complexity creates vendor stickiness.
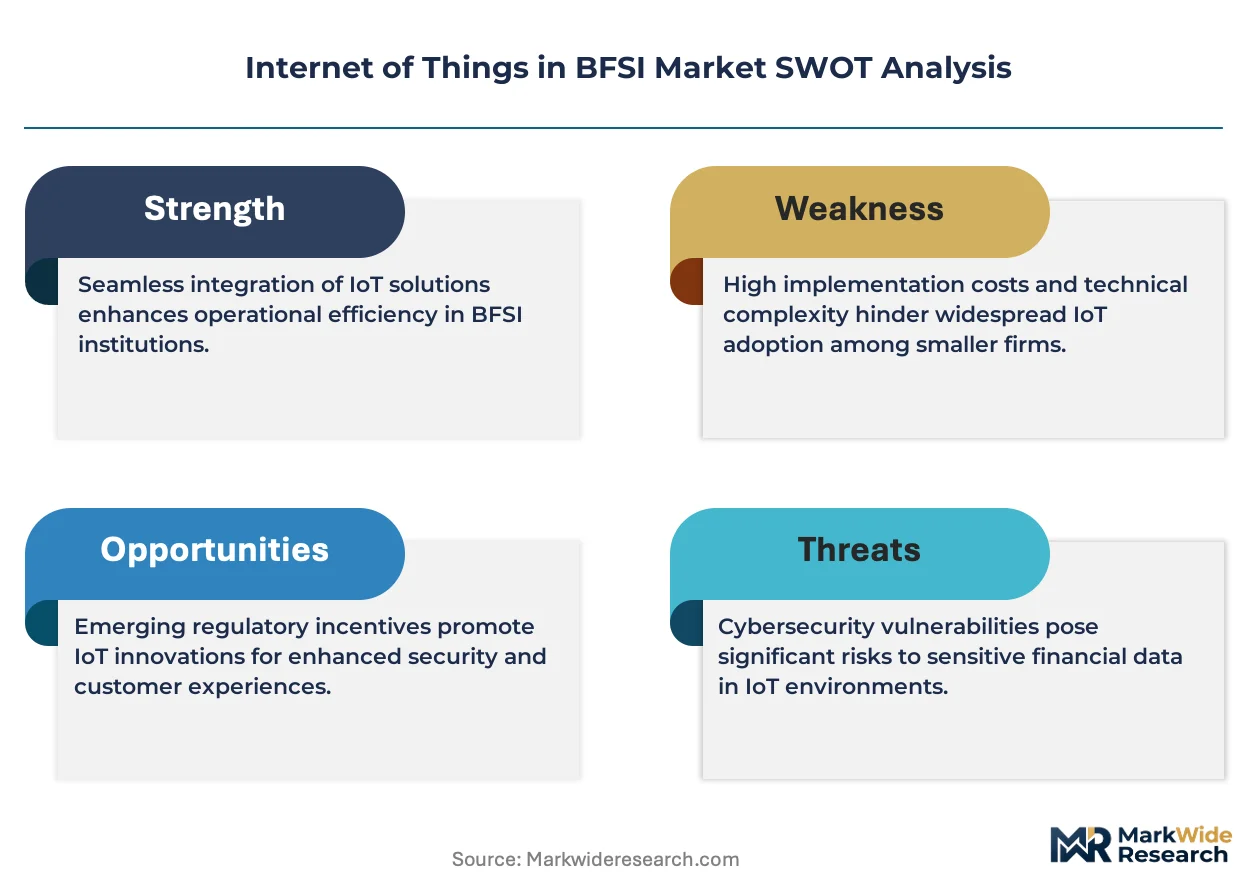
The EU AI Act and GDPR impose algorithmic transparency and data residency mandates that reshape IoT architecture choices for banks operating across European jurisdictions. In the United States, the SEC and state-level banking regulators enforce cybersecurity disclosure rules that elevate investment in connected device monitoring. India's RBI guidelines on digital payment infrastructure and data localization further fragment compliance requirements across multinational deployments. Stakeholders must evaluate whether centralized cloud governance or federated edge architectures better satisfy divergent regulatory trajectories without sacrificing operational interoperability.
Market Dynamics
EU AI Act mandates are forcing tier-one banks to rearchitect IoT deployments toward edge-first data governance, compressing vendor selection cycles and elevating compliance spend above hardware costs.
Growth Catalysts
- GDPR Data Residency Requirements:European banks must localize transactional data processing, accelerating edge computing procurement for branch-level IoT analytics.
- Real-Time Fraud Detection:Sub-millisecond response requirements for payment verification are expanding sensor networks across ATM fleets and POS terminals.
- India:RBI data localization guidelines for digital payments are mandating domestic edge infrastructure investments by multinational banks operating in the jurisdiction.
Market Restraints
- Semiconductor Supply Concentration:Edge AI chip fabrication concentrates in Taiwan and South Korea, creating vulnerability for banks scaling branch-level intelligence.
- EU AI Act Algorithmic Audit Costs:Mandatory transparency documentation for automated decisioning systems imposes recurring compliance overhead on IoT analytics platforms.
- Legacy Core Banking Integration:Mainframe-era transaction processing architectures resist real-time data ingestion from distributed IoT endpoints.
Strategic Opportunities
- Wearable Payment Authentication:Biometric-enabled devices represent underpenetrated consumer touchpoints for contactless transaction verification.
- Germany:Industrial Mittelstand banking relationships offer captive demand for asset-monitoring IoT in manufacturing supply chain finance.
- 5G-Edge Convergence:Ultra-reliable low-latency communication enables new branch automation use cases previously blocked by wireless bandwidth constraints.
Industry Challenges
- Embedded Systems Security Expertise:Shortage of firmware-level cryptography talent delays secure boot implementations for ATM sensor modules.
- Multi-Jurisdiction Certification Timelines:Divergent national cybersecurity frameworks for connected financial devices extend product launch cycles across operating regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things in BFSI Market |
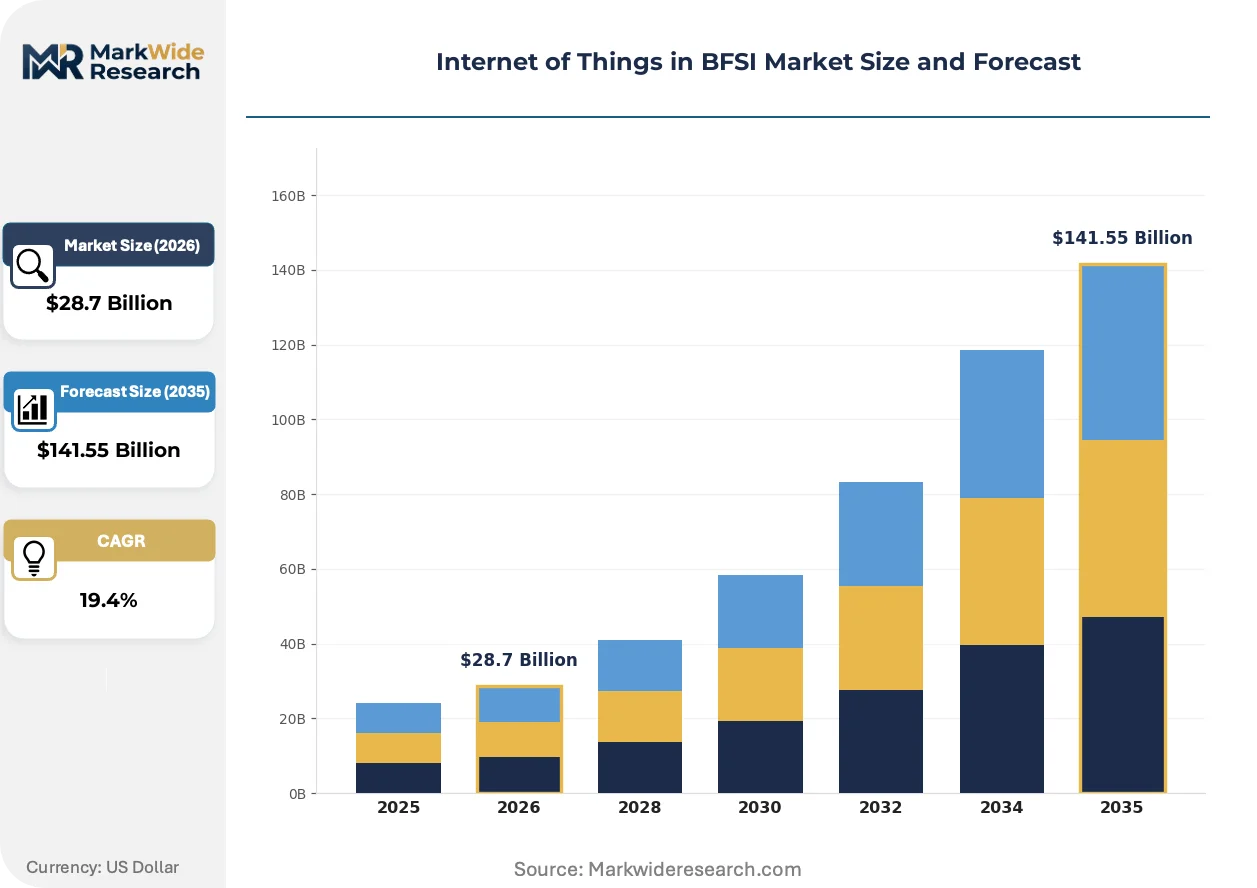
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $141.55 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Asset Tracking, Customer Analytics, Risk Management Technology: Edge Computing, Cloud Computing, Blockchain, API Integration End User: Banking Institutions, Investment Firms, Insurance Providers, Credit Unions Solution: Smart Contracts, Wearable Devices, IoT Platforms, Connected ATMs |
| Companies Covered | IBM Corporation, Cisco Systems, Microsoft Corporation, Oracle Corporation, SAP SE, Accenture Plc, Infosys Limited, Capgemini SE, Software AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things in BFSI Market Emerging Trajectories
Edge-native architectures are displacing cloud-dependent IoT pipelines as latency-sensitive use cases dominate banking infrastructure roadmaps. Three forces are compressing vendor positioning.
Confidential computing is rewriting how banks process sensitive transactional data at branch endpoints. Tier-one institutions in Germany and the United States are deploying trusted execution environments across ATM fleets. This hardware-based isolation is compressing compliance timelines for GDPR and state-level privacy mandates.
EU AI Act algorithmic transparency requirements are mandating explainable decisioning layers atop IoT-generated fraud signals. Banks operating across European jurisdictions must maintain audit trails for automated transaction blocks. The compliance burden falls heaviest on real-time payment verification systems, which are rearchitecting toward interpretable machine learning models.
Branch network consolidation is concentrating procurement authority at national headquarters, displacing regional technology autonomy. Centralized vendor selection committees in the United States and India now mandate enterprise-wide IoT platform standards. This buyer concentration elevates scale requirements for solution providers while compressing margins for point-product specialists.
Internet of Things in BFSI Market Segmentation
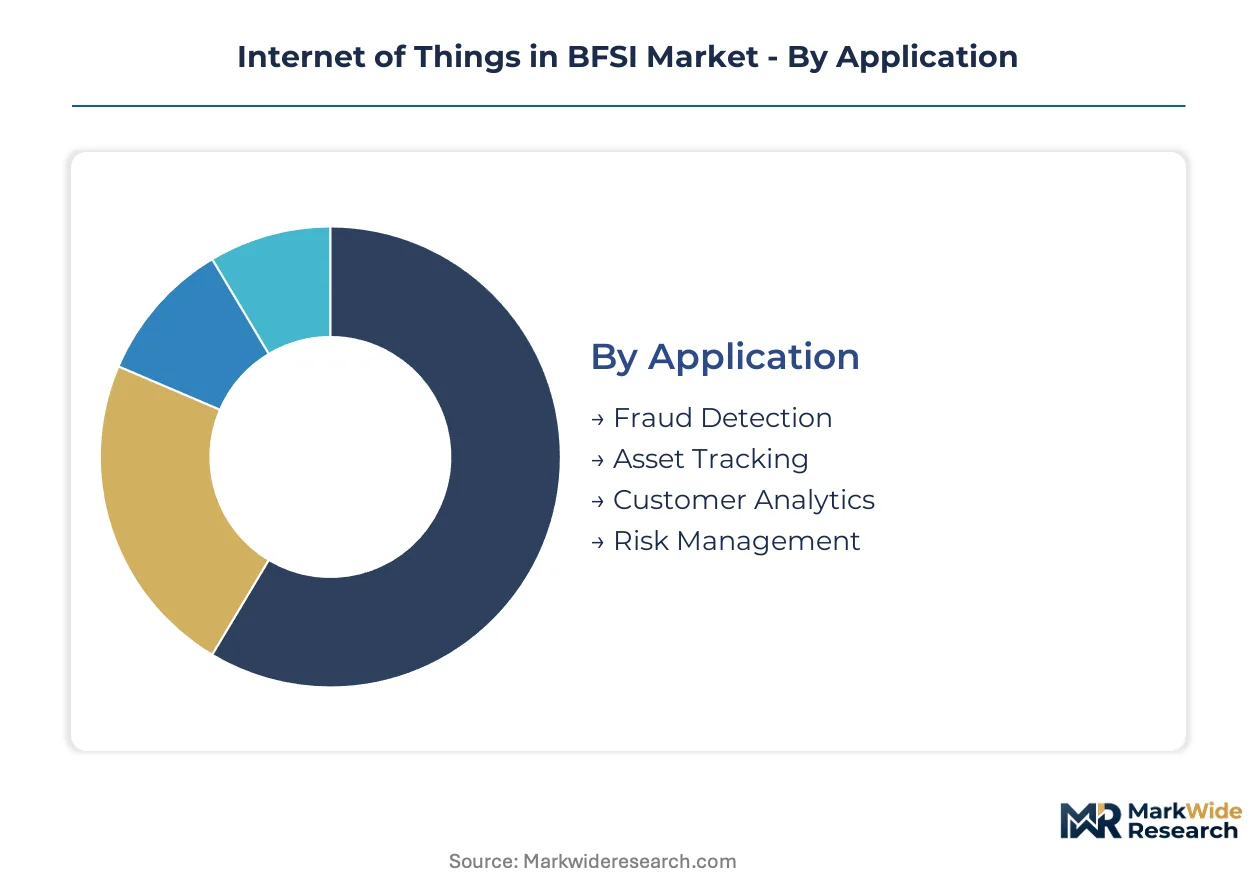
IoT segmentation in BFSI determines procurement authority and integration complexity. Banking technology buyers prioritize segments that compress fraud latency while satisfying divergent regulatory mandates across operating jurisdictions.
Application:
Standalone fraud detection systems operate at network perimeter, while embedded customer analytics integrate directly into core banking platforms.
- Fraud Detection:Real-time transaction monitoring systems deploy sensor networks across ATM fleets and POS terminals. Demand concentrates in tier-one banks across the United States and Germany as SEC and EU AI Act disclosure requirements intensify. Sub-millisecond response mandates are accelerating edge-native architectures.
- Asset Tracking:Geolocation and condition-monitoring sensors track physical collateral and branch equipment utilization. German Mittelstand banking relationships drive captive demand for supply chain finance applications where manufacturing asset visibility reduces underwriting risk.
- Customer Analytics:Behavioral pattern recognition from connected touchpoints enables personalized product recommendations.
- Risk Management:Environmental and operational sensors feed stress-testing models for credit portfolio monitoring.
Fraud detection leads volumes today; customer analytics is gaining share fastest.
Technology:
Cost tiers separate latency-sensitive edge deployments from centralized cloud analytics with lower per-transaction overhead.
- Edge Computing:Distributed processing nodes at branch endpoints execute transactional decisions without cloud round-trips. RBI data localization guidelines in India and GDPR residency mandates across European markets are mandating domestic edge infrastructure investments by multinational banks.
- Cloud Computing:Centralized data lakes aggregate historical patterns for model training and regulatory reporting. United States-based institutions dominate procurement as SEC cybersecurity disclosure rules elevate investment in connected device monitoring at scale.
- Blockchain:Distributed ledger protocols enable tamper-evident audit trails for IoT-generated transactional records.
- API Integration:Standardized interfaces connect legacy core banking systems to modern sensor networks.
Cloud computing anchors current spend; edge computing shows the steepest expansion trajectory.
End User:
Customer type determines procurement scale and solution customization requirements.
- Banking Institutions:National and regional banks deploy enterprise-wide IoT platforms across consolidated branch networks. Centralized vendor selection committees in India and the United States now mandate standardized edge-to-cloud architectures, elevating scale requirements for solution providers.
- Investment Firms:Asset managers utilize environmental sensors for ESG-aligned portfolio monitoring and alternative data sourcing.
- Insurance Providers:Usage-based underwriting models leverage connected device telemetry from policyholder assets.
- Credit Unions:Community-focused institutions prioritize cost-optimized fraud detection with limited IT staff.
Banking institutions dominate procurement volume; investment firms are expanding deployment fastest.
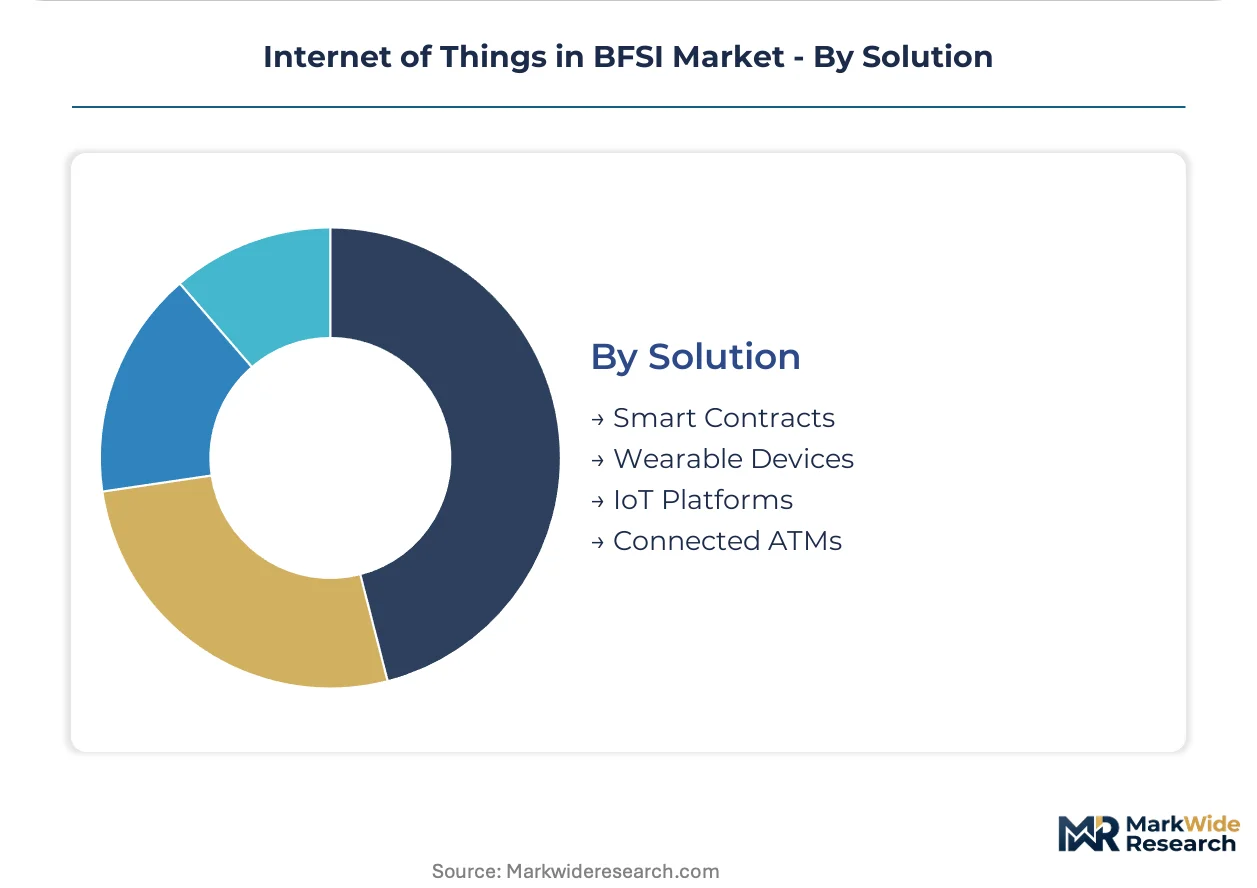
Solution:
Maturity curves separate established hardware-software bundles from emerging service layers.
- Connected ATMs:Sensor-embedded terminals with biometric authentication and predictive maintenance capabilities. Hardware-software integration complexity creates vendor stickiness where firmware-level cryptography expertise concentrates margin pools.
- IoT Platforms:Middleware layers manage device provisioning, data ingestion, and security policy enforcement. Demand clusters in Germany and the United States as confidential computing deployments across ATM fleets compress compliance timelines.
- Smart Contracts:Self-executing agreements triggered by IoT-verified events in trade finance and insurance.
- Wearable Devices:Biometric-enabled consumer touchpoints for contactless payment authentication represent underpenetrated deployment territory.
Connected ATMs lead installed base; IoT platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep pools of embedded systems engineers in Bangalore, firmware security specialists in Munich, and cloud architecture talent in Seattle anchor geographic deployment patterns for IoT-enabled financial infrastructure.
United States
SEC cybersecurity disclosure rules and state-level banking regulations drive tier-one banks toward centralized vendor selection committees. The SEC mandates connected device monitoring at scale, compressing procurement cycles for enterprise-wide IoT platforms. New York Metro and San Francisco Bay Area clusters concentrate fintech engineering talent developing confidential computing architectures for ATM fleets.
Germany
Industrial Mittelstand banking relationships generate captive demand for supply chain finance IoT applications. EU AI Act algorithmic transparency mandates and GDPR data residency requirements force rearchitecture toward edge-first data governance. Frankfurt and Munich financial centers host concentrated engineering teams deploying trusted execution environments across distributed banking infrastructure.
India
RBI data localization guidelines for digital payments mandate domestic edge infrastructure investments by multinational banks. The central bank's stringent digital payment infrastructure rules accelerate branch-level IoT analytics procurement. Mumbai and Bangalore technology corridors concentrate systems integrators bridging legacy core banking to modern sensor networks.
United Kingdom
Financial Conduct Authority operational resilience requirements elevate investment in real-time monitoring of connected banking devices. Post-Brexit regulatory divergence from EU frameworks creates parallel compliance tracks for IoT deployments. London's fintech density supports rapid prototyping of wearable payment authentication systems before continental scaling.
Singapore
Monetary Authority of Singapore digital banking licenses and sandbox frameworks accelerate experimental IoT deployments for new market entrants. The regulator's proactive stance on edge computing standards creates reference architectures for Southeast Asian expansion. Marina Bay financial district hosts regional headquarters coordinating multi-jurisdiction certification timelines for connected device rollouts.
Internet of Things in BFSI Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Cloud hyperscalers and legacy enterprise software vendors occupy the upper tier, leveraging existing financial services relationships to anchor IoT platform contracts. Systems integrators and niche middleware providers populate the mid-tier, competing on implementation speed and regulatory domain expertise. The vendor base exhibits moderate consolidation, with tier-one banks centralizing procurement authority and compressing the viable supplier set. Dominant competitive moves include strategic partnerships bridging cloud-to-edge data pipelines and portfolio diversification into confidential computing capabilities.
Within the technology platform tier, Microsoft Corporation and IBM Corporation exemplify contrasting architectural approaches. Microsoft anchors cloud-native IoT deployments through its Azure platform, while IBM sustains mainframe-integrated analytics for institutions resisting wholesale infrastructure migration. Cisco Systems occupies the networking infrastructure layer, its industrial-grade hardware concentrating in ATM fleet modernization programs. These three entities represent the dominant competitive anchors shaping procurement standards across tier-one banking institutions.
| Leading Market Players |
|---|
| IBM Corporation |
| Cisco Systems |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Accenture Plc |
| Infosys Limited |
| Capgemini SE |
| Software AG |
| Others |
Supply Flow & Price Mechanics
Centralized procurement committees at tier-one banks in the United States and India are mandating enterprise-wide edge computing standards, forcing semiconductor vendors to qualify components across divergent regulatory jurisdictions and compressing hardware margins through volume consolidation requirements.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for edge AI chips deployed in ATM sensor modules. Three-tier pricing structure across premium, standard, and economy levels separates confidential computing-enabled modules from baseline cryptographic units. Price differentiation hinges on firmware certification grade and post-deployment security update bundling. Cost compression in standard-tier components is intensifying because tier-one banks are consolidating supplier lists to satisfy SEC and EU AI Act audit requirements. Credit unions exhibit highest price sensitivity due to constrained IT procurement budgets, while multinational banking institutions absorb premium-tier premiums for compliance acceleration.
Supply Chain Analysis
Freight cost volatility for industrial-grade networking equipment is elevating landed costs for European branch modernization programs. Edge AI chip fabrication concentrates in Taiwan, South Korea, and the United States, creating geographic dependency for banks scaling branch-level intelligence. Supply chains draw from specialized silicon foundries, cryptographic firmware developers, and industrial sensor manufacturers. Single-source vulnerability in advanced node semiconductor production threatens procurement timelines for confidential computing deployments. Distribution runs through systems integrators with regulatory domain expertise in GDPR and RBI compliance certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where tier-one banks are prioritizing certified edge architectures over cost-optimized alternatives, compressing viable supplier sets to vendors with demonstrated EU AI Act and SEC compliance documentation.
For Market Incumbents: Anticipate margin compression from cloud hyperscalers bundling IoT platforms with core banking SaaS contracts. Defensive consolidation moves include acquiring firmware security specialists with embedded systems cryptography expertise and establishing captive edge chip supply through foundry partnerships in South Korea. Vertical integration into confidential computing hardware design protects pricing power as algorithmic audit requirements intensify. For New Entrants and Emerging Players: Enter via wearable payment authentication systems where biometric-enabled devices remain underpenetrated relative to connected ATM infrastructure. White-space targets include German Mittelstand banking relationships for supply chain finance IoT applications and Indian domestic edge infrastructure investments mandated by RBI localization guidelines. Go-to-market positioning should emphasize rapid GDPR compliance certification to bypass incumbent procurement lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier systems integrators bridging legacy core banking to modern sensor networks. Long-term viability favors vendors with demonstrated multi-jurisdiction certification capabilities spanning EU AI Act algorithmic transparency and SEC cybersecurity disclosure frameworks. Acquisition target archetype includes edge-native platform providers with confidential computing deployments at tier-one reference accounts. Signal to watch is consolidation of national procurement authority accelerating vendor list compression.| Strategic Initiative | Industry Significance |
|---|---|
| Confidential Computing Deployment | Trusted execution environments across ATM fleets compress GDPR and state-level privacy compliance timelines for tier-one banks. |
| Edge Infrastructure Localization | Domestic processing nodes satisfy RBI data residency mandates and EU AI Act algorithmic audit requirements in India and Germany. |
| Firmware Security Acquisition | Embedded systems cryptography talent scarcity delays secure boot implementations, creating defensive consolidation opportunities. |
| Multi-Jurisdiction Certification | Parallel compliance tracks for SEC, EU AI Act, and RBI frameworks extend product launch cycles without unified vendor documentation. |
| Wearable Payment Platform Launch | Biometric-enabled consumer touchpoints for contactless authentication represent underpenetrated deployment territory relative to ATM infrastructure. |
Methodological Framework
Coverage spans the United States, Germany, India, the United Kingdom, and Singapore, with primary inputs from each market combining structured interviews with banking technology procurement officers, edge computing platform engineers, regulatory compliance leads, and systems integration specialists. Secondary validation draws from SEC cybersecurity disclosure filings, RBI circulars on digital payment infrastructure, EU AI Act implementation guidance, and hyperscaler IoT platform capex disclosures. Bottom-up segment sizing triangulates against top-down banking IT spend estimates.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation dimensions modeled include application type, technology layer, end-user institution category, and solution maturity tier. CAGRs derive from regression analysis against banking branch consolidation rates, edge computing procurement trajectories, and regulatory compliance spend ratios. Industry-specific forecast inputs incorporate confidential computing adoption curves and multi-jurisdiction certification timeline data.
The model holds under stable regulatory enforcement intensity and continued tier-one bank procurement centralization; deviation in semiconductor supply availability or EU AI Act audit scope expansion would shift edge infrastructure investment timing. Forecasts reflect documented assumptions about buyer concentration trends and compliance cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global Internet of Things Technology Market
Internet of Things (IoT)
Airport Internet of Things Market
Internet of Things (IoT)
LTE IoT Market
Internet of Things (IoT)
Europe Massive IoT Market
Internet of Things (IoT)
Global Machine-To-Machine (M2M) Connections Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Global IOT Connectivity Management Platform (CMP) Market
Internet of Things (IoT)
Global Satellite Enabled IoT Software Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
Smart Sprinkler Controller Market
Internet of Things (IoT)
Global Internet of Behaviors Market
Internet of Things (IoT)
Europe IoT Services Market
Internet of Things (IoT)
Smart Sound and Gateway Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Global IoT Elevators Market