
 Global IoT Elevators Market | 2026-2036
Global IoT Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT Elevators Market Intelligence
A transition from single-source OEM maintenance contracts to multi-source service models for IoT components is expanding. KONE Corporation leverages its cloud-based 24/7 Connected Services platform to offer predictive maintenance globally. Schindler Group differentiates through its digital portfolio and partnerships with technology firms. TK Elevator competes on service flexibility for diverse building portfolios across new and existing installations.
IoT elevators are vertical transport systems integrated with sensors, connectivity modules, and cloud-based platforms for data exchange. These systems use real-time data on operational parameters like door cycles and motor temperature to enable predictive maintenance. Predictive analytics and cloud computing represent the core technology segments driving value for end users like facility operators. While passenger elevators in commercial complexes form the largest application, demand from property management firms for retrofitting existing fleets is a significant growth vector.
Compliance with safety standards like ASME A17.1 in the United States and the EU Lifts Directive is fundamental for market access and product design. Data handling from connected elevators must adhere to regulations such as the GDPR in Europe and China's Cybersecurity Law, shaping system architecture. Stakeholders must now decide on the optimal balance between proprietary, closed-loop systems and open, interoperable platforms for future investments.
Market Dynamics
The transition from reactive repair to predictive maintenance, driven by cloud computing and real-time sensor analytics, is the central structural force. This shift redefines operational efficiency and asset lifecycle management for vertical transportation systems.
Growth Catalysts
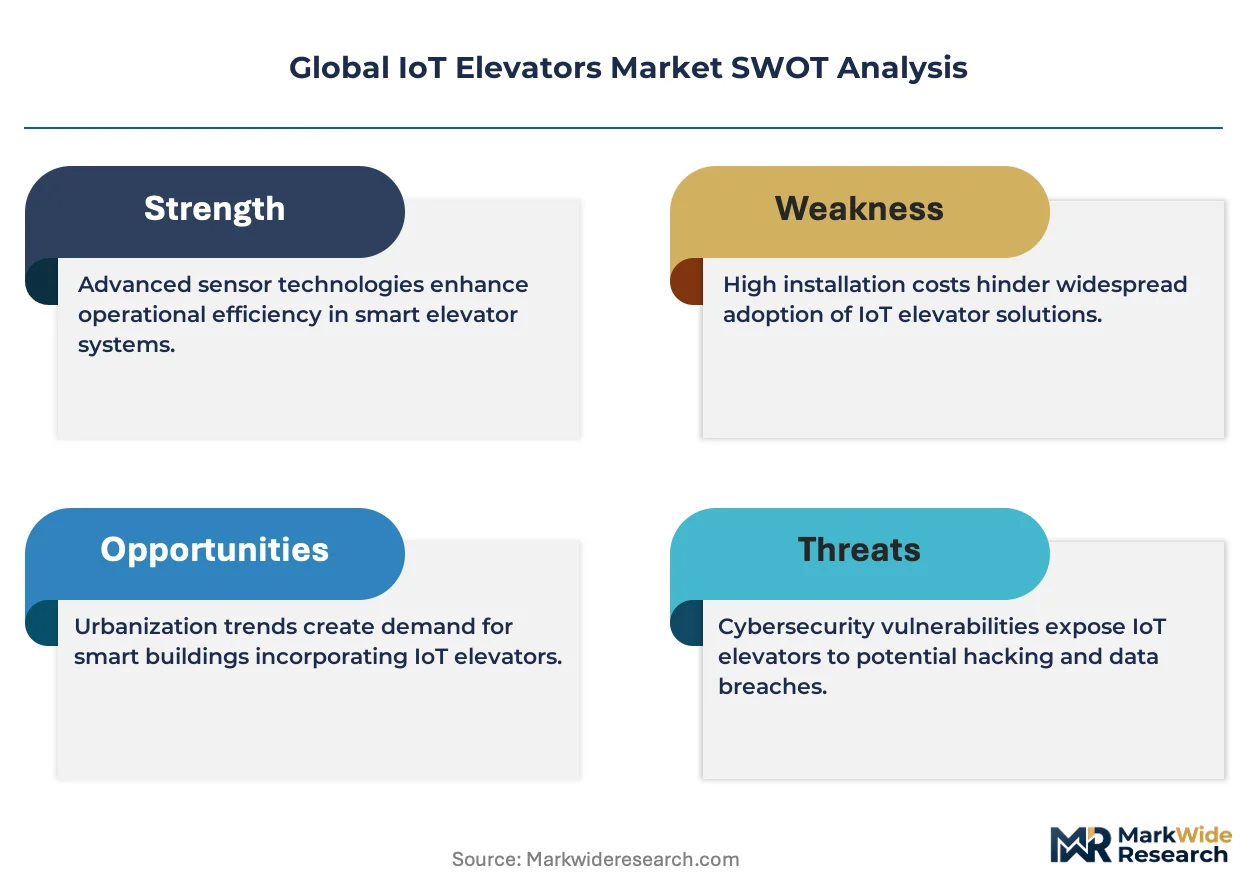
- Predictive Analytics:Demand from operators in hospitals and commercial complexes for reduced downtime and operational efficiency accelerates adoption.
- Smart City Mandates:Urban development projects in China specifying smart building infrastructure create a significant pull for new IoT elevator installations.
- Safety Standard Evolution:Modernization of codes like ASME A17.1 and the EU Lifts Directive encourages integrating digital monitoring capabilities.
Market Restraints
- High Retrofit Costs:Significant capital expenditure to upgrade existing elevator fleets with sensors and connectivity hardware presents a barrier for property owners.
- System Interoperability:Challenges integrating data from proprietary OEM systems with third-party analytics platforms limit flexibility and create vendor lock-in.
- Data Governance Complexity:Adherence to regulations like GDPR and China's Cybersecurity Law complicates system architecture and cross-border data flow.
Strategic Opportunities
- Service Model Unbundling:The growth of multi-source service contracts for IoT components creates an opening for specialized analytics providers to compete with OEMs.
- AI-Powered Passenger Management:Integrating elevator data with AI algorithms for real-time traffic analysis offers a new value proposition for high-density buildings.
- Energy Efficiency Services:Leveraging operational data to optimize elevator energy consumption provides a tangible ROI, aligning with green building certifications.
Industry Challenges
- Technician Skill Gap:A shortage of personnel proficient in both electromechanical systems and IT networking hinders effective service delivery.
- Legacy System Integration:The complexity of connecting new IoT platforms with older Building Management Systems (BMS) often leads to implementation delays and budget overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT Elevators Market |
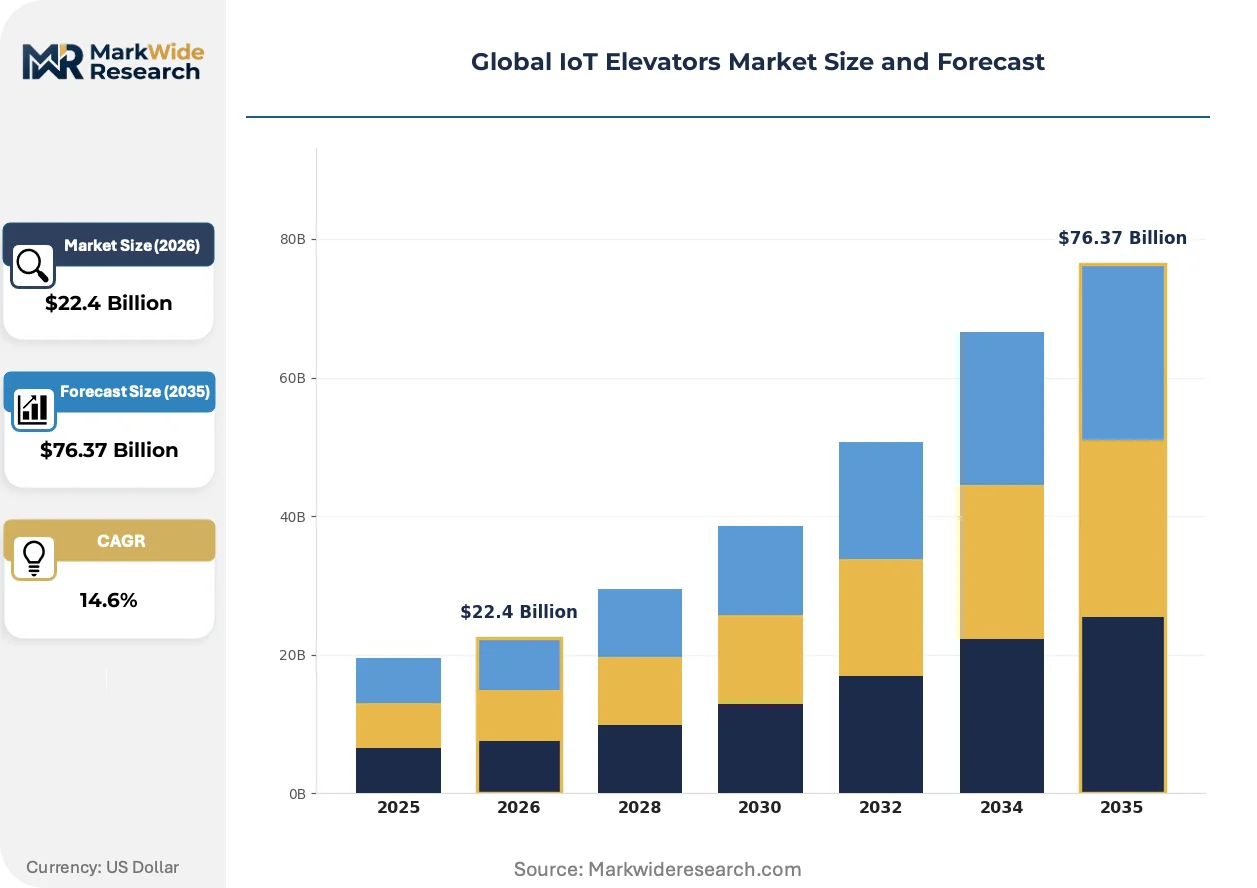
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $76.37 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Elevators, Freight Elevators, Service Elevators, Residential Elevators, Dumbwaiters Technology: Wireless Sensor Networks, Machine Learning, Cloud Computing, Edge Computing, Predictive Analytics Application: Commercial Complexes, Hospitals, Educational Institutions, Airports, Hotels End User: Property Management Firms, Facility Operators, Real Estate Developers, Infrastructure Maintenance Providers |
| Companies Covered | Otis Elevator Company, Schindler Group, KONE Corporation, Hyundai Elevator Co., Ltd., Fujitec Co., Ltd., Mitsubishi Electric Corporation, Hitachi, Ltd., Toshiba Elevator and Building Systems Corporation, TK Elevator, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT Elevators Market Strategic Shifts & Innovations
The market’s evolution now centers on integrating IoT elevators into the broader smart building fabric. This progression moves beyond simple remote monitoring to create intelligent vertical transport systems that enhance building operations and user experience.
Digital twin technology creates a dynamic virtual replica of a physical elevator, updated by real-time sensor data. Maintenance providers are adopting this for advanced diagnostics and failure prediction. This simulation capability is absorbing much of the need for on-site, trial-and-error diagnostics, significantly compressing troubleshooting timelines.
Europe's General Data Protection Regulation (GDPR) imposes strict controls on processing data from connected elevators, including passenger usage patterns. This regulation forces system architects to embed privacy-by-design principles like data anonymization into their platforms. Software developers are most impacted, redesigning data handling protocols to ensure compliance.
A shift from long-term, all-inclusive OEM maintenance contracts to flexible service agreements is gaining traction. This unbundling allows building managers to procure digital services separately from mechanical maintenance, fostering a competitive software ecosystem. The trend is most visible in North American and European commercial real estate with diverse portfolios.
Global IoT Elevators Market Segmentation
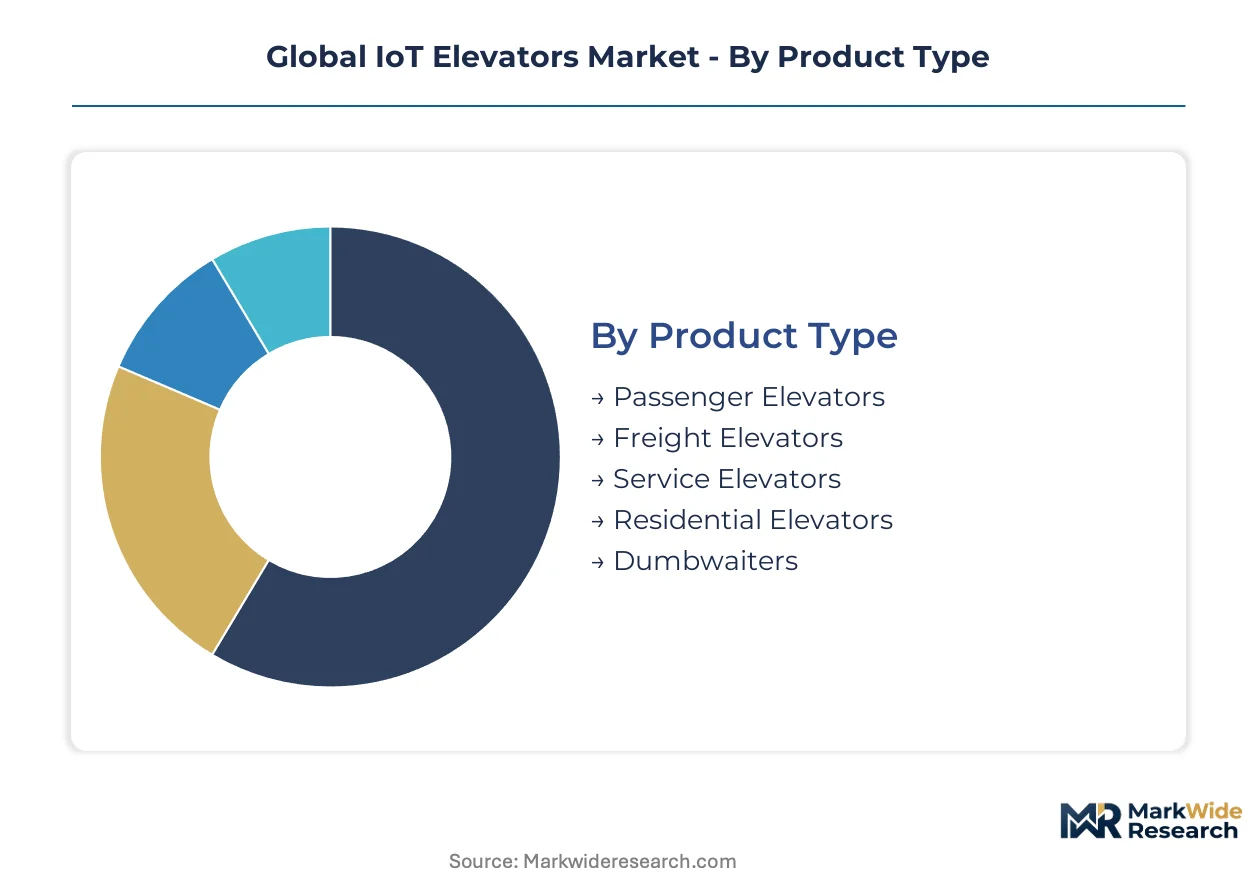
Understanding the segmentation of the global IoT elevators market reveals critical insights into investment priorities and technological adoption patterns. Market dynamics vary significantly across product types, underlying technologies, diverse applications, and distinct end-user requirements. This granular view helps stakeholders align strategies with demand drivers.
Product Type:
The capital intensity of IoT elevator installations varies significantly by product type, reflecting differences in mechanical complexity, sensor requirements, and integration with building infrastructure.
- Passenger Elevators:Designed for human transport in commercial, residential, and institutional buildings, forming the largest segment. Demand concentrates in high-rise commercial complexes, driven by efficient people flow and enhanced safety.
- Freight Elevators:Engineered for heavy-duty vertical transport of goods and materials within industrial facilities. Adoption accelerates in logistics hubs and manufacturing plants seeking optimized material handling and reduced downtime.
- Service Elevators:Specialized elevators used for staff, service carts, and equipment within hospitals, hotels, and offices.
- Residential Elevators:Smaller capacity elevators installed in private homes or multi-family dwellings, focusing on accessibility.
- Dumbwaiters:Compact service lifts for transporting small items like food or documents between floors in restaurants, libraries, or medical settings.
Passenger Elevators absorb the bulk of installed capacity; Residential Elevators are expanding most quickly.
Technology:
The functional application of various IoT technologies defines their market penetration, with some enabling foundational connectivity while others deliver advanced analytical capabilities.
- Predictive Analytics:This technology uses historical and real-time operational data to forecast equipment failures and maintenance needs. Demand concentrates in hospitals and commercial complexes to minimize unscheduled downtime.
- Cloud Computing:Provides scalable infrastructure for storing, processing, and analyzing data from connected elevators. Property management firms leverage cloud platforms for centralized monitoring and remote management of elevator fleets.
- Wireless Sensor Networks:Networks of interconnected sensors deployed within elevator systems collect real-time data on performance parameters, facilitating remote diagnostics.
- Machine Learning:Algorithms enable systems to learn from data patterns, improving predictive model accuracy and optimizing elevator traffic flow.
- Edge Computing:Processing data closer to the source reduces latency and bandwidth, crucial for real-time safety-critical applications.
Demand for Predictive Analytics is driven by operational efficiency, while Cloud Computing enables remote management capabilities.
Application:
The volume of daily passenger traffic and the criticality of uninterrupted operation significantly influence the adoption rates of IoT elevators across various building applications.
- Commercial Complexes:High-traffic office buildings, shopping malls, and mixed-use developments represent a major application area. Demand is driven by optimized traffic flow, reduced waiting times, and energy efficiency.
- Hospitals:Critical environments where elevator reliability and rapid response are paramount for patient and equipment transport. Predictive maintenance is highly valued to ensure continuous operation and minimize service disruptions.
- Educational Institutions:Universities and large school campuses utilize IoT elevators for student and staff movement within multi-story structures.
- Airports:High-volume transportation hubs requiring robust and reliable vertical transport systems to manage significant passenger flows and luggage.
- Hotels:Hospitality venues where smooth, efficient, and pleasing elevator operation contributes to guest experience and operational efficiency.
The integration of IoT elevators in Commercial Complexes is critical for managing high traffic, with Hospitals offering significant value through enhanced reliability.
End User:
Different end-user types prioritize distinct features and services from IoT elevator systems, ranging from operational cost reduction to enhanced tenant satisfaction.
- Property Management Firms:These entities oversee daily operations and maintenance of multiple buildings, seeking solutions offering centralized control and cost-effective fleet management. They prioritize multi-source service models for flexibility and reduced vendor lock-in.
- Facility Operators:Responsible for day-to-day functioning and upkeep of individual buildings, focusing on maximizing uptime and safety compliance. They increasingly demand predictive analytics for preemptive maintenance to prevent unexpected breakdowns.
- Real Estate Developers:Involved in new construction projects, integrating IoT elevators into smart building designs for future-proof infrastructure and market differentiation.
- Infrastructure Maintenance Providers:Specialized companies offering maintenance services for existing elevator fleets, leveraging IoT data to improve service efficiency and expand offerings.
Property Management Firms require advanced solutions for portfolio oversight, whereas Facility Operators prioritize immediate operational reliability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, a global manufacturing and urban development hub, anchors the adoption of IoT elevators due to its extensive smart city initiatives. Demand drivers and regulatory frameworks vary significantly across different major economies, shaping regional market growth. Each region prioritizes distinct aspects of IoT elevator technology, from operational efficiency to enhanced safety and data compliance.
China
Extensive smart city development projects and robust new construction drive significant demand for IoT elevator installations. China's Cybersecurity Law directly influences system architecture and data handling protocols for connected devices. Cities within the Yangtze River Delta, including Shanghai and Hangzhou, lead the integration of IoT elevator systems into large-scale urban infrastructure projects.
United States
Demand from high-traffic commercial complexes and property management firms for retrofitting existing fleets accelerates IoT elevator adoption. Compliance with ASME A17.1 safety standards is fundamental for market access and product design. Major metropolitan areas like New York City and Los Angeles focus on advanced predictive maintenance solutions to minimize downtime and improve building efficiency.
Germany
Operational efficiency in commercial buildings and stringent green building certifications stimulate demand for advanced IoT elevator systems. The EU Lifts Directive governs product design, while GDPR imposes strict data handling requirements for connected elevators. Cities like Berlin and Munich integrate IoT elevators into modern office and mixed-use developments to optimize energy consumption and enhance user experience.
Japan
Advanced urban infrastructure projects and a strong emphasis on earthquake resilience drive the integration of IoT elevators. JIS standards for elevator safety are critical, alongside national data privacy guidelines for connected systems. Tokyo's dense urban environment prioritizes efficient vertical transport and sophisticated passenger management systems, leveraging real-time data analytics.
India
Rapid urbanization, extensive new residential and commercial construction, and infrastructure development fuel the demand for IoT elevators. BIS standards for elevator safety are crucial, while emerging data protection laws influence system design. Major cities such as Mumbai and Bangalore see significant adoption in high-rise residential and commercial projects, driven by the need for reliable and efficient vertical transport.
Global IoT Elevators Market Key Industry Players
Strategic partnerships dominate the current landscape, especially with technology firms specializing in AI and cloud computing, to enhance digital service offerings. The market exhibits a tiered structure, with established global OEMs operating alongside specialized technology providers and regional service companies. Global integrators, regional specialists, and pure-play software/analytics firms represent key archetypes within this competitive environment. Portfolio diversification into digital services and geographic expansion into high-growth urban markets are common competitive moves.
Among global manufacturers, KONE Corporation, Schindler Group, and Otis Elevator Company exemplify firms leveraging extensive installed bases to offer advanced IoT solutions. These companies represent the archetype of vertically integrated OEM providers, increasingly focusing on digital service offerings like predictive maintenance. TK Elevator and Mitsubishi Electric Corporation also operate within this segment, emphasizing service flexibility and advanced system integration for diverse building portfolios. Hyundai Elevator Co., Ltd., and Fujitec Co., Ltd., frequently occupy positions as regional powerhouses, adapting global technologies to local market demands. Hitachi, Ltd. and Toshiba Elevator and Building Systems Corporation further demonstrate the trend towards comprehensive building solutions, integrating IoT elevators into broader smart infrastructure platforms.
| Leading Market Players |
|---|
| Otis Elevator Company |
| Schindler Group |
| KONE Corporation |
| Hyundai Elevator Co., Ltd. |
| Fujitec Co., Ltd. |
| Mitsubishi Electric Corporation |
| Hitachi, Ltd. |
| Toshiba Elevator and Building Systems Corporation |
| TK Elevator |
| Others |
Cost & Logistics Intelligence
IoT integration into elevator systems simultaneously reshapes cost economics by enabling predictive maintenance and influences supply concentration towards digital service providers. This technological shift encourages new competitive models beyond traditional mechanical maintenance.
Pricing Analysis
Service-bundling for IoT components is increasingly unbundled from mechanical maintenance contracts, creating distinct pricing structures. Subscription-based models for cloud analytics and predictive maintenance are gaining traction, complementing project-based pricing for new installations. Price differentiation stems from customization levels for building management system integration and the depth of after-sales technical support. Pricing pressure stems from the emergence of specialized analytics providers offering competitive digital services. Property management firms exhibit the highest price sensitivity, seeking cost-effective fleet management solutions.
Supply Chain Analysis
OEM-led direct sales channels dominate the distribution of new IoT elevator installations, while specialized IT service providers handle digital component integration. Geographic supply concentration for core IoT components like sensors and microcontrollers centers on China, Germany, and Japan. Raw material dependencies include specialized semiconductors, connectivity modules, and cloud infrastructure services. Single-source vulnerability for proprietary IoT platforms represents a structural supply chain risk. Downstream distribution for digital services increasingly runs through partnerships with technology firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT elevators market functions as a vertical-integration race, with players aggressively pursuing upstream control over software and analytics capabilities.
For Market Incumbents: Lock in existing customer bases through enhanced digital service offerings and long-term data partnerships. Invest in upskilling technical personnel to bridge the electromechanical and IT networking skill gap, mitigating service delivery threats. Deepen vertical integration into proprietary software platforms to differentiate against emerging analytics providers. Prioritize interoperability with diverse building management systems to avoid vendor lock-in concerns from property managers.
For New Entrants and Emerging Players: Launch via specialized analytics platforms targeting the retrofitting market within commercial complexes. Focus on delivering tangible ROI through energy efficiency services and AI-powered passenger management for high-density buildings. The most penetrable segment remains property management firms seeking flexible, multi-source service contracts. Leverage open, interoperable platforms to challenge OEM dominance and address system integration challenges directly.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized software and analytics firms capable of integrating with diverse OEM hardware. Long-term viability hinges on companies that can demonstrate robust data governance compliance and scalable cloud-based solutions over the next five to ten years. A critical signal to watch is the widespread adoption of open-standard IoT protocols, indicating reduced vendor lock-in and expanded market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Open API Ecosystems | Enhances platform interoperability for facility operators, fostering broader adoption. |
| Invest in Technician Upskilling Programs | Addresses the critical skill gap in IoT and electromechanical system maintenance. |
| Form AI/Cloud Partnerships | Accelerates digital service innovation and expands predictive maintenance capabilities. |
| Expand Retrofit Solution Portfolio | Captures significant growth from property management firms upgrading existing fleets. |
| Prioritize Cybersecurity Certifications | Builds trust in data handling, crucial for compliance with global regulations like GDPR. |
Research Approach
Independent corroboration across primary interviews, regulatory filings, and industry association data underwrites the qualitative findings within this study. This approach combines insights from facility operators, property managers, OEM engineers, and IT architects with secondary validation from smart city reports and technology publications. The methodology ensures a robust, triangulated perspective on market dynamics and technological trends.
The analytical framework anchors the forecast window to comparable historical reference periods, assessing market evolution over the projection horizon. Segmentation dimensions modeled include product type, underlying technology, diverse applications, end-user requirements, and regional adoption patterns. Compound annual growth rates were derived from a multi-factor analysis, with key forecast inputs including smart city project pipelines and commercial building construction starts.
The model assumes a particular technology adoption path; alternative pathways for edge computing or quantum-resistant cryptography would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Global IoT Connectivity Market
Internet of Things (IoT)
IoT Cloud Platform Market
Internet of Things (IoT)
IoT Software Engineering Market
Internet of Things (IoT)
IoT in Chemical Industry Market
Internet of Things (IoT)
Global Internet of Things (IoT) Software Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
LAMEA Bluetooth 5.0 Market
Internet of Things (IoT)
IoT in Warehouse Management Market
Internet of Things (IoT)
Global IoT Based Asset Tracking and Monitoring Market
Internet of Things (IoT)
North America Industrial IoT Market
Internet of Things (IoT)
IoT Cellular Market
Internet of Things (IoT)
Global IoT in Automobile Market
Internet of Things (IoT)
South Africa IoT Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
IoT for Cold Chain Monitoring Market