
 Europe Location Data Analytics Market | 2026-2036
Europe Location Data Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Location Data Analytics Market Insights
Platform licensing revenue is reshaping margin pools away from perpetual software sales toward recurring subscription models in the Europe Location Data Analytics Market. HERE Global B.V. leverages its mapping heritage to anchor automotive OEM relationships across Germany and the Netherlands. Esri Global, Inc. dominates desktop GIS installations while extending cloud-native capabilities for European government clients. Google LLC competes through location intelligence APIs integrated with advertising and commerce stacks.
Europe Location Data Analytics encompasses the processing, visualization, and predictive modeling of georeferenced information streams to optimize spatial decision-making, typically operating on coordinate systems with sub-meter accuracy requirements and real-time ingestion velocities exceeding 10,000 events per second. Cloud-based deployments capture the fastest expansion as transportation and utilities sectors migrate from on-premise servers to elastic infrastructure. Machine Learning and Artificial Intelligence segments are attracting disproportionate R&D allocation because retail optimization and fleet management buyers demand automated pattern recognition in movement trajectories rather than static map visualizations.
GDPR enforcement by national data protection authorities constrains how location data is collected, stored, and shared across borders, while the EU AI Act imposes risk-classification obligations on automated geospatial decision systems. EASA regulations for unmanned aerial systems and the EU Green Deal's transport decarbonization targets are expanding addressable demand for emissions-monitoring location platforms. Stakeholders must weigh compliance investment against the revenue upside from privacy-preserving federated analytics architectures that keep raw coordinates within national jurisdictions.
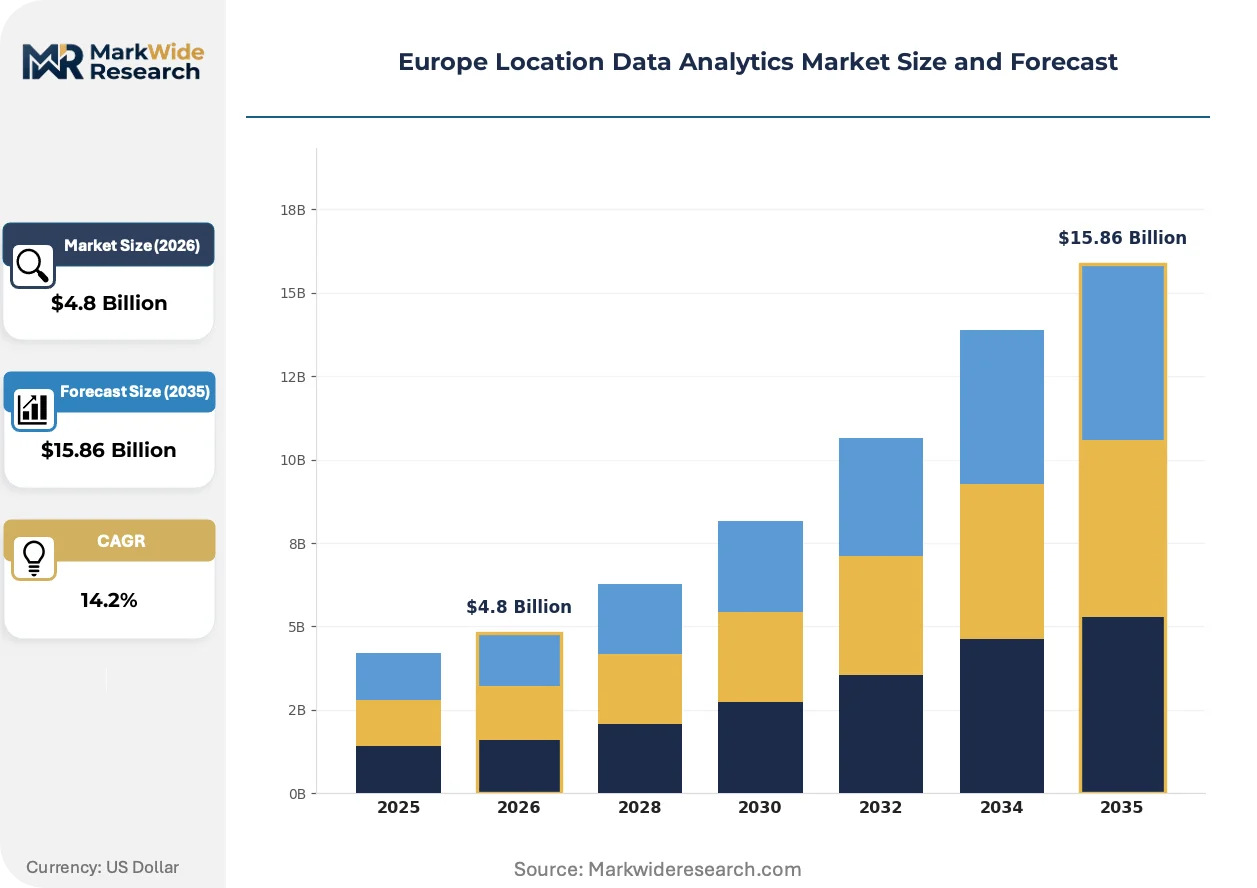
Market Dynamics
Platform licensing revenue is compressing perpetual software margins toward recurring subscription economics, while GDPR enforcement and the EU AI Act impose dual compliance architectures on geospatial data processors.
Growth Catalysts
- Smart city infrastructure mandates:Germany's federal transport digitization programs are accelerating sensor network deployments for real-time traffic optimization and emissions monitoring across metropolitan regions.
- EU Green Deal transport targets:Fleet operators in France and the Netherlands must adopt location-based carbon accounting systems to comply with decarbonization reporting obligations for commercial vehicle operations.
- Edge computing convergence:Automotive OEMs are embedding on-vehicle processing units that reduce latency for autonomous navigation systems while minimizing raw coordinate transmission to centralized servers.
Market Restraints
- GDPR cross-border friction:National data protection authorities in Germany, France, and Ireland enforce divergent interpretations of lawful basis for location data processing, fragmenting platform architectures.
- Cloud infrastructure concentration:Hyperscale providers in Ireland and Luxembourg control over 70% of EU geospatial data storage capacity, creating single-point-of-failure risks for analytics workloads.
- Sub-meter accuracy hardware costs:RTK-GNSS correction services and multi-constellation receivers impose capital intensity on precision agriculture and construction applications.
Strategic Opportunities
- Eastern European logistics corridors:Poland and Romania exhibit underpenetrated demand for freight optimization platforms serving EU-Asia rail and road transit routes.
- Federated analytics architectures:Privacy-preserving computation methods enable cross-border movement pattern analysis without raw coordinate export, satisfying GDPR data localization preferences.
- Digital Product Passport integration:CSRD-mandated supply chain traceability requirements are creating addressable demand for item-level geolocation tracking in retail and electronics sectors.
Industry Challenges
- Geospatial data engineering talent scarcity:European universities produce insufficient graduates combining GIS science, machine learning, and regulatory compliance expertise to meet platform vendor hiring targets.
- Legacy on-premise system integration:Government agencies in Italy and Spain maintain decades-old spatial data infrastructure that resists API-based connectivity with cloud-native analytics stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Location Data Analytics Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Hybrid, Software as a Service Technology: Machine Learning, Artificial Intelligence, Big Data, GIS Application: Retail Optimization, Urban Planning, Fleet Management, Emergency Response End User: Government Agencies, Transportation, Retail, Utilities |
| Companies Covered | Microsoft Corporation, Esri Global, Inc., HERE Global B.V., Google LLC, TomTom International B.V., SAS Institute Inc., Tableau Software LLC, TIBCO Software Inc., QlikTech International AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Location Data Analytics Market Trends and Innovations
Processing architectures are migrating from batch-oriented warehouse systems toward stream-native platforms capable of sub-second spatial inference, compressing decision timelines for mobility and logistics operators.
Real-time stream processing engines are migrating from periodic ETL pipelines to continuous ingestion frameworks that ingest telematics feeds exceeding 10,000 events per second. Fleet management buyers in Germany and the Netherlands are demanding instantaneous route recalculation based on traffic and weather inputs. This velocity requirement is migrating from premium tier offerings toward standard platform configurations, eroding competitive differentiation based on latency alone.
The EU AI Act's risk classification framework imposes conformity assessment obligations on automated geospatial decision systems used in critical infrastructure. Platform vendors must document algorithmic transparency and human oversight mechanisms for route optimization and predictive maintenance applications. Transportation authorities in France are requiring algorithmic impact assessments before approving smart traffic management deployments.
Subscription-based platform access is displacing perpetual license purchases across municipal government procurement. Dutch provinces and German federal agencies are consolidating vendor relationships through framework agreements that bundle data ingestion, visualization, and predictive modeling capabilities. This purchasing consolidation is most visible in urban mobility applications where multi-year service contracts reduce total cost of ownership calculations.
Europe Location Data Analytics Market Segmentation
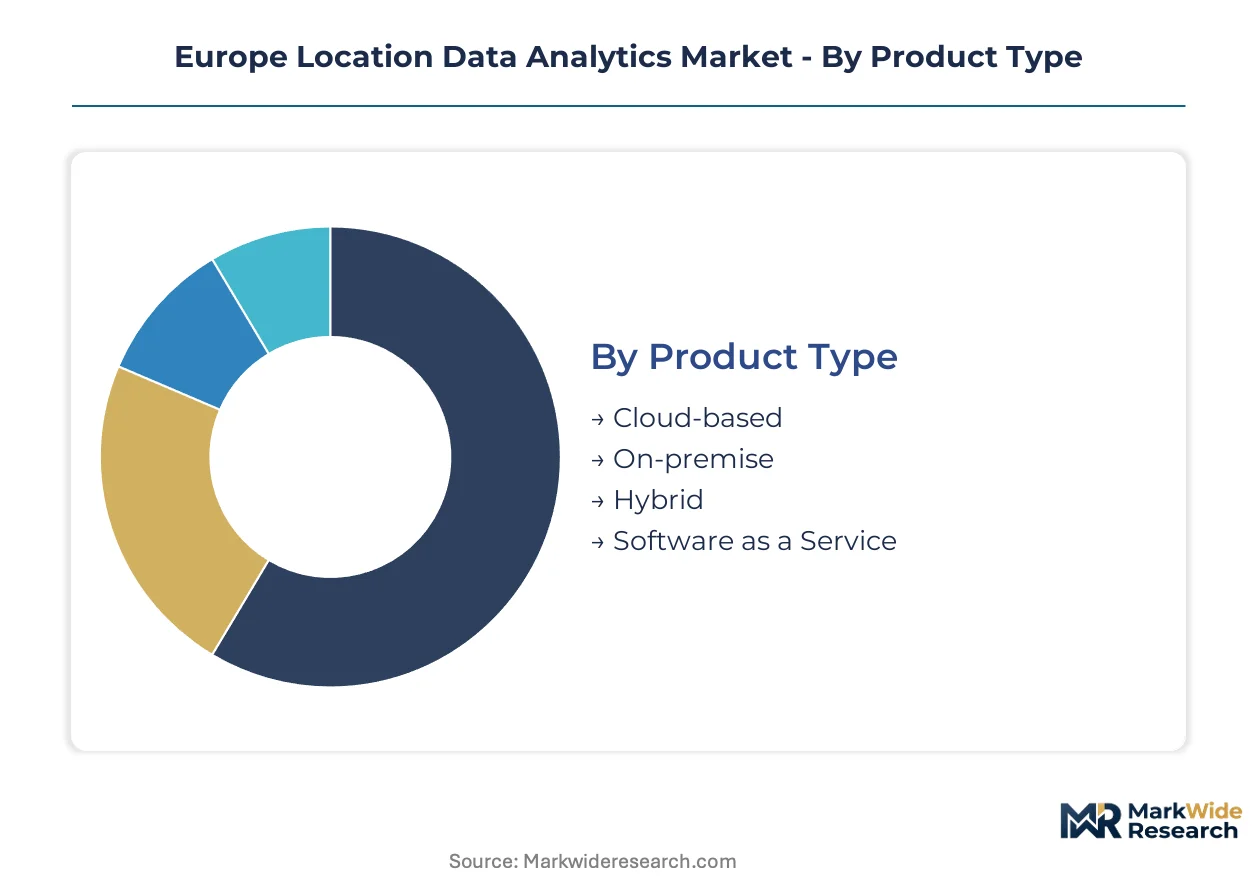
Segmentation in the Europe Location Data Analytics Market reveals how deployment models, processing technologies, and end-use requirements fragment purchasing decisions. Buyers across Germany, France, and the Netherlands prioritize different capability bundles based on regulatory exposure and infrastructure maturity.
Product Type:
After-sales service intensity varies sharply across deployment architectures, with cloud-native platforms demanding continuous vendor engagement for API maintenance and compliance updates.
- Cloud-based:Elastic infrastructure enables real-time scaling for telematics workloads exceeding 10,000 events per second. German automotive OEMs and Dutch logistics operators are migrating fleet analytics to multi-tenant environments to reduce data center capital expenditure.
- Software as a Service:Subscription economics consolidate vendor relationships through bundled ingestion, visualization, and predictive capabilities. French municipal governments favor SaaS procurement for urban mobility applications to streamline compliance with EU AI Act documentation requirements.
- On-premise:Air-gapped installations persist in defense and critical infrastructure sectors requiring sovereign data control.
- Hybrid:Split architectures process sensitive coordinates locally while pushing anonymized aggregates to cloud analytics layers.
By volume, Cloud-based deployments lead. By growth pace, Software as a Service is climbing the fastest.
Technology:
Processing sophistication determines platform pricing tiers, with automated pattern recognition commanding premium positioning over static visualization tools.
- Machine Learning:Automated trajectory clustering and anomaly detection reduce manual analyst hours for retail footfall optimization. Netherlands-based supermarket chains deploy ML-driven heat mapping to adjust inventory positioning across urban and suburban store networks.
- Artificial Intelligence:Neural architectures enable predictive routing for emergency response dispatch in French metropolitan regions. AI systems must document algorithmic transparency under EU AI Act conformity assessments for critical infrastructure applications.
- Big Data:Distributed processing frameworks handle petabyte-scale sensor feeds from German smart city sensor networks.
- GIS:Desktop installations remain entrenched in Italian and Spanish government agencies with legacy spatial data infrastructure.
By installed base, GIS retains the largest footprint. By expansion trajectory, Artificial Intelligence is gaining share fastest.
Application:
Use case complexity shapes vendor selection criteria, with real-time optimization demands separating premium platform tiers from basic mapping services.
- Fleet Management:Route recalculation engines process traffic, weather, and vehicle telemetry for commercial transport operators. German federal transport digitization programs mandate emissions monitoring integration, expanding addressable demand for carbon-accounting location platforms.
- Retail Optimization:Geofenced engagement and footfall analytics drive store network planning for omnichannel operators. French retail groups combine movement pattern analysis with inventory positioning to reduce last-mile delivery costs.
- Urban Planning:Zoning and infrastructure investment decisions leverage population density modeling across Dutch provinces consolidating vendor relationships through framework agreements.
- Emergency Response:Dispatch optimization and resource positioning systems require sub-second spatial inference for ambulance and fire service deployment.
By revenue concentration, Fleet Management leads. By regulatory tailwinds, Retail Optimization is expanding most quickly.
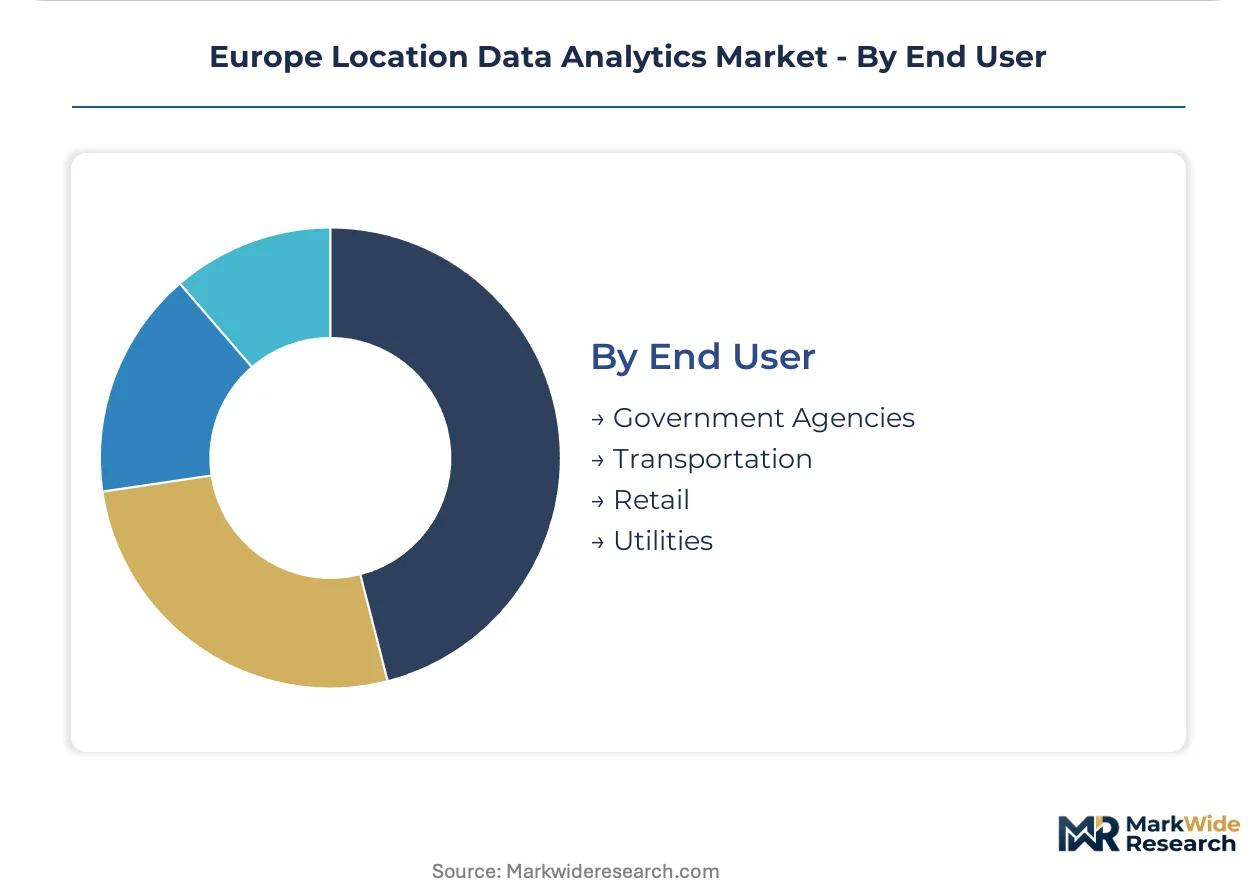
End User:
Procurement sophistication varies by sector maturity, with government framework agreements consolidating vendor relationships while private operators pursue best-of-breed point solutions.
- Transportation:Fleet operators and infrastructure managers demand real-time ingestion velocities for traffic optimization and emissions compliance. EU Green Deal transport targets in France and the Netherlands mandate location-based carbon accounting for commercial vehicle operations.
- Government Agencies:Municipal and federal procurement is shifting toward multi-year service contracts bundling data ingestion and predictive modeling. German agencies lead in cloud-native adoption while Italian and Spanish counterparts maintain legacy on-premise systems.
- Retail:Omnichannel operators deploy geofencing and footfall analytics for store network optimization.
- Utilities:Grid operators and water utilities leverage spatial analytics for asset management and outage response.
By contract value, Government Agencies lead. By technology refresh rates, Transportation is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes location analytics for automotive and smart city infrastructure, while France and the Netherlands concentrate demand in logistics optimization and urban mobility applications. This consumption-mix differential shapes platform feature priorities across the region.
Germany
Federal transport digitization programs and automotive OEM requirements drive sensor network deployments for real-time traffic optimization. The KBA enforces stringent data localization standards for connected vehicle telemetry. Munich and Stuttgart clusters anchor autonomous navigation development with embedded edge computing units.
France
Fleet operators adopt location-based carbon accounting systems to comply with EU Green Deal transport decarbonization targets. The CNIL enforces divergent GDPR interpretations that fragment cross-border data architectures. Paris metropolitan authorities mandate algorithmic impact assessments before smart traffic management approvals.
Netherlands
Logistics operators and urban mobility planners consolidate vendor relationships through multi-year framework agreements bundling predictive capabilities. The Dutch Data Protection Authority prioritizes privacy-preserving federated analytics for movement pattern analysis. Rotterdam and Amsterdam harbor zones deploy real-time route recalculation for freight optimization.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for geospatial data processors serving EU and UK markets. The Information Commissioner's Office maintains distinct lawful basis interpretations for location data processing. London's financial services sector drives demand for real-time spatial inference in insurance risk modeling.
Poland
EU-Asia rail and road transit corridors generate underpenetrated demand for freight optimization platforms serving logistics operators. National data protection frameworks align with GDPR baseline requirements while permitting flexible cross-border processing arrangements. Warsaw and Łódź logistics hubs attract platform deployments for east-west freight routing.
Europe Location Data Analytics Market Competitive Landscape
Capability concentration sits with specialized mapping heritage players; scale advantage sits with hyperscale cloud providers integrating location intelligence into broader enterprise stacks. The vendor base organizes around three strategic archetypes: automotive-focused platform licensors, government-specialized GIS incumbents, and advertising-anchored API providers. Consolidation pressure intensifies as municipal procurement shifts toward multi-year service contracts. Dominant competitive moves include strategic partnerships for edge computing integration and portfolio diversification into privacy-preserving analytics architectures.
Within the automotive-focused tier, HERE Global B.V. and TomTom International B.V. occupy positions anchored by OEM relationships and real-time navigation data assets. Among government-specialized providers, Esri Global, Inc. exemplifies the desktop-to-cloud transition archetype serving European public sector clients. Microsoft Corporation represents the hyperscale integration vector, embedding location capabilities within broader enterprise cloud and productivity stacks. These three patterns illustrate how competitive positioning fragments across deployment models and end-use specializations.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Esri Global, Inc. |
| HERE Global B.V. |
| Google LLC |
| TomTom International B.V. |
| SAS Institute Inc. |
| Tableau Software LLC |
| TIBCO Software Inc. |
| QlikTech International AB |
| Others |
Pricing and Supply Chain Analysis
Munich and Stuttgart automotive clusters anchor the highest-margin platform tiers through embedded edge computing contracts, while downstream subscription compression erodes pricing power for standardized SaaS offerings. Cloud infrastructure concentration in Ireland and Luxembourg creates asymmetric leverage for hyperscale providers negotiating multi-year framework agreements with Dutch logistics operators and German federal agencies.
Pricing Analysis
Long-term framework agreements dominate municipal and federal procurement, displacing spot purchases as Dutch provinces and German agencies consolidate vendor relationships through multi-year service contracts. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM embedded systems from government SaaS bundles and retail API access tiers. Pricing pressure stems from GDPR compliance cost absorption and EU AI Act documentation requirements that vendors cannot fully pass through to public sector buyers. Transportation fleet operators exhibit highest price sensitivity due to thin margins on carbon-accounting mandates, while defense and critical infrastructure sectors accept premium positioning for sovereign data control.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized geospatial sensor producers in Germany, the Netherlands, and Taiwan, with final platform assembly and compliance certification anchored in EU jurisdictions. Raw material dependencies center on GNSS receiver chipsets, high-precision accelerometers, and edge computing processors sourced from semiconductor foundries. Single-source vulnerability concentrates in RTK-GNSS correction service providers serving precision agriculture and construction applications. Distribution runs through direct enterprise sales teams for automotive and government verticals, supplemented by cloud marketplace channels for mid-market SaaS adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Location Data Analytics sits in early-cycle expansion as federated analytics architectures unlock cross-border deployment opportunities previously blocked by GDPR fragmentation. EU Green Deal transport mandates and CSRD supply chain traceability requirements create durable demand tailwinds for emissions-monitoring and item-level tracking platforms.
For Market Incumbents: Insulate automotive OEM relationships through deeper edge computing integration and embedded processing unit co-development with Stuttgart and Munich engineering clusters. Counter hyperscale cloud encroachment by investing in privacy-preserving computation certifications that satisfy Dutch Data Protection Authority preferences for federated analytics. Prioritize compliance automation tooling to reduce EU AI Act documentation burden for French municipal government clients. For New Entrants and Emerging Players: Build out freight optimization capabilities targeting Poland and Romania logistics corridors serving EU-Asia rail and road transit routes, where incumbent platform presence remains thin. Exploit legacy system integration gaps in Italian and Spanish government agencies through API middleware solutions that bridge decades-old spatial data infrastructure with cloud-native analytics stacks. Lead with digital product passport integration as the go-to-market wedge for retail and electronics sector entry. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized federated analytics architects with GDPR-compliant cross-border processing capabilities over generalist cloud platform providers. Five-to-ten year viability hinges on regulatory moat depth rather than raw feature velocity. Target acquisition profiles center on privacy-preserving computation engineering teams with proven CNIL or German data protection authority engagement histories. Monitor Polish logistics hub platform deployment rates as the inflection signal for Eastern European demand maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Analytics Architecture Development | Enables CNIL-compliant cross-border movement pattern analysis without raw coordinate export. |
| Edge Computing Integration Partnership | Reduces latency for KBA-mandated connected vehicle telemetry localization requirements. |
| EU AI Act Conformity Assessment Investment | Accelerates Paris metropolitan authority approval for smart traffic management deployments. |
| Eastern European Logistics Corridor Expansion | Captures underpenetrated freight optimization demand across Poland and Romania transit hubs. |
| Digital Product Passport Platform Launch | Addresses CSRD-mandated supply chain traceability for retail and electronics sector buyers. |
Research Methodology
Desk research of hyperscaler capex disclosures, EU regulatory filings, and smart city procurement databases preceded structured interviews with platform engineering leads, municipal IT procurement officers, automotive OEM connected vehicle strategists, and data protection authority technical staff. Secondary validation drew from EASA unmanned aerial system regulations, EU AI Act implementation guidance, and national transport digitization program documentation. Bottom-up segment sizing triangulated against top-down market envelope estimates from cloud infrastructure deployment metrics and enterprise software spending patterns.
Assumptions held fixed include GDPR enforcement intensity at current national authority levels and EU Green Deal transport target compliance timelines; variables tested included federated analytics adoption velocity and edge computing unit cost decline curves. Segmentation dimensions modeled span deployment architecture, processing technology sophistication, application complexity, and end-user procurement maturity across the analysis window. CAGR derivation incorporated telematics event volume growth, subscription pricing elasticity, and public sector framework agreement renewal rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers or automotive-tier suppliers into federated analytics would shift outcomes substantially. Quarterly review of Polish logistics hub platform deployment rates and French algorithmic impact assessment approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Web Analytics Market
Analytics
Customer Journey Analytics Market
Analytics
Latin America Location Analytics Market
Analytics
Global Data Visualization Tools Market
Analytics
US Video Analytics Market
Analytics
Scientific Text Analytics and Annotators Market
Analytics
Global Enterprise Data Visualization Platform Market
Analytics
Global Development Analytics Tools Market
Analytics
United States Geospatial Analytics Market
Analytics
Customer Analytics in E-Commerce Market
Analytics
Marketing Analytics Market
Analytics
Asia-Pacific Mobile Analytics Market
Analytics
North America HR Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
Asia-Pacific Crowd Analytics Market