
 5G IIOT Market | 2026-2036
5G IIOT Market Size, Share, and Industry Trends Forecast 2026-2036
5G IIOT Market Outlook
Market Context
3GPP Release 16 certification for ultra-reliable low-latency communication is redrawing vendor eligibility for mission-critical deployments. Huawei Technologies Co. Ltd. leverages its end-to-end radio and core portfolio to dominate private network tenders across Asian manufacturing hubs. Nokia Corporation anchors its position through deep partnerships with European automation vendors, integrating its radio access with programmable logic controllers. Qualcomm Technologies, Inc. specializes in modem silicon and reference designs that power industrial gateways and automated guided vehicles.
Technical Definition and Structural Segments
5G Industrial Internet of Things denotes cellular connectivity infrastructure operating in licensed, shared, or unlicensed spectrum below 7 GHz and above 24 GHz, delivering sub-10 millisecond latency and 99.9999% reliability for machine-type communication. Its primary purpose is enabling deterministic control of robotics, sensors, and actuators in environments where wired Ethernet proves inflexible or cost-prohibitive. Smart Manufacturing applications currently absorb the largest deployment spending, as discrete and process industries retrofit assembly lines with wireless machine vision and collaborative robotics. Private 5G technology represents the fastest-expanding segment, driven by enterprises seeking spectrum autonomy and data sovereignty away from public carrier networks. Edge Computing integration commands premium pricing, as manufacturers co-locate compute with radio units to minimize backhaul dependency and satisfy real-time inference requirements.
Regulatory Framework and Outlook
The FCC governs spectrum allocation through CBRS and millimeter-wave auctions, while Germany's BNetzA and Japan's METI administer local 5G licenses that directly shape which vendors qualify for national critical infrastructure projects. ETSI standards for network slicing and the EU Cybersecurity Act's certification schemes determine product compliance thresholds for European industrial deployments. Stakeholders must monitor evolving national security review mechanisms that increasingly restrict vendor selection based on country-of-origin assessments rather than technical performance alone.
Market Dynamics
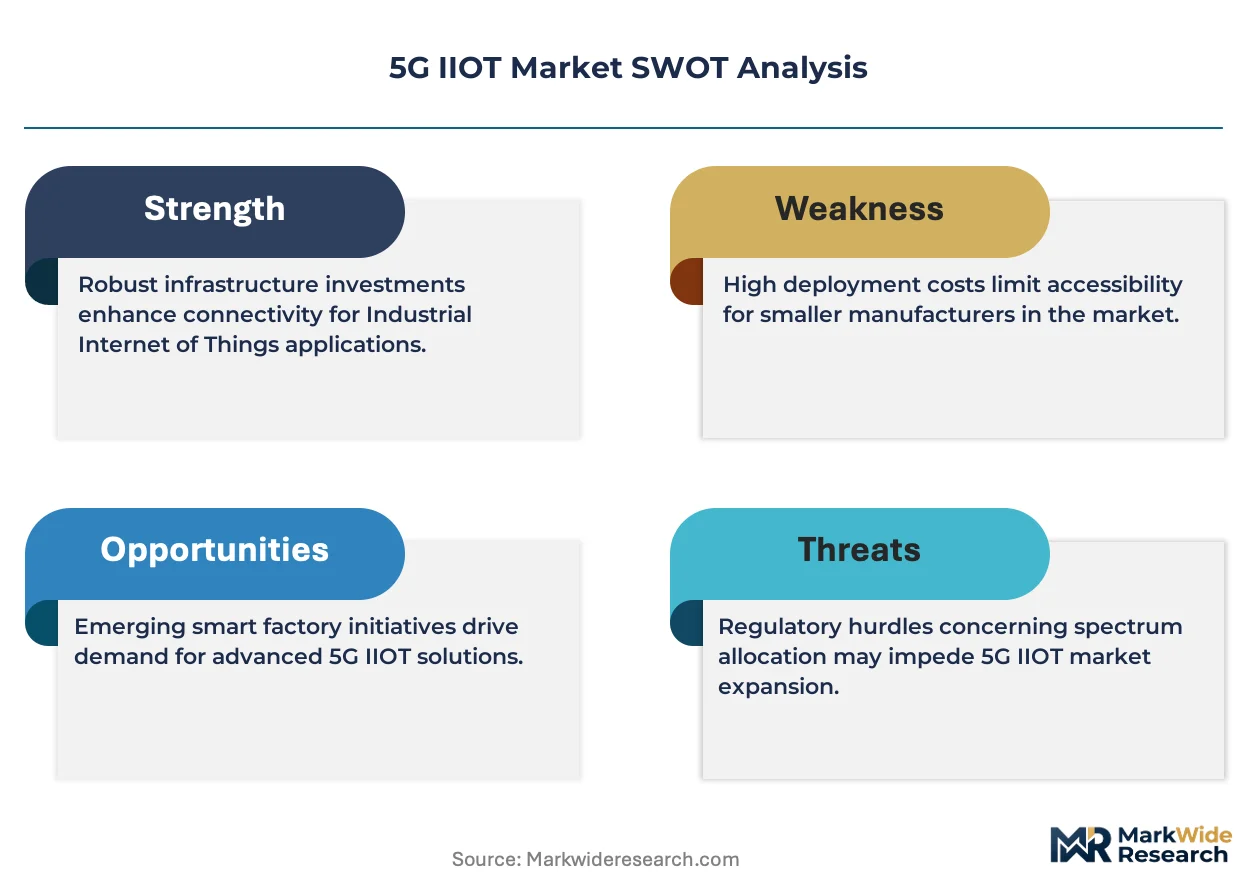
Private 5G spectrum licensing frameworks are fragmenting vendor eligibility across national security boundaries, forcing equipment buyers to qualify dual-source radio suppliers before campus network deployment.
Growth Catalysts
- Local Spectrum Licensing:Germany's BNetzA and the FCC's CBRS framework grant industrial enterprises dedicated radio frequencies, bypassing public carrier dependency for deterministic machine control.
- Release 16 URLLC Certification:3GPP's ultra-reliable low-latency communication standard enables sub-10 millisecond response times for closed-loop robotics in automotive assembly.
- Ruhr Industrial Cluster:Steel and chemical producers across North Rhine-Westphalia are commissioning campus-wide networks, creating reference architectures for process industry replication.
Market Restraints
- Radio Unit Cost Structure:Massive MIMO antenna arrays and specialized industrial-grade chipsets carry 40-60% premiums over enterprise Wi-Fi infrastructure.
- Vendor Concentration Risk:Asian semiconductor foundries dominate 5G modem silicon fabrication, exposing European manufacturers to single-source supply disruptions.
- Millimeter-Wave Propagation Limits:Above-24 GHz signals require dense small-cell deployment in metal-heavy factory environments, multiplying infrastructure spend.
Strategic Opportunities
- Edge-AI Convergence:Co-located GPU clusters with radio units enable real-time machine vision inference without cloud backhaul dependency.
- Japan's Local 5G Framework:METI licensing rules for sub-6 GHz bands open private network deployment to mid-sized precision manufacturers in Aichi and Osaka prefectures.
- Battery-Electric Vehicle Plants:Greenfield automotive facilities in Hungary and Slovakia are specifying 5G-native architectures from foundation, avoiding retrofit constraints.
Industry Challenges
- OT-IT Integration Complexity:Converging operational technology networks with enterprise IT security frameworks demands cross-functional engineering teams scarce in traditional manufacturing.
- Cybersecurity Certification Timelines:EU Cybersecurity Act's Common Criteria evaluation for critical infrastructure components extends vendor qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G IIOT Market |
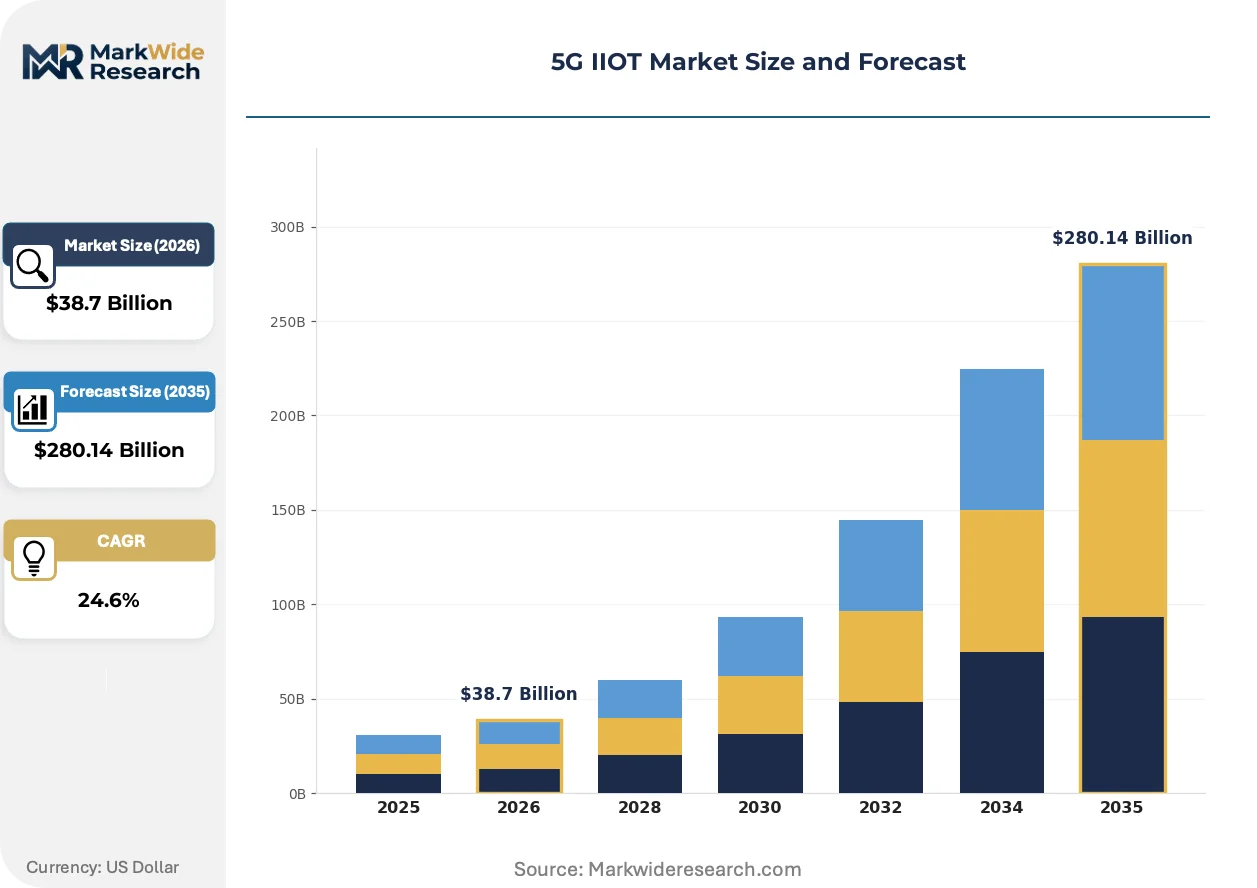
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $280.14 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Smart Manufacturing, Predictive Maintenance, Asset Tracking, Remote Monitoring End User: Oil & Gas, Agriculture, Transportation, Healthcare Technology: Edge Computing, Cloud Computing, Network Slicing, Private 5G Solution: Analytic Tools, Security Solutions, Connectivity Services, IoT Devices |
| Companies Covered | Huawei Technologies Co. Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, Qualcomm Technologies, Inc., AT&T Inc., Verizon Communications Inc., Cisco Systems, Inc., Samsung Electronics Co. Ltd., ZTE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G IIOT Market Strategic Shifts
Deterministic wireless is collapsing the boundary between fixed automation and mobile robotics, enabling production layouts that reconfigure within hours rather than months.
Time-Sensitive Networking over 5G is supplanting wired Ethernet for motion control in packaging and semiconductor handling equipment. German automotive tier-1 suppliers are piloting wireless servo drives on assembly lines previously requiring dedicated cable trays. This shift is compressing factory reconfiguration downtime from weeks to single shifts.
ETSI's network slicing specifications are mandating hard isolation between safety-critical and administrative traffic on shared infrastructure. European process industries must demonstrate slice-level fault containment to satisfy functional safety auditors. Chemical producers in Belgium and the Netherlands are pre-qualifying vendors against these certification thresholds.
Steelmakers and aluminum smelters are unbundling network infrastructure ownership from operational contracts, preferring equipment-as-a-service arrangements with guaranteed latency SLAs. This transfers radio planning and spectrum compliance risk to system integrators. The model is spreading from Nordic process industries to North American metal fabrication clusters.
5G IIOT Market Segmentation
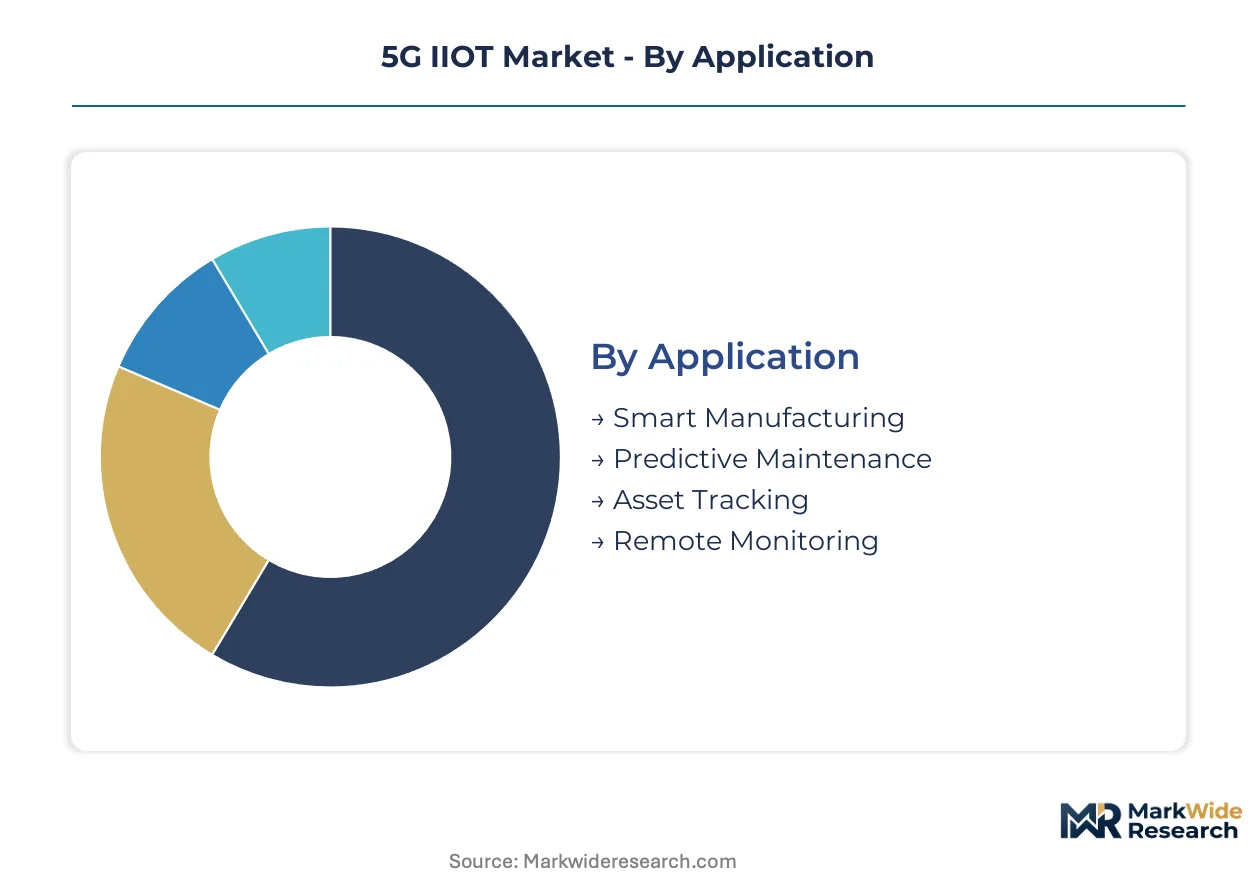
5G IIOT segmentation reveals where deterministic wireless displaces legacy infrastructure versus where it merely supplements existing connectivity. Application patterns diverge sharply between motion-control environments demanding sub-10 millisecond latency and monitoring use cases tolerating higher latency.
Application:
Substitution pressure from wired Ethernet and Wi-Fi 6E varies dramatically across deployment scenarios, with motion-control applications facing the stiffest incumbent resistance.
- Smart Manufacturing:Discrete and process industries deploy wireless machine vision and collaborative robotics on assembly lines. Automotive plants in Germany's Ruhr cluster and electronics foundries in Taiwan commission campus-wide networks for real-time machine control, bypassing cable tray constraints that slow line reconfiguration.
- Predictive Maintenance:Vibration and thermal sensors stream condition data to edge inference engines. Steel mills in Sweden and chemical complexes in Belgium prioritize this segment for its lower latency sensitivity and faster ROI demonstration compared to closed-loop control.
- Asset Tracking:RTLS tags locate mobile equipment across sprawling industrial campuses. Mining operations in Western Australia and port terminals in Rotterdam deploy this for inventory visibility without the reliability demands of safety-critical systems.
- Remote Monitoring:Environmental and security sensors transmit periodic status updates. Offshore oil platforms in the North Sea and pipeline networks in Texas utilize this for distributed infrastructure oversight where wired backhaul proves cost-prohibitive.
Smart Manufacturing anchors the volume base while Predictive Maintenance gains share at the steepest rate.
End User:
Capital intensity and operational technology maturity create distinct customer tiers with diverging procurement timelines and technical requirements.
- Oil & Gas:Upstream exploration and downstream refining operations demand explosion-proof radio units for hazardous area classification. Offshore platforms in the Gulf of Mexico and Norwegian continental shelf drive specifications for salt-spray resistant antenna arrays.
- Agriculture:Precision farming operations deploy soil sensors and autonomous machinery guidance. Large-scale grain operations in Brazil's Mato Grosso and dairy cooperatives in the Netherlands pilot private networks where cellular coverage gaps persist.
- Transportation:Ports, airports, and rail yards coordinate autonomous vehicles and cargo handling equipment. Container terminals in Singapore and freight hubs in Chicago specify 5G for yard tractor automation and crane remote operation.
- Healthcare:Hospitals and pharmaceutical manufacturing deploy wireless for asset tracking and cleanroom monitoring. Surgical robot manufacturers in Japan and sterile drug compounders in Switzerland pursue network slicing for guaranteed isolation of life-critical traffic.
Oil & Gas commands the premium pricing tier while Agriculture expands most quickly from a smaller installed base.
Technology:
Architecture choices determine whether enterprises retain data sovereignty and spectrum autonomy or delegate infrastructure to carrier partners.
- Private 5G:Dedicated radio access networks using locally licensed spectrum or CBRS priority access. German automotive suppliers and Japanese precision manufacturers favor this for deterministic control without public network dependency.
- Edge Computing:GPU and FPGA clusters co-located with radio units for millisecond-scale inference. Semiconductor packaging facilities and quality inspection stations deploy this to eliminate cloud round-trip latency.
- Network Slicing:Virtualized network partitions guaranteeing isolation between safety-critical and administrative traffic. European chemical producers pre-qualify vendors against ETSI slice-level fault containment standards.
- Cloud Computing:Centralized data processing for non-time-sensitive analytics and long-term storage. Fleet management and supply chain optimization applications utilize this for cost efficiency over latency performance.
Private 5G captures the dominant deployment share while Edge Computing climbs the fastest as AI inference demands intensify.
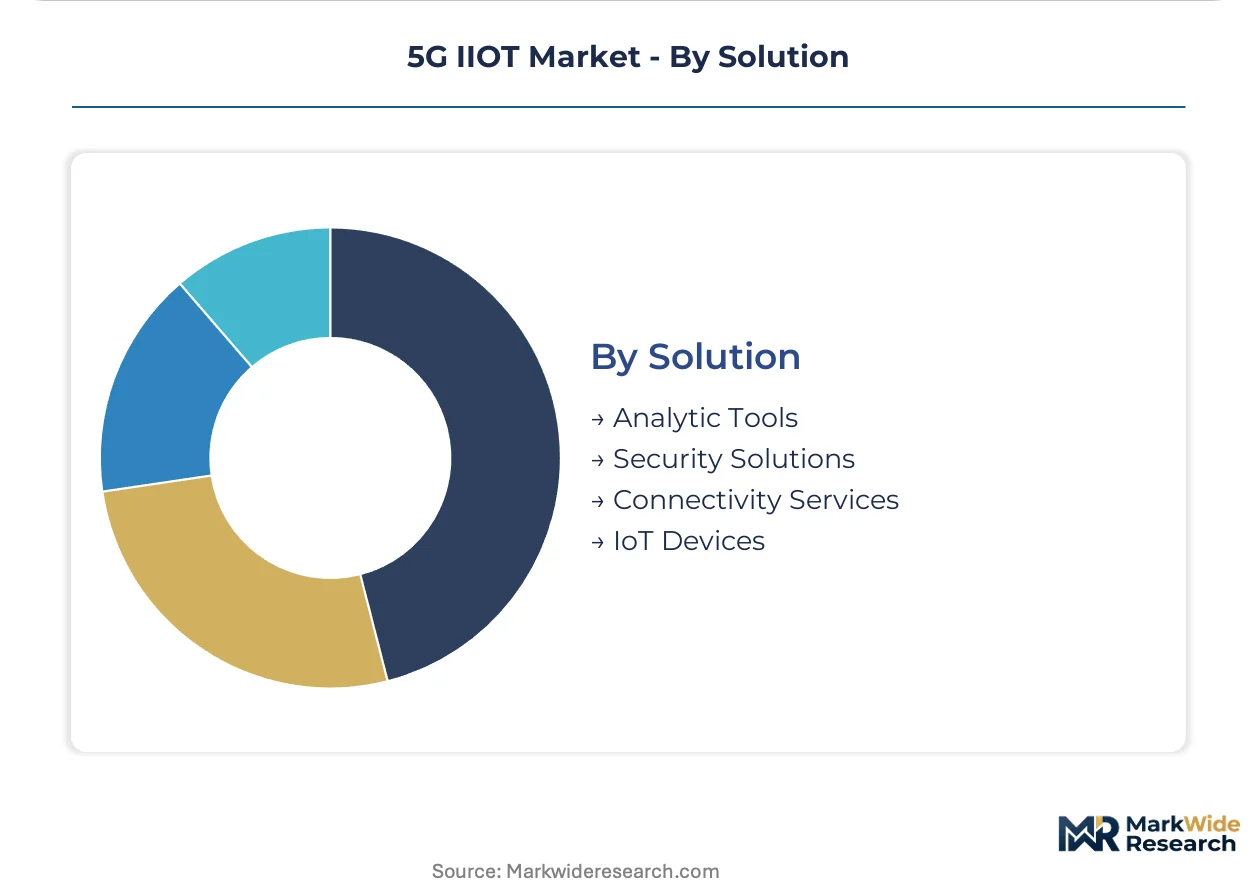
Solution:
Vendor business models fragment across hardware, software, and service components with diverging margin profiles and customer stickiness.
- Connectivity Services:Managed network operations including radio planning, spectrum compliance, and SLA-backed latency guarantees. Nordic steelmakers prefer equipment-as-a-service arrangements transferring infrastructure risk to system integrators.
- Security Solutions:Encryption, authentication, and intrusion detection tailored for operational technology environments. EU Cybersecurity Act certification requirements extend vendor qualification cycles for critical infrastructure deployments.
- Analytic Tools:Machine learning platforms for predictive maintenance and quality optimization. Automotive tier-1 suppliers integrate these with existing MES and SCADA systems.
- IoT Devices:Industrial-grade sensors, gateways, and actuators with 5G modem integration. Automated guided vehicle manufacturers and wireless servo drive suppliers drive volume in this hardware layer.
Connectivity Services generates the recurring revenue base while Security Solutions shows the steepest expansion trajectory amid regulatory compliance pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC's CBRS framework and Germany's BNetzA local licensing regime have created parallel pathways for industrial spectrum access, fragmenting vendor eligibility across national security boundaries while accelerating private network deployment in manufacturing clusters.
United States
Automotive plants in Michigan and Tennessee commission private 5G networks for real-time machine control, replacing legacy Wi-Fi on assembly lines. FCC's CBRS priority access licenses grant manufacturers dedicated 3.5 GHz spectrum without carrier dependency. Steel producers across the Great Lakes region deploy campus-wide infrastructure for wireless machine vision and collaborative robotics.
Germany
Steel, chemical, and automotive facilities in North Rhine-Westphalia's Ruhr industrial cluster drive European deployment volume. BNetzA's local 5G licensing framework permits enterprises to operate dedicated radio access networks for deterministic control. Automotive tier-1 suppliers in Baden-Württemberg pilot wireless servo drives previously requiring dedicated cable trays.
Japan
Precision manufacturers in Aichi and Osaka prefectures leverage METI's local 5G framework for sub-6 GHz private network deployment. Surgical robot manufacturers pursue network slicing specifications for guaranteed isolation of life-critical traffic. Semiconductor packaging facilities in Kyushu co-locate GPU clusters with radio units for millisecond-scale inference.
China
Electronics foundries in Shenzhen and Dongguan commission campus-wide networks for automated guided vehicle coordination. MIIT spectrum policies shape vendor qualification for critical infrastructure projects. Steel producers in Hebei province deploy condition monitoring sensors across sprawling industrial campuses for predictive maintenance applications.
South Korea
Memory semiconductor fabricators in Gyeonggi Province specify 5G-native architectures for cleanroom automation and equipment coordination. Government-backed smart factory initiatives accelerate private network adoption among mid-sized component suppliers. Battery cell manufacturers in Chungcheong Province integrate edge computing with radio units for real-time quality inspection.
5G IIOT Market Competitive Environment
Player mix skews toward integrated infrastructure vendors with end-to-end radio and core portfolios alongside specialized modem silicon suppliers. Market structure concentrates around three strategic archetypes: Asian equipment vendors leveraging manufacturing scale, European specialists embedding automation partnerships, and American semiconductor designers powering industrial gateways. Dominant competitive moves include spectrum-autonomy positioning for data sovereignty and edge-AI convergence to eliminate cloud backhaul dependency.
Within the integrated infrastructure tier, Huawei Technologies Co. Ltd. and Nokia Corporation exemplify contrasting geographic anchoring strategies shaped by national security review mechanisms. Qualcomm Technologies, Inc. occupies a specialist position in modem silicon and reference designs. ZTE Corporation and Samsung Electronics Co. Ltd. sit within the Asian manufacturing hub cluster, while Telefonaktiebolaget LM Ericsson represents European automation integration approaches. AT&T Inc. and Verizon Communications Inc. anchor carrier-led managed service models against enterprise-owned private network alternatives.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Qualcomm Technologies, Inc. |
| AT&T Inc. |
| Verizon Communications Inc. |
| Cisco Systems, Inc. |
| Samsung Electronics Co. Ltd. |
| ZTE Corporation |
| Others |
Value Chain & Pricing Dynamics
Equipment-as-a-service contracts with guaranteed latency SLAs lock in both radio unit supply access and multi-year price visibility for steelmakers and aluminum smelters transferring infrastructure risk to system integrators.
Pricing Analysis
Certification level under the EU Cybersecurity Act and FCC equipment authorization creates the primary spread between premium and standard tiers. Three-tier pricing structure across mission-critical, industrial-grade, and commercial levels reflects differential testing burdens and documentation requirements. Cost compression in the commercial tier intensifies because Asian modem silicon suppliers are scaling reference designs for gateway manufacturers. Mid-sized precision manufacturers in Japan's Aichi prefecture exhibit the highest price sensitivity, while German automotive tier-1 suppliers in Baden-Württemberg prioritize guaranteed latency SLAs over unit economics.
Supply Chain Analysis
Radio unit inventory cycles stretch 16-24 weeks for massive MIMO arrays as Taiwanese and South Korean foundries prioritize automotive and smartphone modem allocations. 5G IIOT infrastructure draws from concentrated semiconductor fabrication in Taiwan, South Korea, and mainland China, with specialized industrial-grade chipsets sourcing from a narrower supplier base than consumer equivalents. Single-source vulnerability in sub-6 GHz power amplifier modules exposes European system integrators to allocation decisions by Asian component vendors. Distribution runs through carrier-managed service partnerships and direct enterprise sales channels, with the latter gaining share as local spectrum licensing expands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
5G IIOT is approaching a platform-economics inflection where ETSI network slicing specifications and 3GPP Release 16 interoperability collapse proprietary radio vendor lock-in, enabling multi-vendor campus deployments.
For Market Incumbents: Shield core radio access network revenue by deepening automation vendor partnerships in Germany's Ruhr cluster and Japan's precision manufacturing belt. Accelerate EU Cybersecurity Act pre-certification for critical infrastructure components before qualification cycles extend further. Prioritize edge-AI convergence roadmaps that co-locate GPU clusters with radio units to eliminate cloud backhaul dependency and raise switching costs. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Belgium and the Netherlands opens European chemical producer accounts before incumbent qualification cycles complete. Target predictive maintenance applications in Nordic steel mills where latency sensitivity is lower and ROI demonstration cycles compress. Pursue equipment-as-a-service financing structures that transfer spectrum compliance risk from capital-constrained mid-sized manufacturers. For Investors and Strategic Acquirers: Capital is best deployed toward edge computing specialists with GPU-FPGA co-location capabilities and existing radio unit integration experience. Long-term viability across the analysis window hinges on spectrum autonomy positioning as national security review mechanisms fragment vendor eligibility by country-of-origin. Watch for BNetzA and FCC local licensing volume acceleration as the signal that private network deployment is shifting from pilot to production scale.| Strategic Initiative | Industry Significance |
|---|---|
| Private 5G Spectrum Acquisition | BNetzA and FCC local licenses grant German and US manufacturers deterministic control without carrier dependency. |
| Edge-AI Infrastructure Convergence | Co-located GPU clusters with radio units enable Kyushu semiconductor facilities to eliminate cloud round-trip latency. |
| ETSI Network Slicing Certification | Slice-level fault containment pre-qualification opens Belgian and Dutch chemical producer accounts to new vendors. |
| Automation Vendor Partnership Deepening | Integration with programmable logic controllers anchors Nokia's position in European automotive tier-1 supplier accounts. |
| Equipment-as-a-Service Model Expansion | Guaranteed latency SLA contracts transfer radio planning risk from Nordic steelmakers to system integrators. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with private network deployment leads at automotive OEMs, automation engineering directors, spectrum licensing officers at BNetzA and FCC, and system integrator program managers; and secondary validation against 3GPP release documentation, ETSI network slicing specifications, EU Cybersecurity Act certification databases, and national spectrum auction records. Bottom-up triangulation of deployment project counts across Germany's Ruhr cluster, US Great Lakes manufacturing belt, and Japan's Aichi-Osaka corridor was cross-checked against top-down infrastructure spend estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including application latency requirements, spectrum access modality, edge computing integration depth, and vendor geographic eligibility shaped by national security review mechanisms. CAGRs were derived from deployment velocity curves in private manufacturing networks versus carrier-managed alternatives. Forecast inputs incorporated MIIT spectrum policy shifts in China and METI local 5G licensing volume in Japan.
Decision-makers should treat outputs as directional under assumptions of continued local spectrum licensing expansion and stable 3GPP standardization timelines; material deviation in regulatory restriction severity or semiconductor supply allocation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Narrowband IoT Enterprise Application Market
Internet of Things (IoT)
Connected IoT Devices Market
Internet of Things (IoT)
Smart Remote Market
Internet of Things (IoT)
Internet of Medical Things (Iomt) Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Global Military IoT Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
US Smart Thermostat Market
Internet of Things (IoT)
Cellular Machine to Machine Market
Internet of Things (IoT)
Wireless Connected Devices Market
Internet of Things (IoT)
Global IOT Gateway Market
Internet of Things (IoT)
IoT Device Management Platform Market
Internet of Things (IoT)
Aviation IoT Solutions Market
Internet of Things (IoT)
Global Narrowband IoT Market
Internet of Things (IoT)
IoT Monetization Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market