
 Global Application Development Software Market | 2026-2036
Global Application Development Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Development Software Market Foresight
India's software engineering capacity build-out is tilting the competitive balance toward Asia-Pacific delivery centers. Microsoft Corporation leverages its Azure cloud ecosystem to anchor enterprise application development workflows across hybrid environments. Oracle Corporation competes through database-integrated development suites that sustain high switching costs among Fortune 500 clients. SAP SE specializes in industry-specific low-code templates that dominate manufacturing and supply chain verticals.
Application development software encompasses integrated toolchains for designing, coding, testing, deploying, and maintaining software applications across enterprise environments, typically incorporating CI/CD pipelines, version control systems, and runtime monitoring with sub-100ms deployment feedback loops. Its primary commercial purpose is reducing time-to-market for digital products while standardizing quality assurance across distributed engineering teams. Cloud-based deployment now captures the largest revenue pool as enterprises abandon capital-intensive on-premises infrastructure, while low-code platforms represent the fastest-expanding solution type by democratizing development beyond traditional IT departments. DevOps tools command premium pricing due to their critical role in automating release cycles and reducing production incident rates.
The EU AI Act and GDPR impose strict algorithmic accountability and data residency requirements that shape platform architecture decisions across European deployments. The SEC's cybersecurity disclosure rules and the US Federal Risk and Authorization Management Program (FedRAMP) create compliance barriers that filter vendor eligibility for government and financial services contracts. Stakeholders must monitor how fragmented regulatory timelines across Washington, Brussels, and Beijing reshape cloud sovereignty requirements and cross-border data flow architectures.
Market Dynamics
Cloud migration mandates from the US Federal Risk and Authorization Management Program (FedRAMP) and the EU AI Act's algorithmic transparency requirements are compressing procurement cycles while fragmenting vendor eligibility across sovereign data zones.
Growth Catalysts
- Low-code democratization:Manufacturing and supply chain departments now build internal applications without IT gatekeeping, expanding addressable seats beyond traditional developer populations.
- EU AI Act compliance:European enterprises face mandatory documentation and audit trails for algorithmic systems, forcing replacement of shadow IT development tools with governed platforms.
- India:Engineering capacity expansion across Bangalore and Hyderabad delivery centers reduces per-seat development costs for Western enterprises outsourcing application maintenance.
Market Restraints
- Cloud concentration risk:Three hyperscale providers control the infrastructure layer beneath most development platforms, creating single-point-of-failure exposure for CI/CD pipelines.
- GDPR data residency:European data localization requirements fragment development environments, forcing redundant tooling investments across regional instances.
- Technical debt accumulation:Legacy COBOL and mainframe systems in US banking and insurance resist API-layer abstraction, slowing modernization ROI.
Strategic Opportunities
- Brazil and Mexico:Nearshore delivery centers capture US enterprise outsourcing as geopolitical friction reduces China and Russia vendor viability.
- Edge computing convergence:5G network slicing and container orchestration enable sub-50ms application deployment for autonomous vehicle and industrial IoT use cases.
- US Inflation Reduction Act:Domestic manufacturing reshoring incentives drive demand for supply chain visibility applications with embedded carbon accounting.
Industry Challenges
- Platform engineering skill scarcity:Organizations lack internal expertise to configure internal developer platforms (IDPs), creating implementation bottlenecks despite tool availability.
- ISO 27001 certification timelines:Security framework audits delay go-live dates for financial services deployments by six to nine months.
- Multi-cloud integration complexity:Enterprises running workloads across AWS, Azure, and Google Cloud struggle with inconsistent API implementations and credential management sprawl.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Development Software Market |
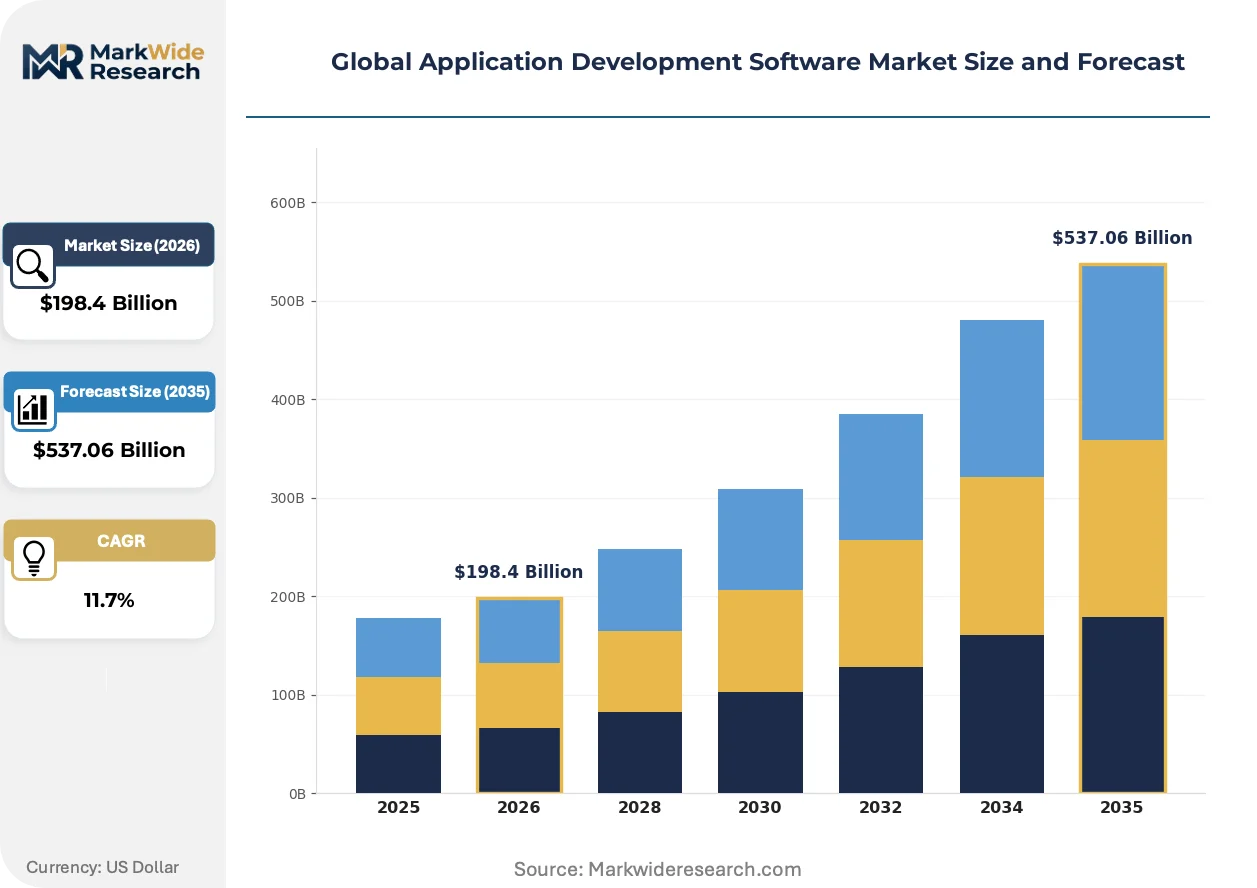
| Market Size in 2026 | $198.4 Billion |
| Market Size in 2035 | $537.06 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid Cloud, Multi-Cloud Solution Type: Low-Code Platforms, Integrated Development Environments, Application Lifecycle Management, DevOps Tools End User Industry: Banking, Telecommunications, Manufacturing, Government Agencies License Model: Subscription, Perpetual, Freemium, Open Source, Enterprise |
| Companies Covered | Microsoft Corporation, Oracle Corporation, IBM Corporation, SAP SE, Salesforce, Inc., Google LLC, HCL Technologies Limited, Fujitsu, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Development Software Market Shifts & Advancements
Generative coding assistants and sovereign cloud architectures are redrawing competitive boundaries between integrated suites and best-of-breed toolchains. Vendors race to embed compliance automation directly into deployment pipelines.
GitHub Copilot and Amazon CodeWhisperer embed large language models directly into integrated development environments, suggesting context-aware code completions from natural language prompts. Enterprise engineering teams at US financial institutions and German automotive manufacturers adopt these tools fastest, measuring productivity through commit velocity and pull request cycle time. Generative assistance is hybridizing the roles of junior developers and senior architects, compressing onboarding timelines while raising code review standards.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes application categories including credit scoring and biometric identification. Platform vendors must implement model registries, bias detection pipelines, and human-in-the-loop approval gates to maintain European market access. Banking and insurance software procurement in Germany, France, and the Netherlands now requires explicit algorithmic impact assessments as standard contract terms.
Platform engineering teams increasingly self-serve infrastructure through internal developer portals rather than submitting tickets to centralized IT. Spotify's Backstage model propagates through US technology and fintech companies, replacing traditional service desk workflows with golden path templates and automated environment provisioning. This consumption pattern shift concentrates purchasing authority with platform engineering directors rather than enterprise architecture committees, shortening sales cycles but demanding deeper technical integration from vendors.
Global Application Development Software Market Segmentation
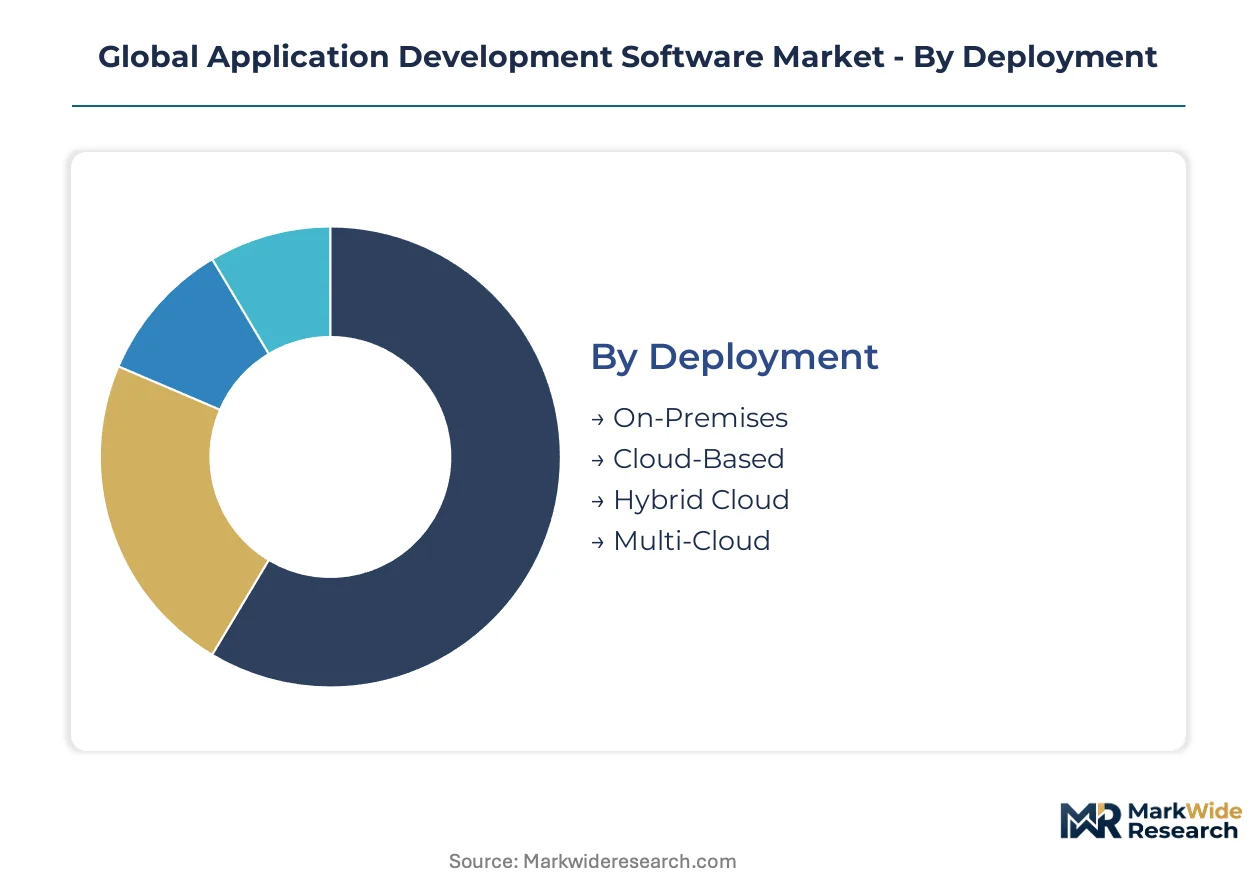
Application development software segments diverge sharply by infrastructure ownership, governance requirements, and buyer technical sophistication. Procurement patterns cluster around cloud maturity stages and regulatory exposure rather than company size alone.
Deployment:
Mature cloud adoption dominates enterprise procurement, while emerging sovereign data architectures reshape infrastructure decisions.
- On-Premises:Legacy installations persist in defense contracting and classified government systems where air-gapped environments are mandatory. German automotive manufacturers and US defense primes maintain captive data centers for IP protection and FedRAMP High compliance.
- Cloud-Based:Public cloud delivery captures the majority of new seat growth as enterprises abandon capital-intensive server refresh cycles. US financial services firms and Indian IT services exporters drive volume through elastic consumption models that align software spend with project delivery milestones.
- Hybrid Cloud:Workload portability between private infrastructure and public cloud enables phased migration for regulated industries. Japanese manufacturing conglomerates and French banking groups deploy hybrid stacks to satisfy data residency while accessing cloud-native development tools.
- Multi-Cloud:Distributing development environments across AWS, Azure, and Google Cloud reduces vendor lock-in but introduces integration complexity. US technology companies and German industrial software vendors adopt multi-cloud strategies to negotiate pricing and ensure continuity.
Cloud-Based handles the majority of throughput; Multi-Cloud is climbing the fastest on share.
Solution Type:
Cost tier differentiation separates premium integrated suites from accessible point solutions.
- Low-Code Platforms:Visual development interfaces enable business analysts to assemble applications without traditional coding. Manufacturing operations teams in the United States and supply chain managers in Germany adopt these tools to bypass IT backlogs for internal workflow automation.
- Integrated Development Environments:Full-featured code editors with debugging, profiling, and version control integration remain essential for professional software engineering. Indian software services firms and US technology companies standardize on IDE-centric workflows for complex system development.
- Application Lifecycle Management:Requirements tracking, test management, and release coordination tools govern regulated development processes. Medical device manufacturers in the United States and automotive suppliers in Germany require ALM suites for FDA and KBA audit trails.
- DevOps Tools:CI/CD pipelines, infrastructure-as-code, and observability platforms automate deployment velocity. US fintech startups and Brazilian digital banks invest heavily in DevOps tooling to compress release cycles and reduce production incident rates.
Integrated Development Environments anchor professional developer spend; Low-Code Platforms are expanding most quickly.
End User Industry:
Application intensity varies by digital transformation maturity and legacy system burden.
- Banking:Core system modernization and regulatory reporting automation drive sustained platform investment. US regional banks and EU institutions under ECB supervision prioritize compliant toolchains for stress testing and anti-money laundering systems.
- Telecommunications:Network function virtualization and customer experience platforms require continuous software iteration. Indian mobile operators and US cable providers deploy development platforms to manage 5G service orchestration and billing system upgrades.
- Manufacturing:Industrial IoT integration and supply chain visibility applications connect factory floor data to enterprise systems. German automotive OEMs and Japanese precision equipment makers lead adoption of edge-connected development environments.
- Government Agencies:Citizen service portals and internal efficiency applications modernize public sector operations. US federal agencies under FedRAMP mandates and Indian state governments digitizing land records represent distinct procurement patterns.
Banking commits the largest absolute spend; Government Agencies are gaining share fastest.
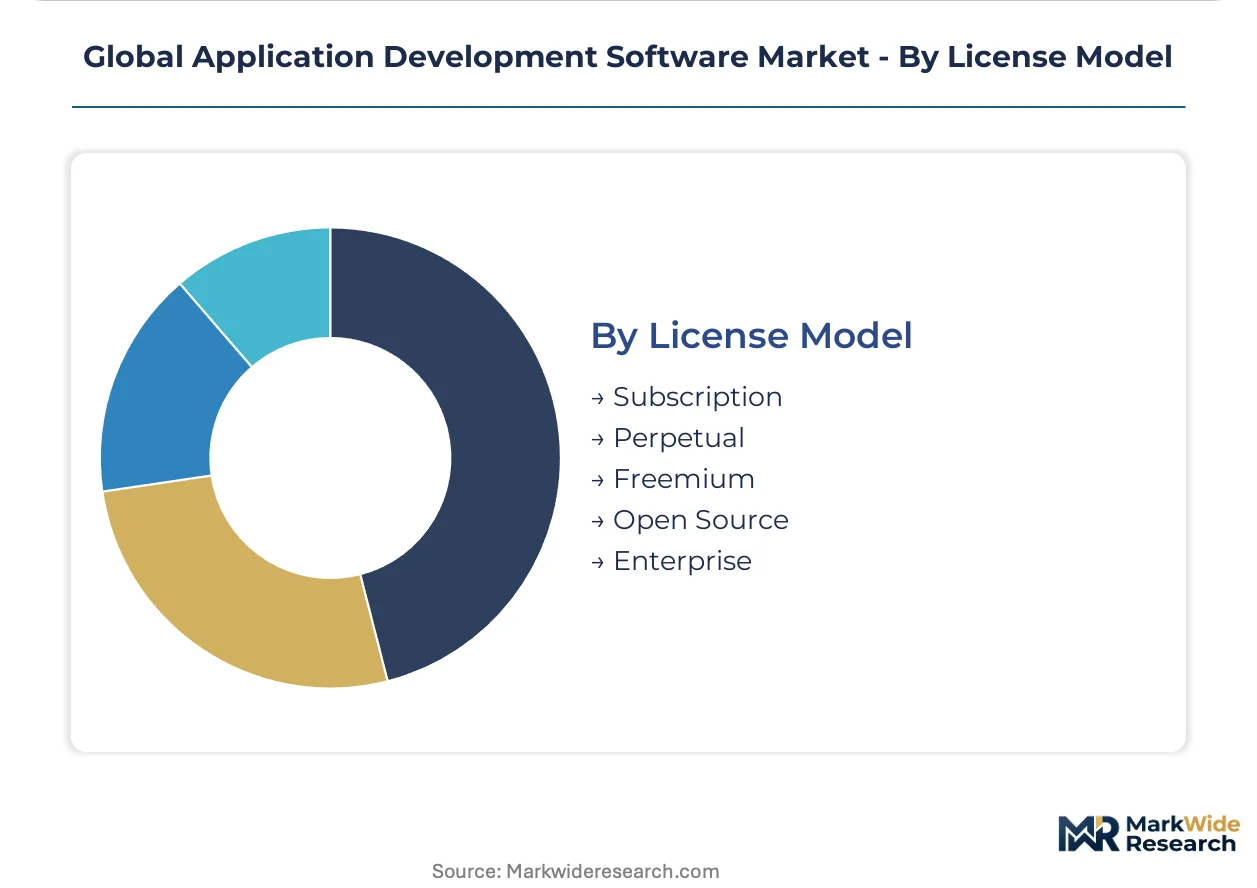
License Model:
Customer type and procurement authority determine pricing architecture preferences.
- Subscription:Recurring revenue models align vendor success with customer retention through continuous feature delivery. US enterprise software buyers and EU mid-market companies favor subscriptions for predictable budgeting and automatic security updates.
- Perpetual:One-time purchase with maintenance contracts persists in capital-budget-driven organizations. Japanese industrial conglomerates and some US defense contractors prefer asset ownership for multi-year depreciation schedules.
- Freemium:Tiered entry points convert individual developers and small teams to paid tiers. Independent developers in India and startup founders in Brazil build initial products on free tiers before scaling to enterprise licenses.
- Open Source:Community-licensed tools with commercial support options reduce licensing friction. European public sector bodies and US academic research institutions standardize on open source to ensure auditability and avoid vendor lock-in.
- Enterprise:Custom-negotiated agreements with dedicated support, SLAs, and professional services attach. Fortune 500 companies in the United States and large EU banking groups negotiate enterprise terms for standardized global deployments.
Subscription captures the dominant revenue pool; Open Source is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FedRAMP compliance mandates from the SEC and US federal procurement rules concentrate platform investment authority in Washington and New York financial centers. Enterprises across Germany, India, Japan, and the United Kingdom face divergent regulatory timelines that fragment cloud sovereignty architectures.
United States
Banking modernization budgets and defense contracting requirements drive procurement velocity. FedRAMP High authorization filters vendor eligibility for federal cloud deployments. Seattle and San Francisco Bay Area technology clusters anchor hybrid development platform adoption across Fortune 500 enterprises.
Germany
Automotive supply chain digitization and industrial IoT integration sustain platform demand. KBA documentation requirements and EU AI Act algorithmic audits reshape procurement specifications for credit scoring applications. Munich and Stuttgart engineering centers concentrate low-code manufacturing adoption.
India
IT services export capacity and domestic startup formation expand addressable developer populations. RBI data localization guidelines and SEBI cybersecurity mandates govern financial services tooling procurement. Bangalore and Hyderabad delivery centers reduce per-seat costs for Western enterprise outsourcing contracts.
Japan
Manufacturing conglomerate legacy system modernization and 5G network deployment create tooling demand. METI data governance guidelines and JIS standards compliance shape platform selection criteria. Tokyo and Nagoya industrial software clusters drive edge computing convergence for factory automation.
United Kingdom
Fintech regulatory sandbox participation and open banking API mandates accelerate development platform procurement. FCA operational resilience requirements and GDPR data residency rules constrain cloud architecture decisions. London financial technology corridors concentrate DevOps tooling investment among digital banks.
Global Application Development Software Market Competitive Landscape
Hyperscale cloud providers and enterprise software incumbents split the market through divergent integration strategies. Consolidation pressure intensifies as procurement authority shifts from central IT committees to platform engineering directors. Three archetypes dominate: cloud-native toolchains anchored to infrastructure ecosystems, database-integrated suites sustaining high switching costs, and low-code platforms democratizing development beyond traditional engineering functions. Competitive moves concentrate on M&A for specialized compliance capabilities and strategic partnerships for sovereign cloud deployments.
Within the cloud-native toolchain tier, Microsoft Corporation and Google LLC exemplify infrastructure-anchored positioning, while Oracle Corporation occupies a position within the database-integrated suite archetype. These entities represent contrasting strategic bets on where platform value accumulates—at the infrastructure layer versus the data management layer—shaping how enterprise buyers evaluate total cost of ownership across multi-year deployment horizons.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| IBM Corporation |
| SAP SE |
| Salesforce, Inc. |
| Google LLC |
| HCL Technologies Limited |
| Fujitsu |
| ServiceNow |
| Others |
Supply & Pricing Matrix
Undercapacity in Indian engineering delivery centers tightens per-seat pricing for Western outsourcing contracts while compressing margins for platform vendors competing on cost. This utilization squeeze feeds back into supplier consolidation as smaller toolchain providers exit price-sensitive tiers.
Pricing Analysis
Geographic price spreads of 40-60% separate US enterprise subscriptions from Indian IT services procurement. The market runs on a SaaS-tiered subscription model with premium-mid-economy pricing differentiation anchored to FedRAMP certification levels. Price compression in the economy tier stems from open-source alternatives and hyperscale bundling. Indian IT services exporters exhibit highest price sensitivity; US federal contractors show lowest due to compliance-driven vendor lock-in.
Supply Chain Analysis
US export controls on advanced AI training infrastructure limit flows of high-performance compute to Chinese and Russian development environments. Supply concentrates in the United States for cloud-native platforms, India for services delivery capacity, and Germany for industrial compliance-integrated suites. The chain draws from semiconductor foundries in Taiwan, open-source repositories, and hyperscale data center infrastructure. Single-source vulnerability runs through AWS, Azure, and Google Cloud control of underlying compute. Distribution runs through direct enterprise sales with channel partners penetrating mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
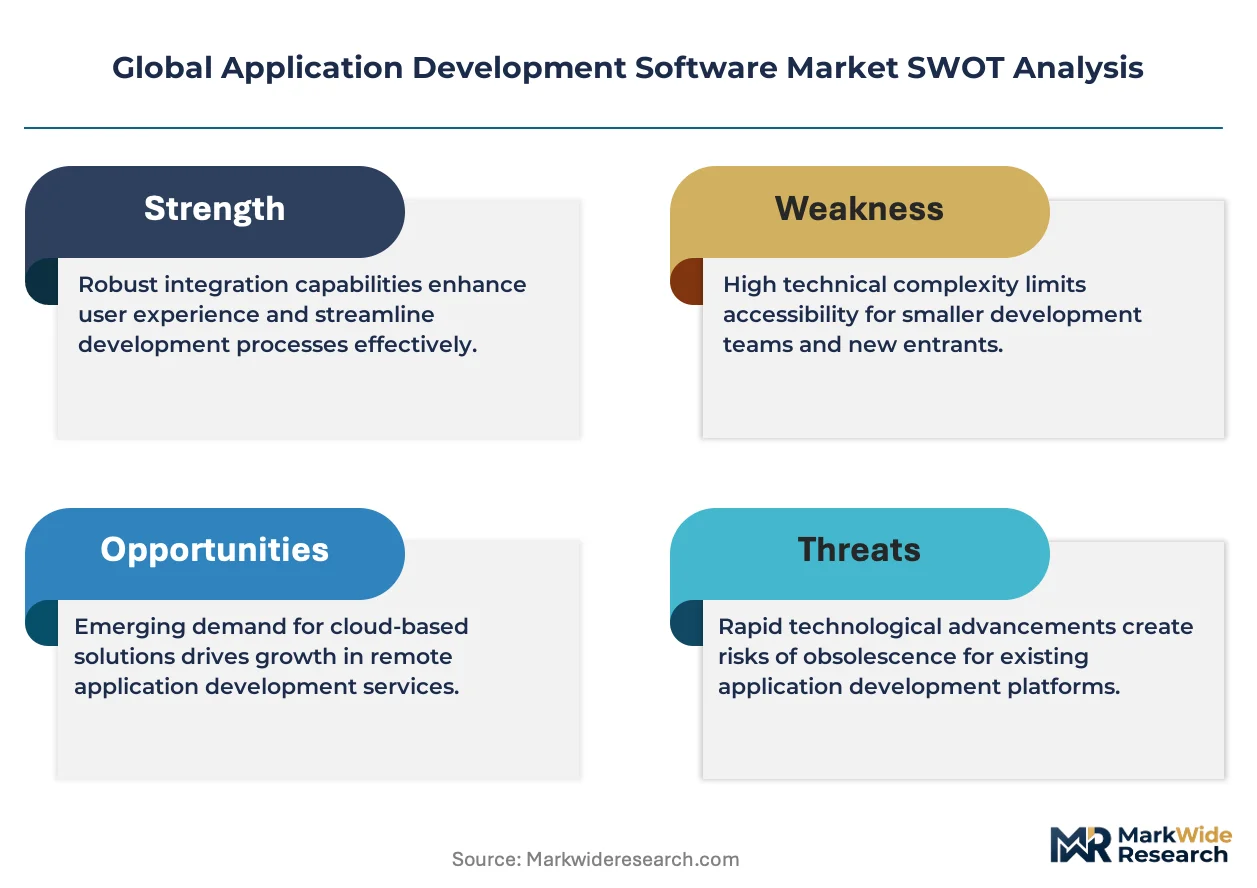
This market functions as a defensive-moat story where regulatory entrenchment creates durable competitive positions. FedRAMP, GDPR, and EU AI Act compliance requirements erect barriers that compound over time.
For Market Incumbents: Build switching-cost moats through deeper integration into customer CI/CD pipelines and compliance automation layers. Incumbents should acquire specialized algorithmic audit firms to embed EU AI Act documentation directly into deployment workflows. Capacity addition in Indian delivery centers captures cost-sensitive outsourcing demand before regional challengers consolidate. For New Entrants and Emerging Players: Pursue white-space targets in Brazilian and Mexican nearshore delivery centers as geopolitical friction reduces China and Russia vendor viability. The most penetrable segment comprises manufacturing operations teams seeking low-code tools for supply chain visibility applications. A vertical-specific go-to-market angle targeting carbon accounting modules for US Inflation Reduction Act compliance unlocks faster sales cycles than horizontal platform competition. For Investors and Strategic Acquirers: Capital is best deployed toward compliance-automation specialists with embedded regulatory workflows rather than generic development toolchains. Long-term viability across the projection horizon favors vendors with sovereign cloud partnerships and multi-cloud orchestration capabilities. The signal to watch is FedRAMP authorization velocity as a proxy for federal market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding CI/CD pipelines into Azure and AWS ecosystems locks in enterprise workflows. |
| Acquisition of Specialist Firm | Buying algorithmic audit vendors accelerates EU AI Act compliance productization. |
| Strategic Partnership | Sovereign cloud alliances with European telecom operators satisfy data residency mandates. |
| Geographic Expansion | Brazilian and Mexican delivery centers capture US nearshore outsourcing migration. |
| Product Launch | Carbon accounting modules align with US Inflation Reduction Act manufacturing incentives. |
Research Methodology
Desk research of hyperscaler capex disclosures, SEC 10-K filings, and EU regulatory databases preceded structured interviews with platform engineering directors, IT procurement officers, CTOs at financial services firms, and compliance leads at German automotive manufacturers. Primary fieldwork combined with secondary validation from open-source repository analytics and cloud vendor revenue segment reporting. Bottom-up seat-count modeling and top-down enterprise IT spend allocation were triangulated to converge on market estimates.
Assumptions held FedRAMP authorization timelines and EU AI Act implementation schedules fixed while varying cloud adoption curves and low-code penetration rates across verticals. The analytical framework segmented by deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived from elastic demand modeling against IT budget growth elasticities. Industry-specific forecast inputs included hyperscaler infrastructure expansion plans and Indian IT services headcount projections.
Sensitivities concentrate around regulatory timeline acceleration, sovereign cloud mandate expansion, and generative coding assistant adoption curves. Forecasts reflect these assumptions without claiming precision on timing. Material shifts in US-China technology decoupling intensity or EU AI Act enforcement rigor would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Document Control Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Content Services Platforms Market
Software & Services
North America Automotive Software Market
Software & Services
Supply Chain Management (SCM) Software Market
Software & Services
Global Archiving Software Market
Software & Services
Scanning and Migration Software Market
Software & Services
Android Emulator Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Automation Test Software Market
Software & Services
Global Brain Training Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Digital Painting Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
Background Removal Software Market