
 Sea Water Injection Pumps Market | 2026-2036
Sea Water Injection Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Water Injection Pumps Market Analytics
Modular skid packaging is decoupling pump procurement from integrated EPC contracts, letting operators source sea water injection pumps separately from balance-of-plant equipment. Baker Hughes leverages its subsea systems heritage to anchor long-term service agreements. Flowserve Corporation sustains aftermarket revenue through dedicated corrosion-resistant alloy foundries. Schlumberger Limited competes via digital twin integration across its OneSubsea platform.
Sea water injection pumps are high-pressure fluid handling machines engineered to deliver filtered seawater into hydrocarbon reservoirs for pressure maintenance and enhanced oil recovery, typically constructed from super-duplex stainless steel or nickel-aluminum bronze to withstand chloride-induced pitting at discharge pressures exceeding 200 bar. Centrifugal pumps dominate brownfield retrofit budgets due to proven reliability in high-volume low-viscosity service. Positive displacement pumps occupy niche high-pressure low-flow applications where multiphase tolerance justifies capital premiums. Electromechanical drive configurations lead newbuild installations as platform electrification displaces gas turbine-driven alternatives.
API 610 and ISO 5199 govern hydraulic performance and mechanical runout tolerances for offshore pump installations, while NORSOK M-001 and NACE MR0175/ISO 15156 dictate material selection for sour service exposure in the North Sea and Middle East respectively. Brazil's national petroleum regulator enforces local content thresholds that shape supplier qualification for pre-salt field developments. Stakeholders must monitor evolving corrosion allowance standards and platform electrification roadmaps to align product development with operator decarbonization commitments.
Market Dynamics
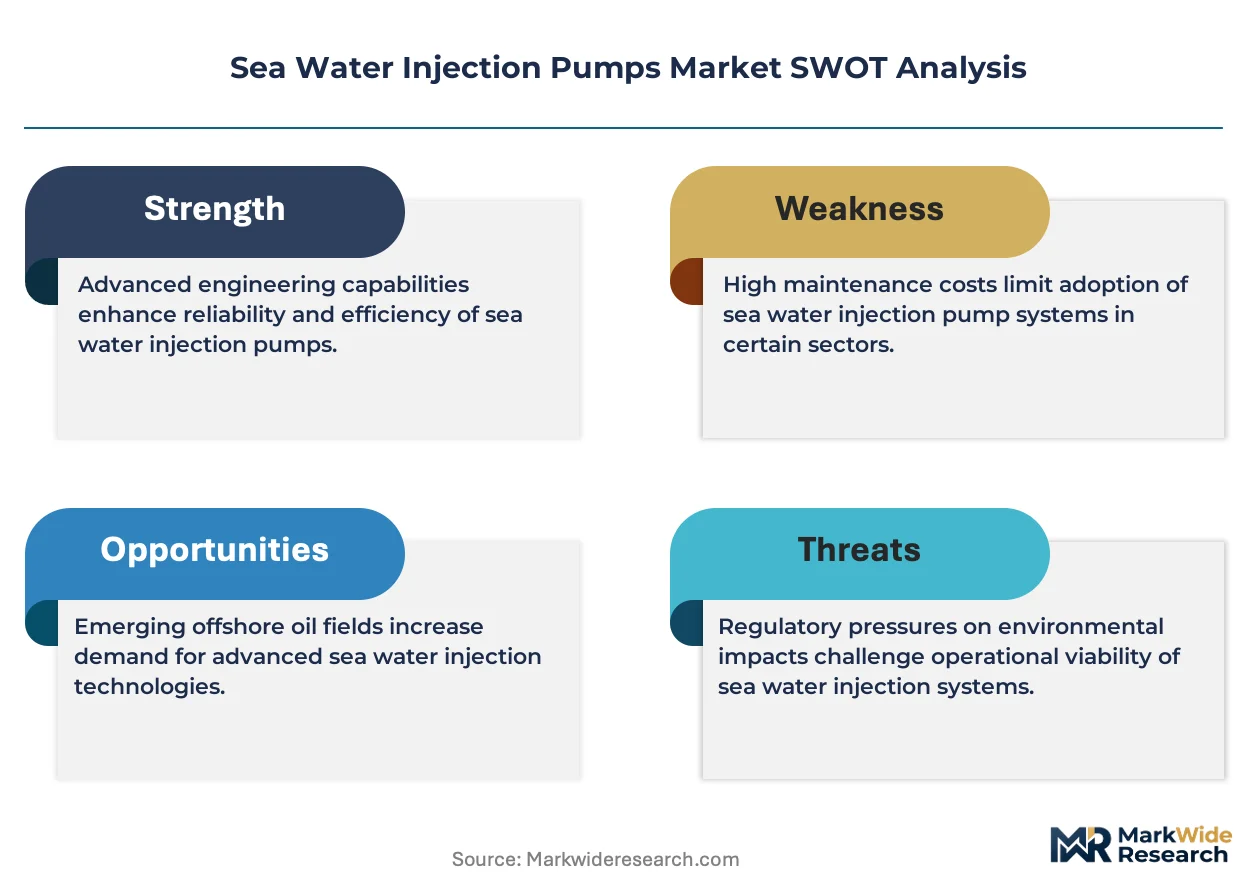
Platform electrification roadmaps across offshore basins are forcing a generational replacement cycle in drive systems, with operators retiring gas turbine-driven pumps ahead of mechanical end-of-life to meet Scope 1 reduction targets tied to lender sustainability covenants.
Growth Catalysts
- Mature field revitalization programs:Brazil's national petroleum regulator mandates local content thresholds for pre-salt developments, accelerating pump procurement for pressure maintenance in declining reservoirs.
- API 610 compliance upgrades:North Sea operators face NORSOK M-001 corrosion allowance revisions that trigger wholesale pump replacement cycles in installations exceeding twenty years of service.
- Super-duplex stainless steel casting capacity:Dedicated foundry investments in Norway and Saudi Arabia are compressing lead times for high-pressure pump components rated above 200 bar discharge pressure.
Market Restraints
- Nickel price volatility:Super-duplex alloy feedstock costs fluctuate with Indonesian ore export quotas, squeezing foundry margins and forcing pass-through clauses in long-term supply agreements.
- Single-source forging concentration:Large-diameter pump shafts above 500mm depend on a concentrated German-Japanese supplier base, creating vulnerability to geopolitical trade friction.
- Positive displacement substitution ceiling:Multiphase pump technology limits addressable market expansion for conventional sea water injection pumps in high-gas-fraction reservoirs.
Strategic Opportunities
- Modular skid packaging unbundling:Operators in Norway now source pumps separately from balance-of-plant equipment, opening direct procurement channels previously captured by integrated EPC contractors.
- Digital twin integration:Convergence of pump telemetry with reservoir simulation software enables predictive maintenance contracts tied to availability guarantees rather than time-based service intervals.
- EU Green Deal offshore electrification incentives:Carbon border adjustment mechanisms favor electromechanical drive configurations over gas turbine alternatives in North Sea newbuild projects.
Industry Challenges
- Corrosion-resistant welding certification:ASME Section IX qualification for super-duplex overlay procedures requires specialized technicians with limited availability in Atlantic basin service hubs.
- Legacy control system integration:New variable-frequency drive installations must interface with obsolete platform SCADA architectures, extending commissioning timelines and requiring custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Water Injection Pumps Market |
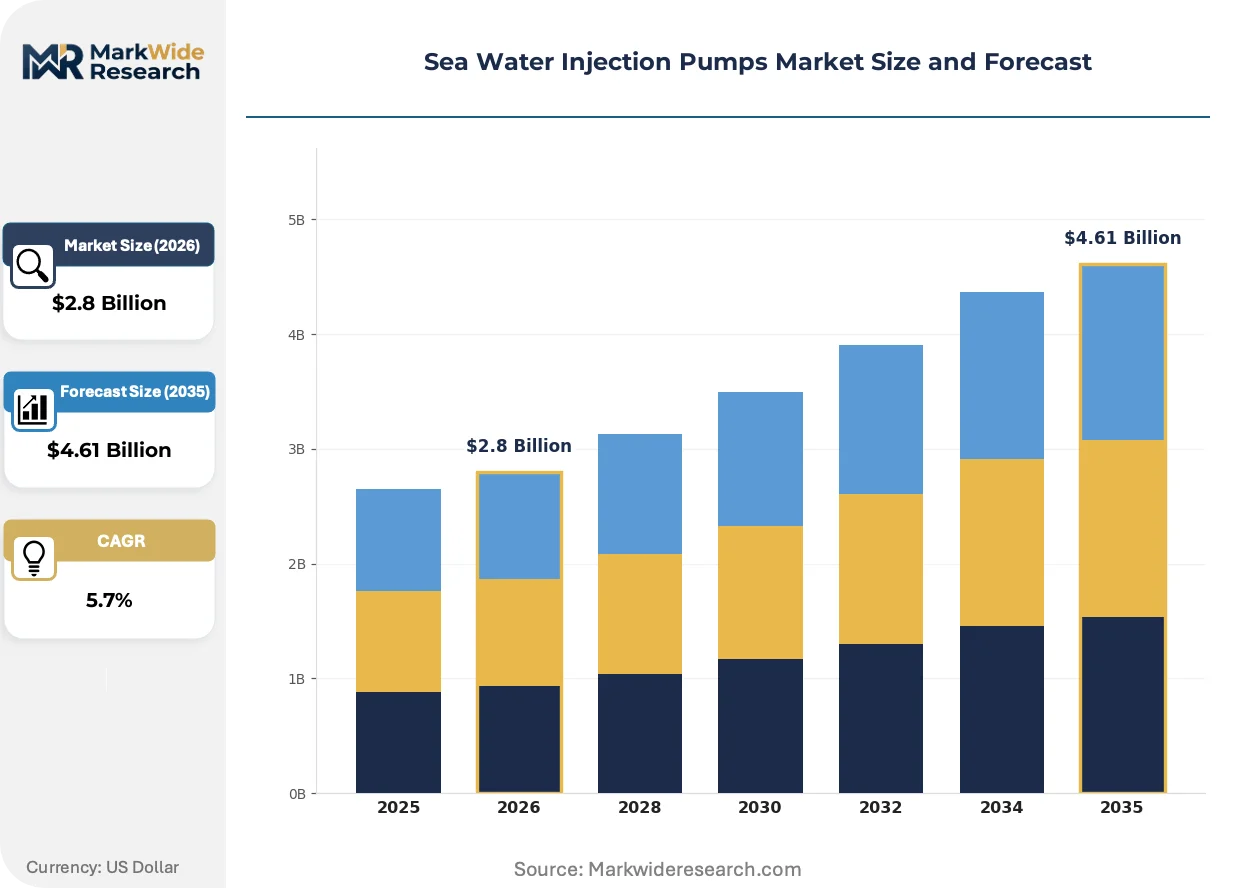
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Pumps, Positive Displacement Pumps, Submersible Pumps, Multistage Pumps Application: Oil Recovery, Water Supply, Chemical Processing, Aquaculture End User: Oil & Gas Companies, Marine Industries, Water Treatment Facilities, Research Institutions Technology: Electromechanical, Hydraulic, Pneumatic, Mechanical |
| Companies Covered | Aker Solutions, Baker Hughes, Schlumberger Limited, Halliburton Company, OneSubsea, Flowserve Corporation, Sulzer, FMC Technologies, ITT Bornemann, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Water Injection Pumps Market Evolving Landscape
Equipment intelligence and materials science are converging to redefine pump lifecycle economics, with operators demanding predictive capability and extended corrosion warranties as baseline procurement criteria rather than premium options.
Additive manufacturing is absorbing complex impeller geometries previously machined from solid forgings, enabling internal cooling passages and optimized vane profiles that improve hydraulic efficiency by three to five percentage points. Offshore operators in Brazil and Norway are qualifying laser-powder-bed-fusion components for non-rotating hardware first, with rotating element adoption following accelerated fatigue testing protocols. The technology is absorbing capital previously allocated to five-axis machining centers and long-le-time forging inventory, compressing working capital requirements for pump OEMs.
REACH restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent alternatives or ceramic coatings for pump wear rings and shaft sleeves, with ECHA substance evaluation timelines creating compliance uncertainty for spare parts strategies. Mechanical seal manufacturers face reformulation deadlines that intersect with pump overhaul cycles, creating synchronized procurement windows. North Sea operators are responding by consolidating seal and pump maintenance contracts under single-source agreements to manage transition risk.
Service unbundling is fragmenting traditional aftermarket relationships, with national oil companies in Saudi Arabia and Brazil negotiating direct spare parts agreements with foundries and seal manufacturers rather than routing through OEM service networks. Digital parts catalogs with 3D visualization are displacing printed manuals and phone-based technical support as the primary post-sale interface. This pattern concentrates in regions with mature local content requirements, where operators possess sufficient technical staffing to manage direct supplier relationships.
Sea Water Injection Pumps Market Segmentation
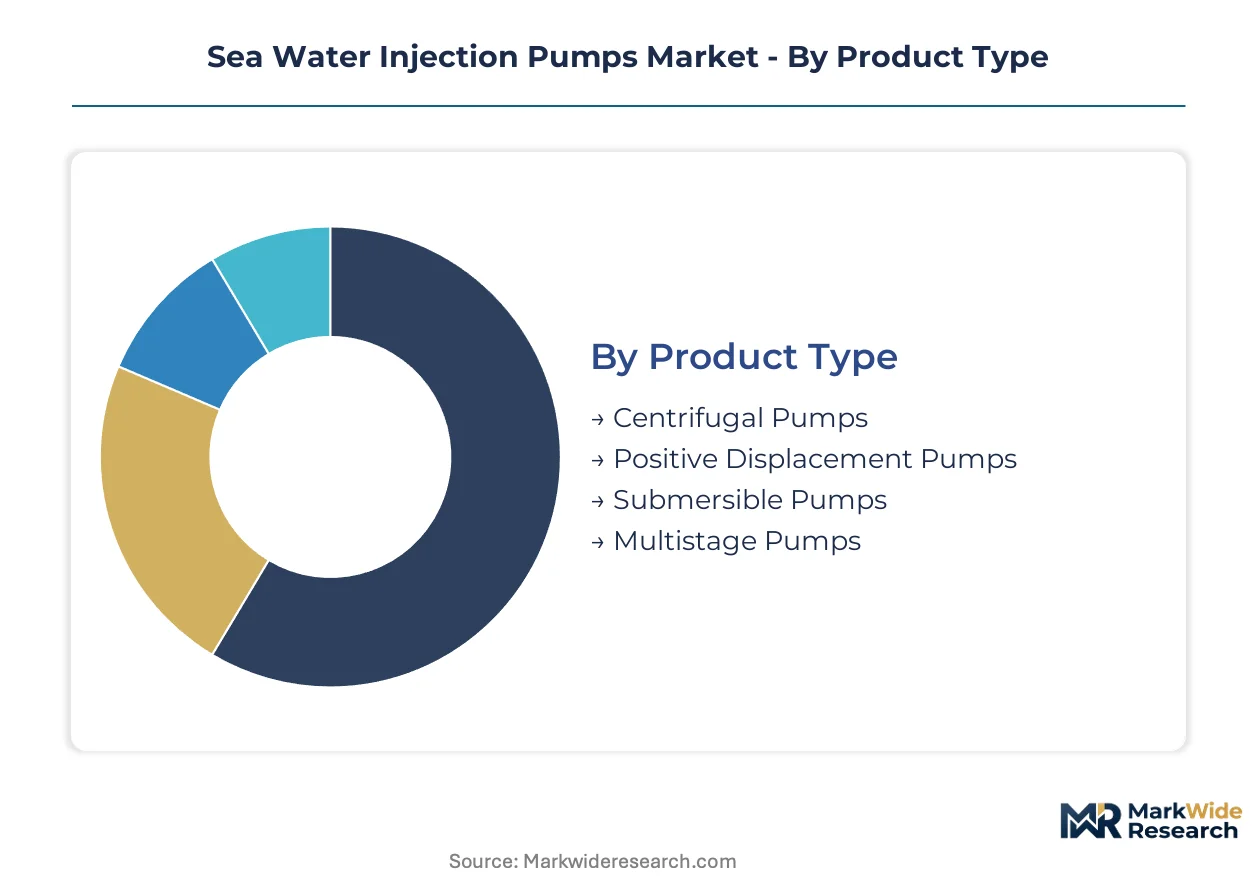
Capital allocation patterns across the Sea Water Injection Pumps Market diverge sharply by segment, with super-duplex alloy specifications and platform electrification requirements driving procurement decisions. Operators segment their supplier base by technical risk tolerance and reservoir pressure profiles.
Product Type:
Centrifugal configurations demand the highest upfront capital outlays due to super-duplex casting requirements and API 610 compliance testing protocols.
- Centrifugal Pumps:These high-flow machines handle filtered seawater at discharge pressures exceeding 200 bar through single or multistage impeller arrangements. Brazil's pre-salt field operators specify these for pressure maintenance in carbonate reservoirs where volume throughput dominates economics.
- Positive Displacement Pumps:Reciprocating or rotary mechanisms deliver precise flow control at extreme pressures above 400 bar. Norwegian operators deploy these in high-viscosity or multiphase-tolerant applications where gas breakthrough risks justify capital premiums over centrifugal alternatives.
- Submersible Pumps:Electric submersible configurations integrate motor and pump stages for deep-set installations.
- Multistage Pumps:Axially split or barrel-type housings stack multiple impeller stages for incremental pressure buildup.
Most installed capacity flows through Centrifugal Pumps. Expansion is steepest in Positive Displacement Pumps as high-pressure reservoir applications multiply.
Application:
Downstream value capture varies dramatically by application, with oil recovery commanding the longest service contracts and most stringent material specifications.
- Oil Recovery:Enhanced oil recovery and pressure maintenance operations inject filtered seawater into depleted reservoirs to sustain production rates. Saudi Aramco and Petrobras dominate procurement volumes for mature field revitalization programs.
- Water Supply:Desalination pre-treatment and industrial water intake systems require corrosion-resistant pumping at lower pressure differentials. Coastal municipalities in the Middle East specify these for seawater reverse osmosis feed systems.
- Chemical Processing:Brine handling and chlor-alkali production circuits utilize sea water injection pump architectures for corrosive fluid transport.
- Aquaculture:Open-water fish farm operations deploy submersible configurations for cage flushing and oxygenation systems.
Procurement volume concentrates in Oil Recovery. Aquaculture applications are expanding most quickly as offshore farming operations scale in Norway and Chile.
End User:
Contracting sophistication separates end user segments, with oil and gas majors demanding integrated service agreements unavailable to smaller facility operators.
- Oil & Gas Companies:Integrated majors and national oil companies specify API 610 compliant units with NACE MR0175 material certifications for sour service exposure. These operators negotiate direct foundry relationships to compress lead times for super-duplex components.
- Marine Industries:Shipboard ballast water treatment and cooling systems drive demand for compact, corrosion-resistant configurations. Classification society rules from DNV and ABS govern material selection and testing protocols.
- Water Treatment Facilities:Municipal desalination plants and industrial water utilities prioritize energy efficiency and extended mean time between overhauls.
- Research Institutions:Oceanographic and climate research platforms require specialized low-flow high-precision pumping for instrument deployment.
Technical specification authority rests with Oil & Gas Companies. Research Institutions represent the fastest-growing customer type as deep-sea exploration funding expands.
Technology:
Drive system selection determines lifecycle emissions profiles and platform electrification compliance trajectories.
- Electromechanical:Variable-frequency drive configurations with permanent magnet or induction motors displace gas turbine alternatives in newbuild platform specifications. EU Green Deal carbon border adjustments favor these systems in North Sea developments.
- Hydraulic:Power fluid-driven units persist in subsea installations where electrical penetrations pose reliability risks. These configurations tolerate wellhead proximity and multiphase exposure better than electromechanical alternatives.
- Pneumatic:Compressed air drive systems occupy niche hazardous area classifications where electrical ignition risks dominate safety planning.
- Mechanical:Direct shaft coupling to gas turbines or diesel engines retains installed base in legacy platforms with limited electrical infrastructure.
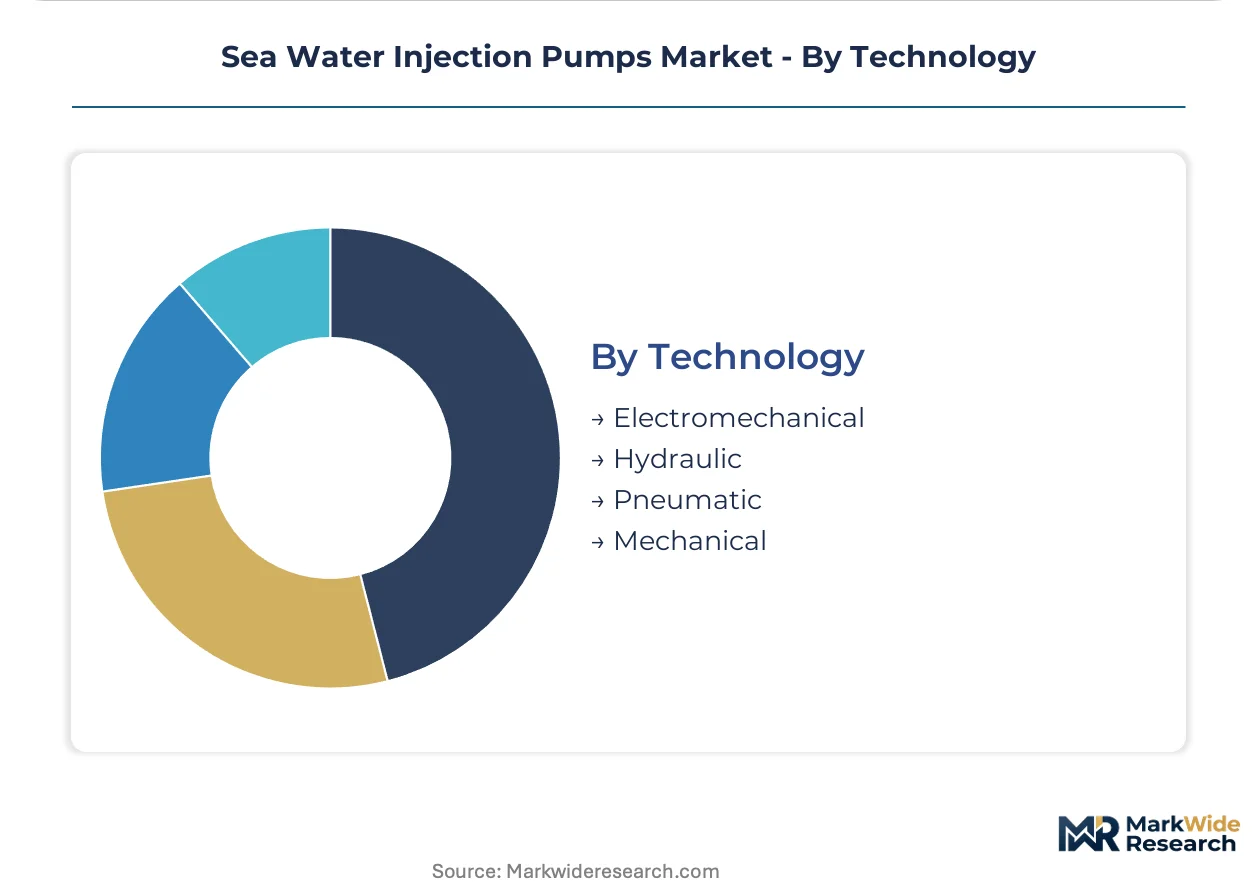
Electromechanical technology captures the dominant share of newbuild specifications. Hydraulic systems are gaining share fastest in subsea tieback projects where electrification costs prove prohibitive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore oilfield engineering for high-pressure seawater injection originated in the North Sea during the 1970s, with Norwegian and UK operators pioneering super-duplex metallurgy for subsea pump installations. This technical foundation subsequently transferred to Brazil's pre-salt developments and Saudi Arabia's mature field revitalization programs.
Brazil
Petrobras drives procurement volumes through pre-salt carbonate reservoir pressure maintenance programs. ANP local content mandates force foreign OEMs to partner with domestic fabricators for pump package qualification. The Santos Basin cluster near Rio de Janeiro anchors super-duplex foundry investments and subsea assembly yards.
Norway
Equinor and Aker BP execute brownfield electrification roadmaps that retire gas turbine-driven pumps ahead of mechanical end-of-life. NORSOK M-001 corrosion allowance revisions trigger replacement cycles in installations exceeding twenty years. The Stavanger-Bergen corridor concentrates subsea engineering competence and dedicated alloy casting capacity.
Saudi Arabia
Saudi Aramco's mature field revitalization programs sustain demand for high-pressure injection systems in carbonate reservoirs. The national oil company negotiates direct foundry relationships to compress lead times for super-duplex components. The Eastern Province industrial zone around Jubail hosts pump assembly facilities and corrosion-resistant alloy supply chains.
United States
Gulf of Mexico operators pursue platform electrification to satisfy lender sustainability covenants tied to Scope 1 reduction targets. BSEE safety and environmental enforcement shapes subsea equipment qualification protocols. The Houston-Galveston petrochemical corridor maintains engineering offices and aftermarket service hubs for deepwater developments.
United Kingdom
North Sea decommissioning timelines intersect with extended field life programs that sustain pump replacement demand. HSE offshore safety regulations govern mechanical integrity testing for high-pressure fluid handling equipment. Aberdeen maintains subsea engineering clusters despite production decline in mature basin areas.
Sea Water Injection Pumps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across metallurgical certification and digital service integration capabilities. The vendor base concentrates around integrated oilfield service conglomerates with captive subsea engineering divisions and standalone pump OEMs with dedicated corrosion-resistant foundry investments. Three archetypes dominate: full-stream providers bundling pumps with reservoir services, component specialists controlling super-duplex casting capacity, and electromechanical system integrators capturing platform electrification mandates. Competitive moves center on unbundling modular skid packages from EPC contracts and securing long-term availability-based service agreements.
Within the full-stream provider tier, Baker Hughes and Schlumberger Limited anchor integrated service portfolios that bundle pumping hardware with reservoir characterization and digital twin platforms. Flowserve Corporation exemplifies the component specialist archetype through captive corrosion-resistant alloy foundry investments that compress lead times for high-pressure pump castings. These three entities occupy positions that span procurement channels previously captured by integrated EPC contractors.
| Leading Market Players |
|---|
| Aker Solutions |
| Baker Hughes |
| Schlumberger Limited |
| Halliburton Company |
| OneSubsea |
| Flowserve Corporation |
| Sulzer |
| FMC Technologies |
| ITT Bornemann |
| Others |
Value Network & Pricing Analysis
ANP local content mandates in Brazil are forcing foreign pump OEMs to partner with domestic fabricators, compressing procurement timelines while inflating qualification costs that suppliers must recover through premium pricing on qualified packages.
Pricing Analysis
Three-tier pricing structure across API 610-certified premium, NORSOK M-001-compliant standard, and economy-grade configurations separates suppliers by metallurgical certification depth. Price differentiation rests on super-duplex alloy grade and digital twin integration bundling. Cost compression in economy tiers is intensifying because Indonesian nickel ore export quotas squeeze foundry feedstock margins. National oil companies exhibit lowest price sensitivity due to availability guarantees, while marine industry buyers prioritize upfront capital minimization over lifecycle cost.
Supply Chain Analysis
Freight costs for super-duplex castings from Norway and Saudi Arabia to Atlantic basin assembly yards absorb working capital previously allocated to inventory buffers, compressing OEM margins on just-in-time deliveries. Component sourcing draws from German-Japanese forging networks for large-diameter pump shafts, Norwegian foundries for corrosion-resistant housings, and Brazilian fabricators for skid packaging. Single-source vulnerability concentrates in shaft forgings above 500mm. Distribution runs through direct foundry relationships that national oil companies negotiate to bypass OEM service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal carbon border adjustments and NORSOK M-001 corrosion allowance revisions generate replacement demand independent of underlying reservoir economics.
For Market Incumbents: Anticipate multiphase pump substitution threats in high-gas-fraction reservoirs by deepening captive super-duplex casting capacity in Norway and Saudi Arabia. Secure ASME Section IX welding certification pipelines ahead of Atlantic basin service hub shortages. Anchor long-term availability contracts with Petrobras and Saudi Aramco before modular procurement unbundling accelerates. For New Entrants and Emerging Players: Begin with aquaculture submersible configurations in Norway and Chile where technical barriers sit below oil and gas certification thresholds. Target direct spare parts agreements with foundries in regions with mature local content requirements. Lead with 3D-visualized digital parts catalogs to displace legacy OEM service relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists controlling dedicated corrosion-resistant alloy foundries rather than full-stream providers dependent on reservoir service bundling. Five-to-ten year viability favors foundry-backward-integrated pump OEMs over pure-play digital integrators. Monitor nickel price volatility and Indonesian ore export policy as inflection signals for foundry margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Super-Duplex Foundry Investment | Compresses lead times for NORSOK M-001 compliant castings above 200 bar discharge pressure. |
| Digital Twin Platform Integration | Enables predictive maintenance contracts tied to availability guarantees with Equinor and Aker BP. |
| Modular Skid Packaging Unbundling | Opens direct procurement channels previously captured by integrated EPC contractors in Norway. |
| ASME Section IX Welding Certification Pipeline | Addresses technician scarcity for super-duplex overlay procedures in Atlantic basin service hubs. |
| Direct Foundry Relationship Negotiation | Bypasses OEM service networks for national oil companies in Saudi Arabia and Brazil. |
Research Methodology
Coverage spans Brazil, Norway, Saudi Arabia, and the United States Gulf Coast, with primary inputs from each region combined with secondary validation. Interviews with subsea project engineers, pump OEM procurement directors, foundry operations managers, and national oil company maintenance heads anchor demand-side intelligence. Secondary sources include ANP local content filings, NORSOK M-001 revision documentation, SEC equipment supplier disclosures, and Brazilian customs import records for super-duplex alloy components. Bottom-up unit deployment estimates triangulate against top-down capital expenditure allocations across offshore basin developments.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include pump type configuration, drive technology architecture, pressure rating tier, and end-user contracting sophistication. CAGRs derive from rolling installation base replacement cycles and newbuild electrification roadmaps. Forecast inputs incorporate platform decommissioning timelines intersecting with extended field life programs, plus REACH restriction compliance deadlines for hexavalent chromium surface treatments.
Several conditions sit outside the modeled scope, including unforeseen nickel price spikes beyond historical volatility bands, geopolitical trade friction affecting German-Japanese shaft forging supply, and accelerated multiphase pump technology adoption that could compress addressable market for conventional seawater injection pumps. Forecasts reflect assumptions about regulatory enforcement continuity and operator electrification commitment durability. Stakeholders should weight assumptions against their own operating context and stress-test procurement plans against single-source forging concentration risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Digital Pump Market
Pumps and Control Devices
Liquid Ring Vacuum Pump Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
In Pipe Hydro Systems Market
Pumps and Control Devices
Fluid Transfer System Market
Pumps and Control Devices
Global Commercial Pumps Market
Pumps and Control Devices
Global Heavy Duty Pumps Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Global Pumps Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
Global Industrial Submersible Pumps Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Global Lobe Pumps Market