
 Digital Finance Market | 2026-2036
Digital Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Finance Market Insights
Unbundling of core banking functions into modular API products is rebalancing buyer choice away from monolithic suites toward composable stacks. Stripe leverages developer-centric tooling to anchor its position in payment infrastructure for platforms. Adyen competes through unified commerce capabilities that span online, in-store, and marketplace channels. SoFi Technologies specializes in vertically integrated consumer finance, combining lending, banking, and investment products under one digital roof.
Digital finance encompasses technology-enabled financial services delivered through software platforms, APIs, and mobile interfaces, operating on real-time data pipelines with sub-second transaction processing and multi-layer encryption protocols. Its primary commercial purpose is to disintermediate traditional financial intermediaries while reducing unit costs per transaction. Payment Processing dominates solution-type revenue pools due to high transaction velocity across e-commerce and SaaS channels. Cloud-Based deployment is expanding fastest as regulated entities migrate core systems away from legacy on-premises infrastructure. API Integration represents a concentrated margin pool where vendors monetize connectivity layers between banks, fintechs, and enterprise treasury systems.
The US OCC and CFPB shape charter pathways and consumer protection standards for digital lenders and neobanks, while the EU's PSD2 and forthcoming PSD3 mandate open banking data sharing that forces incumbents to expose account interfaces. India's RBI operates a regulatory sandbox that permits live testing of blockchain-based settlements and AI-driven credit underwriting. Stakeholders must monitor how divergent national approaches to stablecoin regulation and AI governance fragment cross-border service architectures.
Market Dynamics
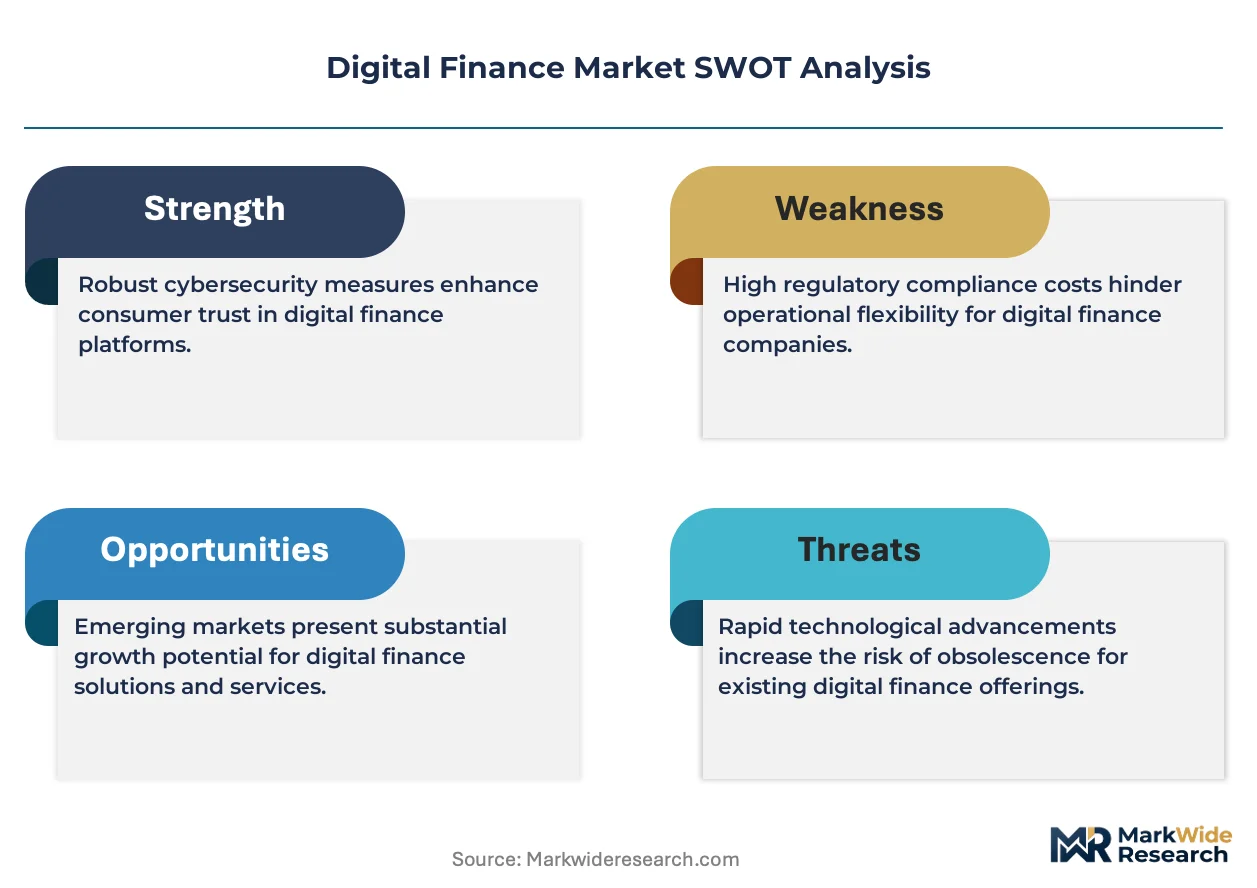
API-first banking infrastructure is fragmenting traditional core banking monopolies into composable service layers, forcing incumbents to expose payment rails and account data through standardized interfaces or lose platform relationships.
Growth Catalysts
- UPI Real-Time Rails:India's unified payments interface processes billions of monthly transactions, creating template infrastructure that neighboring markets are replicating through bilateral technical assistance agreements.
- PSD2 Open Banking Mandates:European account access regulations force incumbent banks to expose customer data interfaces, accelerating third-party payment initiation and account aggregation services.
- Cloud Migration:Regulated financial institutions are replatforming core ledger systems onto distributed cloud architectures to reduce data center capital intensity and improve elastic capacity during settlement peaks.
Market Restraints
- Core Banking Vendor Concentration:Three legacy technology vendors dominate mission-critical deposit and lending systems, creating switchover risk for institutions seeking modular replacements.
- Cross-Border Settlement Friction:Correspondent banking relationships are contracting due to de-risking policies, fragmenting currency corridors and raising transaction costs for emerging market participants.
- Quantum Cryptography Timeline:Current encryption protocols face obsolescence risk from advancing quantum computing capabilities, forcing premature infrastructure investment ahead of standardized post-quantum algorithms.
Strategic Opportunities
- Embedded Finance Penetration:Non-financial platforms in logistics, healthcare, and agriculture are white-labeling payment and lending capabilities, expanding addressable market beyond traditional banking customers.
- Regulatory Sandbox Pathways:India's RBI and the UAE's central bank permit live testing of blockchain settlement and AI credit models, compressing time-to-market for novel product architectures.
- Real-Time Cross-Border:Bilateral central bank digital currency linkages between Thailand, Singapore, and the UAE are establishing corridor-specific alternatives to SWIFT for regional trade settlement.
Industry Challenges
- Legacy System Integration:COBOL-based core banking infrastructure requires expensive middleware layers to connect with modern API gateways, inflating total cost of ownership for hybrid architectures.
- Model Risk Management:AI-driven credit underwriting demands specialized validation frameworks that most institutions lack in-house, creating dependency on external audit boutiques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Finance Market |
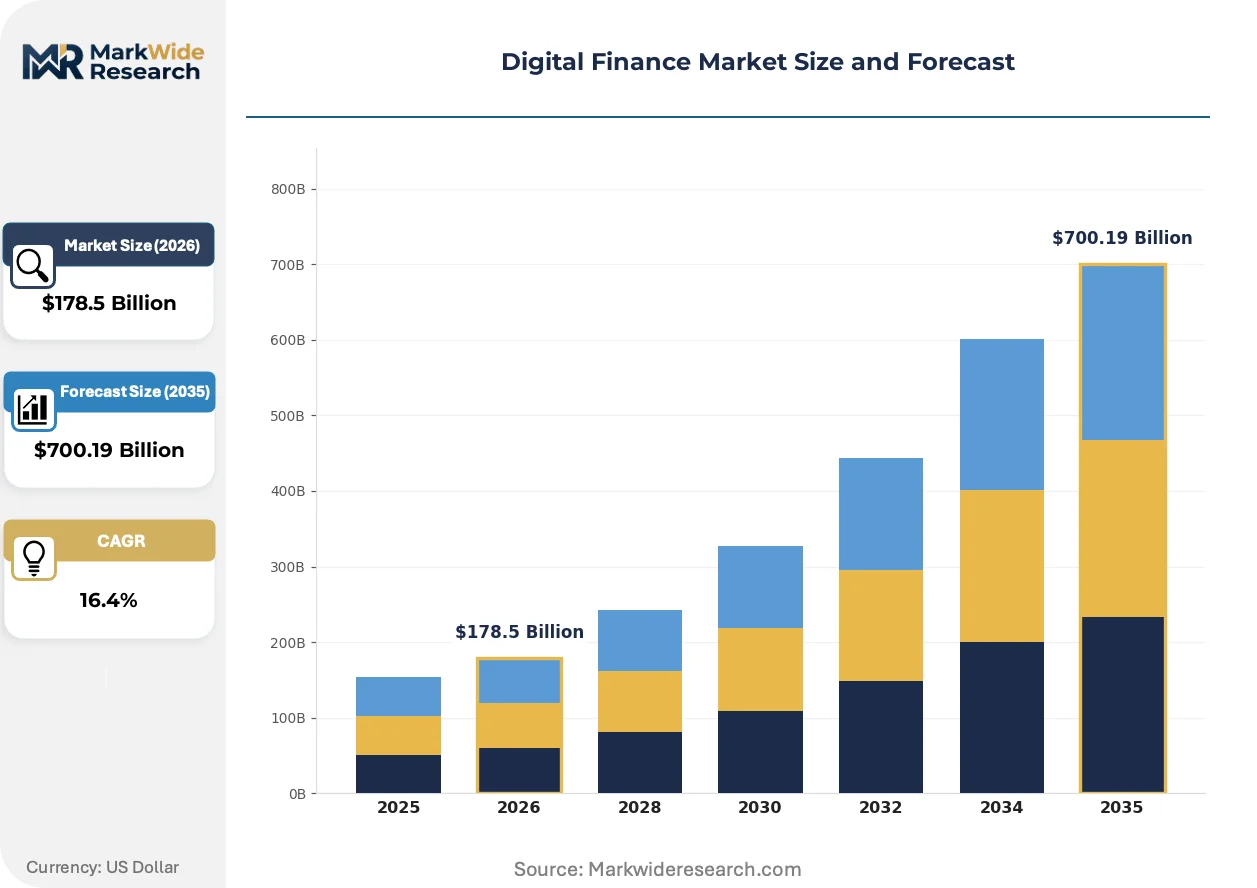
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $700.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Payment Processing, Digital Wallets, Lending Platforms, Wealth Management, Fraud Detection, RegTech Deployment Model: Cloud-Based, On-Premises, Hybrid Systems, API Integration, Mobile-First, Web-Based End User: Retail Investors, Small Businesses, Financial Advisors, E-commerce Merchants, Institutional Traders, Payment Gateways Pricing Model: Subscription, Transaction Fee, Freemium, Tiered, Pay-As-You-Go, Licensing |
| Companies Covered | PayPal, Stripe, Plaid, Revolut, Nubank, Ant Group, Checkout.com, SoFi Technologies, Adyen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Finance Market Trends and Innovations
Distributed ledger architectures are migrating from experimental pilots to production settlement layers, while regulatory sandboxes compress approval timelines for novel custody and payment instruments.
Blockchain-based settlement infrastructure is decentralizing correspondent banking relationships by enabling atomic, programmable value transfers without intermediary reconciliation delays. Southeast Asian central banks are deploying production-grade networks for regional trade finance, replacing multi-day settlement windows with near-instant finality. This architecture compresses counterparty exposure and collateral requirements for cross-border treasury operations.
The EU's forthcoming PSD3 mandates enhanced fraud liability frameworks and standardized variable recurring payment interfaces, extending open banking obligations beyond account access to include payment initiation controls. Merchants and fintech platforms must upgrade technical integrations to comply with stronger customer authentication protocols. German and Dutch retail banks are consolidating API gateway investments to amortize compliance costs across product lines.
Platform-native financial services are displacing standalone banking applications as primary customer touchpoints. Ride-hailing, e-commerce, and freight logistics platforms in Indonesia, Brazil, and Nigeria are embedding credit, insurance, and treasury products directly into operational workflows. This pattern concentrates customer acquisition economics with vertical software providers rather than traditional deposit-taking institutions.
Digital Finance Market Segmentation
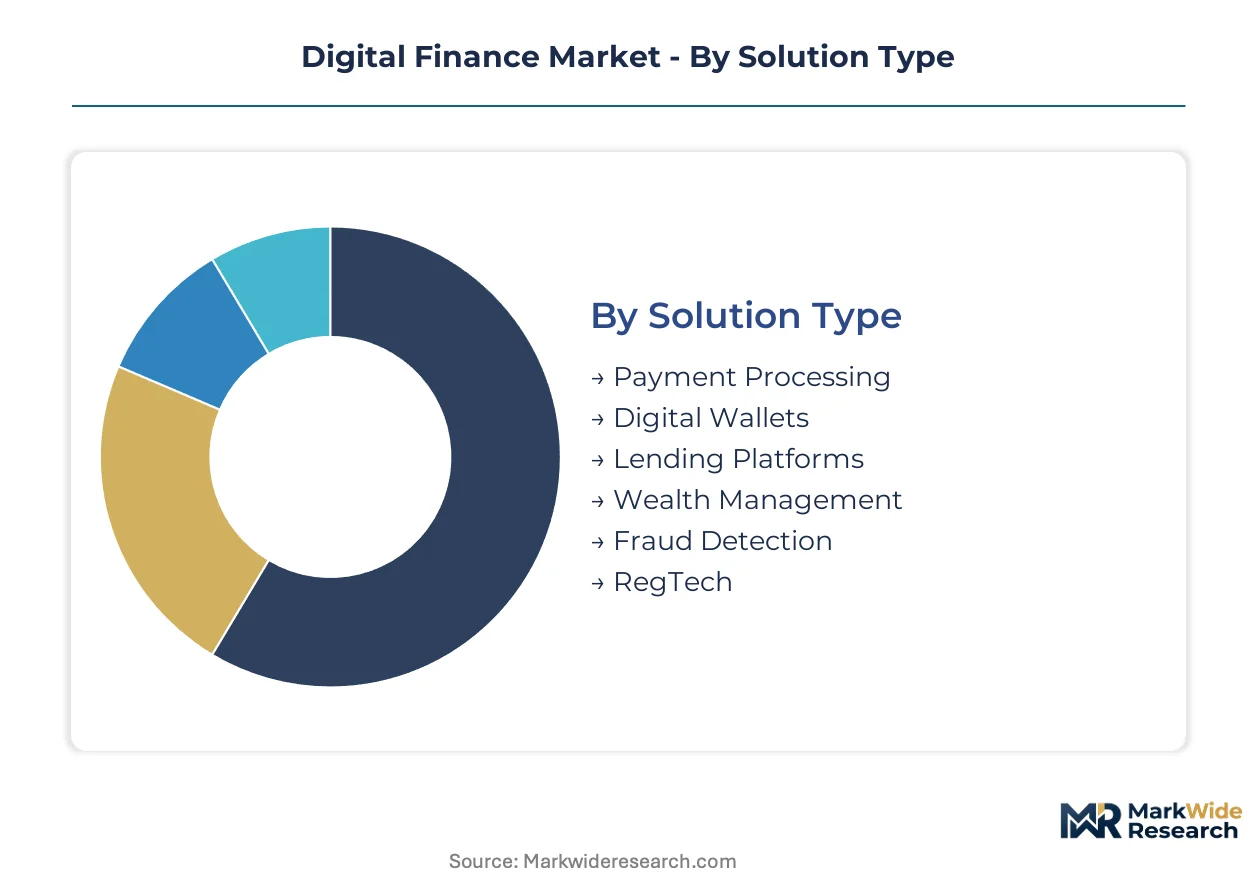
Segmentation in digital finance reveals how infrastructure choices and pricing architectures determine vendor profitability. Buyers select across solution types, deployment models, end-user categories, and pricing structures based on regulatory exposure and transaction velocity requirements.
Solution Type:
Payment Processing commands the highest transaction volumes, while RegTech solutions capture premium pricing from compliance-heavy institutions.
- Payment Processing:Real-time transaction routing infrastructure handling authorization, clearing, and settlement across card networks and alternative rails. Demand concentrates among e-commerce merchants in India and Southeast Asia, where UPI and QR-code penetration reduce cash dependency.
- Digital Wallets:Stored-value accounts enabling peer-to-peer transfers, merchant payments, and bill settlements through mobile interfaces. Small businesses in Brazil and Nigeria embed these into operational workflows, driven by underbanked population access and instant settlement needs.
- Lending Platforms:Automated credit origination systems using alternative data scoring and API-connected underwriting engines.
- Wealth Management:Robo-advisory and self-directed investment platforms with fractional share trading and tax-optimization tools.
- Fraud Detection:Machine-learning systems monitoring transaction patterns for synthetic identity and account takeover risks.
- RegTech:Compliance automation covering KYC, AML screening, and regulatory reporting for licensed financial institutions.
Mature deployment sits with Payment Processing. Newer deployment is concentrated in RegTech as PSD3 and AI governance frameworks expand audit requirements.
Deployment Model:
Cloud architectures dominate new implementation, though hybrid configurations persist where data residency mandates require on-premises ledger storage.
- Cloud-Based:Distributed infrastructure with elastic compute scaling and multi-region redundancy for core banking systems. Financial advisors and neobanks in Germany and the Netherlands favor this model, driven by capital expenditure reduction and disaster recovery requirements.
- API Integration:Connectivity layers exposing account data, payment initiation, and identity verification through standardized interfaces. E-commerce merchants across Singapore and Thailand adopt these for embedded checkout experiences, compelled by open banking mandates and platform economics.
- On-Premises:Dedicated hardware installations maintaining physical control over encryption keys and audit logs.
- Hybrid Systems:Split architectures with sensitive workloads on-premises and customer-facing layers in cloud environments.
- Mobile-First:Native application architectures optimized for smartphone-dominant user bases in emerging markets.
- Web-Based:Browser-accessible platforms requiring no local software installation for institutional treasury portals.
Established institutions retain On-Premises for core ledgers. API Integration is gaining share fastest as platform business models proliferate.
End User:
Retail-facing segments drive transaction volume, while institutional users generate higher revenue per seat through complex workflow integration.
- Small Businesses:Merchants and service providers requiring integrated payment acceptance, working capital credit, and cash flow forecasting. Adoption concentrates in India's tier-2 cities, where UPI acceptance infrastructure and GST-compliant invoicing tools reduce administrative burden.
- E-commerce Merchants:Online retailers needing multi-currency checkout, chargeback management, and marketplace settlement splits. Cross-border sellers in the UAE leverage these capabilities, shaped by dirham-pegged stablecoin corridors and real-time FX hedging.
- Retail Investors:Individual wealth builders accessing fractional securities, retirement accounts, and robo-advisory services.
- Financial Advisors:Registered representatives managing client portfolios through unified practice management platforms.
- Institutional Traders:Asset managers and hedge funds executing algorithmic strategies with colocated infrastructure.
- Payment Gateways:Technical intermediaries aggregating multiple acquiring relationships for merchant service provision.
Payment Gateways represent mature, consolidated demand. Small Businesses show the steepest expansion trajectory as embedded finance penetrates vertical software.
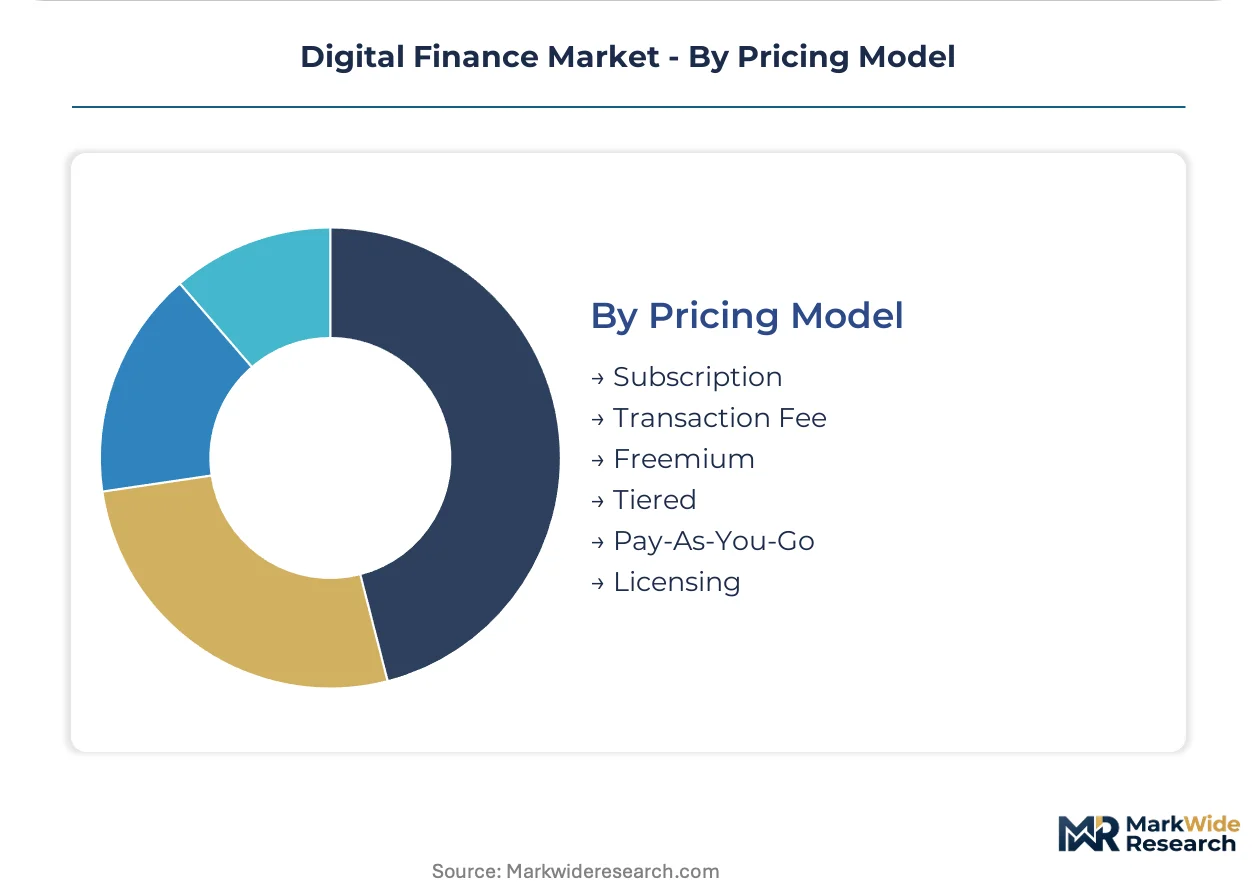
Pricing Model:
Transaction-linked structures align vendor success with customer growth, while subscription models suit predictable compliance and infrastructure costs.
- Transaction Fee:Per-payment pricing calculated as basis points on volume plus fixed authorization charges. Payment gateways processing UPI and card-not-present volumes in India favor this structure, as it scales with merchant sales without upfront commitment.
- Subscription:Recurring fixed fees for platform access, feature tiers, and support levels. Wealth management platforms serving financial advisors in Switzerland and Luxembourg adopt this model, driven by predictable budgeting and white-label customization needs.
- Freemium:Basic functionality at no cost with premium features unlocked through upgrade payments.
- Tiered:Volume-discounted pricing bands rewarding transaction scale with reduced marginal rates.
- Pay-As-You-Go:Consumption-based billing for compute, storage, and API call volumes without minimum commitments.
- Licensing:Perpetual or term-limited software rights for on-premises installation with maintenance add-ons.
Licensing dominates legacy core banking procurement. Transaction Fee structures are displacing fixed subscriptions in payment infrastructure as usage-based economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital finance infrastructure concentrates production in technology hubs while consumption spreads across emerging and developed economies. The United States generates substantial platform innovation. India and China process massive transaction volumes through domestic payment rails. European markets drive regulatory standardization.
United States
Venture capital flows and cloud infrastructure investment sustain platform development in Silicon Valley and New York fintech corridors. The SEC and CFPB enforce disclosure and consumer protection standards for digital lenders and robo-advisors. San Francisco anchors developer-centric payment infrastructure firms that serve global SaaS and marketplace customers.
India
UPI transaction volumes exceeding billions monthly create the world's largest real-time payment ecosystem for retail and small business use. The RBI regulatory sandbox permits live testing of blockchain settlements and AI credit models. Mumbai and Bangalore clusters host neobanks and payment aggregators building on domestic rails for Southeast Asian export.
China
Super-app financial integration and central bank digital currency pilots drive transaction density across consumer and merchant segments. SAMR and the central bank enforce antitrust and data localization requirements for platform financial services. Shenzhen and Shanghai house technology conglomerates that embed payments, lending, and wealth management into e-commerce and social platforms.
Germany
Industrial treasury digitization and open banking compliance create demand for API-connected corporate banking services. BaFin implements PSD2 account access mandates and prepares financial institutions for PSD3 fraud liability frameworks. Frankfurt and Berlin clusters concentrate B2B fintechs serving manufacturing supply chain finance and embedded insurance.
Singapore
Wealth management digitization and regional trade finance modernization attract institutional platform investment. The Monetary Authority of Singapore operates a regulatory sandbox for blockchain-based cross-border settlement and digital asset custody. The city-state serves as ASEAN headquarters for payment networks linking Thailand, Indonesia, and Vietnam through bilateral CBDC corridors.
Digital Finance Market Competitive Landscape
The competitive structure tilts toward platform-scale infrastructure providers with developer-centric distribution. Three to five legacy core banking vendors retain institutional deposit and lending system dominance. Strategic archetypes include API-first payment infrastructure, vertically integrated consumer finance, and unified commerce orchestration. Consolidation proceeds through strategic partnerships between banks and technology platforms, plus geographic expansion into regulatory sandbox jurisdictions.
Within the developer-centric infrastructure tier, Stripe and Adyen exemplify contrasting approaches to platform embedding and unified commerce. PayPal occupies a position spanning consumer wallets and merchant services across North American and European markets. These anchors represent how scale and specialization split the competitive field between horizontal infrastructure and vertical financial product integration.
| Leading Market Players |
|---|
| PayPal |
| Stripe |
| Plaid |
| Revolut |
| Nubank |
| Ant Group |
| Checkout.com |
| SoFi Technologies |
| Adyen |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure cost indices cascading through API gateway provisioning and core banking system migration are compressing pricing tiers for digital finance infrastructure buyers. This input cost volatility stratifies vendor offerings across premium managed-service bundles, standard API connectivity packages, and economy self-serve developer tiers.
Pricing Analysis
Margin tightening in standard-tier payment processing reflects hyperscaler compute pricing pressure and open-source middleware proliferation. Three-tier pricing structure across premium, standard, and economy levels differentiates by SLA guarantees, dedicated support, and geographic redundancy coverage. Price differentiation traces to certification burden and transaction volume scale. Small businesses in India's tier-2 cities exhibit highest price sensitivity, while institutional traders in Singapore accept premium tiers for colocated infrastructure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor fabrication for payment terminal chipsets and China-dominated rare earth processing for server magnet components. Infrastructure provisioning draws from Ireland and Singapore for cloud data center capacity, plus India for software engineering talent. Supply chain risk centers on cross-border data residency restrictions fragmenting architecture choices. Distribution runs through API marketplace aggregators and direct enterprise sales teams serving neobanks and payment gateways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital finance infrastructure is becoming a vertical-integration race where control over payment rails and regulatory licensing determines margin capture. Incumbents and challengers alike are pursuing downstream embedding relationships with non-financial platforms.
For Market Incumbents: Deepen API gateway consolidation through acquisition of specialist fraud-detection boutiques before embedded finance platforms internalize these capabilities. Defend core ledger relationships by accelerating COBOL-modernization partnerships with cloud-native vendors, as regulatory sandboxes in India and the UAE lower switching barriers for challenger banks.
For New Entrants and Emerging Players: PSD3 in Germany and the Netherlands opens a window for variable recurring payment infrastructure plays as incumbent banks amortize compliance costs slowly. Target agricultural supply chain platforms in Brazil and Indonesia with white-label treasury products, leveraging mobile-first architectures that bypass legacy branch networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor API-first infrastructure specialists with RBI or MAS sandbox approvals in Mumbai and Singapore corridors. Watch for consolidation signals when tier-2 neobanks face capital adequacy pressure from rising interest rate environments, creating acquisition targets with embedded customer bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Entry | RBI and MAS approvals compress time-to-market for novel settlement architectures in India and ASEAN corridors. |
| API Gateway Consolidation | Horizontal integration of fraud-detection layers strengthens pricing power against embedded finance platform insourcing. |
| Cloud-Native Core Migration | Distributed ledger replatforming reduces data center capital intensity for European banks facing PSD3 compliance deadlines. |
| Vertical Software Embedding | White-label payment integration into logistics and healthcare platforms expands addressable market beyond traditional banking. |
| Cross-Border CBDC Linkage | Bilateral central bank digital currency corridors between Thailand, Singapore, and UAE establish alternatives to SWIFT settlement. |
Research Methodology
Multi-period observation of UPI transaction velocity, cloud infrastructure capex disclosures, and regulatory sandbox approval timelines anchored the trend analysis, supplemented by interviews with neobank CTOs, payment gateway integration specialists, RBI regulatory affairs leads, and enterprise treasury platform engineers. Secondary validation drew from SEC filings of listed fintech infrastructure providers, ECB payment statistics, NPCI UPI volume reports, and MAS fintech regulatory circulars. Bottom-up transaction flow modeling and top-down banking technology spend estimates were triangulated to cross-check segment sizing.
Input-output matrices mapped API call volumes, licensing fee structures, and infrastructure deployment costs across solution type, deployment model, end-user category, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted adoption curves and replacement cycle analysis. Forecast inputs included open banking mandate implementation schedules and central bank digital currency pilot expansion trajectories.
Caveats apply where stablecoin regulatory bans, quantum cryptography standard delays, or correspondent banking de-risking acceleration could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Europe Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Blockchain Distributed Ledger Market
Digital Assets and Cryptocurrency Finance
Blockchain Finance Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
Bitcoin and Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Global Hardware Wallets Market
Digital Assets and Cryptocurrency Finance
Trading Data Platform Market
Digital Assets and Cryptocurrency Finance
NFT Art Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency and Blockchain Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market