
 Blockchain Distributed Ledger Market | 2026-2036
Blockchain Distributed Ledger Market Size, Share, and Industry Trends Forecast 2026-2036
Blockchain Distributed Ledger Market Intelligence
Software-defined smart contract templates are shifting how blockchain platforms monetize infrastructure. ConsenSys leverages its Ethereum tooling suite to anchor enterprise adoption across DeFi and institutional settlement layers. ChainSafe specializes in cross-chain interoperability protocols, while HashCash Consultants dominates blockchain-as-a-service offerings for banking clients in Asia and the Middle East.
A blockchain distributed ledger is a cryptographically linked database architecture where consensus mechanisms validate transactions across distributed nodes without centralized authority, typically employing SHA-256 hashing, Byzantine fault tolerance, or proof-of-stake validation to ensure immutability and transparency. Its primary commercial purpose is enabling trustless multi-party transaction recording, asset tokenization, and automated execution through self-executing code. Public blockchain infrastructure captures the largest deployment volume, though private blockchain configurations command premium pricing from financial institutions requiring permissioned network governance. Smart contract applications are expanding fastest as enterprises automate compliance and settlement workflows, while supply chain management remains the most mature application segment with established ROI documentation.
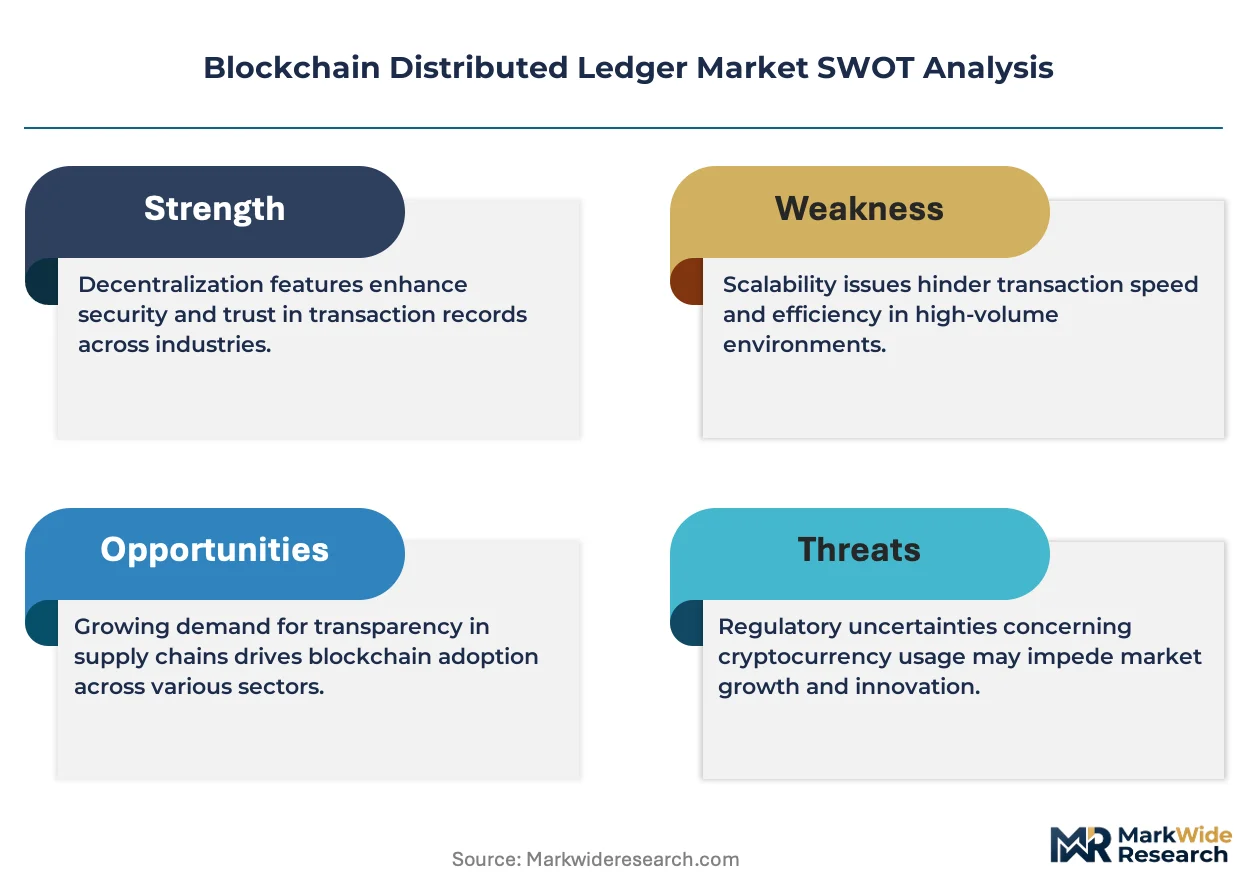
FDA scrutiny of blockchain-based health data integrity, SEC enforcement actions on unregistered token offerings, and EU MiCA framework provisions for stablecoin reserves collectively shape product development roadmaps and market access conditions for distributed ledger vendors. The EU AI Act's overlap with automated smart contract execution adds compliance complexity for European deployments. Stakeholders must monitor evolving jurisdictional treatment of tokenized securities versus utility tokens as this distinction determines licensing requirements and capital formation pathways.
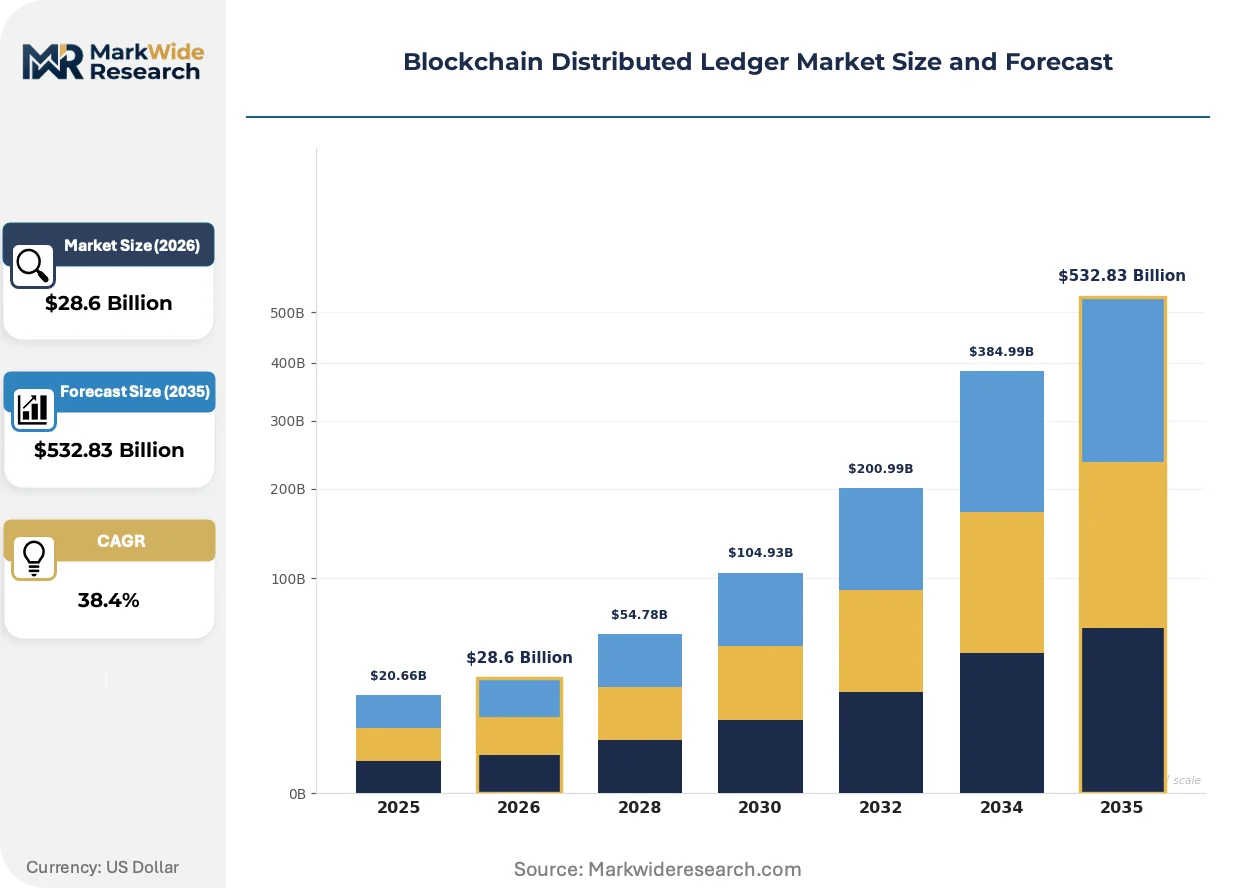
Market Dynamics
Cross-chain interoperability protocols are collapsing siloed blockchain networks into unified settlement layers, forcing infrastructure vendors to abandon single-chain architectures or lose institutional procurement contracts.
Growth Catalysts
- MiCA Stablecoin Reserves:The EU's Markets in Crypto-Assets framework mandates full reserve backing for euro-denominated stablecoins, compelling banks to deploy compliant tokenization infrastructure.
- Trade Finance Digitization:Letter-of-credit processing on distributed ledgers cuts settlement cycles from weeks to hours for commodity traders in Singapore and Dubai.
- Zero-Knowledge Proofs:zk-SNARK implementations enable private transaction validation without exposing counterparty data, satisfying institutional confidentiality requirements.
Market Restraints
- Validator Concentration Risk:Proof-of-stake networks exhibit stake concentration among custodial providers in the United States, creating systemic failure points.
- Quantum Vulnerability:Elliptic curve cryptography securing current blockchains faces obsolescence from fault-tolerant quantum computing advances.
- Energy Input Volatility:Proof-of-work validation remains dependent on electricity pricing fluctuations in jurisdictions with stranded renewable assets.
Strategic Opportunities
- Carbon Credit Tokenization:Verified emission reduction registries on-chain unlock fractional trading for project developers in Brazil and Indonesia.
- Central Bank Digital Currency Integration:Wholesale CBDC interoperability protocols position private ledgers as settlement rails for monetary authorities.
- AI-Contract Convergence:Machine learning oracles feeding parametric insurance smart contracts automate claims processing for agricultural underwriters.
Industry Challenges
- Cryptographic Talent Scarcity:Zero-knowledge circuit engineering and formal verification expertise commands premium compensation, constraining protocol development velocity.
- Legacy Core Banking Integration:ISO 20022 message mapping between distributed ledgers and mainframe systems requires multi-year transformation programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blockchain Distributed Ledger Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $532.83 Billion |
| CAGR (2026 – 2036) | 38.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Application: Supply Chain Management, Digital Identity Verification, Smart Contracts, Cross-Border Payments End User: Financial Institutions, Healthcare Providers, Government Agencies, Retail Businesses Deployment: On-Premises, Cloud-Based, Hybrid Cloud, Managed Service |
| Companies Covered | PixelPlex, ScienceSoft, ConsenSys, ChainSafe, Kaleido, Coinbase Global, LeewayHertz, HashCash Consultants, Alchemy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blockchain Distributed Ledger Market Strategic Shifts & Innovations
Modular blockchain architectures are fragmenting monolithic execution layers into specialized components for data availability, consensus, and settlement, enabling purpose-built chains for specific asset classes.
Zero-knowledge rollups are rewriting scalability economics for Ethereum-compatible networks by compressing transaction data off-chain while inheriting base-layer security guarantees. Decentralized exchanges and derivatives platforms are migrating execution to zkEVM environments, reducing gas costs by orders of magnitude. This compression is rewriting fee market structures and displacing layer-one congestion pricing models.
The EU AI Act's automated decision-making provisions impose audit requirements on smart contract execution involving algorithmic credit scoring or insurance underwriting. Financial institutions deploying self-executing agreements must document training data provenance and model interpretability. European DeFi protocols are responding by integrating on-chain explainability modules and human-in-the-loop override mechanisms.
Institutional procurement of blockchain infrastructure is consolidating around vertically integrated platform vendors capable of delivering custody, staking, and compliance tooling as unified service bundles. Buy-side firms in Switzerland and Singapore are abandoning multi-vendor patchwork configurations. This bundling is most visible among asset managers seeking single-counterparty accountability for tokenized fund administration.
Blockchain Distributed Ledger Market Segmentation
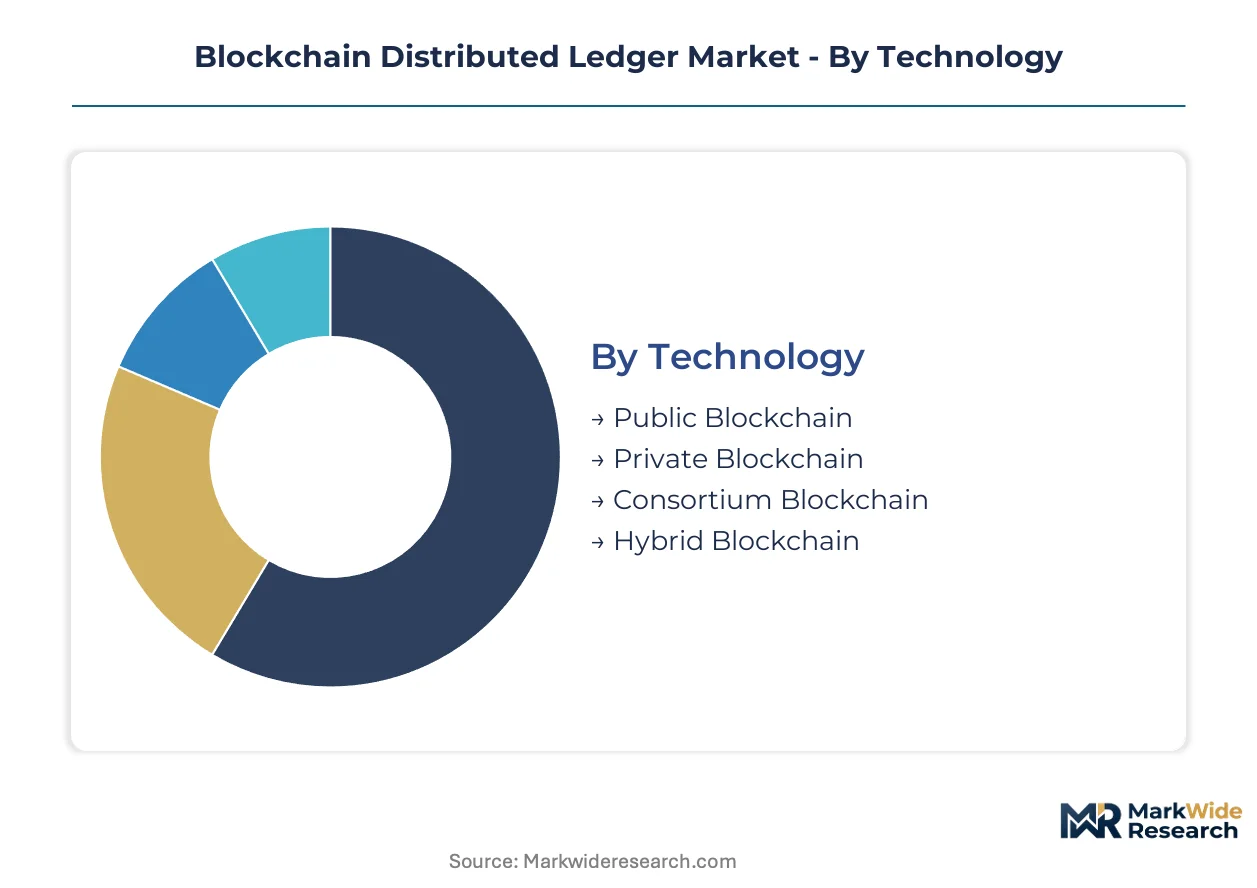
Segmentation reveals how capital allocation, regulatory exposure, and technical requirements fragment the blockchain distributed ledger market. Distinct technology architectures, application domains, and deployment models command divergent pricing, implementation timelines, and vendor ecosystems.
Technology:
Capital intensity varies sharply across consensus architectures, with permissioned infrastructure requiring substantial upfront investment in node deployment and cryptographic key management.
- Public Blockchain:Open-access networks rely on distributed validator sets and native token economics for security. Demand concentrates among DeFi protocols and NFT marketplaces in Singapore and Switzerland, where regulatory clarity on digital asset classification reduces legal uncertainty for developers.
- Private Blockchain:Permissioned ledgers restrict node participation to pre-approved entities, enabling confidential transaction processing. Financial institutions in the United Arab Emirates deploy these configurations for internal settlement networks, driven by SWIFT compatibility requirements and counterparty confidentiality mandates.
- Consortium Blockchain:Multi-party governance structures distribute infrastructure costs across industry coalitions.
- Hybrid Blockchain:Dual-layer architectures balance transparency with privacy through selective data exposure.
Public blockchain absorbs the bulk of installed capacity; private blockchain is expanding most quickly among regulated financial institutions.
Application:
Commercial maturity determines where enterprise procurement budgets flow, with established use cases commanding larger deployment contracts.
- Supply Chain Management:Immutable provenance tracking for commodities and pharmaceuticals leverages RFID integration and IoT oracles. Commodity traders in Singapore and Dubai drive adoption, motivated by letter-of-credit digitization that compresses settlement cycles from weeks to hours.
- Smart Contracts:Self-executing code automates compliance and settlement workflows across insurance and derivatives markets. European deployments face additional scrutiny under the EU AI Act's automated decision-making provisions, requiring on-chain explainability modules for algorithmic credit scoring applications.
- Digital Identity Verification:Decentralized credential systems reduce fraud in KYC processes.
- Cross-Border Payments:Real-time gross settlement bypasses correspondent banking networks.
Supply chain management captures the largest share of enterprise deployment spend; smart contracts show the steepest expansion trajectory as regulatory frameworks mature.
End User:
Procurement sophistication and risk tolerance create distinct customer tiers with divergent vendor selection criteria.
- Financial Institutions:Banks, asset managers, and payment processors require institutional-grade custody, staking, and compliance tooling as unified service bundles. Swiss and Singaporean buy-side firms increasingly demand single-counterparty accountability for tokenized fund administration.
- Government Agencies:Central banks and customs authorities explore wholesale CBDC interoperability and trade finance digitization. The EU's Markets in Crypto-Assets framework mandates full reserve backing for euro-denominated stablecoins, compelling national treasuries to deploy compliant tokenization infrastructure.
- Healthcare Providers:FDA scrutiny of blockchain-based health data integrity shapes product roadmaps for clinical trial documentation.
- Retail Businesses:Loyalty programs and payment acceptance drive smaller-scale deployments.
Financial institutions dominate current procurement volume; government agencies are gaining share fastest through CBDC and trade digitization mandates.
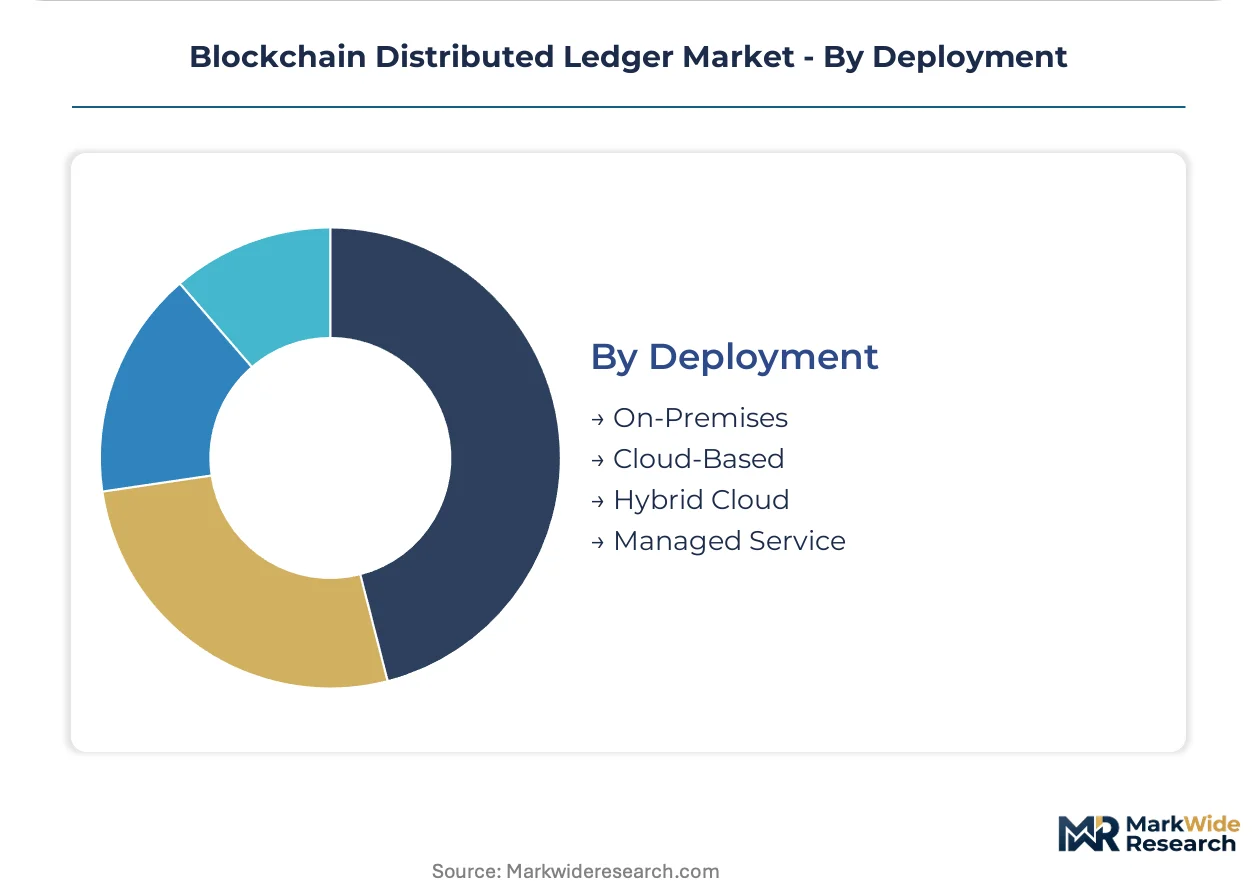
Deployment:
Operational control requirements and data sovereignty concerns determine infrastructure hosting decisions across regulated industries.
- Cloud-Based:Elastic compute resources reduce capital expenditure for protocol startups and mid-market enterprises. Asian banking clients in Hong Kong and Tokyo favor managed cloud deployments to accelerate time-to-market for trade finance applications.
- On-Premises:Air-gapped infrastructure satisfies data residency requirements for defense and intelligence applications. Swiss private banks maintain captive node operations in Zurich and Geneva to preserve client confidentiality under FINMA guidance.
- Hybrid Cloud:Split architectures separate sensitive consensus operations from public-facing query layers.
- Managed Service:Outsourced node operation and key management reduce internal cryptographic talent requirements.
Cloud-based deployment holds the majority of new node provisioning; on-premises configurations are climbing the fastest among privacy-sensitive institutional clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors the densest concentration of blockchain infrastructure deployment, with trading houses and commodity financiers driving cross-border settlement digitization across Southeast Asian corridors.
Singapore
Commodity traders and maritime financiers demand letter-of-credit automation on distributed ledgers. The Monetary Authority of Singapore's Project Guardian framework permits institutional DeFi experimentation under regulatory supervision. The Raffles Place district hosts the highest density of enterprise blockchain node operations outside Zurich.
Switzerland
Private banks and asset managers procure unified custody-staking-compliance bundles for tokenized fund administration. FINMA guidance on distributed ledger technology enables banks to hold crypto-assets on balance sheets. Zurich and Geneva maintain captive node clusters for client confidentiality compliance.
United Arab Emirates
Trade finance digitization accelerates through Dubai Multi Commodities Centre partnerships with distributed ledger vendors. VARA licensing requirements mandate operational resilience standards for virtual asset service providers. Abu Dhabi Global Market courts institutional blockchain deployments through English common law jurisdiction.
United States
SEC enforcement actions on unregistered token offerings constrain retail-facing protocol development. The agency's Wells notice practices shape product roadmaps for settlement infrastructure vendors. New York's BitLicense regime filters exchange and custody operations, concentrating compliant providers in Manhattan and Silicon Valley corridors.
Germany
BaFin's crypto custody licensing regime enables banks to offer institutional-grade digital asset services under existing supervision. The Electronic Securities Act permits debt instruments on distributed ledgers without paper certificates. Frankfurt's banking cluster experiments with wholesale CBDC interoperability protocols.
Blockchain Distributed Ledger Market Key Industry Players
Capital-heavy infrastructure operators compete with asset-light protocol designers for institutional procurement contracts. The vendor base clusters around vertically integrated platform bundlers, specialized interoperability engineers, and modular tooling providers. Dominant competitive moves include strategic partnerships with cloud hyperscalers and geographic expansion into regulatory sandbox jurisdictions.
Within the vertically integrated tier, ConsenSys anchors enterprise Ethereum tooling across DeFi and institutional settlement layers. HashCash Consultants occupies a position serving banking clients in Asian and Middle Eastern corridors. ChainSafe exemplifies the interoperability specialist archetype with cross-chain protocol development.
| Leading Market Players |
|---|
| PixelPlex |
| ScienceSoft |
| ConsenSys |
| ChainSafe |
| Kaleido |
| Coinbase Global |
| LeewayHertz |
| HashCash Consultants |
| Alchemy |
| Others |
Cost & Logistics Intelligence
Institutional procurement consolidation around unified custody-staking-compliance bundles forces infrastructure vendors to absorb cryptographic talent costs or cede contracts to vertically integrated platform operators, compressing margins across modular tooling providers.
Pricing Analysis
Margin tightening in private blockchain deployments reflects validator concentration among United States custodial providers and premium compensation demands for zero-knowledge circuit engineering expertise. Pricing stratifies across enterprise-grade bundled platforms, modular interoperability protocols, and project-based consulting engagements. Cost-down pressure on cloud-based node provisioning accelerates because Asian banking clients in Hong Kong and Tokyo favor managed deployments to accelerate trade finance time-to-market. Government agencies demonstrate lowest price sensitivity due to CBDC mandate urgency; retail businesses exhibit highest sensitivity with preference for open-source tooling.
Supply Chain Analysis
Refurbishment flows for cryptographic hardware security modules and validator node equipment remain underdeveloped, creating stranded asset risk for decommissioned proof-of-work mining infrastructure. Supply concentrates in Taiwan for semiconductor fabrication of secure enclave processors, in the United States for cloud compute infrastructure, and in Switzerland for air-gapped custody hardware. Raw material dependencies span gallium nitride for power efficiency, specialized ASIC designs for consensus validation, and rare earth elements for hardware manufacturing. Single-source vulnerability around Taiwan semiconductor output threatens validator hardware availability. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and systems integrators serving financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blockchain distributed ledger market sits in a technology-transition phase where zero-knowledge rollup architectures displace layer-one congestion pricing models and monolithic execution frameworks.
For Market Incumbents: Deepen vertical integration into formal verification tooling and cross-chain interoperability protocols to defend against modular infrastructure vendors eroding enterprise contract margins. Expand captive node operations in Zurich and Singapore to preserve single-counterparty accountability positioning. Invest in ISO 20022 message mapping capabilities to accelerate legacy core banking integration timelines. For New Entrants and Emerging Players: Capture white-space in carbon credit tokenization infrastructure for Brazil and Indonesia project developers, and in AI-oracle parametric insurance smart contracts for agricultural underwriters. The most penetrable segment lies in mid-market trade finance digitization across Dubai Multi Commodities Centre partnerships. Lead with regulatory sandbox admission in Abu Dhabi Global Market or Monetary Authority of Singapore jurisdictions to establish credibility before scaling. For Investors and Strategic Acquirers: The window for entry favors zero-knowledge rollup specialists and formal verification engineering teams before cryptographic talent scarcity forces acquisition premiums upward. Long-term viability hinges on protocol architectures compatible with wholesale CBDC interoperability standards. Monitor SEC Wells notice patterns and EU MiCA implementation timelines as inflection indicators for retail-facing versus institutional-only deployment strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Chain Protocol Development | Enables unified settlement layers collapsing siloed network architectures for institutional procurement. |
| Regulatory Sandbox Admission | Positions vendors for VARA licensing in Dubai and MAS Project Guardian participation in Singapore. |
| Formal Verification Tooling Investment | Addresses EU AI Act audit requirements for automated smart contract execution in European deployments. |
| Wholesale CBDC Interoperability Partnership | Aligns private ledger infrastructure with Bundesbank and Monetary Authority of Singapore settlement experiments. |
| Zero-Knowledge Circuit Engineering Acquisition | Secures scarce cryptographic talent for zk-SNARK implementations satisfying institutional confidentiality mandates. |
Research Approach
SEC filings, EU regulatory databases, and hyperscaler infrastructure capex disclosures formed the secondary backbone, cross-referenced with primary interviews across protocol engineers, regulatory affairs leads at distributed ledger vendors, institutional custody operators, and trade finance digitization specialists at commodity trading houses. Bottom-up node deployment counts and top-down enterprise IT spending allocations were triangulated against validator network growth metrics and smart contract deployment volumes.
Bottom-up modeling aggregated individual protocol revenue streams, node operation fees, and consulting engagement values across the projection horizon. Top-down validation referenced aggregate financial institution technology spending and government CBDC program budgets. Segmentation dimensions spanned consensus architecture type, application domain maturity, end-user procurement sophistication, and deployment model control requirements. CAGRs were derived from fitted growth curves incorporating regulatory milestone impacts and infrastructure adoption S-cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to quantum computing cryptography advances and proof-of-stake network centralization dynamics. Practitioners should monitor SEC enforcement patterns, EU MiCA stablecoin reserve implementation, and fault-tolerant quantum computing progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
United States Digital Asset Management Market
Digital Assets and Cryptocurrency Finance
Global Bitcoin and Cryptocurrency Wallets Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Bitcoin Exchange Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Automated Trading Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Atms Market
Digital Assets and Cryptocurrency Finance
Crypto Art Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Digital Asset Management (DAM) Market
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Market
Digital Assets and Cryptocurrency Finance
Bitcoin Trading Software Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchange Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Market